
 Vegan Wax Market | 2026-2036
Vegan Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Wax Market Analytics
Specialized chemists with plant lipid formulation expertise is rotating toward vegan wax producers as conventional paraffin technicians exit the field. KahlWax leverages its German manufacturing heritage to dominate refined candelilla supply chains. Strahl & Pitsch sustains century-old botanical extraction capabilities that anchor its carnauba and candelilla portfolios. Calwax competes through backward integration into soy wax cultivation networks across North American agricultural zones.
Vegan wax denotes plant-derived lipid materials—primarily esters, fatty acids, and long-chain alcohols—extracted from sources such as soybeans, carnauba palm leaves, or candelilla shrubs, then refined to melting points between 46°C and 82°C for industrial binding and coating applications. These materials serve as functional replacements for beeswax and paraffin in formulations requiring controlled release, surface gloss, or structural integrity without animal origin. Soy wax occupies the largest volume position due to abundant feedstock and lower refining costs, though carnauba wax commands superior margin pools in premium cosmetics where hardness and natural luster justify price premiums. Candelilla wax represents the fastest-expanding product category as Mexican harvest cooperatives scale sustainable wildcrafting practices to meet European cosmetics demand.
REACH registration requirements in Europe compel full toxicological disclosure for imported botanical waxes, while the EU Green Deal's deforestation-free supply chain mandates reshape sourcing from Brazilian carnauba plantations and Mexican candelilla harvesting regions. The US FDA maintains Generally Recognized as Safe status for soy and carnauba waxes in food contact applications, though California's Proposition 65 enforcement creates compliance friction for trace contaminant thresholds. Stakeholders must monitor evolving biodegradability certification schemes from ISO and national regulators, as these standards will determine market access for non-European suppliers within the next planning cycle.
Market Dynamics
REACH registration requirements and EU Green Deal deforestation-free mandates are forcing cosmetics formulators to requalify entire supply chains, converting compliance from a procurement checkbox into a strategic sourcing differentiator that reshapes supplier viability.
Growth Catalysts
- REACH toxicological disclosure mandates:European cosmetics brands must document full botanical wax safety profiles, creating captive demand for pre-registered suppliers with existing dossiers.
- Clean-label personal care procurement:German natural beauty brands command premium shelf positioning by marketing plant-derived waxes as ethical alternatives to beeswax and paraffin.
- Sustainable wildcrafting cooperatives:Mexican candelilla harvesters scale certified extraction practices to meet European import volume requirements.
Market Restraints
- Feedstock price volatility:Soybean commodity fluctuations transmit directly to soy wax input costs, compressing blender margins during agricultural supply shocks.
- Brazilian carnauba plantation concentration:Three northeastern states dominate global carnauba leaf harvesting, creating single-source vulnerability for high-hardness wax applications.
- Beeswax price competitiveness:Traditional apiculture byproduct wax retains cost advantages in candle and pharmaceutical coating segments where animal origin carries no regulatory penalty.
Strategic Opportunities
- Indian natural cosmetics expansion:BIS certification pathways for plant-derived inputs remain underdeveloped, offering first-mover positioning for compliant suppliers.
- Food-grade coating applications:FDA GRAS status for soy and carnauba waxes enables entry into produce preservation and confectionery glazing segments beyond cosmetics.
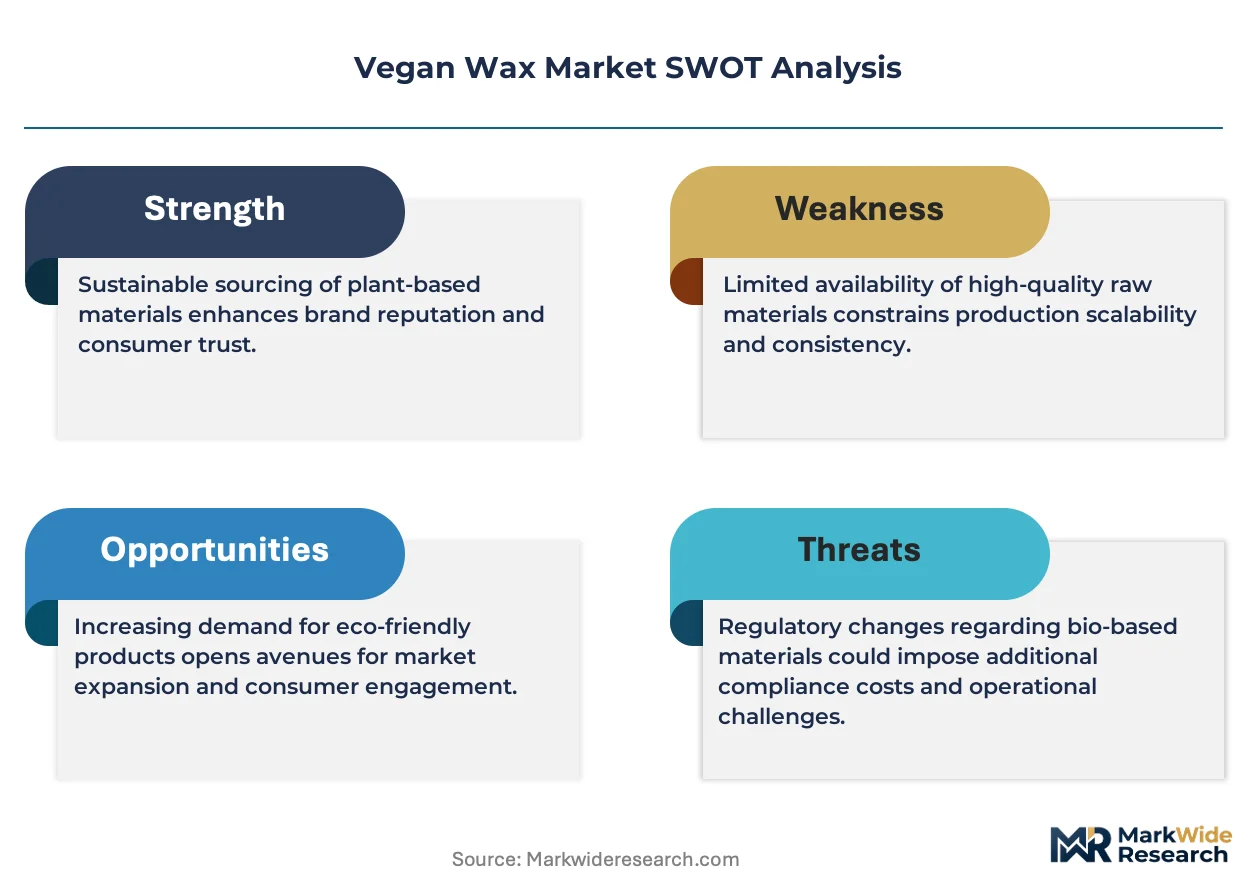
- ISO biodegradability certification convergence:Emerging standards for aquatic toxicity and compostability create new qualification barriers that favor integrated producers with in-house testing capabilities.
Industry Challenges
- Plant lipid formulation expertise scarcity:Conventional paraffin technicians lack training in ester chemistry and natural wax rheology, constraining R&D throughput at mid-scale producers.
- California Proposition 65 trace contaminant enforcement:Heavy metal and pesticide residue testing requirements add 12-18 month compliance timelines for new botanical wax entrants.
- Legacy equipment incompatibility:Natural waxes exhibit different melting profiles and oxidative stability than petroleum alternatives, requiring reformulation of existing coating and molding infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Wax Market |
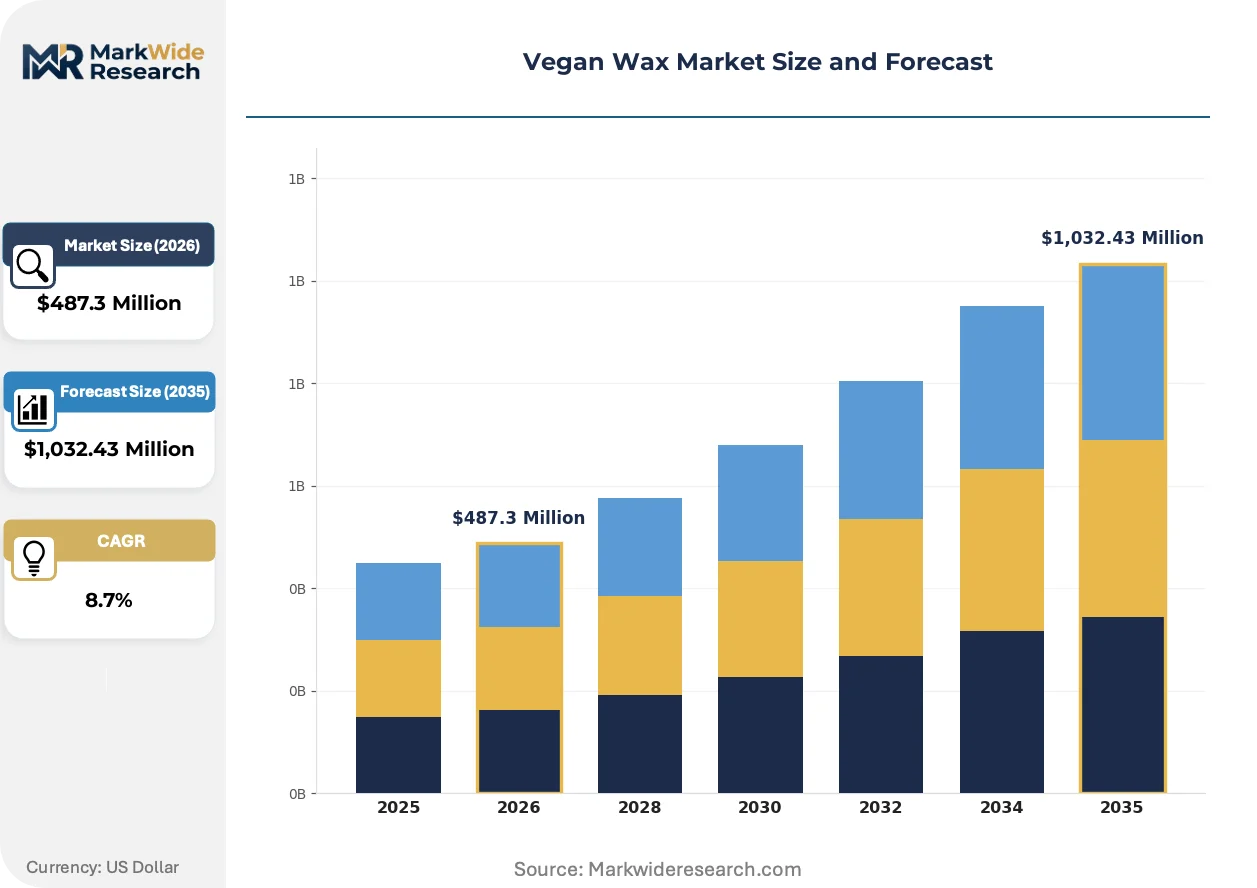
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beeswax Alternative, Soy Wax, Candelilla Wax, Carnauba Wax Application: Candles, Cosmetics, Food Packaging, Personal Care End User: Manufacturers, Retailers, Distributors, Consumers Form: Solid, Liquid, Powder, Granules |
| Companies Covered | Calwax, Akrochem Corporation, Strahl & Pitsch, NOREVO, Brenntag, KahlWax, Poth Hille, AF Suter, Paramold Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Wax Market Evolving Landscape
Formulation science is diverging along performance-versus-sustainability axes as cosmetics chemists engineer plant-derived waxes to match functional specifications previously dominated by synthetic and animal-based materials.
Fractionation and molecular distillation of candelilla wax is bifurcating the high-end cosmetics segment. Premium German skincare houses specify ultra-refined grades with sub-0.5% hydrocarbon content for lip balm and mascara formulations. Mass-market personal care brands absorb standard-refined material with higher residual coloration. This technical split is compressing mid-tier suppliers unable to justify dual processing lines.
EU Green Deal deforestation-free supply chain verification now requires GPS-tagged harvesting documentation for Brazilian carnauba and Mexican candelilla inputs. European cosmetics brands face 2025 compliance deadlines for due diligence systems. German formulators are consolidating supplier relationships to reduce audit burden, favoring integrated producers with captive plantation or wildcrafting networks.
Direct sourcing contracts between cosmetics brands and agricultural cooperatives are displacing traditional distributor intermediaries in European procurement. German natural beauty leaders now negotiate multi-year offtake agreements with Mexican candelilla harvester associations. This channel compression is most visible in premium segments where provenance storytelling commands retail price premiums.
Vegan Wax Market Segmentation
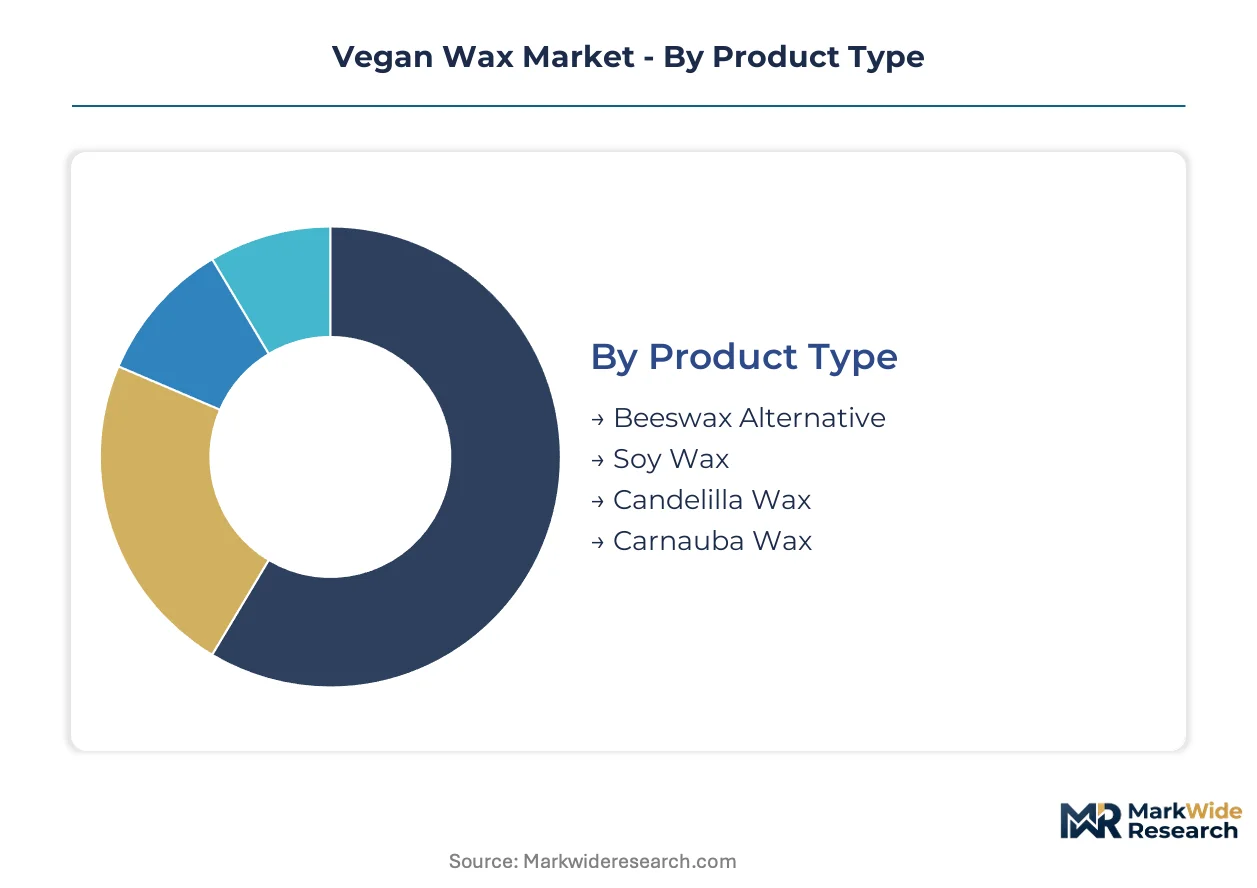
Vegan wax procurement decisions hinge on functional specifications that vary sharply across end-use applications. Formulators must reconcile melting point requirements, hardness profiles, and certification standards when selecting from plant-derived alternatives.
Product Type:
REACH registration tiers create divergent compliance burdens across botanical wax categories, with pre-registered suppliers capturing disproportionate European volume.
- Soy Wax:Hydrogenated soybean oil refined to melting points between 46°C and 52°C dominates candle manufacturing and mass-market cosmetics. Abundant North American feedstock and FDA GRAS status for food contact applications anchor volume leadership, though commodity price volatility transmits directly to blender margins.
- Carnauba Wax:Extracted from Brazilian palm leaves, this high-hardness material (82°C melting point) commands premium positioning in luxury cosmetics and automotive polishes. Three northeastern Brazilian states concentrate global leaf harvesting, creating single-source vulnerability for formulators requiring deforestation-free documentation under EU Green Deal mandates.
- Candelilla Wax:Mexican wildcrafting cooperatives scale certified extraction of this shrub-derived ester for European cosmetics demand.
- Beeswax Alternative:Blended plant lipid formulations replicate animal wax rheology for vegan-certified personal care brands.
Established volume favors soy wax; emerging adoption favors candelilla wax.
Application:
Clean-label procurement intensity varies by end-use exposure to consumer scrutiny and regulatory visibility.
- Cosmetics:German natural beauty brands specify ultra-refined grades with sub-0.5% hydrocarbon content for lip balm and mascara formulations. Premium skincare houses absorb higher input costs to market plant-derived binding agents as ethical alternatives, while mass-market brands tolerate standard-refined material with residual coloration.
- Personal Care:Solid bar soaps and hair styling products incorporate vegan waxes for structural integrity and controlled release. California Proposition 65 enforcement on trace contaminants adds 12-18 month compliance timelines for new botanical entrants targeting this segment.
- Candles:Container and pillar applications utilize soy wax for lower melting profiles and extended burn times.
- Food Packaging:FDA GRAS status enables carnauba and soy wax entry into produce preservation coatings and confectionery glazing.
Cosmetics commands margin premiums; food packaging offers volume scale.
End User:
Channel position determines specification authority and certification requirements.
- Manufacturers:Cosmetics formulators with in-house R&D capabilities drive technical specifications and audit supplier dossiers for REACH compliance. Direct sourcing contracts with Mexican candelilla harvester associations now displace traditional distributor intermediaries in premium European procurement.
- Distributors:Inventory consolidation across multiple botanical wax grades serves mid-scale personal care brands lacking technical procurement staff.
- Retailers:Private-label natural beauty lines specify vegan wax inputs for shelf differentiation.
- Consumers:Artisan candle makers purchase granule and flake formats through specialty supply channels.
Manufacturers control specification design; distributors capture fragmented mid-market volume.
Form:
Physical state selection reflects processing equipment compatibility and formulation integration requirements.
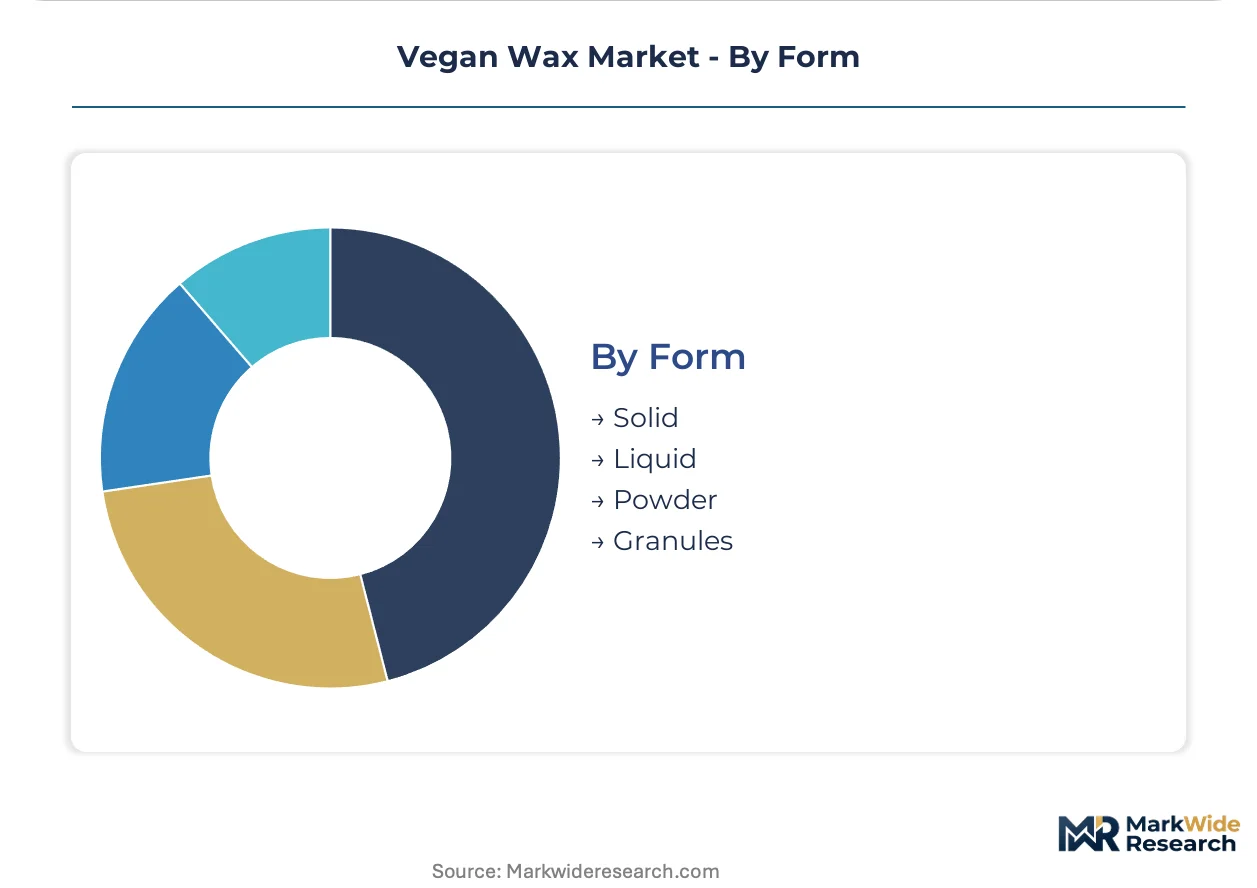
- Solid:Block and slab formats suit high-volume candle manufacturers with heated melting tanks. Standard inventory form across all product types.
- Powder:Micronized particles enable dry blending in powder cosmetics and instant dissolution in heated oil phases. Candelilla powder specifications bifurcate between premium sub-50-micron grades for color cosmetics and standard 100-micron material for industrial applications.
- Liquid:Pre-melted dispersions reduce energy input for small-batch formulators.
- Granules:Free-flowing pellets optimize automated feeding systems in continuous coating operations.
Solid forms dominate current inventory; powder formats gain share in color cosmetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European procurement patterns, with German formulators driving specification intensity for botanical wax imports across multiple industrial clusters.
Germany
Natural cosmetics brands in Hamburg and Berlin command premium shelf positioning through plant-derived wax certifications. ECHA's full toxicological disclosure requirements for imported botanical inputs create captive demand for pre-registered suppliers with existing dossiers. The Rhine-Ruhr industrial corridor concentrates refining capacity for ultra-refined candelilla grades destined for lip balm and mascara formulations.
United States
California's Proposition 65 enforcement on trace contaminants adds compliance friction for new botanical wax entrants targeting personal care segments. The FDA maintains GRAS status for soy and carnauba waxes in food contact applications. Midwest agricultural zones anchor soy wax cultivation networks, with processing clusters in Illinois and Iowa serving candle manufacturers and mass-market cosmetics blenders.
Brazil
Carnauba leaf harvesting concentrates in three northeastern states, creating single-source vulnerability for high-hardness wax applications. EU Green Deal deforestation-free supply chain mandates reshape sourcing documentation requirements from Brazilian plantations. The Ceará industrial zone processes raw leaf material into refined grades for European cosmetics and automotive polish export markets.
Mexico
Wildcrafting cooperatives in Zacatecas and San Luis Potosí scale certified candelilla extraction to meet European import volume requirements. Direct sourcing contracts between German natural beauty brands and Mexican harvester associations displace traditional distributor intermediaries. The Chihuahuan Desert harvesting regions supply the fastest-expanding product category in premium cosmetics formulations.
India
BIS certification pathways for plant-derived inputs remain underdeveloped, offering first-mover positioning for compliant suppliers targeting natural cosmetics expansion. Domestic Ayurvedic personal care brands in Maharashtra and Karnataka specify vegan wax alternatives for structural integrity in solid bar soaps. The Mumbai-Pune industrial corridor attracts technical investment from European formulators seeking alternative supply chain origins.
Vegan Wax Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the vegan wax supply base. The upper tier commands pre-registered REACH dossiers and captive plantation or wildcrafting networks that reduce audit burden for European cosmetics brands. Mid-scale specialists compete on fractionation capabilities and molecular distillation expertise for ultra-refined grades. Dominant competitive moves include backward integration into agricultural feedstocks and direct offtake contracting with harvester cooperatives.
Among German heritage manufacturers, KahlWax and Strahl & Pitsch exemplify the integrated archetype through century-old botanical extraction capabilities. Calwax anchors the North American scale-driven segment with upstream control over soy cultivation networks. These three entities represent divergent geographic and feedstock specializations that shape competitive positioning across premium and mass-market tiers.
| Leading Market Players |
|---|
| Calwax |
| Akrochem Corporation |
| Strahl & Pitsch |
| NOREVO |
| Brenntag |
| KahlWax |
| Poth Hille |
| AF Suter |
| Paramold Manufacturing |
| Others |
Value Network & Pricing Analysis
Paraffin displacement by plant-derived alternatives simultaneously redistributes procurement geography toward Brazilian and Mexican feedstock zones and compresses margin structures for mid-tier refiners lacking captive cultivation networks. REACH registration costs and EU Green Deal compliance documentation now function as pricing gatekeepers that stratify the supplier base between integrated heritage producers and commodity blenders.
Pricing Analysis
Geographic price spreads between German ultra-refined candelilla grades and standard North American soy wax inputs now exceed threefold, reflecting divergent certification burdens and fractionation intensity. Three-tier pricing structure across premium, standard, and economy levels segments by hydrocarbon content thresholds and REACH dossier completeness. Cost compression in mass-market soy wax is intensifying because agricultural commodity volatility transmits directly to blender margins without downstream pricing power. Candle manufacturers exhibit highest price sensitivity, while German natural cosmetics houses absorb premiums for deforestation-free documentation.
Supply Chain Analysis
Inventory lead times for Brazilian carnauba leaf inputs have extended substantially as GPS-tagged harvesting documentation requirements add verification stages before European customs clearance. Supply concentrates in Brazil, Mexico, and the United States, with the Chihuahuan Desert and Ceará industrial zone anchoring candelilla and carnauba extraction respectively. Raw material dependencies rest on soybean cultivation networks, palm leaf harvesting cooperatives, and shrub wildcrafting associations. Single-source vulnerability from three-state Brazilian carnauba concentration creates structural exposure to climate and regulatory shocks. Distribution runs through direct offtake contracts between cosmetics formulators and agricultural cooperatives, displacing traditional distributor intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan wax market sits in early-cycle expansion as clean-label procurement mandates in European cosmetics accelerate material substitution away from petroleum and animal-derived alternatives. Penetration remains shallow in food-grade coatings and Indian natural cosmetics, offering runway for compliant suppliers.
For Market Incumbents: Consolidate supplier relationships through multi-year offtake agreements with Mexican candelilla harvester associations to lock in deforestation-free feedstock access ahead of EU compliance deadlines. Deepen backward integration into soy cultivation networks across Midwest agricultural zones to buffer margin compression from commodity price swings. Prioritize REACH dossier maintenance and ISO biodegradability certification investment as competitive moats against emerging entrants lacking regulatory heritage.
For New Entrants and Emerging Players: Lead with BIS certification pathway navigation in India, where underdeveloped regulatory infrastructure creates first-mover positioning for compliant plant-derived wax suppliers targeting Ayurvedic personal care expansion. Target food packaging applications leveraging existing FDA GRAS status for soy and carnauba waxes, a segment where provenance storytelling carries less weight than technical specification meeting. Deploy direct sourcing narratives emphasizing harvester cooperative partnerships to differentiate from established distributor-dependent competitors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with captive plantation networks and pre-registered REACH dossiers. Long-term viability over the next planning cycle rests on deforestation-free supply chain verification capabilities and fractionation expertise for ultra-refined grade production. Acquisition candidates should demonstrate established relationships with German natural cosmetics formulators and Mexican wildcrafting cooperatives. Watch for ISO biodegradability certification convergence as the signal indicating which non-European suppliers will retain market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Captive soy and candelilla supply secures margin control against agricultural commodity volatility. |
| REACH Dossier Pre-Registration Investment | Existing toxicological documentation creates captive demand from European cosmetics formulators facing compliance deadlines. |
| Direct Offtake Contracting with Harvester Cooperatives | German natural beauty brands consolidate supplier relationships to reduce EU Green Deal audit burden. |
| ISO Biodegradability Certification Program | Emerging aquatic toxicity and compostability standards determine market access for non-European suppliers. |
| Fractionation Capability Expansion | Ultra-refined grade production with sub-0.5% hydrocarbon content commands premium positioning in lip balm and mascara formulations. |
Research Methodology
Operator-level perspectives from cosmetics formulators, agricultural cooperative managers, refinery plant engineers, and European regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews across these stakeholder categories combined with secondary validation from ECHA registration databases, customs and trade flow records, SEC filings from disclosed wax consumers, and botanical extraction industry association reports. Bottom-up volume modeling from feedstock cultivation estimates and top-down demand calibration from end-use consumption patterns provided triangulation checks across the projection horizon.
Sensitivity analysis tested forecast robustness against soybean commodity price volatility scenarios and REACH registration timeline variations across the analysis window. The analytical framework segmented by product type, application intensity, end-user channel position, and physical form, with additional dimensioning by certification tier and geographic supply origin. CAGRs derived from trend extrapolation of clean-label procurement adoption curves and regulatory mandate implementation schedules, incorporating plant lipid formulation expertise scarcity as a capacity constraint input.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity and stable wildcrafting cooperative scaling would require recalibration. Forecasts reflect assumptions regarding deforestation-free documentation system deployment and biodegradability certification scheme convergence. Revision becomes warranted when Brazilian carnauba harvest disruption or Mexican candelilla certification backlog crosses thresholds that materially constrain European cosmetics feedstock access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Surface Technology Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market