
 Expandable Graphite Market | 2026-2036
Expandable Graphite Market Size, Share, and Industry Trends Forecast 2026-2036
Expandable Graphite Market Analysis
Intumescent coatings are pivoting away from halogen-based additives toward expandable graphite formulations across commercial building projects. SGL Carbon leverages captive graphite processing in Europe to sustain cost advantages in specialty fire-retardant grades. GrafTech International anchors North American supply through integrated needle coke-to-graphite operations. Qingdao Xinghe Graphite competes on volume scale from Shandong Province processing clusters.
Expandable graphite consists of intercalated flake graphite that expands up to 300 times its original volume when exposed to heat, forming a thermally insulating char layer that protects substrates from flame propagation. The material typically contains sulfuric acid or nitric acid intercalants at 3-8 wt% and achieves onset expansion temperatures between 150°C and 300°C depending on grade formulation. Natural graphite feedstock dominates product type segmentation due to established mining infrastructure and lower processing costs, while synthetic graphite variants command premium positioning in battery thermal management applications where purity thresholds exceed 99.9% carbon content. Fire retardants lead application segmentation by installed volume, though battery sector demand is accelerating fastest as electric vehicle manufacturers adopt expandable graphite in pack-level fire suppression systems.
REACH registration requirements under ECHA govern chemical intercalant classifications and restrict certain acid treatments in European supply chains. EPA TSCA Section 5 premanufacture notifications affect new graphite intercalation compounds entering US commerce, while China's GB 8624 building material fire classification standards mandate intumescent performance thresholds in high-rise construction. Stakeholders must monitor evolving battery safety regulations in automotive end-use sectors, where thermal runaway containment specifications are tightening faster than graphite purification capacity can respond.
Market Dynamics
Construction safety mandates across Germany, China, and the United States are forcing rapid substitution of halogenated flame retardants with intumescent systems anchored by expandable graphite, tightening feedstock purity requirements faster than mining capacity can adjust.
Growth Catalysts
- GB 8624 fire classification standards:China's high-rise building codes now mandate intumescent performance thresholds that expandable graphite formulations satisfy more reliably than legacy halogen alternatives.
- Electric vehicle battery pack thermal management:Automakers in Germany and the United States are adopting expandable graphite in fire suppression layers between battery cells to contain thermal runaway propagation.
- Qingdao-Yichang processing corridor concentration:East Asian manufacturing clusters achieve sulfuric acid intercalation at scale, driving unit cost reductions that accelerate substitution in commercial construction.
Market Restraints
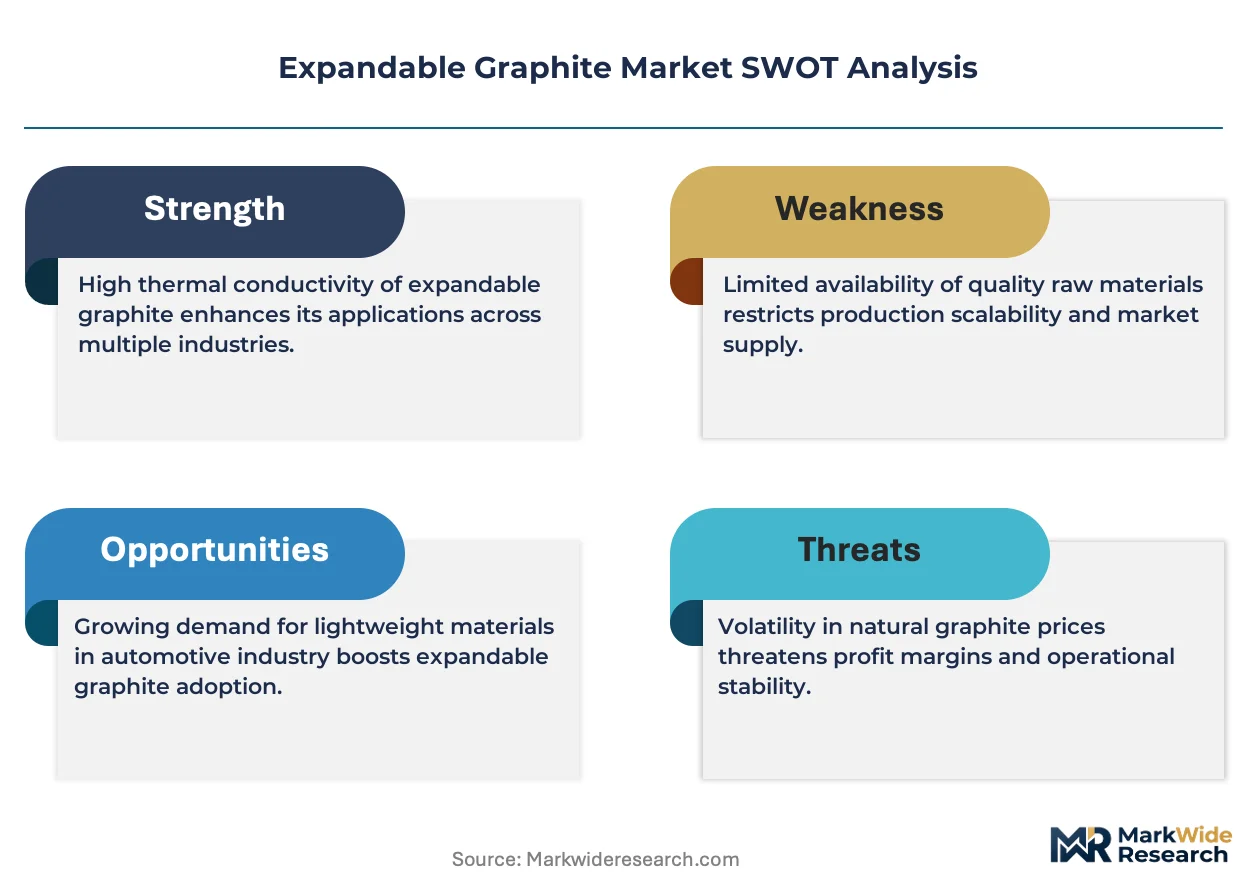
- Natural graphite feedstock price volatility:Flake graphite ore from African and Brazilian mines experiences extraction cost swings that compress processor margins during sulfuric acid intercalation stages.
- REACH acid intercalant restrictions:ECHA registration requirements classify certain nitric acid treatments as substances of very high concern, forcing European formulators toward higher-cost synthetic feedstock alternatives.
- Synthetic graphite substitution threat:Battery thermal management applications above 99.9% carbon purity specifications favor synthetic graphite variants despite 40-60% cost premiums over natural expandable grades.
Strategic Opportunities
- Underpenetrated Indian construction sector:BIS fire safety standards for high-rise residential towers remain below European intumescence thresholds, creating first-mover positioning for expandable graphite importers before local capacity develops.
- Convergence with aerogel insulation systems:Hybrid fire-barrier products combining expandable graphite expansion with silica aerogel thermal resistance target data center and battery enclosure applications.
- EU Green Deal sustainable chemistry incentives:Formulations reducing sulfuric acid intercalant residuals below 3 wt% qualify for preferential procurement in public infrastructure tenders across Germany and France.
Industry Challenges
- Graphite purification technician scarcity:Acid intercalation process control requires specialized chemical engineering expertise concentrated in Shandong Province and Saxony, limiting replication in emerging processing regions.
- EPA TSCA Section 5 notification timelines:New graphite intercalation compounds face 90-180 day premanufacture review periods that delay product launches for US construction and automotive customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expandable Graphite Market |
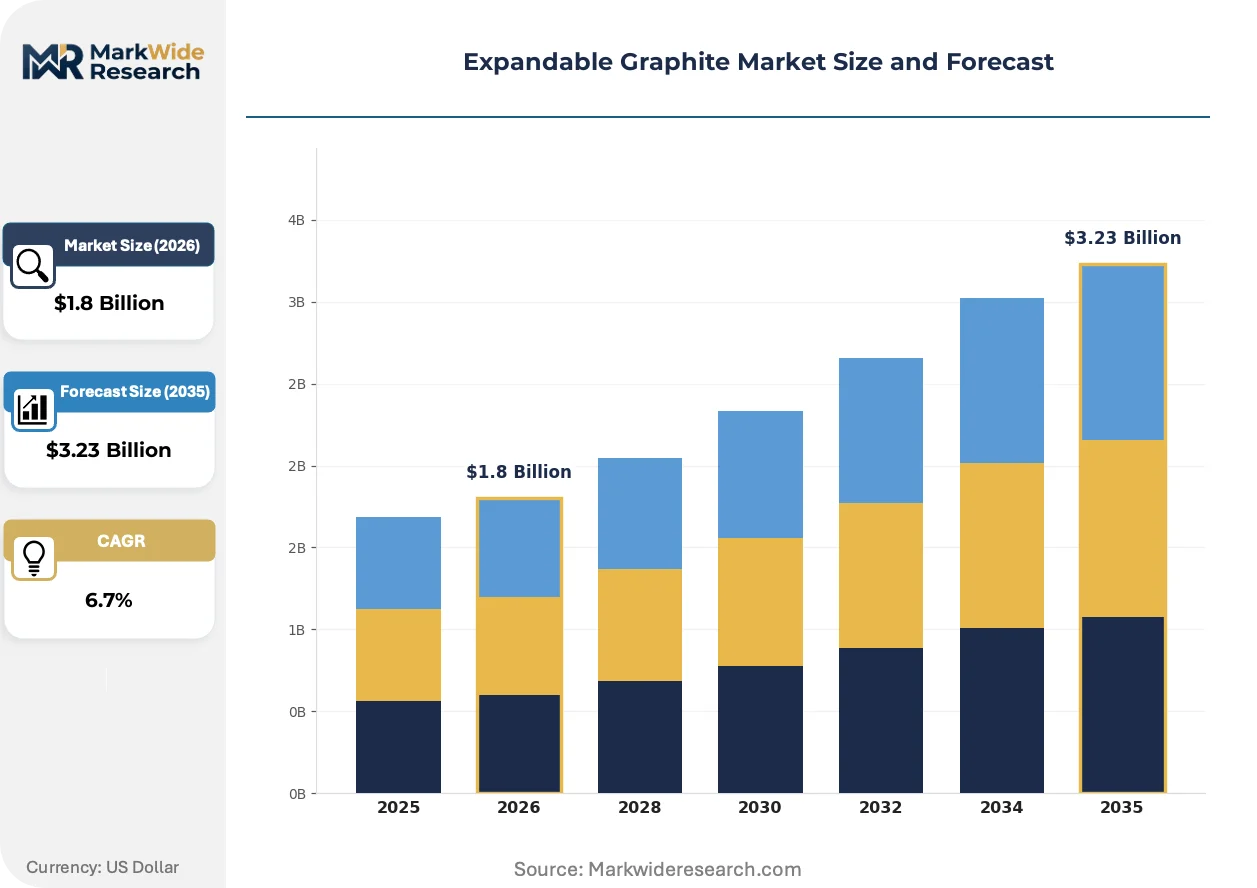
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Graphite, Synthetic Graphite, Expandable Graphite, Graphene Application: Fire Retardants, Batteries, Fuel Cells, Coatings End User: Aerospace, Automotive, Electronics, Construction Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Graphit Kropfmühl GmbH, Nacional de Grafite, SGL Carbon, Fangda Carbon New Material Co., Ltd., GrafTech International Ltd., NeoGraf, Qingdao Xinghe Graphite Co., Ltd., Tokai Carbon Co., Ltd., Yichang Xincheng Graphite Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expandable Graphite Market Emerging Trajectories
Processing automation and regulatory chemistry restrictions are compressing the viable technology set for flame-retardant formulations, while procurement consolidation among battery manufacturers concentrates demand around certified supply chains.
Continuous acid intercalation reactor systems are automating flake graphite processing that previously required batch-wise operator intervention. German chemical engineering firms deploy these systems for REACH-compliant sulfuric acid treatments at 150-200°C controlled expansion onset. The technology is automating quality variance reduction that previously required post-process sorting, compressing premium-grade yield losses from 15% toward 5%.
REACH authorization requirements for nitric acid intercalants are forcing European formulators toward sulfuric acid-only process routes by 2026 sunset dates. Industrial consequence includes 8-12% formulation cost increases for intumescent coating producers serving German and French construction markets. Affected segments are responding with backward integration into captive graphite mining in Mozambique and Tanzania to offset intercalation chemistry constraints.
Automotive battery procurement teams now mandate IATF 16949 certification and thermal runaway test documentation before supplier qualification. Tier-1 battery enclosure manufacturers are displacing spot-market graphite purchases with 3-5 year offtake agreements tied to purity guarantees. This pattern is most visible in South Korean and US Midwest battery plant clusters where pack assembly concentration creates buyer leverage over unqualified suppliers.
Expandable Graphite Market Segmentation
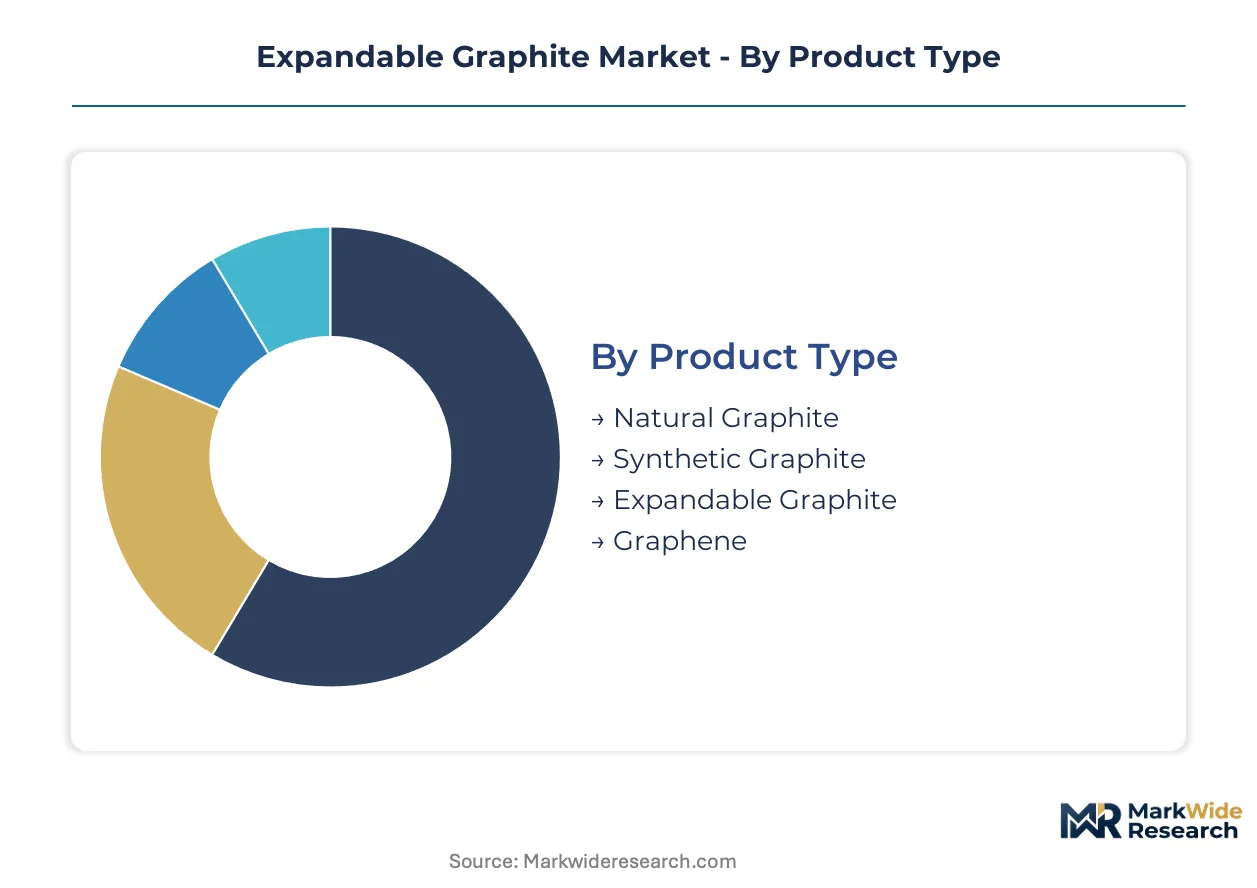
Segmentation in expandable graphite markets reveals how capital deployment, regulatory chemistry, and end-use performance requirements split value capture across fundamentally different production economics. Each dimension exposes distinct margin structures and competitive moats.
Product Type:
Natural graphite feedstock demands the heaviest upfront capital for mining infrastructure and acid intercalation facilities, while synthetic variants require controlled atmosphere furnaces and ultra-high purity purification systems.
- Natural Graphite:Intercalated flake graphite containing sulfuric or nitric acid at 3-8 wt% achieves 150-300°C expansion onset. Construction fire-retardant demand in Germany and China concentrates here due to lower processing costs versus synthetic alternatives, though African and Brazilian ore price volatility compresses processor margins.
- Synthetic Graphite:Petroleum coke or needle coke feedstock processed above 2,800°C delivers 99.9%+ carbon purity required for battery thermal management. German and US automakers specify synthetic grades for electric vehicle pack fire suppression layers despite 40-60% cost premiums.
- Expandable Graphite:Post-intercalation product ready for direct formulation into intumescent systems or battery enclosures.
- Graphene:Exfoliated derivative targeting specialized thermal interface materials and conductive coatings.
Most installed capacity flows through natural graphite. Expansion is steepest in synthetic graphite.
Application:
Application segments diverge sharply in customer concentration, with battery procurement teams consolidating around certified supply chains while fire-retardant coatings fragment across regional construction markets.
- Fire Retardants:Intumescent coatings and building materials represent the volume anchor. China's GB 8624 high-rise standards and Germany's REACH-compliant construction codes mandate performance thresholds that expandable graphite satisfies more reliably than legacy halogen alternatives.
- Batteries:Thermal runaway containment layers between lithium-ion cells command the steepest purity premiums. South Korean and US Midwest battery plant clusters now require IATF 16949 certification and documented thermal propagation test results before supplier qualification.
- Fuel Cells:Gas diffusion layer substrates and bipolar plate coatings.
- Coatings:Industrial corrosion protection and specialized barrier films.
Fire retardants absorb the most tonnage. Battery applications are climbing the fastest.
End User:
End-user concentration patterns track regulatory stringency, with automotive and aerospace imposing certification barriers that construction and electronics markets cannot replicate.
- Automotive:Electric vehicle manufacturers in Germany and the United States specify expandable graphite for pack-level fire suppression. Tier-1 battery enclosure producers are displacing spot-market purchases with multi-year offtake agreements tied to purity guarantees.
- Construction:Commercial building codes across Germany, China, and the United States are forcing substitution of halogenated flame retardants. Intumescent coating formulators serve fragmented regional contractor networks with lower switching costs than automotive.
- Aerospace:Cabin interior fire barrier specifications.
- Electronics:Consumer device thermal management and circuit protection.
Construction channels the most volume. Automotive is gaining share fastest.
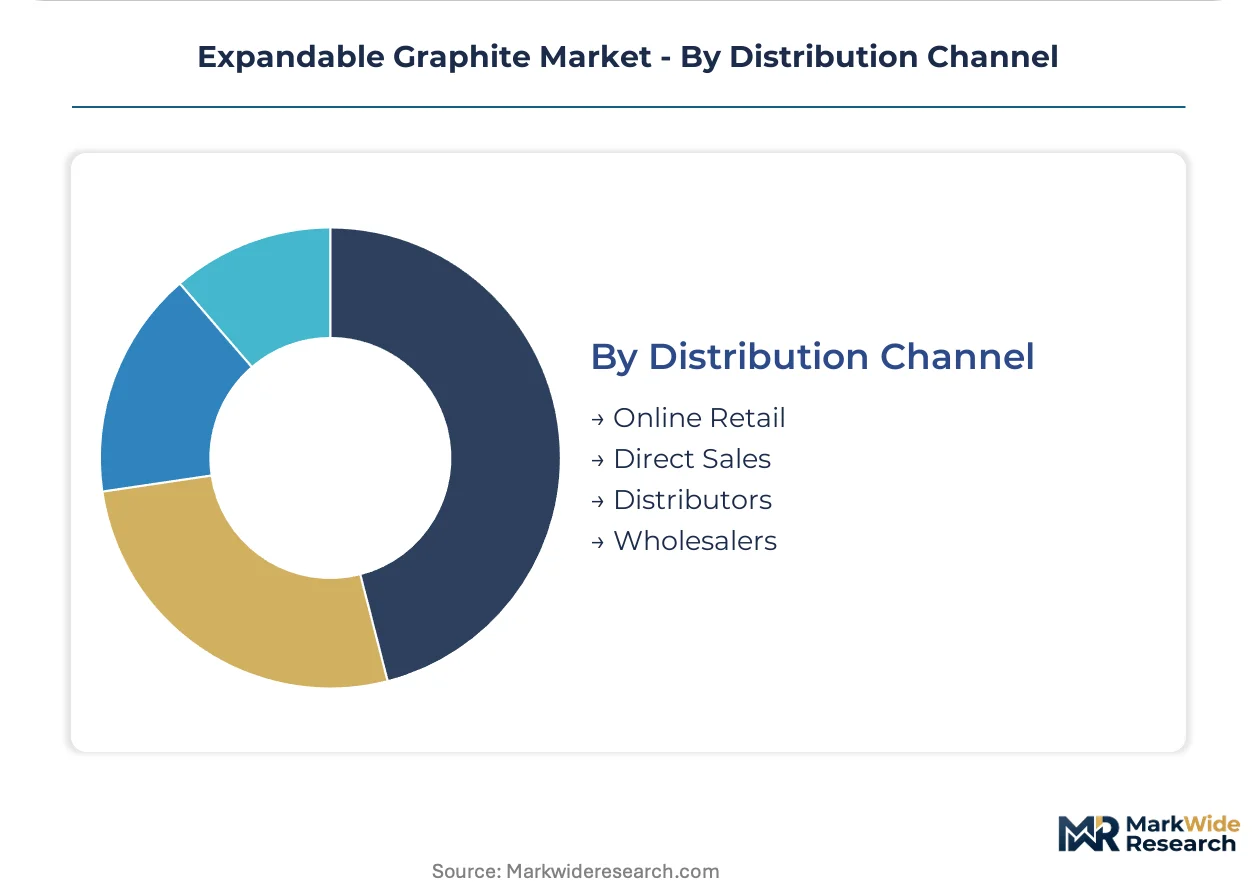
Distribution Channel:
Channel economics reflect customer scale and technical service requirements, with direct sales capturing the highest-margin battery accounts and distributors serving fragmented construction formulators.
- Direct Sales:Long-term supply agreements dominate battery and automotive procurement. German chemical engineering firms and Qingdao-based processors negotiate directly with South Korean and US Midwest battery plant operators for certified grade volumes.
- Distributors:Regional chemical distributors serve European and North American intumescent coating formulators with smaller batch requirements and less stringent certification demands.
- Online Retail:Small-laboratory and R&D quantities.
- Wholesalers:Bulk commodity grades for industrial processors.
Direct sales capture the highest value per ton. Distributor volumes are expanding most quickly in underpenetrated construction markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Yichang processing corridor concentrates expandable graphite manufacturing capacity. Construction safety mandates and electric vehicle battery procurement are reshaping demand patterns across four major economies. Regulatory chemistry restrictions and feedstock access are splitting competitive positioning between East Asian scale and European specialty grades.
Germany
REACH authorization deadlines for nitric acid intercalants are forcing formulators toward sulfuric acid-only process routes by 2026. The country's national chemical safety regulator classifies certain acid treatments as substances of very high concern. Bavarian chemical engineering firms deploy continuous reactor systems for compliant sulfuric acid intercalation at 150-200°C controlled expansion onset.
China
GB 8624 high-rise building codes mandate intumescent performance thresholds that expandable graphite satisfies more reliably than legacy halogen alternatives. The Ministry of Ecology and Environment monitors acid intercalation emissions from Shandong Province processing clusters. Qingdao and Yichang manufacturing corridors achieve sulfuric acid intercalation at scale, driving unit cost reductions that accelerate substitution in commercial construction.
United States
Electric vehicle manufacturers specify expandable graphite for pack-level fire suppression layers between battery cells. EPA TSCA Section 5 premanufacture notifications affect new graphite intercalation compounds entering US commerce. Midwest battery plant clusters now require IATF 16949 certification and documented thermal propagation test results before supplier qualification.
India
BIS fire safety standards for high-rise residential towers remain below European intumescence thresholds, creating first-mover positioning for expandable graphite importers. The Bureau of Indian Standards is gradually tightening flame-resistance requirements for commercial construction. Maharashtra and Gujarat industrial corridors show early distributor activity as regional coating formulators test intumescent formulations.
Expandable Graphite Market Vendor Landscape
Backward integration into captive graphite mining dominates the current landscape as European processors respond to REACH chemistry constraints. The vendor base splits between Chinese volume-scale processors and German specialty chemical engineering firms. Three archetypes define positioning: East Asian integrated miners with acid intercalation scale, European equipment-and-chemistry specialists, and North American battery-grade purifiers. Capacity expansion and strategic offtake agreements are the dominant competitive moves as battery procurement teams consolidate around certified supply chains.
Among German chemical engineering specialists, Graphit Kropfmühl GmbH exemplifies the European archetype of REACH-compliant processing. SGL Carbon represents integrated carbon materials positioning with captive graphite processing capabilities. Qingdao Xinghe Graphite Co., Ltd. anchors the Chinese volume-scale tier competing from Shandong Province processing clusters. These three occupy positions across the chemistry-constrained, certification-heavy, and scale-driven vectors respectively.
| Leading Market Players |
|---|
| Graphit Kropfmühl GmbH |
| Nacional de Grafite |
| SGL Carbon |
| Fangda Carbon New Material Co., Ltd. |
| GrafTech International Ltd. |
| NeoGraf |
| Qingdao Xinghe Graphite Co., Ltd. |
| Tokai Carbon Co., Ltd. |
| Yichang Xincheng Graphite Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Automotive battery procurement teams mandating IATF 16949 certification and multi-year purity guarantees are forcing processors to absorb acid intercalation cost volatility rather than pass through to buyers, compressing margins in natural graphite grades while synthetic variants capture premium positioning.
Pricing Analysis
Acid intercalation cost pass-through from sulfuric acid and nitric acid treatments dominates pricing structures across natural graphite grades, with expansion onset temperature precision and residual acid content below 3 wt% serving as the primary price differentiation drivers. Synthetic graphite variants commanding 40-60% premiums over natural grades reflect ultra-high purity furnace processing costs and battery thermal management certification requirements. Pricing pressure intensifies downward in construction fire-retardant segments where Qingdao-based volume processors compete on unit cost, while automotive battery buyers show least price sensitivity due to thermal runaway liability exposure. Three-tier pricing structure across battery-certified premium, REACH-compliant standard, and construction-economy levels captures divergent buyer willingness-to-pay across end-use applications.
Supply Chain Analysis
Dual-sourcing requirements from German and US Midwest battery plant operators mandate qualified backup suppliers for sulfuric acid intercalated grades, stretching certification timelines and concentrating procurement leverage among IATF 16949 holders. Geographic supply concentrates in China through Qingdao-Yichang processing corridors, Germany via Bavarian continuous reactor systems, and Mozambique-Tanzania captive mining operations responding to REACH chemistry constraints. Raw material dependencies center on African and Brazilian flake graphite ore, sulfuric acid intercalant chemicals, and petroleum needle coke for synthetic variants. Single-source vulnerability runs through Shandong Province acid intercalation technician concentration, where specialized chemical engineering expertise limits rapid capacity replication. Distribution runs through direct long-term offtake agreements for battery and automotive accounts, with regional chemical distributors serving fragmented European and North American construction formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The expandable graphite market functions as a stable compounder anchored by irreversible regulatory substitution of halogenated flame retardants across German, Chinese, and US construction codes, with battery thermal runaway containment layering additional demand insulation.
For Market Incumbents: Anchor market position through backward integration into captive flake graphite mining in Mozambique and Tanzania to offset REACH sulfuric acid intercalant constraints, while simultaneously expanding continuous reactor automation to compress premium-grade yield losses from batch processing variance. Synthetic graphite substitution threats from battery manufacturers demanding 99.9%+ carbon purity specifications require dedicated furnace capacity investment to defend automotive qualification status against petroleum coke-based competitors. For New Entrants and Emerging Players: Launch via distributor partnerships targeting underpenetrated Indian construction markets where BIS fire safety standards lag European intumescence thresholds, establishing first-mover positioning before local Shandong-style processing clusters develop. Hybrid fire-barrier formulations combining expandable graphite expansion with silica aerogel thermal resistance offer the most penetrable white-space targeting data center and battery enclosure applications underserved by pure intumescent or pure insulation suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with European specialty chemical engineering firms possessing REACH-compliant continuous reactor technology and existing automotive certification relationships, acquisition of which captures battery procurement consolidation tailwinds with limited replication risk from Chinese volume competitors. Long-term viability over the 5-10 year window rests on sulfuric acid intercalant residual reduction capabilities qualifying for EU Green Deal preferential procurement. The signal to watch is EPA TSCA Section 5 notification timeline compression or expansion, which would materially accelerate or delay US market entry for new graphite intercalation compounds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Mozambique and Tanzania flake graphite acquisitions secure feedstock against African ore price volatility. |
| Continuous Reactor Automation Deployment | Bavarian chemical engineering firms reduce premium-grade yield losses from 15% toward 5%. |
| REACH-Compliant Sulfuric Acid Process Route | EU Green Deal qualification requires intercalant residuals below 3 wt% for public infrastructure tenders. |
| IATF 16949 Certification Investment | South Korean and US Midwest battery plants mandate documented thermal propagation test results. |
| Hybrid Aerogel-Graphite Formulation Development | Data center fire-barrier applications combine intumescent expansion with silica thermal resistance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with acid intercalation plant managers, procurement leads at German automotive OEMs, intumescent coating formulators, and technical R&D directors at battery enclosure manufacturers with secondary validation from customs and trade data, SEC 10-K filings of listed carbon materials processors, ECHA REACH registration databases, and GB 8624 building code compliance records. Bottom-up capacity and demand modeling triangulated against top-down market sizing across natural and synthetic graphite feedstock tiers.
Segment-weighting approaches distributed value and volume across product type dimensions including natural versus synthetic feedstock, application segments spanning fire retardants and battery thermal management, and end-user categories tracking construction and automotive procurement concentration. CAGRs were derived from installed capacity expansion timelines, regulatory mandate phase-in schedules, and electric vehicle production ramp assumptions. Industry-specific forecast inputs incorporated acid intercalation technician availability constraints and EPA TSCA Section 5 notification processing durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH authorization timeline acceleration or sudden sulfuric acid supply disruptions from Shandong Province environmental enforcement actions. Deviation in battery thermal runaway testing standard harmonization across German, US, and South Korean automotive regulators would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Case Material Market
Composite Materials
PCR Laminates Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
China Marine Composites Market
Composite Materials
Plastic Composites Market
Composite Materials
Composite Cans Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Graphite Carbon Raiser Market
Composite Materials
Biocomposites Market
Composite Materials
Global Lightweight Construction Material Market