
 Super-Hard Material Market | 2026-2036
Super-Hard Material Market Size, Share, and Industry Trends Forecast 2026-2036
Super-Hard Material Market Analytics
Subscription-based tool life monitoring and predictive maintenance software is hardening the commercial model for super-hard cutting inserts, shifting revenue from unit sales to performance contracts. Element Six leverages its synthetic diamond research heritage to dominate high-purity CVD substrates for electronics. Sandvik Group anchors its position through backward integration into cemented carbide substrates that pair with cubic boron nitride tips. Sumitomo Electric Industries specializes in electrically conductive diamond heat spreaders for power semiconductor packages.
Super-hard materials comprise substances with Vickers hardness exceeding 40 GPa, including synthetic and natural diamond, cubic boron nitride, and hexagonal boron nitride, synthesized through high-pressure high-temperature or chemical vapor deposition processes to deliver extreme wear resistance and thermal conductivity for precision machining and electronic thermal management. Diamond product lines command premium positioning in optical and semiconductor applications where thermal conductivity thresholds exceed 1,000 W/mK, while cubic boron nitride competes aggressively in ferrous metal cutting where diamond's carbon solubility creates tool degradation. Coating technology segments attract disproportionate R&D investment as manufacturers seek to deposit super-hard films onto complex geometries without subsurface damage.
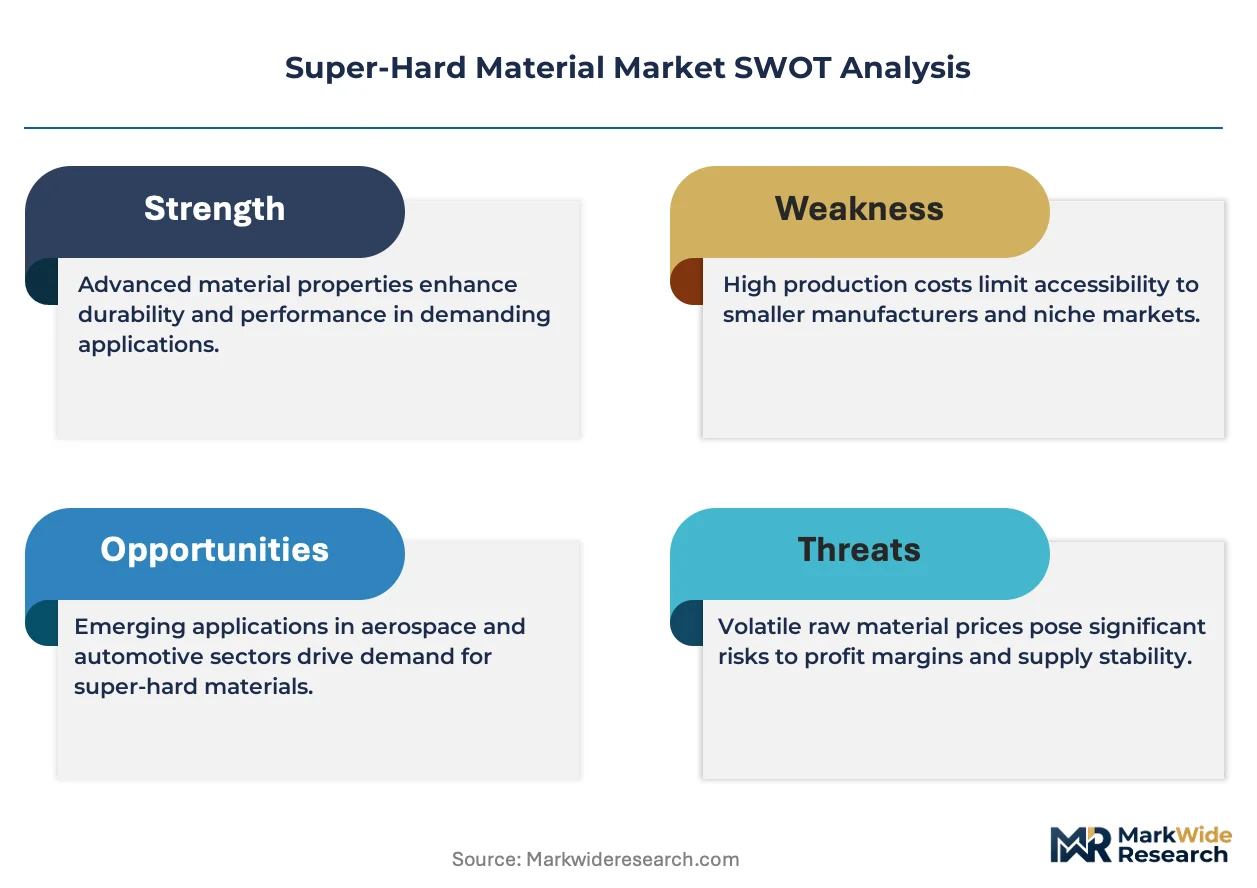
EPA emissions standards and OSHA crystalline silica exposure limits constrain synthetic diamond powder processing facilities in the United States, while REACH registration requirements in Europe restrict certain metal binder chemistries used in polycrystalline diamond compacts. China's MEE enforces wastewater discharge standards on diamond synthesis plants operating near the Yellow River basin, elevating capital requirements for smaller producers. Stakeholders must monitor how evolving carbon accounting rules across multiple jurisdictions reshape the cost structure of energy-intensive HPHT synthesis relative to lower-temperature CVD alternatives.
Market Dynamics
China's dual carbon goals and MEE wastewater discharge standards are compressing synthetic diamond production margins while simultaneously accelerating CVD adoption as manufacturers flee energy-intensive HPHT synthesis near the Yellow River basin.
Growth Catalysts
- Aerospace turbine blade machining:Super-hard cutting inserts enable precision machining of nickel-based superalloys at temperatures exceeding 1,000°C, with Boeing and Airbus supply chains standardizing polycrystalline cubic boron nitride tools for blade root profiles.
- REACH registration requirements:European restrictions on cobalt and nickel binder chemistries in polycrystalline diamond compacts are forcing reformulation investments that favor established producers with dedicated compliance infrastructure.
- Henan province cluster concentration:Synthetic diamond producers in Zhengzhou and neighboring cities supply 80% of global cutting tool manufacturers, creating dense supplier networks that compress lead times for polycrystalline diamond blanks.
Market Restraints
- HPHT energy cost volatility:Electricity accounts for 35-45% of high-pressure high-temperature synthesis costs, exposing producers to grid pricing fluctuations in coal-dependent Chinese manufacturing zones.
- Diamond carbon solubility in ferrous metals:Synthetic diamond tools degrade rapidly when cutting iron, nickel, or cobalt alloys, permanently capping addressable market share in automotive powertrain machining.
- OSHA crystalline silica exposure limits:Synthetic diamond powder processing facilities in the United States face capital-intensive ventilation and monitoring upgrades, constraining domestic micron powder capacity expansion.
Strategic Opportunities
- Electrically conductive diamond heat spreaders:Sumitomo Electric Industries and Element Six are qualifying boron-doped CVD diamond substrates for silicon carbide power module thermal management in electric vehicle inverters.
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor packaging and display fabrication are creating first-mover opportunities for diamond heat sink suppliers establishing local CVD deposition capacity.
- Subscription-based tool life monitoring:Sensor-embedded cutting inserts with predictive maintenance software enable performance contracting models that shift revenue from unit sales to guaranteed machining throughput.
Industry Challenges
- CVD deposition technician scarcity:Chemical vapor diamond growth requires plasma physics and surface chemistry expertise that outpaces vocational training pipeline output in established manufacturing regions.
- Polycrystalline diamond compact certification timelines:Oil and gas drill bit qualifications for geothermal and extended-reach applications demand 18-24 month field validation cycles before procurement authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super-Hard Material Market |
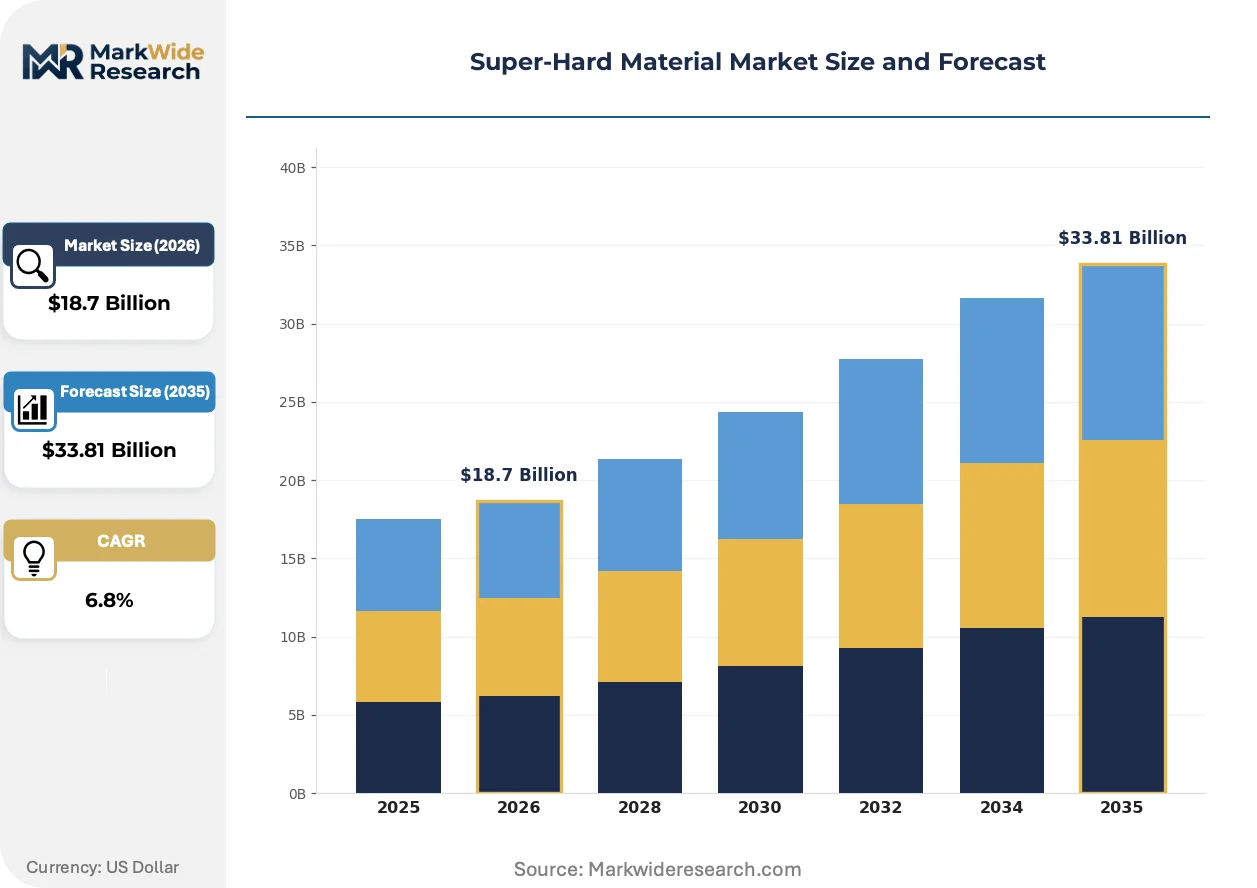
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond, Boron Nitride, Cubic Boron Nitride, CVD Diamond Application: Aerospace, Mining, Cutting Tools, Electronics Technology: Synthetic, Natural, Coating, Machining End User: Manufacturing, Construction, Oil & Gas, Automotive |
| Companies Covered | Element Six, Sandvik Group, Sumitomo Electric Industries, ILJIN Diamond, Sino-Crystal Diamond, Huanghe Whirlwind, SF-Diamond, Zhongnan Diamond, Hyperion Materials & Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super-Hard Material Market Evolving Landscape
Three converging forces are restructuring competitive advantage: manufacturing process substitution away from energy-intensive synthesis, regulatory carbon accounting that reshapes cost structures, and thermal management applications that outpace traditional cutting tool growth.
Chemical vapor deposition diamond synthesis is decentralizing production geography by enabling smaller-scale reactors with lower capital thresholds than high-pressure high-temperature presses. Aerospace heat exchanger manufacturers and semiconductor packaging houses are installing captive CVD systems to secure supply chain control. This technology is decentralizing synthetic diamond production away from Henan province concentration toward end-user sites in Germany, Japan, and the United States.
China's MEE wastewater discharge standards and dual carbon goals are forcing synthetic diamond producers to relocate or retrofit facilities operating near the Yellow River basin. Plants without flue gas treatment or closed-loop water systems face operating license non-renewal. HPHT synthesis capacity is migrating to regions with renewable energy access or consolidating into integrated producers with captive environmental infrastructure.
Power semiconductor manufacturers are unbundling thermal interface material procurement from traditional electronics distributors, establishing direct specifications for diamond heat spreader thermal conductivity thresholds exceeding 1,200 W/mK. Tier-one automotive suppliers now require lot-level thermal performance certification with traceable CVD growth parameters. This specification tightening is most visible in German and Japanese electric vehicle inverter supply chains, where thermal management failures carry catastrophic warranty exposure.
Super-Hard Material Market Segmentation
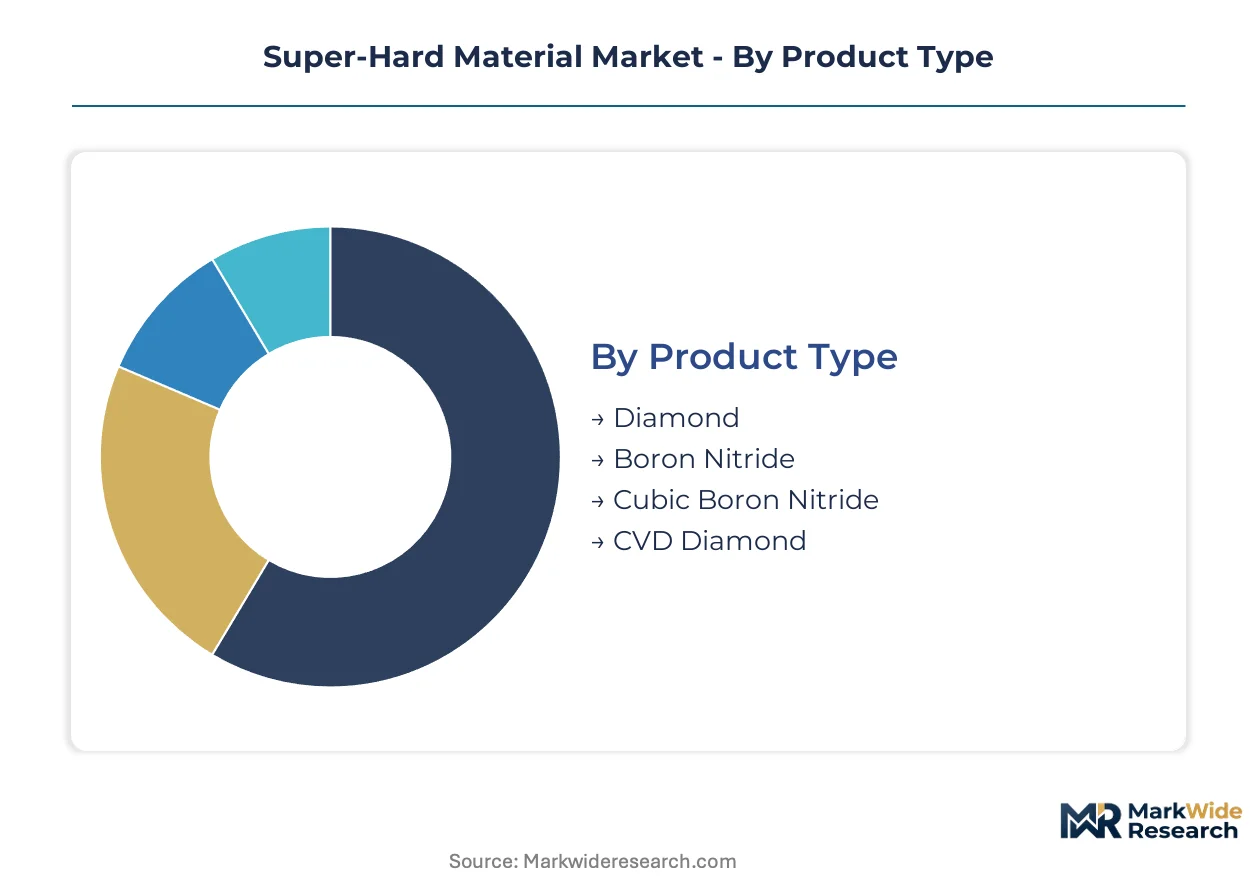
Super-hard material procurement decisions hinge on thermal performance thresholds, machining substrate compatibility, and synthesis energy intensity. Buyers segment suppliers by CVD versus HPHT provenance to manage carbon accounting exposure and tool life predictability.
Product Type:
Buyers prioritize thermal conductivity specifications and ferrous metal compatibility when selecting among diamond-based and boron nitride alternatives.
- Diamond:Natural and synthetic diamond deliver Vickers hardness exceeding 100 GPa with thermal conductivity surpassing 1,000 W/mK. Aerospace optical window manufacturers and semiconductor packaging houses in Germany and Japan specify lot-level traceability for CVD growth parameters to guarantee thermal performance.
- Cubic Boron Nitride:Second-hardest known material after diamond, cBN resists chemical degradation when cutting ferrous alloys at temperatures above 1,000°C. Boeing and Airbus supply chains standardize polycrystalline cBN inserts for nickel-based superalloy turbine blade root profiles.
- Boron Nitride:Hexagonal boron nitride serves as a solid lubricant and thermal insulator in crucible applications rather than cutting tools, with demand concentrated in aluminum casting operations.
- CVD Diamond:Chemical vapor deposition produces high-purity diamond films and free-standing substrates for electronics thermal management. Power semiconductor manufacturers now require direct supplier relationships bypassing traditional electronics distributors.
Volume sits with diamond across optical and semiconductor applications; growth tilts toward CVD diamond as electric vehicle inverter manufacturers qualify boron-doped heat spreaders.
Application:
End-use concentration follows capital equipment investment cycles and regulatory pressure on manufacturing emissions.
- Cutting Tools:Polycrystalline diamond and cBN inserts dominate precision machining of hardened steels and non-ferrous alloys. China's Henan province cluster supplies 80% of global cutting tool manufacturers, compressing lead times for polycrystalline diamond blanks.
- Aerospace:Turbine blade machining demands tools maintaining edge integrity at extreme temperatures. Extended-reach and geothermal drilling applications require 18-24 month field validation cycles for polycrystalline diamond compact certification.
- Electronics:Thermal management applications for silicon carbide power modules are displacing traditional cutting tool volume. German and Japanese automotive suppliers require thermal conductivity thresholds exceeding 1,200 W/mK with catastrophic warranty exposure for failure.
- Mining:Oil and gas drill bits consume large-diameter polycrystalline diamond compacts, though procurement authorization timelines stretch across multiple drilling seasons.
Cutting tools anchor current revenue; electronics thermal management climbs fastest as power semiconductor packaging unbundles from traditional distribution channels.
Technology:
Synthesis method selection determines capital intensity, energy cost exposure, and geographic production flexibility.
- Synthetic:HPHT synthesis requires massive presses consuming 35-45% electricity by cost, concentrating production in China's coal-dependent manufacturing zones. MEE wastewater discharge standards near the Yellow River basin are forcing facility relocation or retrofit.
- Coating:Super-hard film deposition onto cemented carbide substrates enables complex geometries without subsurface damage. Sandvik Group anchors position through backward integration into carbide substrates paired with cBN tips.
- Natural:Geological diamond supply constrains scalability for industrial applications beyond gem-quality optical components and specialized research equipment.
- Machining:Post-synthesis processing into finished cutting inserts requires grinding and edge preparation with crystalline silica exposure controls.
HPHT retains volume leadership; CVD synthesis gains share fastest as decentralized reactors enable captive production at aerospace and semiconductor packaging sites in Germany, Japan, and the United States.
End User:
Procurement sophistication varies by industry maturity and total cost of failure for tooling systems.
- Manufacturing:General machining operations balance tool life against insert replacement cost, with subscription-based predictive maintenance software shifting supplier relationships toward performance contracts.
- Automotive:Powertrain machining permanently caps diamond tool applicability due to carbon solubility in ferrous metals, directing demand toward cBN alternatives for engine block and transmission component finishing.
- Oil & Gas:Geothermal drilling and extended-reach applications demand polycrystalline diamond compact durability validation across extreme pressure-temperature conditions.
- Construction:Stone cutting and concrete drilling consume lower-specification synthetic diamond grit with price sensitivity limiting premium product penetration.
Manufacturing commands greatest volume; automotive thermal management applications for electric vehicle inverters represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhengzhou anchors global synthetic diamond production, with Henan province clusters supplying cutting tool manufacturers across three continents. Germany and Japan concentrate CVD diamond growth for semiconductor thermal management. The United States maintains aerospace and oilfield drilling demand centers while facing domestic powder processing constraints.
China
Henan province generates synthetic diamond blanks for global cutting tool supply chains, with Zhengzhou and neighboring cities compressing lead times through dense supplier networks. MEE wastewater discharge standards near the Yellow River basin force facility relocation or environmental retrofit investments. Dual carbon goals accelerate CVD adoption as manufacturers exit energy-intensive HPHT synthesis in coal-dependent zones.
Germany
Automotive inverter manufacturers specify diamond heat spreader thermal conductivity thresholds exceeding 1,200 W/mK for silicon carbide power modules. REACH registration requirements restrict cobalt and nickel binder chemistries in polycrystalline diamond compacts, favoring producers with dedicated compliance infrastructure. Bavarian and Baden-Württemberg automotive suppliers now require lot-level thermal performance certification with traceable CVD growth parameters.
United States
Boeing and Airbus supply chains standardize polycrystalline cubic boron nitride tools for nickel-based superalloy turbine blade machining. EPA emissions standards and OSHA crystalline silica exposure limits constrain synthetic diamond powder processing facility expansion, elevating capital requirements for ventilation and monitoring systems. Domestic micron powder capacity faces hard limits despite aerospace and geothermal drilling demand.
Japan
Power semiconductor packaging houses qualify boron-doped CVD diamond substrates for electric vehicle inverter thermal management. METI industrial policy supports captive CVD reactor installation at electronics manufacturing sites to secure supply chain control. Osaka and Nagoya automotive suppliers now unbundle thermal interface material procurement from traditional distributors, establishing direct diamond heat spreader specifications.
India
PLI scheme production-linked incentives for semiconductor packaging and display fabrication create first-mover opportunities for diamond heat sink suppliers establishing local CVD deposition capacity. Karnataka and Telangana electronics manufacturing corridors attract equipment vendors seeking proximity to packaging houses. Central government carbon accounting rules reshape cost structures for imported versus domestically synthesized super-hard materials.
Super-Hard Material Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across synthesis technology boundaries. HPHT press operators face electricity cost volatility that CVD reactor owners avoid through smaller-scale distributed systems. Three archetypes dominate: integrated synthesis-to-tooling manufacturers controlling substrate supply, pure-play CVD technology licensors enabling captive customer production, and coating specialists depositing super-hard films onto third-party cemented carbide. Capacity consolidation and strategic partnerships represent the dominant competitive moves as environmental compliance costs reshape viable scale thresholds.
Within the integrated synthesis tier, Element Six and Sandvik Group occupy positions spanning raw material production through finished cutting insert distribution. Sumitomo Electric Industries exemplifies the electronics-specialist archetype, anchoring thermal management applications rather than traditional machining markets. Chinese producers including Huanghe Whirlwind and Zhongnan Diamond represent volume-driven manufacturing clusters concentrated in Henan province, while ILJIN Diamond and SF-Diamond occupy intermediate positions between regional supply and global specification compliance.
| Leading Market Players |
|---|
| Element Six |
| Sandvik Group |
| Sumitomo Electric Industries |
| ILJIN Diamond |
| Sino-Crystal Diamond |
| Huanghe Whirlwind |
| SF-Diamond |
| Zhongnan Diamond |
| Hyperion Materials & Technologies |
| Others |
Value Network & Pricing Analysis
Tier-one automotive suppliers in Germany and Japan concentrate procurement power for diamond heat spreaders, anchoring value-based contracts tied to thermal conductivity guarantees rather than unit volume. This buyer concentration forces suppliers toward performance-based pricing models with catastrophic warranty exposure for failure, compressing margins for uncertified producers while rewarding lot-level traceability.
Pricing Analysis
Value-based pricing anchored to guaranteed thermal conductivity thresholds dominates electronics applications, with contracts specifying minimum heat dissipation performance rather than per-gram rates. Price differentiation rests on CVD growth parameter certification and lot-level traceability, with uncertified producers facing severe compression. Cost compression in HPHT-synthesized diamond grit is intensifying because China's MEE standards force facility relocation or retrofit investments. Construction segment buyers exhibit highest price sensitivity, while semiconductor packaging houses prioritize thermal performance over unit cost.
Supply Chain Analysis
Qualification timelines for polycrystalline diamond compacts in oil and gas drilling create 18-24 month gating periods that freeze supplier switching and entrench incumbents. Supply concentrates in China, Germany, and Japan, with Henan province clusters feeding cutting tool manufacturers while CVD growth localizes near automotive and semiconductor end-users. Raw material dependencies include methane feedstock purity, metal binder powders, and cemented carbide substrates. Single-source vulnerability runs through HPHT press anvil supply chains concentrated in Chinese manufacturing zones. Distribution runs through direct specifications from power semiconductor manufacturers bypassing traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as environmental compliance costs for HPHT synthesis force smaller Chinese producers toward acquisition or exit. MEE wastewater standards and dual carbon goals are compressing viable scale thresholds.
For Market Incumbents: Extend certification infrastructure investments to capture share from distressed competitors facing MEE license non-renewal near the Yellow River basin. Backward integration into captive CVD reactor networks in Germany and Japan secures direct relationships with automotive thermal management buyers. Sumitomo Electric Industries demonstrates the defensive value of electronics-specialist positioning away from commoditized cutting tool competition. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for establishing local CVD deposition capacity ahead of packaging house demand maturation. Karnataka and Telangana electronics corridors offer white-space positioning for diamond heat sink suppliers qualifying under domestic carbon accounting rules. Target captive production partnerships with power semiconductor packaging houses seeking supply chain control rather than distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor HPHT operators with existing environmental infrastructure in renewable energy zones or consolidated CVD technology licensors with proven automotive qualifications. Long-term viability hinges on synthesis technology flexibility across HPHT-to-CVD transition scenarios. Watch for MEE operating license renewal decisions as inflection indicators for Chinese production capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CVD Reactor Networks | Sandvik Group and Element Six secure substrate supply control for automotive thermal management specifications. |
| Environmental Retrofit Investment | Henan province producers facing MEE standards gain operating license continuity against non-compliant competitors. |
| Direct Specification Relationships | Power semiconductor manufacturers in Japan and Germany bypass electronics distributors for diamond heat spreader procurement. |
| Captive CVD Installation | Osaka and Nagoya packaging houses secure supply chain control through METI-supported reactor deployment. |
| Performance Contracting Models | Sensor-embedded cutting inserts shift revenue from unit sales to guaranteed machining throughput for aerospace suppliers. |
Research Methodology
Trade databases, SEC filings from listed super-hard material producers, and MEE environmental compliance disclosures formed the secondary backbone for supply-side capacity assessment. Primary interviews with CVD deposition technicians, polycrystalline diamond compact procurement managers at oilfield service companies, and thermal management engineers at automotive Tier 1 suppliers validated synthesis technology adoption trajectories. Bottom-up modeling of reactor capacity and utilization rates was triangulated against top-down demand segmentation from aerospace, automotive, and electronics end-use channels.
Historical trendline analysis of HPHT press installations and CVD reactor deployments informed capacity expansion assumptions across the projection horizon. Segmentation modeling incorporated product type, synthesis technology, application vertical, and geographic regulatory cluster dimensions. CAGRs were derived from weighted average growth across these segments calibrated to energy cost trajectories and carbon accounting rule evolution. Forecast inputs included electricity pricing volatility in Chinese manufacturing zones and thermal conductivity specification tightening in German automotive supply chains.
The model assumes a particular technology adoption path; alternative pathways for decentralized CVD reactor deployment at end-user sites would alter the outlook for Henan province production concentration. Forecasts reflect assumptions about MEE enforcement consistency and REACH registration timeline stability. A model refresh is warranted upon material change in China's dual carbon goal implementation pace or automotive inverter thermal management specification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Alginate Films Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Reflective Polarizing Films Market