
 Optical Amplifier Market | 2026-2036
Optical Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Amplifier Market Analysis
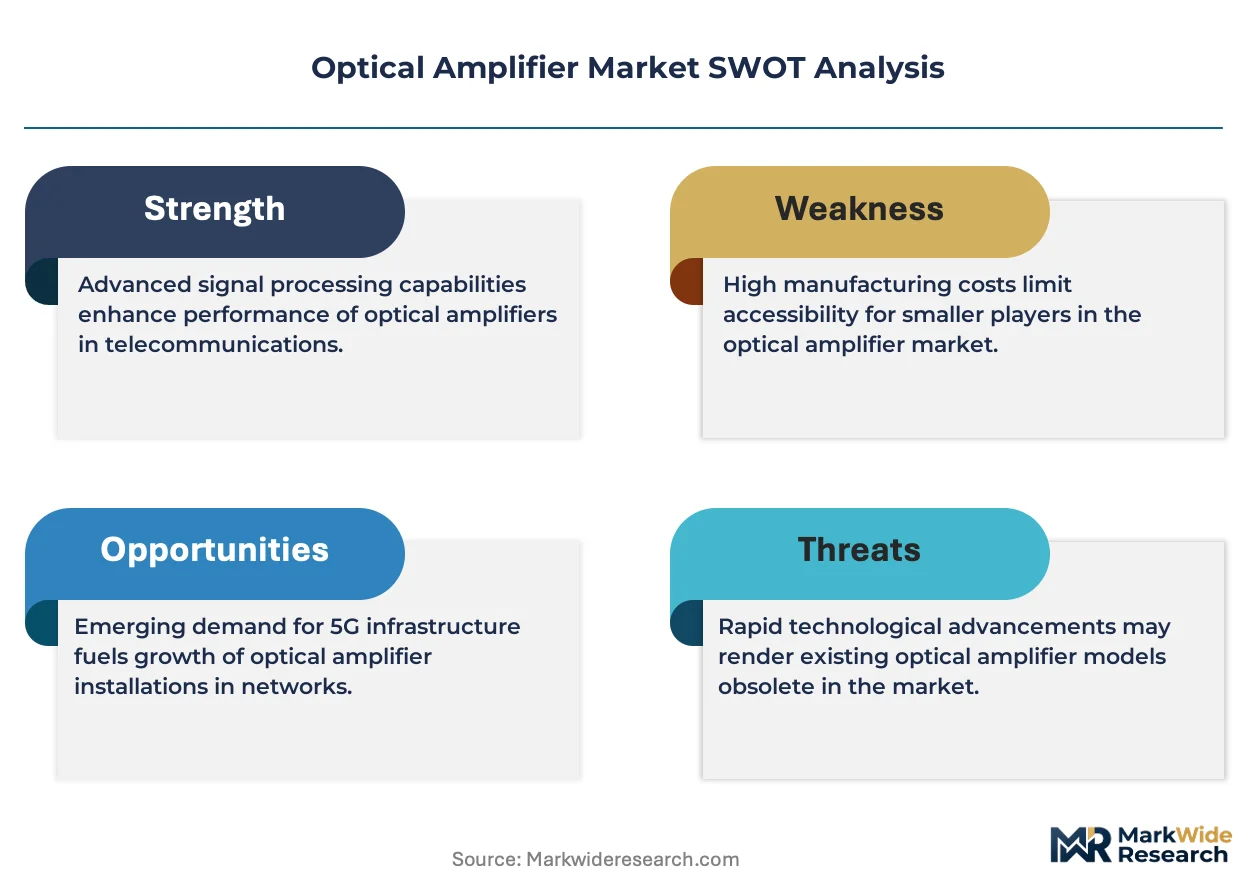
Co-packaged optics and silicon photonics integration is tilting amplifier architectures toward smaller form factors with lower power budgets. Lumentum Holdings Inc. leverages its vertical integration in pump laser diodes to control critical component supply. II-VI Incorporated anchors its position through dominance in gallium arsenide substrate manufacturing for high-power optical chips. Fujitsu competes on system-level integration, embedding amplifiers within end-to-end optical transport platforms rather than selling discrete modules.
An optical amplifier is a device that boosts the amplitude of an optical signal directly without optical-to-electrical conversion, typically employing erbium-doped fiber pumped at 980 nm or 1480 nm to achieve gain across the C-band and L-band windows. It serves primarily to extend transmission distances in fiber optic networks and compensate for splitting losses in dense wavelength division multiplexing systems. EDFA technology occupies the mature core of installed base revenue, while Raman amplification gains traction in submarine cable systems where ultra-low noise figures justify higher complexity. Semiconductor optical amplifiers show the fastest trajectory among product categories as data centers demand compact, integrable solutions for co-packaged transceiver designs.
FCC spectrum management rules in the United States, EU Green Deal energy efficiency mandates under ECHA frameworks, and China's GB standards for telecommunications equipment collectively shape certification requirements and market access protocols across major demand centers. These regulatory layers force manufacturers to maintain parallel compliance tracks for electromagnetic compatibility, material restrictions under REACH, and national security screening of network infrastructure components. Stakeholders must monitor how export control expansions on gallium and germanium substrates reshape supply security for pump laser and specialty fiber inputs.
Market Dynamics
Co-packaged optics integration is compressing amplifier form factors and power budgets, forcing component suppliers to redesign thermal management architectures around silicon photonics substrates rather than discrete fiber-based modules.
Growth Catalysts
- Hyperscale data center buildouts:Interconnection bandwidth requirements at cloud infrastructure facilities are multiplying amplifier deployment density in fiber backbones.
- F-Gas Regulation:The European Union's tightening restrictions on fluorinated greenhouse gases are compelling cooling system redesigns that favor solid-state amplification over refrigerant-dependent architectures.
- Erbium-doped fiber advances:Improved dopant uniformity and pump efficiency are extending C-band and L-band gain flatness without hybrid amplification stages.
Market Restraints
- Gallium arsenide substrate concentration:Pump laser diode manufacturing depends on limited high-purity substrate supply, creating input cost volatility and allocation risk.
- REACH material restrictions:ECHA frameworks constrain certain dopants and coatings used in specialty fiber fabrication, forcing reformulation cycles.
- Semiconductor optical amplifier noise floors:SOA devices exhibit higher amplified spontaneous emission than EDFA alternatives, limiting deployment in noise-sensitive submarine links.
Strategic Opportunities
- India's BharatNet expansion:Rural fiber-to-the-home infrastructure targets create volume demand for cost-optimized amplification modules.
- EU Green Deal energy efficiency mandates:ECHA frameworks incentivize amplifier designs below specific watt-per-gigabit thresholds, rewarding thermal innovation.
- Silicon photonics-Raman convergence:Hybrid integration of waveguide Raman gain with CMOS-compatible processing enables chip-scale amplification for co-packaged transceivers.
Industry Challenges
- Specialized photonics packaging talent:Assembly of high-power pump laser subassemblies requires skills scarce outside Germany's Jena corridor and select Japanese manufacturing centers.
- Dual compliance track maintenance:Manufacturers must simultaneously satisfy FCC electromagnetic compatibility rules, REACH material declarations, and China's GB telecommunications equipment standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Amplifier Market |
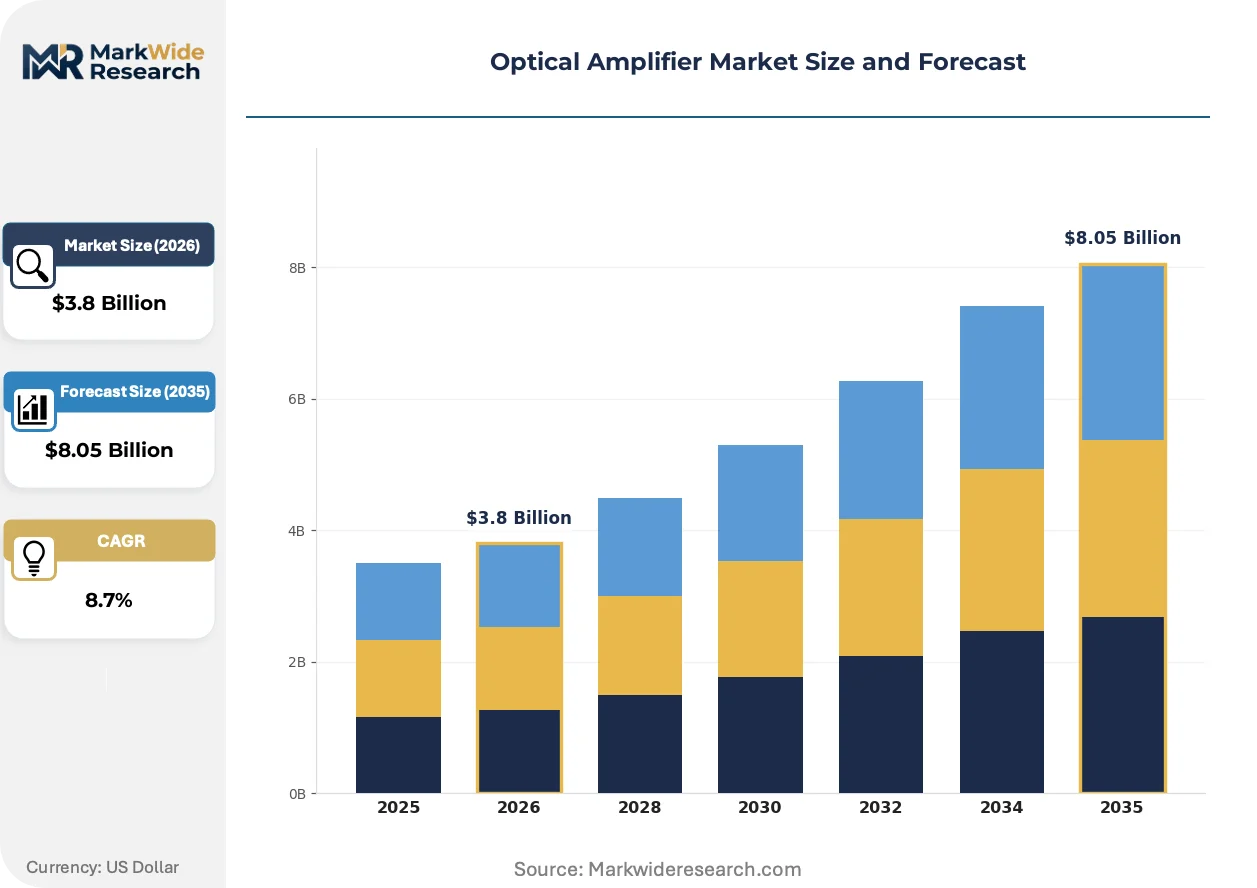
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
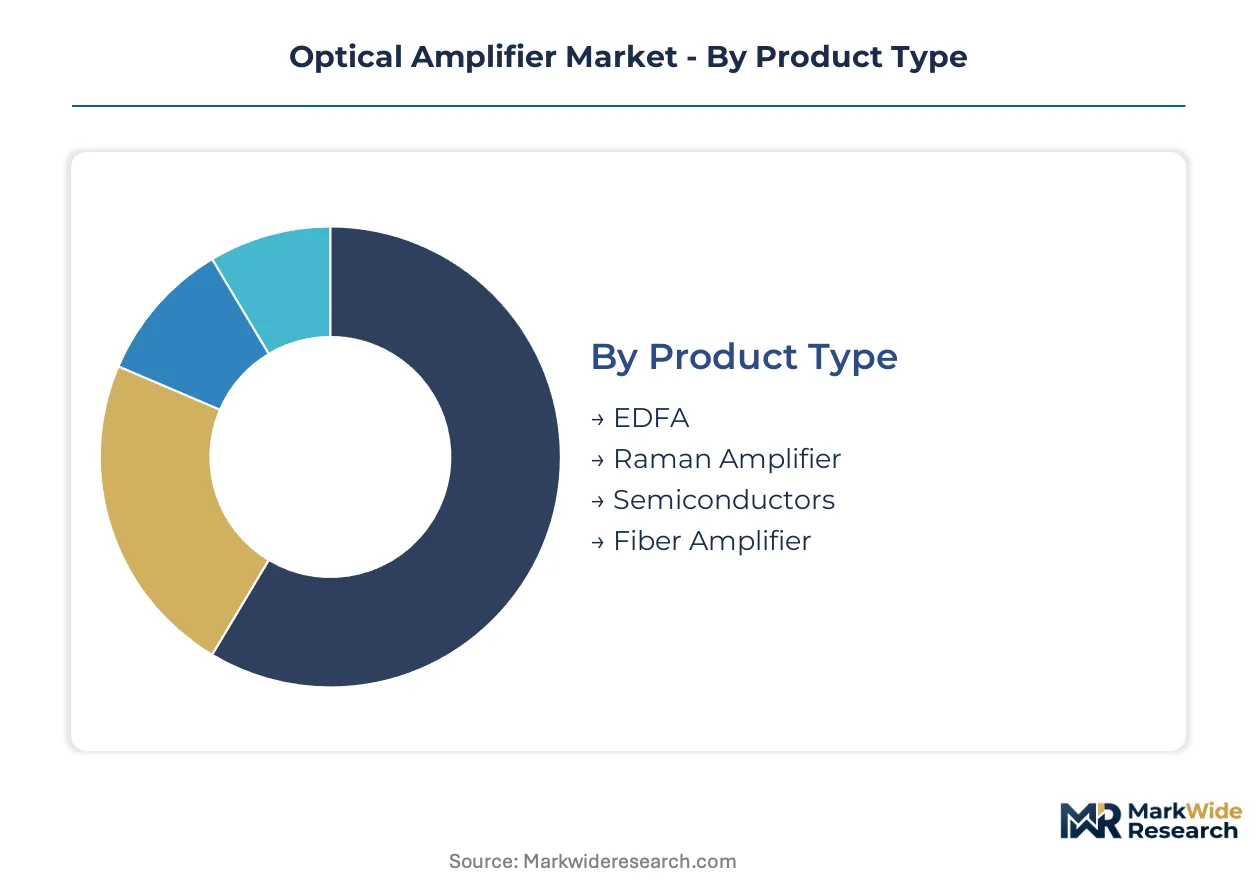
| Segmentation | Product Type: EDFA, Raman Amplifier, Semiconductors, Fiber Amplifier Technology: Wavelength Division Multiplexing, Time Division Multiplexing, Spatial Division Multiplexing, Optical Frequency Combs End User: Telecommunications, Data Centers, Research Laboratories, Broadcasting Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Lumentum Holdings Inc., Ciena Corporation, Huawei Technologies Co., Ltd., Cisco Systems Inc., II-VI Incorporated, Broadcom Inc., Fujitsu, NEC Corporation, Infinera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Amplifier Market Emerging Trajectories
Amplifier architectures are converging toward silicon photonics substrates, driven by data center demands for integrable, low-power alternatives to discrete erbium-doped fiber modules.
Silicon photonics integration embeds optical gain functions directly onto CMOS-compatible substrates, eliminating fiber pigtail interfaces. Hyperscale data center operators are adopting these devices for co-packaged transceiver designs at accelerating pace. This convergence is rendering obsolete traditional discrete amplifier modules with separate pump lasers and fiber couplers.
The European Union's F-Gas Regulation is tightening phase-down schedules for hydrofluorocarbon refrigerants used in amplifier cooling systems. Equipment manufacturers must redesign thermal architectures around passive or liquid cooling alternatives. Submarine cable system suppliers face the steepest compliance burden, as their sealed repeater housings historically relied on refrigerant-based temperature stabilization.
Buying patterns among telecommunications carriers are compressing qualification cycles for new amplifier suppliers. Procurement teams now demand pre-certified modules compatible with multiple vendor transport platforms, displacing historical single-source equipment relationships. This shift is most visible in Germany's Deutsche Telekom and France's Orange procurement frameworks, where interoperability testing precedes volume commitments.
Optical Amplifier Market Segmentation
Optical amplifier procurement cycles vary dramatically by deployment environment, with hyperscale data center installations refreshing every 3-4 years while submarine cable systems operate on 15-20 year replacement horizons. Understanding these velocity differentials helps suppliers calibrate inventory strategies and R&D roadmaps across divergent customer bases.
Product Type:
Replacement cycles stretch from 18 months for data center-destined semiconductor devices to two decades for sealed submarine EDFA repeaters, creating fundamentally different margin and service attach-rate economics.
- EDFA:Erbium-doped fiber amplifiers employ 980 nm or 1480 nm pump lasers to achieve gain across C-band and L-band transmission windows. Deutsche Telekom's procurement frameworks anchor continental European volume, though F-Gas Regulation compliance costs are compressing margins on legacy refrigerant-cooled architectures.
- Semiconductor Optical Amplifiers:Chip-scale devices integrate directly onto silicon photonics substrates for co-packaged transceiver applications. Hyperscale cloud operators in Northern Virginia and Frankfurt are driving the steepest volume acceleration as 800G/1.6T optical links proliferate.
- Raman Amplifier:Distributed amplification through stimulated Raman scattering enables ultra-low noise figures in submarine cable systems. Transoceanic route upgrades between Japan and California concentrate demand.
- Fiber Amplifier:Specialty doped fibers serve niche sensing and metrology applications. Research laboratories in Germany's Jena corridor represent the primary offtake channel.
EDFA anchors the volume base while semiconductor optical amplifiers gain share at the steepest rate.
Technology:
Cost tiers separate mature multiplexing platforms from emerging comb-based architectures still carrying premium pricing for specialized test and measurement applications.
- Wavelength Division Multiplexing:DWDM systems multiplex 80+ channels onto single fiber pairs, with amplifier spacing determining reach economics. Long-haul terrestrial routes across India's BharatNet infrastructure are expanding deployment density.
- Time Division Multiplexing:TDM architectures persist in legacy access networks where amplifier requirements remain minimal. Rural fiber-to-the-home buildouts in France's Orange service territories sustain residual demand.
- Spatial Division Multiplexing:Multi-core and few-mode fiber amplification addresses capacity exhaustion in metro ducts. NTT's testbed installations in Tokyo anchor early commercial traction.
- Optical Frequency Combs:Precision spectroscopy and coherent communications testbeds drive specialized amplifier requirements. National metrology institutes in Germany and Japan represent the concentrated customer base.
Wavelength division multiplexing dominates installed value while spatial division multiplexing climbs fastest from negligible base.
End User:
Customer type dictates specification rigor, with telecommunications carriers demanding decade-long reliability guarantees versus research laboratories accepting higher failure rates for experimental performance boundaries.
- Telecommunications:Tier-1 carriers specify amplifier mean-time-between-failures exceeding 25 years for submarine applications. FCC certification requirements and China's GB standards create parallel compliance tracks for equipment vendors.
- Data Centers:Hyperscale operators prioritize power efficiency and thermal density over absolute reliability. Interconnection bandwidth multiplication at cloud facilities is forcing 3-year amplifier refresh cycles.
- Research Laboratories:Academic and government facilities drive demand for specialized gain bandwidths and nonlinear performance. CERN's fiber infrastructure around Geneva concentrates European scientific procurement.
- Broadcasting:Video transport networks require amplifiers with minimal group delay variation across wide bandwidths. National broadcasters in Germany and Japan sustain niche volume.
Telecommunications anchors the volume base while data centers expand most quickly.
Installation:
Environmental protection ratings and thermal management requirements create four distinct specification clusters with minimal component commonality.
- Offshore:Submarine repeaters operate at depths exceeding 6,000 meters with zero maintenance access. Sealed housings historically relied on hydrofluorocarbon refrigerants now constrained by EU F-Gas Regulation phase-down schedules.
- Outdoor:Hardened amplifiers for cell tower backhaul and rural fiber routes face temperature extremes from -40°C to +65°C. India's BharatNet rural infrastructure targets are expanding volume.
- Indoor:Climate-controlled central offices and data halls enable standard commercial specifications. Germany's Berlin-Brandenburg data center cluster concentrates European indoor deployment.
- Onshore:Terrestrial long-haul routes require amplifier huts with active cooling across desert and alpine environments. Cross-United States fiber corridors sustain steady replacement demand.
Onshore terrestrial installations anchor the volume base while offshore submarine systems command the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German photonics manufacturers export precision amplifier components to data center operators across Northern Virginia and Frankfurt, establishing the primary trade-flow corridor in this sector.
United States
Hyperscale cloud infrastructure in Northern Virginia and Dallas-Fort Worth drives dense amplifier deployment in fiber backbones. FCC spectrum management rules govern electromagnetic compatibility certification for network equipment. Boston's photonics research cluster feeds engineering talent into commercial amplifier design teams.
Germany
Deutsche Telekom's procurement frameworks anchor continental European volume demand for transport-grade amplification. The EU F-Gas Regulation compels cooling system redesigns away from hydrofluorocarbon refrigerants. Berlin and Jena host specialized component clusters serving continental fiber networks with pump laser and specialty fiber expertise.
China
Domestic cloud operators expand interconnection bandwidth in Beijing and Shanghai data center corridors. GB standards for telecommunications equipment establish national certification protocols distinct from Western frameworks. Yangtze River Delta manufacturing bases produce pump laser diodes and erbium-doped fiber for regional supply.
India
BharatNet rural fiber-to-the-home targets create volume demand for cost-optimized amplification modules. TRAI and CEA frameworks govern telecom infrastructure deployment and power efficiency standards. Maharashtra and Gujarat manufacturing zones assemble imported photonic subcomponents into finished amplifier units.
Japan
NTT's testbed installations for spatial division multiplexing anchor early commercial traction in next-generation amplification. METI industrial policy supports photonics R&D through targeted funding mechanisms. Tokyo and Osaka metropolitan corridors concentrate submarine cable system engineering for transoceanic routes.
Optical Amplifier Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into three strata: integrated transport system vendors, discrete component suppliers, and silicon photonics specialists. Strategic archetypes include pump laser diode vertically integrated players, gallium arsenide substrate dominant suppliers, and system-level integration platform providers. Competitive moves center on co-packaged optics partnerships and thermal architecture redesigns for F-Gas compliance.
Within the integrated transport tier, Lumentum Holdings Inc. and Fujitsu occupy positions exemplifying divergent strategic approaches to amplifier market participation. II-VI Incorporated anchors the substrate-specialist archetype through its position in compound semiconductor materials. These three entities represent the dominant competitive anchors around which smaller specialists and regional fabricators organize their market participation.
| Leading Market Players |
|---|
| Lumentum Holdings Inc. |
| Ciena Corporation |
| Huawei Technologies Co., Ltd. |
| Cisco Systems Inc. |
| II-VI Incorporated |
| Broadcom Inc. |
| Fujitsu |
| NEC Corporation |
| Infinera Corporation |
| Others |
Supply Flow & Price Mechanics
Gallium arsenide substrate concentration determines both tiered pricing spreads and supply chain configuration in optical amplification. Single-source dependency on high-purity compound semiconductor feedstocks forces premium pricing for pump laser diodes while compressing margins at the module integration tier.
Pricing Analysis
Technology-generation pricing gaps separate legacy EDFA modules from emerging silicon photonics-integrated alternatives and developmental co-packaged designs. Three-tier pricing structure across submarine-qualified, carrier-grade, and data center-optimized levels reflects certification burden and reliability guarantee differentials. Cost compression in standard terrestrial EDFA tiers is intensifying because hyperscale operators negotiate volume offtakes with shortened refresh cycles. Data center buyers exhibit highest price sensitivity, prioritizing power efficiency metrics over absolute noise performance, while submarine system integrators accept premium positioning for 25-year reliability warranties.
Supply Chain Analysis
Upstream gallium arsenide substrate manufacturing anchors in Germany's Freiberg corridor, Japan's compound semiconductor foundries, and select Chinese state-backed wafer facilities. Pump laser diode fabrication draws from specialty III-V epitaxy houses, erbium-doped fiber preform suppliers cluster around Heraeus in Germany and Corning in the United States, and precision photonics packaging talent concentrates in Jena and select Japanese centers. Single-source vulnerability in high-purity gallium and germanium substrates, subject to export control expansion, threatens input security. Distribution runs through direct OEM partnerships for submarine and carrier equipment, with merchant component channels serving data center integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical amplification sits in early-cycle expansion as co-packaged optics penetration accelerates data center refresh velocity and silicon photonics integration opens new architectural possibilities.
For Market Incumbents: Entrench pump laser diode supply control through backward integration into epitaxial wafer production or long-term offtake agreements with German and Japanese substrate suppliers. Solidify thermal architecture IP for F-Gas-compliant cooling designs before regulatory phase-down deadlines eliminate refrigerant-dependent competitors. Threat substitution from semiconductor optical amplifiers in noise-tolerant applications demands pre-emptive positioning in hybrid amplification portfolios.
For New Entrants and Emerging Players: Build out silicon photonics-Raman hybrid capabilities for co-packaged transceiver integration, the most penetrable white-space as 800G/1.6T links proliferate in Northern Virginia and Frankfurt corridors. Target India's BharatNet rural infrastructure with cost-optimized EDFA modules stripped of submarine-grade reliability overengineering. Go-to-market through merchant component distribution rather than direct carrier qualification, bypassing decade-long incumbent relationships.
For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by devaluing refrigerant-cooled equipment portfolios and rewarding thermal innovation capabilities. Long-term viability over a 5-10 year window favors compound semiconductor substrate specialists and silicon photonics integration platforms over discrete module assemblers. Acquisition target archetype: mid-cap pump laser diode manufacturers with captive epitaxy and F-Gas-ready thermal designs. Signal to watch: Deutsche Telekom and Orange procurement framework shifts toward interoperability certification as precursor to volume supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Partnership | Silicon photonics integration with hyperscale cloud operators accelerates 800G/1.6T deployment timelines. |
| F-Gas Thermal Architecture Redesign | Passive and liquid cooling alternatives replace hydrofluorocarbon refrigerants in submarine repeater housings. |
| Backward Integration into Epitaxy | Captive gallium arsenide substrate supply secures pump laser diode input against export control volatility. |
| BharatNet Cost Optimization Program | Stripped-down EDFA modules address rural fiber-to-the-home volume targets with reduced reliability overhead. |
| Interoperability Certification Investment | Pre-certified module compatibility with multiple transport platforms compresses carrier qualification cycles. |
Methodological Framework
The analysis maps EDFA, semiconductor optical amplifier, Raman amplifier, and fiber amplifier sub-sectors, each validated through network equipment procurement managers, photonics component engineers, data center interconnection planners, and submarine cable system architects. Primary interviews with these stakeholders combined with secondary validation against FCC equipment authorization databases, EU ECHA REACH declarations, China's GB telecommunications certification records, and hyperscaler capex disclosures. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and installation segmentation dimensions.
Assumptions around co-packaged optics penetration velocity, F-Gas Regulation compliance timelines, and gallium export control stringency were held fixed at baseline scenarios while varying hyperscale data center buildout intensity and BharatNet deployment pacing across sensitivity runs. Segmentation dimensions modeled include amplification technology, multiplexing architecture, customer type, and environmental installation class. CAGRs were derived from installed base replacement velocity differentials and net new deployment absorption rates, with pump laser diode supply constraints and silicon photonics yield learning curves as industry-specific forecast inputs.
Stress conditions across gallium arsenide substrate allocation, F-Gas phase-down acceleration, and co-packaged optics adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged revision risk from export control expansion, REACH material restriction additions, or hyperscaler demand shifts. Cross-checking against equipment vendor backlog disclosures and carrier procurement pipeline visibility is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
VCSEL for Data Communication Market
Optical Components
Pancake Optical Module Market
Optical Components
100G Optical Transceivers Market
Optical Components
Global Tunable Filter Market
Optical Components
Optical Isolator Market
Optical Components
Silicon Photonics Wafer Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Fluorophore Market
Optical Components
Optical Transceiver Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Spatial Light Modulator Market
Optical Components
Global Optical Measurement Market
Optical Components
Faraday Rotator Market