
 Waveguide Phase Shifter Market | 2026-2036
Waveguide Phase Shifter Market Size, Share, and Industry Trends Forecast 2026-2036
Waveguide Phase Shifter Market Insights
The gap between ferrite and semiconductor phase shifter architectures is narrowing as gallium nitride foundries mature and thermal management solutions improve. Qorvo leverages its compound semiconductor foundry network to anchor high-volume military contracts. L3Harris Technologies sustains dominance in shipborne radar integration through captive testing facilities. China Electronics Technology Group Corporation competes on cost-engineered ferrite designs for domestic satellite programs.
A waveguide phase shifter is a passive or active RF component that introduces a controlled phase delay to electromagnetic signals propagating through hollow metallic waveguide structures, typically operating between 1 GHz and 110 GHz with insertion loss below 1 dB in precision designs. Engineers deploy these devices to steer beam patterns in phased array antennas without mechanical rotation. Ferrite phase shifters occupy the mature high-power segment where margin pools erode slowly under long-term defense contracts. Semiconductor phase shifters lead commercial volume growth as telecom operators densify 5G millimeter-wave infrastructure. Digital phase shifters attract R&D investment from research institutes seeking programmable beamforming for quantum communication experiments.
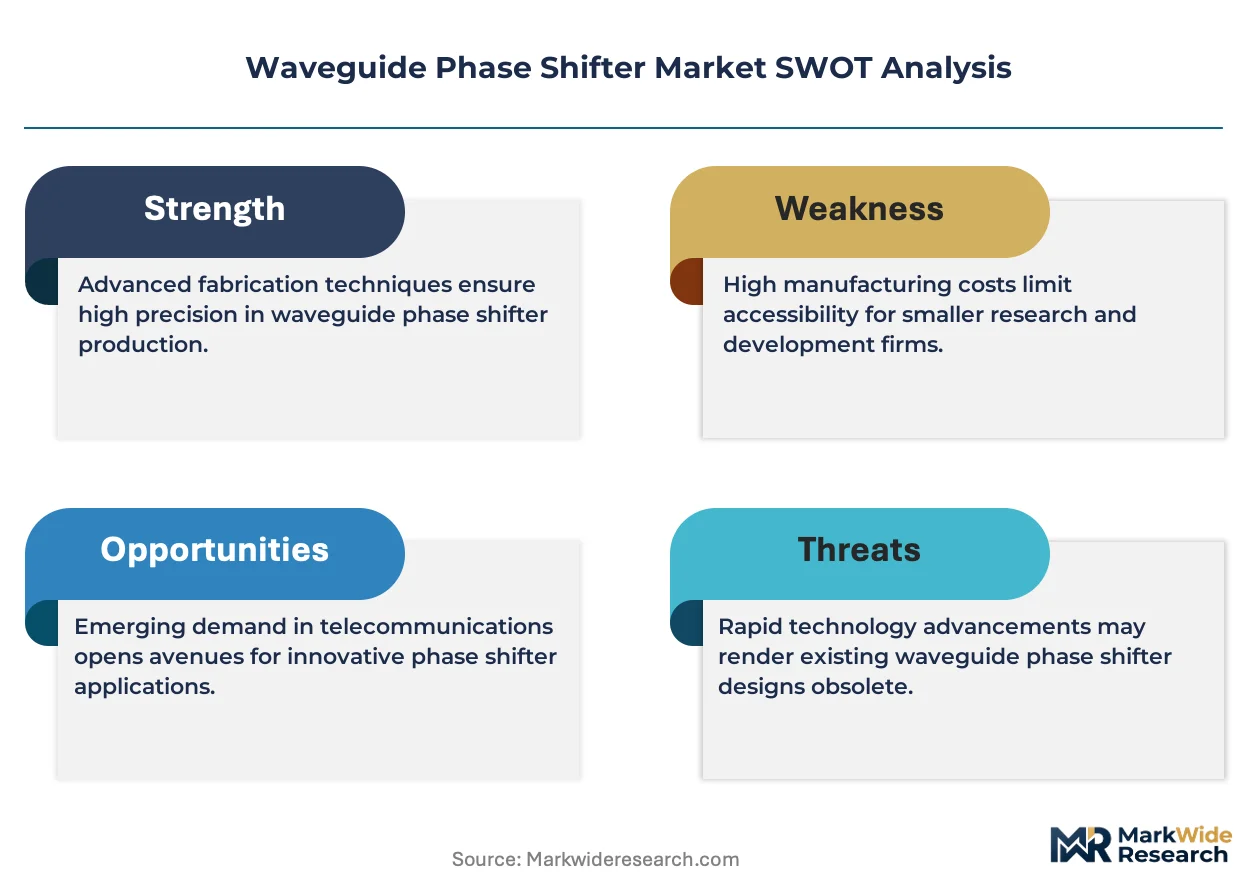
The FCC governs spectrum efficiency mandates that force equipment refreshes in civilian telecommunications, while the EPA restricts hexavalent chromium in waveguide plating processes. EAR and ITAR frameworks administered by the US Commerce and State Departments control export licensing for phase shifters exceeding specific power thresholds. Stakeholders must monitor how dual-use technology classifications reshape supplier eligibility for cross-border defense contracts.
Market Dynamics
The waveguide phase shifter market faces structural pressure from gallium nitride foundry maturation, which erodes the traditional performance gap between ferrite and semiconductor architectures while defense procurement cycles lengthen.
Growth Catalysts
- Electronically Scanned Arrays:NATO defense contractors are expanding procurement of active electronically scanned arrays for fighter aircraft and naval vessels, creating sustained demand for high-power phase shifters.
- Spectrum Reallocation Mandates:The FCC's forced replacement of legacy RF hardware in civilian telecommunications accelerates equipment refresh cycles across base station infrastructure.
- 5G Millimeter-Wave Densification:Telecom operators in Germany's aerospace manufacturing corridor around Munich and Hamburg are deploying semiconductor phase shifters for small-cell backhaul networks.
Market Restraints
- Hexavalent Chromium Restrictions:The EPA's plating process regulations constrain waveguide manufacturing throughput and raise compliance costs for domestic suppliers.
- Export Licensing Friction:EAR and ITAR frameworks administered by the US Commerce and State Departments create bureaucratic delays for cross-border defense contracts exceeding specific power thresholds.
- Thermal Management Complexity:High-power ferrite designs face inherent heat dissipation limitations that restrict miniaturization for space-constrained platforms.
Strategic Opportunities
- Quantum Communication R&D:Research institutes are investing in programmable digital phase shifters for beamforming experiments in quantum key distribution systems.
- Satellite Constellation Expansion:Domestic satellite programs in China favor cost-engineered ferrite designs for LEO and MEO payload applications.
- Dual-Use Technology Reclassification:Stakeholders can exploit evolving dual-use classifications to access previously restricted supplier pools for cross-border contracts.
Industry Challenges
- Compound Semiconductor Talent Scarcity:Gallium nitride foundry operations face acute shortages of RF device physicists and thermal engineers capable of precision design.
- Captive Testing Infrastructure:Shipborne radar integration demands specialized anechoic chambers and naval environmental simulation facilities that require heavy capital deployment.
- Legacy System Interoperability:New phase shifter architectures must maintain backward compatibility with existing waveguide flange standards and mechanical interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waveguide Phase Shifter Market |
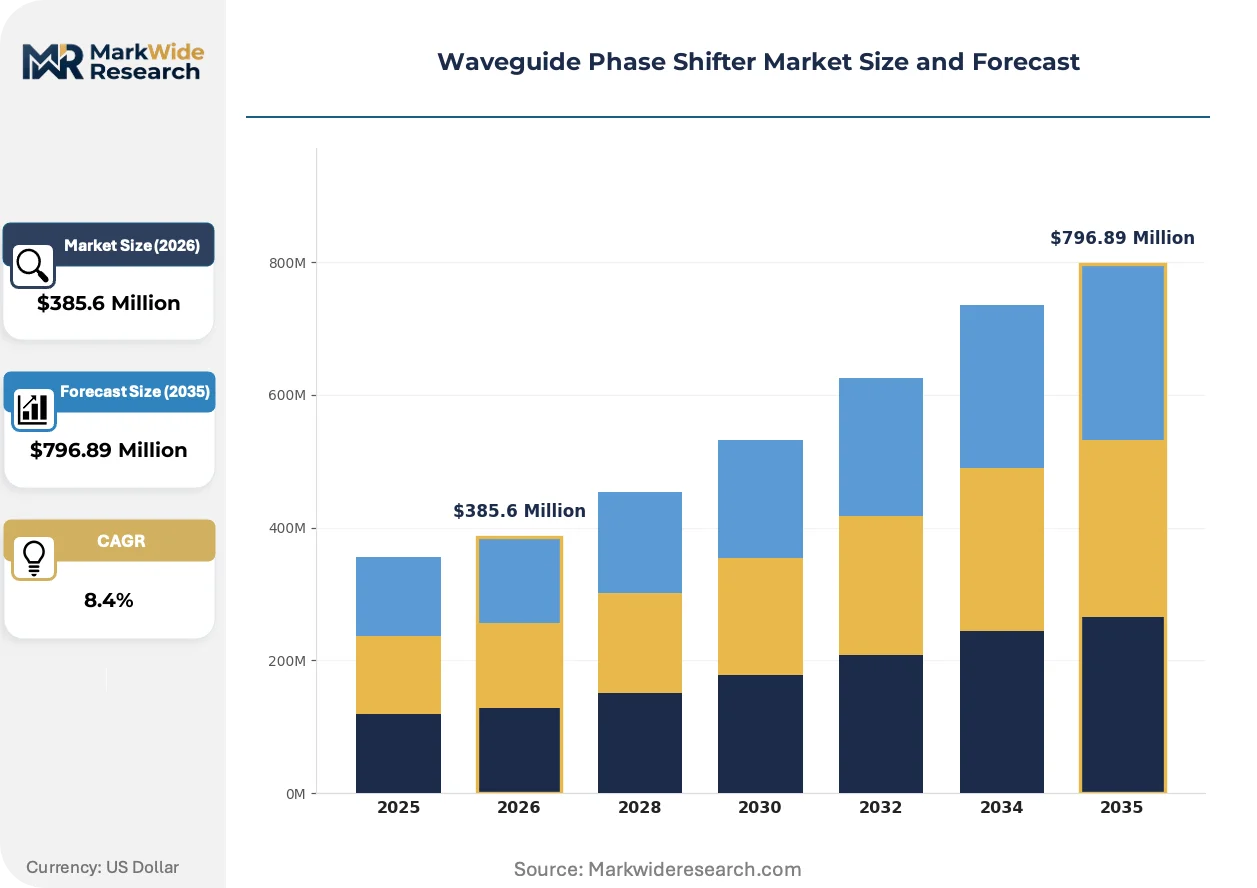
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrite Phase Shifter, Mechanical Phase Shifter, Semiconductor Phase Shifter, Analog Phase Shifter, Digital Phase Shifter Technology: MEMS, Liquid Crystal, Piezoelectric, Electro-optic, Magneto-optic Application: Radar Systems, Satellite Communication, Military Communication, Telecommunication Networks, Space Exploration End User: Defense Contractors, Aerospace Manufacturers, Telecom Operators, Research Institutes |
| Companies Covered | Flann Microwave, Thales Group, Microwave Techniques, Qorvo, Rosenberger, Mega Industries, L3Harris Technologies, China Electronics Technology Group Corporation, Pasternack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waveguide Phase Shifter Market Trends and Innovations
Phase shifter architectures are converging as material science advances and thermal engineering solutions mature, compressing the traditional performance hierarchy between established technologies.
Gallium nitride-on-silicon-carbide substrates are hybridizing the phase shifter landscape by combining semiconductor switching speed with ferrite-grade power handling. Defense prime contractors are piloting these devices for next-generation radar front-ends. The technology is hybridizing procurement patterns as buyers no longer default to ferrite for high-power applications.
REACH restrictions on hazardous substances in electronic equipment are forcing waveguide manufacturers to eliminate hexavalent chromium from plating baths and cadmium from connector finishes. European suppliers face the steepest compliance timelines. Military-specification phase shifters for NATO platforms are migrating to trivalent chromium and electroless nickel alternatives.
Buyer concentration among tier-one defense primes and national telecom operators is compressing supplier negotiation leverage. Small-to-mid phase shifter vendors are ceding ground to integrated subsystem providers with captive RF component capabilities. Germany's defense industrial base exhibits the most pronounced consolidation, with Munich and Hamburg corridors absorbing independent component suppliers into platform prime supply chains.
Waveguide Phase Shifter Market Segmentation
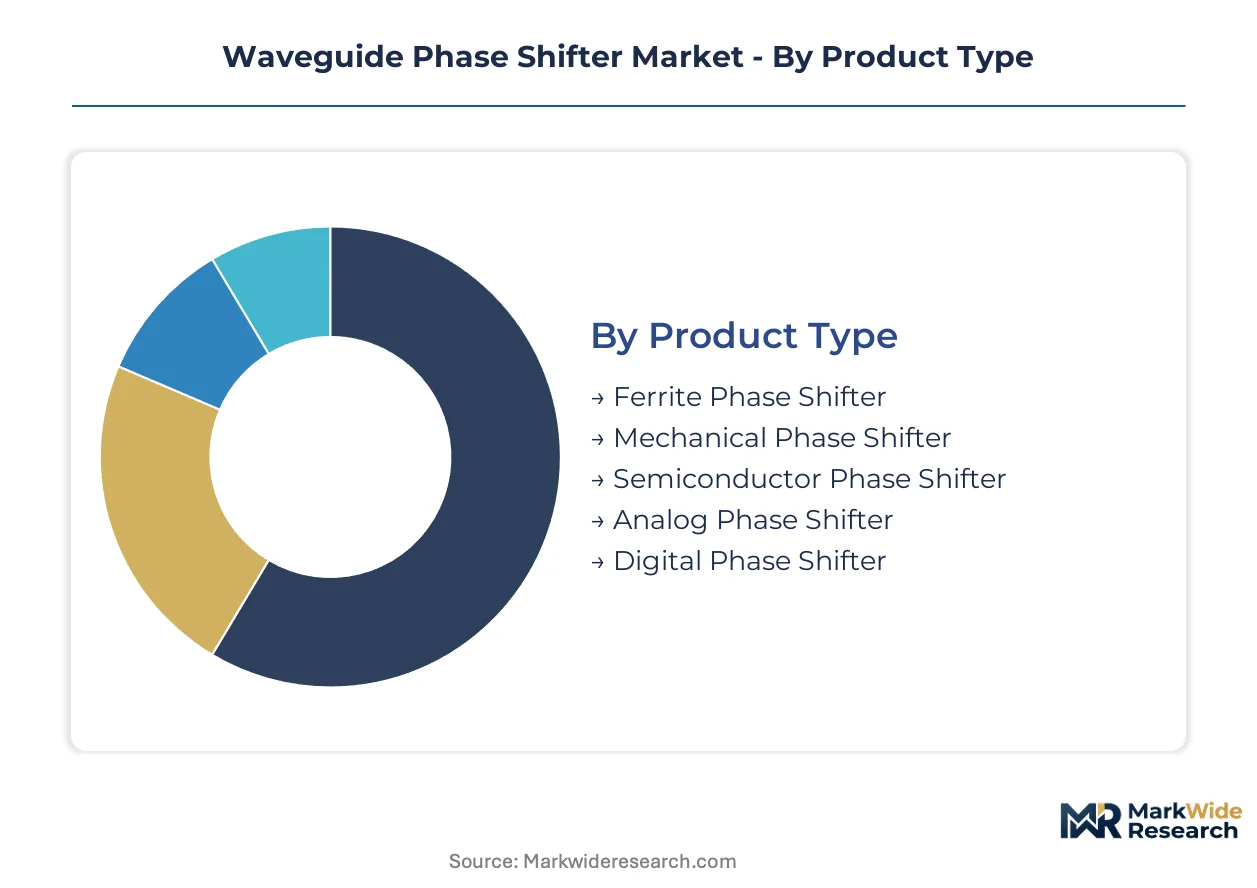
Waveguide phase shifter procurement patterns diverge sharply across product architectures and end-use verticals. Defense contracts favor ferrite reliability while commercial telecom drives semiconductor volume. Technology selection hinges on power handling requirements, switching speed demands, and thermal constraints specific to each deployment environment.
Product Type:
Cost tier differentiation separates legacy military-grade designs from emerging commercial alternatives. Premium pricing attaches to high-power ferrite systems under long-term defense contracts. Economy positioning concentrates in semiconductor variants for mass-market telecom infrastructure.
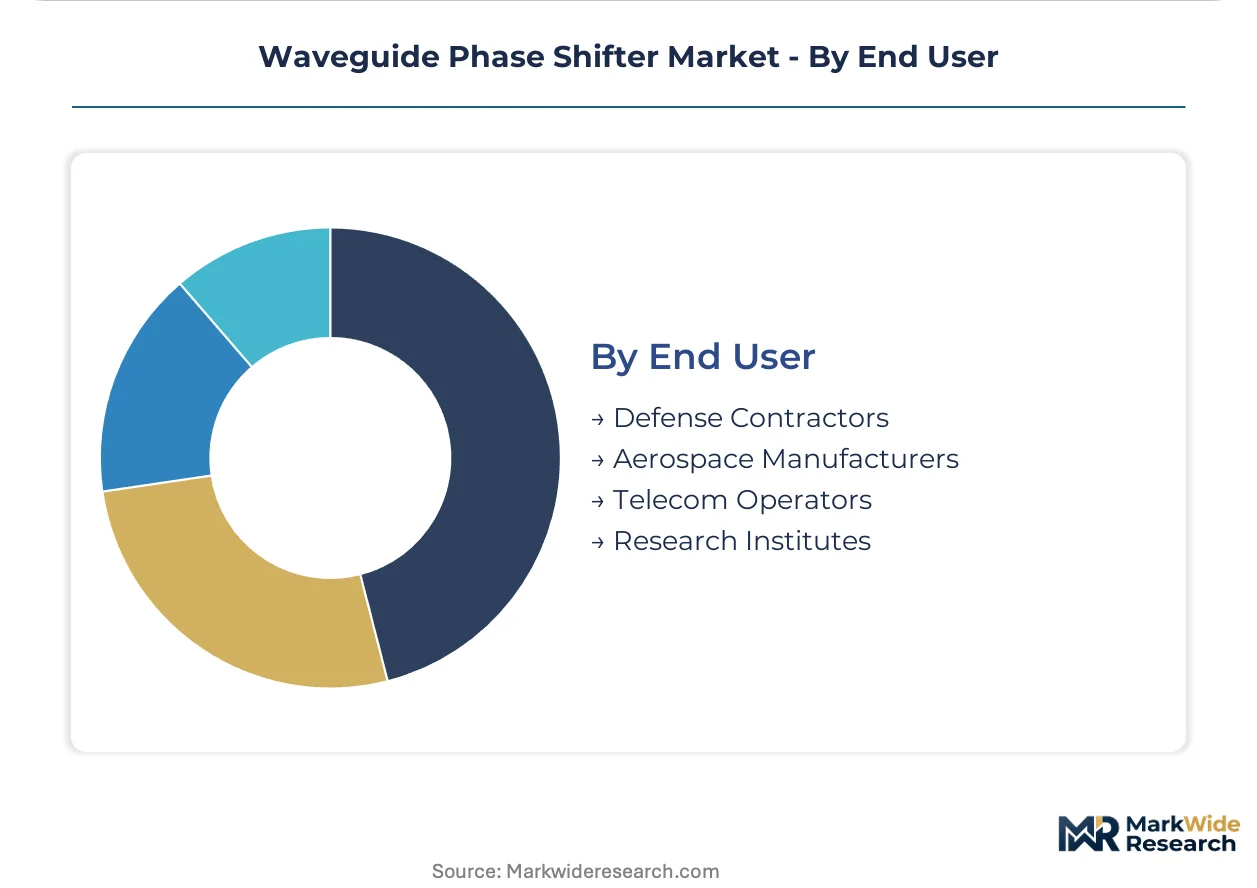
- Ferrite Phase Shifter:These devices exploit gyromagnetic resonance in ferrite materials to achieve phase control with power handling exceeding kilowatt levels. Defense contractors across NATO member states anchor procurement for fighter radar and naval fire-control systems where thermal stability under extreme load matters more than switching speed.
- Semiconductor Phase Shifter:Gallium nitride and silicon germanium designs deliver nanosecond switching for agile beam steering. Telecom operators in Germany's aerospace manufacturing corridor deploy these for 5G millimeter-wave small-cell densification where cost-per-unit and footprint drive selection.
- Mechanical Phase Shifter:Motorized dielectric plungers or rotary vane configurations serve laboratory test equipment and calibration standards.
- Analog Phase Shifter:Continuous phase variation supports smooth beam shaping in satellite communication uplink terminals.
- Digital Phase Shifter:Discrete phase states with bit-resolution precision enable programmable beamforming for quantum communication experiments at research institutes.
Ferrite phase shifters command the established base. The steepest expansion runs through semiconductor phase shifters.
Technology:
Application requirements dictate technology selection across the frequency and power spectrum. Radar front-ends prioritize switching speed and thermal resilience. Satellite payloads emphasize low insertion loss and radiation hardness.
- MEMS:Microelectromechanical systems employ electrostatically actuated cantilevers or bridges to vary transmission line geometry. Aerospace manufacturers integrate MEMS phase shifters for reconfigurable satellite antennas where gram-level mass budgets override switching speed limitations.
- Liquid Crystal:Nematic liquid crystal layers alter dielectric constant under applied electric field for continuous phase tuning. Research institutes in quantum communication programs favor liquid crystal devices for low-power programmable beamforming at optical and millimeter-wave frequencies.
- Piezoelectric:Mechanical deformation of ferroelectric substrates enables precise phase control with minimal power consumption.
- Electro-optic:Voltage-dependent refractive index changes in lithium niobate support ultra-fast modulation for photonic integrated circuits.
- Magneto-optic:Faraday rotation in magnetized garnet crystals provides non-reciprocal phase shift for isolator and circulator applications.
MEMS technology anchors established satellite programs. The steepest expansion trajectory belongs to liquid crystal approaches.
Application:
End-use concentration varies by power regime and regulatory environment. Military applications sustain premium pricing through ITAR-controlled supply chains. Commercial telecom faces FCC-mandated refresh cycles that accelerate replacement demand.
- Radar Systems:Phased array antennas for air defense, weather monitoring, and automotive collision avoidance demand phase shifters with rapid beam agility. Defense contractors in Germany's Munich corridor integrate these for next-generation fighter radar where gallium nitride foundry output is displacing legacy ferrite procurement.
- Telecommunication Networks:Base station beamforming and backhaul links require cost-optimized phase shifters at millimeter-wave frequencies. The FCC's spectrum reallocation mandates force equipment refreshes across United States cellular infrastructure, accelerating semiconductor phase shifter adoption.
- Satellite Communication:Geostationary and low-earth-orbit payloads need radiation-hardened phase control for steerable spot beams.
- Military Communication:Secure tactical networks rely on ferrite-based designs for electronic warfare resilience and high-power tolerance.
- Space Exploration:Deep-space missions impose extreme reliability requirements with minimal maintenance access.
Radar systems command the established base. The steepest expansion runs through telecommunication networks.
End User:
Customer type determines procurement volume, contract structure, and technical specification rigor. Defense primes negotiate multi-year sole-source agreements. Research institutes drive early adoption of experimental architectures.
- Defense Contractors:Lockheed Martin, Raytheon, and BAE Systems anchor demand for high-reliability ferrite phase shifters under ITAR-controlled supply chains. These buyers prioritize thermal management and electromagnetic compatibility over unit cost.
- Telecom Operators:Deutsche Telekom, Verizon, and NTT deploy semiconductor phase shifters for 5G infrastructure densification. Volume procurement and competitive tendering compress supplier margins while accelerating technology refresh cycles.
- Aerospace Manufacturers:Airbus, Boeing, and Thales integrate phase shifters for radar and communication payloads with stringent qualification protocols.
- Research Institutes:CERN, MIT Lincoln Laboratory, and Fraunhofer institutes pilot digital and liquid crystal phase shifters for quantum communication and radio astronomy applications.
Defense contractors command the established base. The steepest expansion runs through telecom operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense primes and telecom operators concentrate procurement in mature industrial corridors with captive testing infrastructure and compound semiconductor foundry access. Buyer archetypes cluster around NATO defense contractors in Western Europe, FCC-regulated carriers in North America, and state-backed satellite programs in Asia.
United States
The FCC's spectrum reallocation mandates force cellular operators to refresh base station hardware, accelerating semiconductor phase shifter procurement for millimeter-wave networks. EPA restrictions on hexavalent chromium plating constrain domestic manufacturing throughput and elevate compliance costs. Boston and Los Angeles corridors host defense primes integrating gallium nitride devices into next-generation radar front-ends.
Germany
REACH regulations on hazardous substances drive waveguide manufacturers toward trivalent chromium and electroless nickel alternatives in plating processes. The country's aerospace manufacturing corridor around Munich and Hamburg anchors demand for electronically scanned arrays in fighter aircraft and naval vessels. Thales and Airbus suppliers in Bavaria maintain captive anechoic chambers for shipborne radar qualification.
China
State-backed satellite constellation programs favor cost-engineered ferrite designs for LEO and MEO payload applications. MIIT spectrum policies and GB standards govern domestic telecommunications infrastructure refresh cycles. Beijing and Shanghai corridors concentrate foundry capacity for compound semiconductor phase shifter production serving both civilian and military programs.
United Kingdom
BAE Systems and defense primes sustain procurement of ITAR-controlled ferrite phase shifters for fighter radar and electronic warfare systems. The UK Space Agency's satellite funding programs stimulate demand for radiation-hardened components in geostationary payloads. Bristol and Stevenage clusters host subsystem integrators with captive RF testing capabilities.
Japan
METI industrial policy supports gallium nitride foundry maturation for next-generation radar and telecommunications applications. NTT and KDDI deploy semiconductor phase shifters for 5G millimeter-wave densification in Tokyo and Osaka metro areas. Yokohama and Nagoya corridors concentrate precision machining capacity for waveguide fabrication serving aerospace and defense programs.
Waveguide Phase Shifter Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Defense primes and integrated subsystem providers dominate high-value contracts through captive testing infrastructure and long-term sole-source agreements. The vendor base separates into three strategic archetypes: compound semiconductor foundry operators, ferrite legacy specialists, and integrated defense platform primes. Competitive moves center on foundry capacity expansion and strategic partnerships to secure gallium nitride wafer supply.
Among defense-integrated primes, L3Harris Technologies and Thales Group exemplify the platform-captive archetype with in-house RF component capabilities and anechoic testing facilities. Qorvo represents the compound semiconductor foundry tier with high-volume military contract anchoring. China Electronics Technology Group Corporation occupies the state-backed cost-engineering position for domestic satellite programs.
| Leading Market Players |
|---|
| Flann Microwave |
| Thales Group |
| Microwave Techniques |
| Qorvo |
| Rosenberger |
| Mega Industries |
| L3Harris Technologies |
| China Electronics Technology Group Corporation |
| Pasternack |
| Others |
Pricing and Supply Chain Analysis
The Hamburg-Rotterdam freight corridor's volatile container rates ripple through waveguide phase shifter landed costs, amplifying price spreads between ferrite legacy suppliers in Germany and semiconductor foundry outputs in East Asia while defense primes absorb premiums for ITAR-compliant sourcing.
Pricing Analysis
Cost-plus contracts with Bureau of Labor Statistics producer price indexation dominate defense procurement, insulating NATO suppliers from raw material swings while telecom operators face spot-market volatility in gallium nitride substrates. Price differentiation rests on ITAR certification tier and thermal management specification, with radiation-hardened ferrite designs commanding substantial premiums over commercial-grade semiconductor variants. Cost compression in 5G infrastructure tiers intensifies as Deutsche Telekom and Verizon consolidate vendor pools. Research institutes exhibit lowest price sensitivity, prioritizing programmable precision over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in yttrium iron garnet ferrite powders centers on Chinese rare earth processing facilities and Japanese specialty chemical manufacturers, with gallium nitride epitaxial wafers drawing from foundry capacity in Taiwan, South Korea, and the United States. Critical dependencies include high-purity iron oxide, rare earth oxides, and silicon carbide substrates. Single-source vulnerability in gallium nitride-on-silicon-carbide wafer supply threatens semiconductor phase shifter output scaling. Distribution runs through tier-one defense primes with captive RF integration capabilities and direct OEM relationships with telecom infrastructure vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waveguide phase shifter procurement fragments across divergent buyer archetypes—defense primes demanding ITAR fidelity, telecom operators optimizing cost-per-link, and research institutes pioneering quantum architectures—creating specialized niches resistant to commoditization.
For Market Incumbents: Harden supply chain resilience through backward integration into gallium nitride epitaxial growth or captive ferrite powder processing, countering foundry capacity constraints that threaten fulfillment on multi-year naval radar contracts. Deepen anechoic chamber infrastructure in Munich and Hamburg corridors to defend sole-source qualification status against emerging subsystem integrators. For New Entrants and Emerging Players: Establish a beachhead in liquid crystal phase shifters for quantum communication R&D programs at Fraunhofer and MIT Lincoln Laboratory, where procurement flexibility overrides incumbent scale advantages. Target commercial satellite constellation suppliers in China with cost-engineered ferrite alternatives to state-backed incumbents, leveraging trivalent chromium plating compliance as a regulatory wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from defense platform primes divesting non-core RF component divisions under portfolio rationalization pressures. Long-term viability hinges on dual-use technology reclassification trends that expand addressable markets beyond ITAR-restricted defense pools. Monitor FCC spectrum auction timelines as inflection signals for telecom infrastructure refresh velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Partnership | Qorvo and defense primes secure wafer supply for next-generation radar front-ends. |
| Trivalent Chromium Plating Conversion | European suppliers achieve REACH compliance ahead of regulatory deadlines. |
| Captive Anechoic Chamber Investment | L3Harris and Thales maintain sole-source qualification for shipborne integration. |
| Quantum Communication R&D Collaboration | Research institutes pilot digital phase shifters for programmable beamforming. |
| Dual-Use Technology Reclassification | Stakeholders access previously restricted supplier pools for cross-border contracts. |
Research Methodology
A standing panel of RF device physicists, defense procurement officers at NATO primes, telecom infrastructure planners, and waveguide manufacturing engineers provided ongoing calibration across primary interview rounds, with secondary validation drawing from FCC equipment authorization databases, EAR/ITAR licensing records, SEC supplier disclosure filings, and compound semiconductor foundry utilization reports. Bottom-up build-ups of phase shifter unit economics triangulated against top-down defense budget allocation models.
Scenario-bracketing around gallium nitride foundry maturation velocity, REACH compliance timeline slippage, and dual-use reclassification probability bounded projections across the analysis window. Segmentation modeling spanned product architecture, power handling tier, switching speed requirement, and end-use regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating 5G millimeter-wave densification schedules and electronically scanned array procurement cycles.
Stress conditions across rare earth export restrictions, gallium nitride wafer supply disruptions, and EPA plating process enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense procurement cycle continuity and telecom infrastructure refresh cadence. Cross-checking against Department of Defense budget justification materials and FCC spectrum auction proceeds is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Spatial Light Modulator Market
Optical Components
Global Optical Imaging System Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Film Market
Optical Components
Objective Lens Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Display Optical Film Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Quartz Glass Substrate Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Fiber-Optic Attenuator Market
Optical Components
Optical Dome Market