
 Electronic Digital Magnifiers Market | 2026-2036
Electronic Digital Magnifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Digital Magnifiers Market Insights
High-resolution CMOS sensor integration with AI-powered text-to-speech is tilting the core technology stack away from pure optical magnification toward intelligent vision assistance systems. Freedom Scientific leverages its established distribution network across North American rehabilitation centers to sustain recurring institutional sales. Enhanced Vision anchors its competitive stance through specialized desktop magnifier lines with integrated OCR capabilities. HumanWare competes in the wearable segment with head-mounted displays that extend user mobility beyond stationary reading tasks.
Electronic digital magnifiers are electro-optical devices that combine camera sensors, liquid crystal or OLED displays, and digital signal processors to enlarge text and images with adjustable contrast, color inversion, and brightness parameters for users with macular degeneration, glaucoma, or diabetic retinopathy. The primary commercial purpose centers on restoring functional independence in reading, medication management, and workplace document handling for individuals with moderate to severe vision loss. Handheld magnifiers occupy the highest unit-volume tier due to portability and lower price points, while wearable magnifiers represent the fastest-expanding segment as head-mounted designs gain traction among younger low-vision users seeking mobility-preserving solutions. Desktop magnifiers concentrate margin pools in institutional channels where healthcare providers and educational facilities prioritize durability and large-screen formats over consumer portability.
The FDA regulates electronic digital magnifiers as Class I medical devices under 510(k) exempt or cleared pathways, while the EU Medical Device Regulation imposes conformity assessment and post-market surveillance obligations through notified bodies. Japan's PMDA maintains distinct pharmaceutical and medical device agency standards that govern software-enabled magnification devices with therapeutic claims. Stakeholders must monitor evolving reimbursement coding decisions by Medicare and national health services, as these determinations directly shape patient out-of-pocket costs and institutional procurement cycles across major demand centers.
Market Dynamics
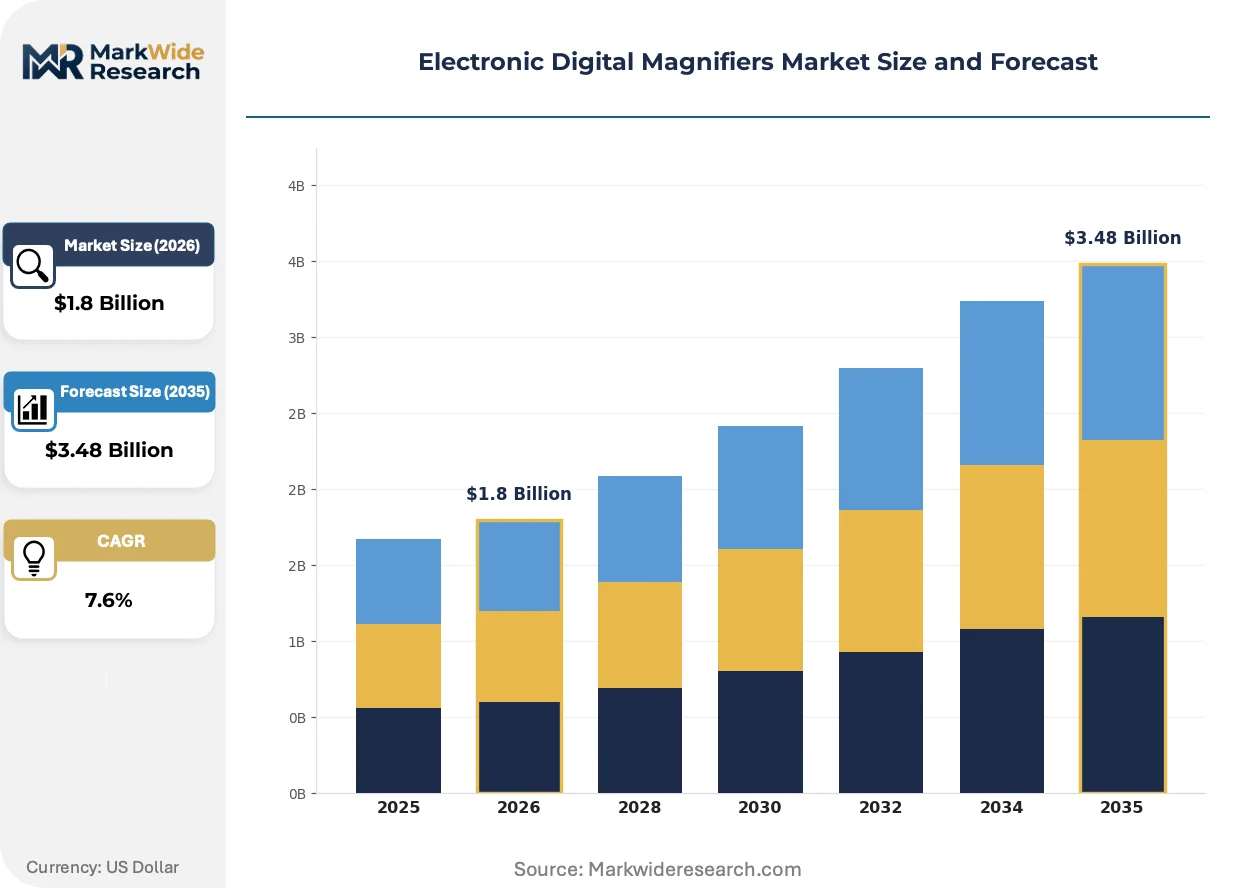
The Electronic Digital Magnifiers Market pivots on reimbursement coding decisions by Medicare and national health services, which compress or expand patient out-of-pocket costs and institutional procurement cycles across major demand centers.
Growth Catalysts
- Aging Demographics:Healthcare providers in the United States, Germany, and Japan are expanding procurement of desktop and wearable units as macular degeneration prevalence rises among populations over 65.
- AI-Powered Text-to-Speech:High-resolution CMOS sensor integration with intelligent vision assistance systems is tilting the core technology stack away from pure optical magnification toward functional independence restoration.
- FDA 510(k) Pathway:The streamlined clearance process for low-vision assistive devices accelerates product development timelines and reduces regulatory friction for manufacturers targeting institutional channels.
Market Restraints
- Input Cost Volatility:OLED display panel prices fluctuate with semiconductor foundry capacity constraints, compressing margins on handheld units at lower price points.
- Supply Concentration Risk:CMOS sensor fabrication concentrates in East Asian foundry clusters, exposing manufacturers to geopolitical trade friction and shipping disruptions.
- Substitution Threat:Smartphone-based magnification applications with built-in accessibility features erode demand for dedicated handheld devices among mild vision impairment users.
Strategic Opportunities
- Underpenetrated Markets:India's nascent reimbursement framework for visual impairment aids presents first-mover advantages for manufacturers establishing distribution through rehabilitation centers.
- Technology Convergence:Integration of head-mounted displays with real-time object recognition and navigation assistance extends wearable magnifiers beyond stationary reading into mobility-preserving solutions.
- Distribution Innovation:Direct-to-patient e-commerce channels bypass traditional optical retail gatekeepers, capturing margin and reducing patient acquisition costs in markets with established digital infrastructure.
Industry Challenges
- Certification Timeline Compression:The EU Medical Device Regulation imposes extended conformity assessment and post-market surveillance obligations through notified bodies, delaying product launches.
- Integration Complexity:Software-enabled magnification devices with therapeutic claims must navigate Japan's PMDA distinct pharmaceutical and medical device agency standards, fragmenting development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Digital Magnifiers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Magnifiers, Desktop Magnifiers, Wearable Magnifiers, Video Magnifiers Technology: Optical, Digital, Hybrid, LCD End User: Individuals with Low Vision, Educational Institutions, Healthcare Providers, Retail Application: Reading Assistance, Daily Living Aids, Office Use, Leisure Activities |
| Companies Covered | Freedom Scientific, Enhanced Vision, HumanWare, Optelec, Zoomax, LVI Low Vision International, Eschenbach Optik, Ash Technologies, Vispero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Digital Magnifiers Market Trends and Innovations
Digital signal processing architectures are virtualizing traditional optical pathways, compressing device form factors while expanding functional capabilities for users with diabetic retinopathy and glaucoma.
Edge-deployed neural networks in head-mounted displays are virtualizing the role of dedicated OCR hardware, enabling real-time text extraction and audio feedback without cloud connectivity. Younger low-vision users in Germany and Japan are adopting these wearable designs at accelerated rates, displacing stationary desktop configurations in workplace document handling scenarios. This shift is virtualizing the traditional product category boundaries between magnification and full vision assistance systems.
The EU Medical Device Regulation (MDR) imposes conformity assessment and post-market surveillance obligations through notified bodies, elevating documentation burdens for software-enabled devices. Manufacturers targeting European institutional channels must restructure quality management systems to meet extended clinical evidence requirements. Desktop magnifier lines with integrated therapeutic claims face the steepest compliance adjustments, compressing launch timelines for mid-tier product refreshes.
Rehabilitation centers and educational facilities are consolidating vendor relationships around full-service contracts bundling hardware, training, and maintenance. This concentration displaces transactional procurement of standalone devices through optical retail channels. The United States exhibits the most pronounced shift, with Medicare reimbursement frameworks favoring bundled service models that reduce patient out-of-pocket complexity.
Electronic Digital Magnifiers Market Segmentation
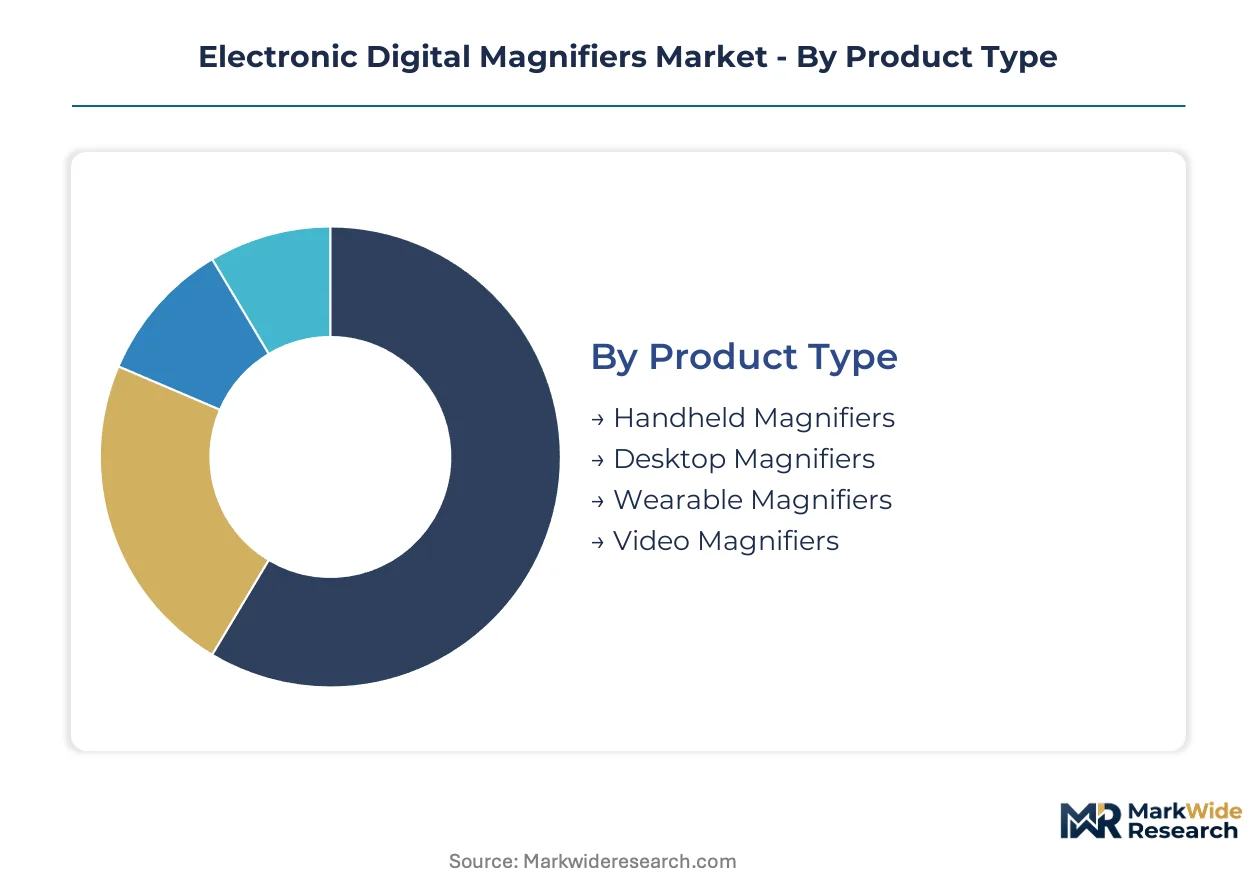
Segmentation in electronic digital magnifiers reveals how technology choices and user mobility requirements split procurement patterns across institutional and consumer channels. Understanding these divides enables manufacturers to align sensor specifications and display formats with reimbursement-eligible use cases.
Product Type:
Handheld units serve intermittent reading tasks, while desktop and wearable configurations address sustained document work and mobility-preserving applications respectively.
- Handheld Magnifiers:Compact CMOS-based devices with 3-7 inch LCD or OLED panels deliver pocket-portable magnification for price-sensitive consumers. Demand concentrates in retail channels across the United States and Germany where out-of-pocket purchases dominate mild vision impairment cases.
- Desktop Magnifiers:Large-format displays with integrated OCR and adjustable XY tables anchor institutional procurement in rehabilitation centers and educational facilities. Healthcare providers in Japan prioritize these units for macular degeneration patients requiring extended reading sessions.
- Wearable Magnifiers:Head-mounted displays with real-time object recognition extend functional independence beyond stationary tasks. Younger low-vision users in Germany adopt these for workplace document handling.
- Video Magnifiers:Camera-to-screen systems with HDMI output and programmable color inversion serve multi-user environments in libraries and senior centers.
The dominant share belongs to Handheld Magnifiers, while Wearable Magnifiers are closing the gap fastest.
Technology:
Cost tier differentiation separates legacy optical systems from AI-enabled digital architectures with text-to-speech integration.
- Optical:Traditional lens-based magnification without electronic processing occupies economy pricing tiers for budget-constrained users.
- Digital:CMOS sensor arrays with DSP-driven contrast enhancement and storage capabilities command premium positioning in Medicare-reimbursed channels.
- Hybrid:Combined optical-digital pathways balance cost and functionality for mid-tier educational procurement.
- LCD:Liquid crystal display panels with adjustable backlighting remain standard in institutional desktop units where durability outweighs OLED color fidelity.
Digital technology captures the largest installed base, though Hybrid systems are expanding most quickly in cost-sensitive markets.
End User:
Customer type determines feature bundling, training requirements, and whether procurement flows through retail, reimbursement, or institutional contracting channels.
- Individuals with Low Vision:Consumers with macular degeneration, glaucoma, or diabetic retinopathy drive handheld and wearable volume through direct purchase and Medicare Part B claims.
- Educational Institutions:Schools and universities procure desktop magnifiers with site licenses for OCR software to support students with visual impairments.
- Healthcare Providers:Rehabilitation hospitals and low-vision clinics specify durable desktop units with service contracts under bundled reimbursement frameworks.
- Retail:Optical shops and assistive technology distributors stock entry-level handheld devices for walk-in customers with mild vision loss.
Individuals with Low Vision constitute the primary demand pool, while Healthcare Providers are scaling procurement fastest under expanded Medicare coding.
Application:
Use-case specificity shapes magnification ratio requirements, battery versus AC power preferences, and the priority of OCR integration.
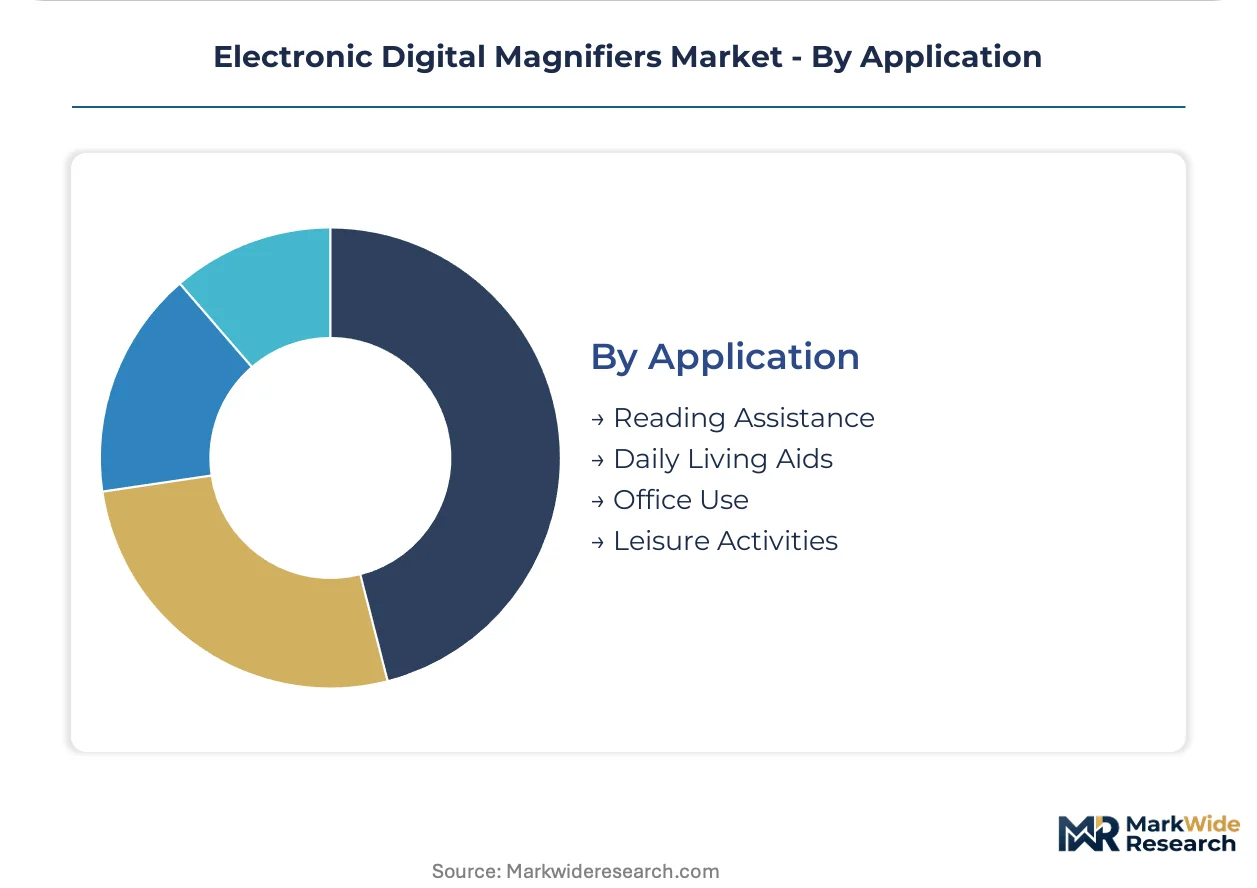
- Reading Assistance:Text enlargement for books, medication labels, and mail represents the core functional requirement across all device formats.
- Daily Living Aids:Cooking, grooming, and household task support drives demand for wearable magnifiers with hands-free operation in Japan and Germany.
- Office Use:Document processing and computer screen compatibility requirements favor desktop magnifiers with HDMI passthrough in workplace accommodation programs.
- Leisure Activities:Hobby and entertainment applications including craft work and television viewing support specialized video magnifier configurations.
Reading Assistance anchors category volume, though Daily Living Aids is gaining share fastest as wearable form factors mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers in aging economies dominate procurement, with reimbursement frameworks determining patient access and vendor selection patterns across major demand centers.
United States
Medicare Part B reimbursement for low-vision devices drives healthcare provider procurement of desktop magnifiers in rehabilitation centers. The FDA's 510(k) clearance pathway accelerates product launches for manufacturers targeting institutional channels. Boston and Minneapolis anchor specialized low-vision clinic networks where bundled service contracts consolidate vendor relationships.
Germany
Statutory health insurance coverage for visual impairment aids sustains demand for wearable magnifiers among working-age users. The EU Medical Device Regulation imposes extended conformity assessment through notified bodies, compressing launch timelines. Stuttgart and Munich concentrate rehabilitation engineering research clusters developing AI-integrated magnification systems.
Japan
PMDA standards for software-enabled therapeutic devices govern wearable magnifier approvals as macular degeneration prevalence rises among seniors over 75. The Ministry of Health, Labour and Welfare maintains distinct reimbursement coding for assistive technology in workplace accommodation programs. Osaka and Nagoya host precision optics manufacturing clusters supplying CMOS sensor assemblies.
United Kingdom
NHS England's low-vision service specifications determine eligibility criteria for electronic magnifier prescriptions through hospital eye services. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for post-market surveillance. London and Manchester concentrate assistive technology assessment centers conducting device trials for regional procurement committees.
India
Nascent reimbursement frameworks for visual impairment aids create first-mover opportunities through rehabilitation center distribution partnerships. The Central Drugs Standard Control Organization oversees medical device import licensing for magnification equipment. Bangalore and Hyderabad anchor emerging assistive technology startup clusters developing cost-optimized handheld units for price-sensitive consumers.
Electronic Digital Magnifiers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across institutional and retail pathways, producing a tiered structure where scale advantages in reimbursement navigation separate leaders from followers. Rehabilitation center networks and optical retail chains function as gatekeepers, filtering vendor access to end-users. Three archetypes dominate: full-service institutional contractors, wearable technology specialists, and optical heritage brands with retail distribution. Competitive moves center on bundling hardware with training services and securing exclusive rehabilitation center contracts.
Among North American assistive technology providers, Freedom Scientific and Vispero exemplify channel-controlling archetypes with established rehabilitation center networks, while HumanWare occupies a specialist position in wearable form factors. Eschenbach Optik represents European optical heritage brands leveraging retail optical shop relationships. These anchors illustrate how geographic origin and company structure correlate with distribution strategy selection.
| Leading Market Players |
|---|
| Freedom Scientific |
| Enhanced Vision |
| HumanWare |
| Optelec |
| Zoomax |
| LVI Low Vision International |
| Eschenbach Optik |
| Ash Technologies |
| Vispero |
| Others |
Pricing and Supply Chain Analysis
CMOS sensor fabrication concentrates in East Asian foundry clusters, channeling margin capture toward downstream vendors who bundle training and maintenance services with hardware procurement. OLED display panel volatility feeds directly into handheld unit economics, compressing returns at entry price points while institutional desktop contracts preserve premium positioning through multi-year service attachments.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate component sourcing, while finished-device pricing stratifies across premium, standard, and economy tiers based on OCR integration depth and FDA 510(k) clearance status. Brand premiums attach to Medicare-reimbursed channels where bundled service contracts reduce patient out-of-pocket complexity. Cost compression in handheld segments is intensifying because smartphone substitution erodes dedicated-device demand among mild impairment users. Retail optical channels exhibit highest price sensitivity, while rehabilitation centers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from East Asian foundry partners stabilize working capital for assembly-tier manufacturers sourcing CMOS sensors from Taiwan and South Korea, plus OLED panels from China. Raw material dependencies center on semiconductor-grade silicon, display driver ICs, and precision optical glass. Single-source vulnerability concentrates in advanced CMOS fabrication nodes. Distribution runs through rehabilitation center networks and optical retail chains that function as procurement gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from training and maintenance contracts is expanding faster than hardware sales, creating durable margin pools for vendors who integrate recurring-revenue layers into institutional procurement frameworks.
For Market Incumbents: Build exclusive rehabilitation center network moats by consolidating vendor-of-record status through bundled service contracts that embed multi-year maintenance and training commitments. Capacity addition in domestic assembly facilities reduces tariff exposure from East Asian component sourcing. Certification investment in EU MDR conformity assessment preserves European institutional channel access against regulatory fragmentation. For New Entrants and Emerging Players: Pursue India's nascent reimbursement framework through distribution partnerships with rehabilitation centers in Bangalore and Hyderabad, where statutory coverage expansion creates first-mover positioning before competitive saturation. Daily living aids applications for wearable magnifiers represent the most penetrable segment given younger user adoption curves in Germany. Direct-to-patient e-commerce channels bypass optical retail gatekeepers in markets with established digital infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed assistive technology platforms seeking add-on acquisitions to deepen rehabilitation center coverage and cross-sell wearable product lines. Five-to-ten year viability hinges on reimbursement coding expansion rather than hardware innovation cycles. Watch Medicare Part B coding decisions for low-vision devices as the primary inflection signal for institutional procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare Part B coding expansion directly unlocks patient access and institutional procurement volume. |
| Software Companion Development | AI-powered text-to-speech integration differentiates premium tiers from smartphone substitution threats. |
| Hospital System Partnership | Bundled service contracts with rehabilitation centers consolidate vendor relationships and recurring revenue. |
| CE Marking Pathway | EU MDR conformity assessment enables institutional channel access across German and UK procurement frameworks. |
| FDA Submission | 510(k) clearance accelerates product launches for desktop magnifiers targeting Medicare-reimbursed channels. |
Research Methodology
A spread of perspectives from rehabilitation center procurement directors, biomedical engineers at low-vision clinics, GPO contracts managers, and assistive technology distributors converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up unit demand estimates and top-down reimbursement-eligible population sizing were triangulated to anchor market sizing.
Demand-supply balance modeling across product type, technology architecture, end-user channel, and application use case structured the analytical framework over the projection horizon. CAGRs derived from weighted average of reimbursement expansion scenarios and technology substitution curves. Forecast inputs incorporated macular degeneration prevalence projections and statutory health insurance coverage expansion timelines.
Sensitivities concentrate around Medicare coding decisions, EU MDR implementation delays, and CMOS sensor supply disruptions. Forecasts reflect documented assumptions about reimbursement eligibility and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Instruments and Lenses Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Global Adaptive Optics Market
Optical Components
Global Tunable Filter Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Erbium Oxide Market
Optical Components
Optical Component Tester Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Europe Scintillator Market
Optical Components
Optical Isolator Market
Optical Components
Ring Panel Filters Market
Optical Components
Fiber-Optic Attenuator Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Fluorophore Market
Optical Components
Global Optical Connectivity Solutions Market