
 Intravenous Access Devices Market | 2026-2036
Intravenous Access Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Access Devices Market Analysis
Hospital group purchasing is narrowing the vendor shortlist for high-volume catheter contracts. Becton Dickinson and Company leverages its integrated manufacturing footprint to sustain supply security for safety IV catheters across integrated delivery networks. ICU Medical anchors its position through needlefree connector technology that dominates medication delivery lines in U.S. acute care. Terumo Corporation competes on polyurethane catheter formulations that reduce phlebitis incidence in extended dwell protocols.
Intravenous access devices comprise catheters, infusion sets, pumps, and accessories engineered from polyurethane, silicone, or polyvinyl chloride to establish vascular pathways for fluid, medication, or nutrient delivery directly into the bloodstream. These systems function under pressure ratings of 300-325 psi for power-injection CT compatibility and integrate Luer-lock or needlefree connections to prevent disconnections and microbial ingress. Catheters command the largest product share where peripherally inserted central catheters and midlines capture margin pools from extended antibiotic therapy and oncology infusion. Home care represents the fastest-growing end user segment as payer pressure shifts chemotherapy and antimicrobial administration from inpatient to ambulatory settings.
FDA 510(k) requirements and ISO 10555 vascular catheter standards govern material biocompatibility, mechanical performance, and sterility assurance for U.S. market access. The EU Medical Device Regulation imposes unique device identification and post-market surveillance obligations that reshape documentation burdens for catheter manufacturers serving European hospitals. Stakeholders must monitor how FDA guidance on closed system drug-transfer devices and EUDAMED database integration will reshape compliance costs and competitive barriers across their served geographies.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously demanding enhanced safety features and supply chain redundancy from catheter manufacturers serving integrated delivery networks.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance mandates are accelerating hospital replacement cycles for legacy IV catheters across European acute care facilities, creating fresh equipment demand.
- Home infusion therapy:Payer pressure in the United States is shifting chemotherapy and extended antibiotic administration to ambulatory settings, expanding the addressable market for peripherally inserted central catheters and portable infusion pumps.
- Polyurethane formulation advances:Extended-dwell protocols in oncology and infectious disease units are driving catheter material upgrades that reduce phlebitis rates and lower total complication costs.
Market Restraints
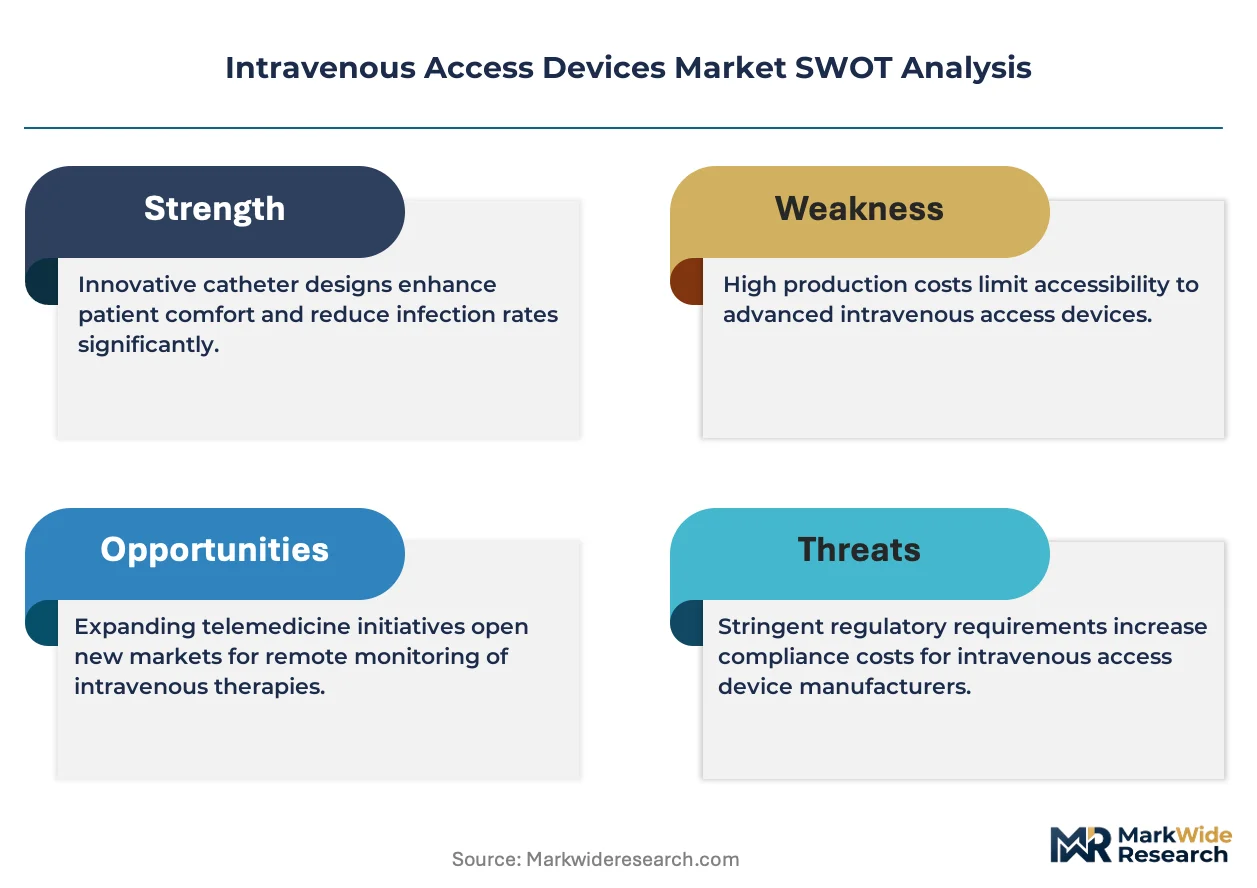
- Polymer feedstock volatility:Medical-grade polyurethane and silicone resin prices fluctuate with petrochemical markets, squeezing gross margins for catheter manufacturers without backward integration into polymer production.
- Manufacturing concentration in Germany:B. Braun SE and Becton Dickinson anchor European supply from German production facilities, creating geographic risk exposure for hospital procurement teams seeking supply security.
- Technical limitation of power-injection compatibility:Not all midline catheters withstand 300-325 psi pressure ratings required for contrast-enhanced CT protocols, restricting their deployment in diagnostic imaging workflows.
Strategic Opportunities
- Needlefree connector standardization:ICU Medical's dominant position in Luer-lock alternatives creates white space for competitors offering interoperable closed-system designs that reduce bloodstream infection risk.
- Closed-system transfer device mandates:FDA guidance on hazardous drug handling is tightening material standards for oncology infusion sets, opening premium positioning for manufacturers with validated barrier technologies.
- Ambulatory surgery center expansion:United States outpatient facility construction is outpacing hospital bed growth, redirecting catheter volume toward shorter-dwell peripheral devices with rapid-turn inventory requirements.
Industry Challenges
- Biocompatibility certification timelines:ISO 10555 vascular catheter testing protocols require 18-24 month validation cycles, delaying product launches and compressing effective patent life for novel materials.
- EUDAMED database integration:European manufacturers face documentation burdens for unique device identification that strain quality assurance staffing and extend time-to-market for catheter line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Access Devices Market |
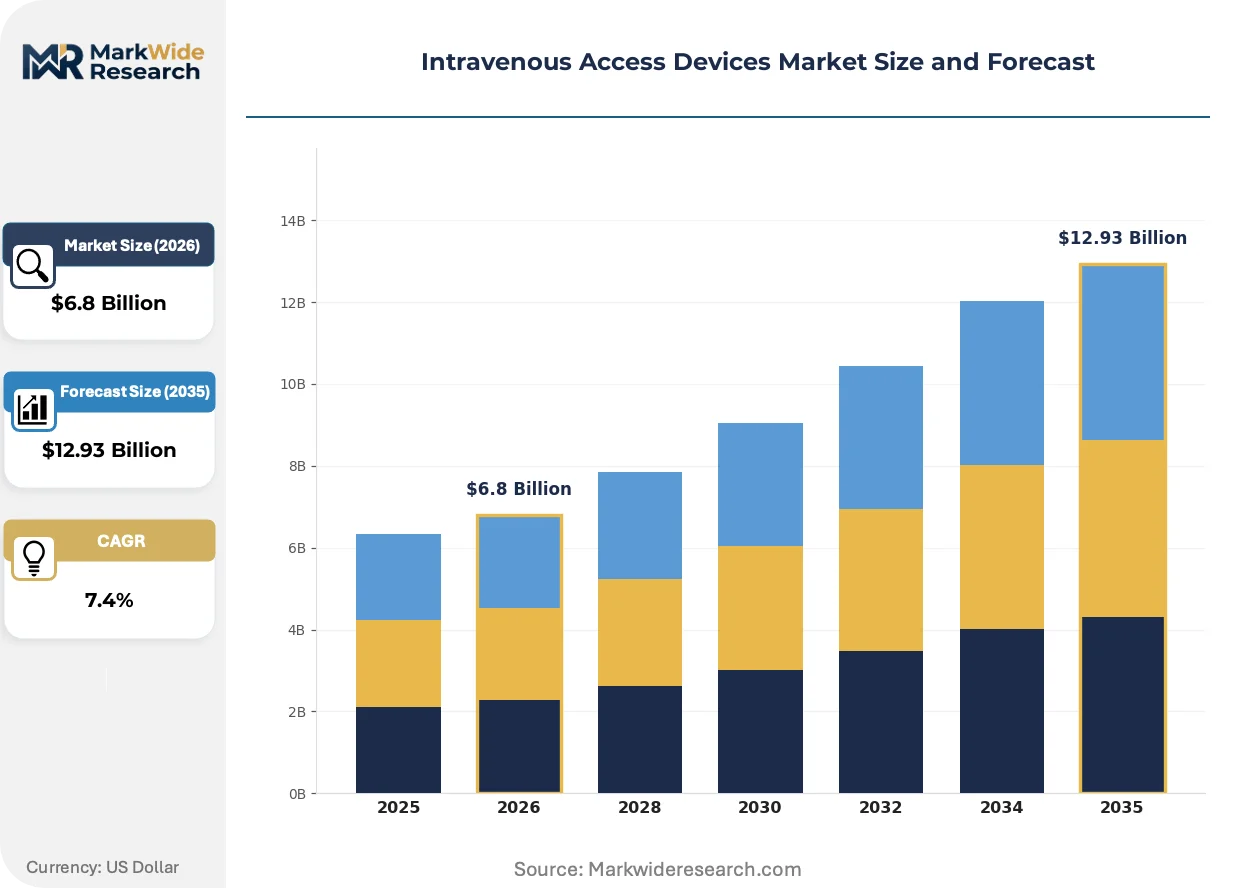
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, IV Sets, Infusion Pump, Accessories End User: Hospitals, Home Care, Ambulatory Surgical Centers, Specialty Clinics Delivery Mode: Bolus Administration, Continuous Infusion, Intermittent Infusion, PCA Material: Polyvinyl Chloride, Silicone, Polyurethane, Others |
| Companies Covered | Becton Dickinson and Company, Teleflex Incorporated, ICU Medical, B. Braun SE, Medtronic, AngioDynamics, Terumo Corporation, Cook Medical, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Access Devices Market Emerging Trajectories
Material science breakthroughs and regulatory tightening on closed-system drug handling are converging to redefine catheter safety standards and procurement criteria across acute and ambulatory care settings.
Antimicrobial-impregnated catheter technology is migrating from premium oncology units to standard medical-surgical floors as hospitals face CMS penalties for central line-associated bloodstream infections. Academic medical centers in the United States are leading adoption, with community hospitals following 18-24 month implementation lags. This diffusion pattern is compressing the price premium for silver-ion and chlorhexidine-coated devices while raising baseline expectations for all catheter purchases.
REACH chemical restrictions and the EU Medical Device Regulation are jointly restricting phthalate plasticizer use in polyvinyl chloride infusion tubing, forcing reformulation investments across European supply chains. Manufacturers serving German and French hospitals must now validate alternative plasticizers or shift toward polyurethane and silicone alternatives entirely. The compliance burden falls heaviest on mid-tier suppliers lacking dedicated regulatory affairs teams, accelerating consolidation among catheter vendors.
Hospital group purchasing organizations are unbundling safety-engineered catheters from legacy sole-source contracts, enabling competitive bidding for high-volume peripherally inserted central catheter and midline categories. Integrated delivery networks in Texas and California are piloting dual-source strategies that split volume between Becton Dickinson and secondary suppliers to mitigate supply disruption risk. This procurement evolution is compressing switching costs and rewarding manufacturers with redundant manufacturing footprints and regional distribution density.
Intravenous Access Devices Market Segmentation
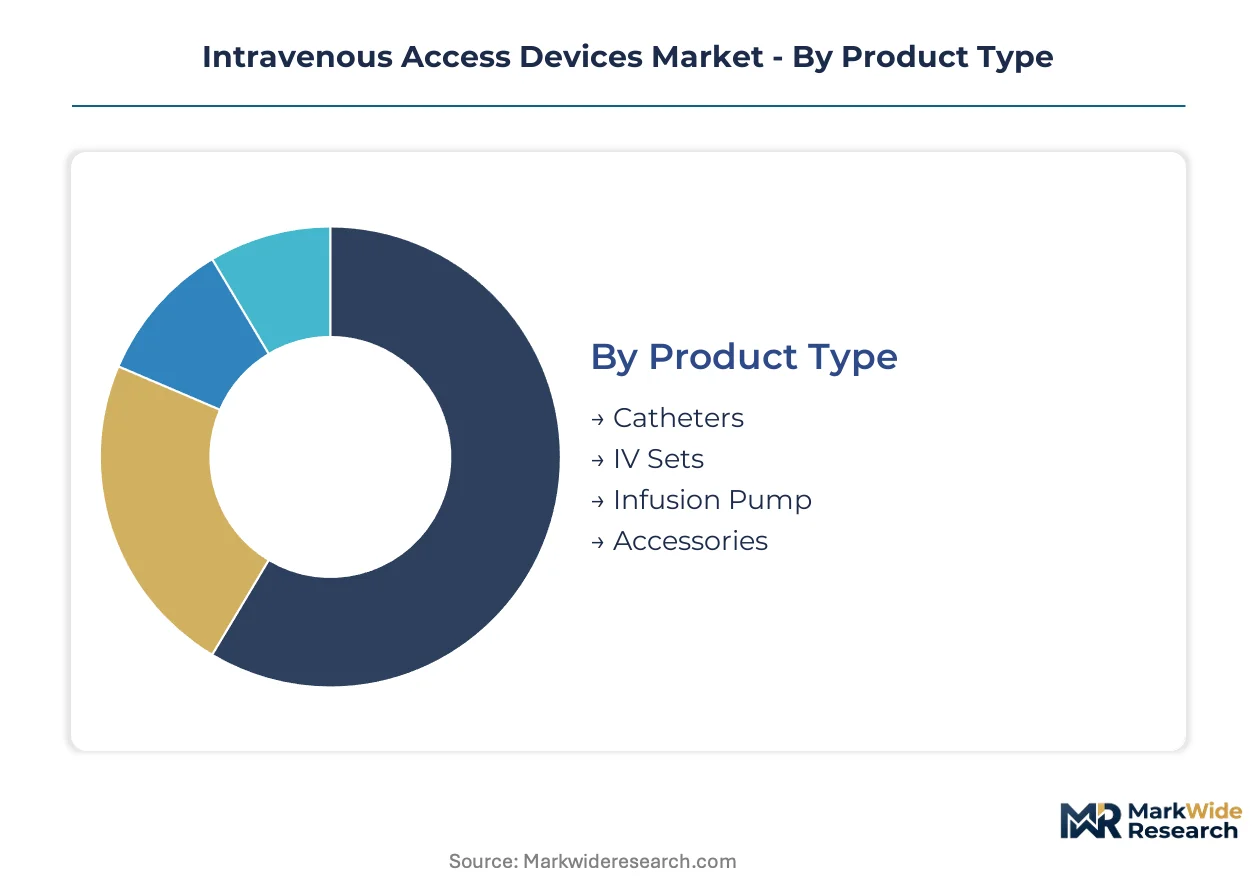
Segmentation in intravenous access devices reveals how clinical requirements, care settings, and material specifications create distinct competitive arenas. Manufacturers must align product portfolios across these dimensions to capture volume in acute care while building positions in expanding ambulatory channels.
Product Type:
Use-case spectrum spans emergency vascular access through precision oncology delivery, with each product category demanding differentiated engineering and regulatory validation.
- Catheters:Engineered from polyurethane, silicone, or polyvinyl chloride with pressure ratings of 300-325 psi for power-injection CT compatibility. Demand concentrates in hospital ICUs and oncology units where peripherally inserted central catheters and midlines support extended antibiotic therapy and chemotherapy infusion protocols.
- IV Sets:Tubing assemblies integrating Luer-lock or needlefree connectors to prevent disconnections and microbial ingress. Home care expansion in the United States is accelerating volume for ambulatory infusion sets as payer pressure shifts administration from inpatient to residential settings.
- Infusion Pump:Programmable devices delivering controlled medication volumes with alarm systems for occlusion or air-in-line detection. Ambulatory surgical centers drive demand for compact, portable pumps supporting rapid-turn procedures.
- Accessories:Needlefree connectors, extension sets, and securement devices completing infusion systems. German acute care facilities anchor European procurement volume through B. Braun SE and Becton Dickinson distribution networks.
The dominant share belongs to catheters, while home care expansion is pushing IV sets to gain share fastest.
End User:
Customer-type concentration shows acute care maintaining volume leadership while reimbursement shifts redirect growth toward lower-cost settings.
- Hospitals:Integrated delivery networks in Texas and California are consolidating procurement through group purchasing organizations, narrowing vendor shortlists for high-volume safety-engineered catheter contracts. FDA 510(k) requirements and CMS penalties for central line-associated bloodstream infections are raising baseline safety specifications.
- Home Care:Payer pressure in the United States is redirecting chemotherapy and extended antimicrobial administration from inpatient to residential settings. Portable infusion pumps and peripherally inserted central catheters with simplified maintenance protocols are capturing this ambulatory expansion.
- Ambulatory Surgical Centers:United States outpatient facility construction is outpacing hospital bed growth, creating demand for shorter-dwell peripheral devices with rapid inventory turnover.
- Specialty Clinics:Oncology and infectious disease infusion centers require extended-dwell catheters with antimicrobial coatings and power-injection compatibility for diagnostic imaging workflows.
Hospitals retain the dominant procurement volume, though home care is climbing the fastest as reimbursement models evolve.
Delivery Mode:
Application-driven segmentation aligns device selection with pharmacokinetic requirements and patient mobility needs across care continuums.
- Bolus Administration:Rapid single-dose delivery for emergency medications or contrast agents. Emergency departments and radiology suites specify pressure-rated catheters for power-injection CT protocols.
- Continuous Infusion:Steady medication delivery over extended periods for chemotherapy, parenteral nutrition, or critical care sedation. Oncology units and ICUs drive specification for programmable pumps with occlusion detection.
- Intermittent Infusion:Scheduled dosing with flush protocols between administrations, common in antibiotic therapy. Home care nurses favor needlefree connector systems reducing bloodstream infection risk.
- PCA:Patient-controlled analgesia enabling self-administered pain medication within programmed limits. Post-surgical recovery units in ambulatory surgical centers deploy disposable PCA pumps for short-stay procedures.
Continuous infusion commands the dominant application share, while PCA is expanding most quickly in ambulatory surgical settings.
Material:
Cost-tier and performance segmentation reflects trade-offs between biocompatibility, dwell duration, and regulatory compliance burden.
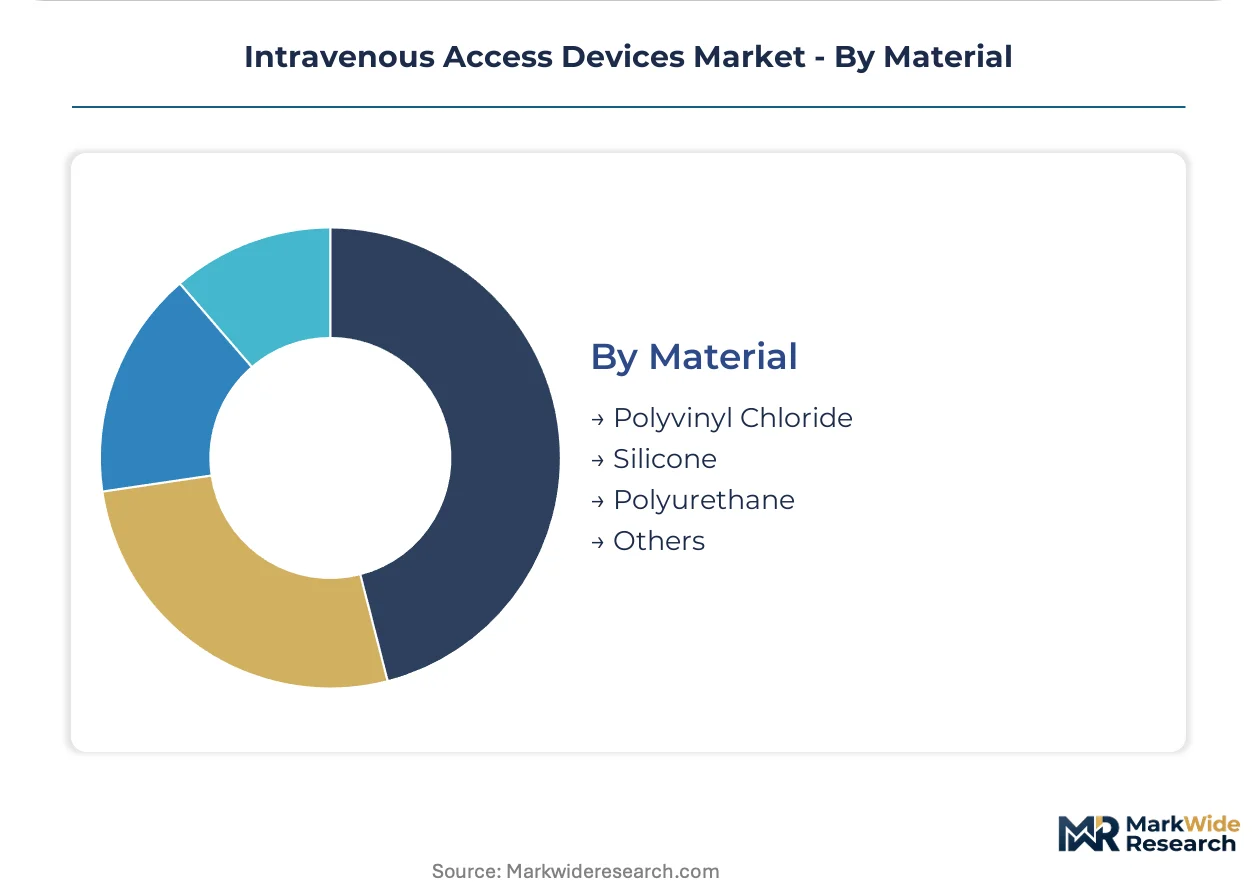
- Polyurethane:Advanced formulation delivering extended dwell capability with reduced phlebitis incidence. Terumo Corporation competes on proprietary polyurethane blends capturing margin pools in oncology and infectious disease extended protocols.
- Silicone:Superior biocompatibility for long-term vascular access in parenteral nutrition or chemotherapy. REACH chemical restrictions and EU Medical Device Regulation are validating silicone alternatives as phthalate-plasticized PVC faces reformulation pressure.
- Polyvinyl Chloride:Cost-effective standard for short-dwell peripheral catheters and gravity infusion sets. ECHA restrictions on phthalate plasticizers are forcing manufacturers serving German and French hospitals toward alternative plasticizers or material substitution.
- Others:Emerging materials including thermoplastic elastomers and antimicrobial-impregnated compounds. Academic medical centers in the United States are piloting adoption ahead of community hospital implementation lags.
Polyurethane holds the dominant position for premium applications, though silicone is gaining share fastest under European regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European distribution for medical-grade polymer feedstocks, while the Trans-Siberian rail corridor links German manufacturing clusters to Asian silicone suppliers.
United States
FDA 510(k) clearance pathways for closed-system transfer devices are tightening material standards as hospital procurement consolidates through Texas and California integrated delivery networks. CMS penalties for central line-associated bloodstream infections are accelerating antimicrobial-impregnated catheter adoption in academic medical centers ahead of community hospital implementation lags.
Germany
B. Braun SE and Becton Dickinson anchor manufacturing and distribution networks serving European acute care from production facilities concentrated in Melsungen and Heidelberg. EU Medical Device Regulation post-market surveillance mandates are accelerating hospital replacement cycles for legacy IV catheters, creating fresh equipment demand across German hospital procurement.
China
NMPA vascular catheter standards are converging with ISO 10555 biocompatibility protocols as domestic manufacturers expand polyurethane formulation capacity in Jiangsu and Zhejiang provinces. The Yangtze River Delta cluster is capturing contract manufacturing volume from multinational OEMs seeking cost-competitive silicone catheter production.
Japan
PMDA regulatory harmonization with FDA 510(k) pathways is streamlining market access for Terumo Corporation's proprietary polyurethane blends developed in Shibuya manufacturing facilities. METI industrial policy is incentivizing domestic production of power-injection compatible catheters for diagnostic imaging workflows.
India
CDSCO medical device rules are formalizing quality standards for peripheral catheter imports as domestic manufacturers in Gujarat and Maharashtra scale polyvinyl chloride infusion set production. Government hospital procurement under the Ayushman Bharat scheme is concentrating volume for safety-engineered catheters in tertiary care facilities.
Intravenous Access Devices Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in catheter materials and connector engineering. The vendor base organizes around three strategic archetypes: integrated multinationals with redundant manufacturing footprints, regional specialists with formulation expertise, and contract manufacturers serving private-label hospital brands. Consolidation is accelerating through dual-source procurement mandates and backward integration into polymer production.
Among integrated multinationals, Becton Dickinson and Company and B. Braun SE exemplify the platform-tier archetype with manufacturing and distribution density across integrated delivery networks. ICU Medical occupies a position within the component-specialist tier, anchoring needlefree connector technology for medication delivery lines. Terumo Corporation represents the formulation-driven specialist archetype, competing on proprietary material science for extended-dwell protocols.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Teleflex Incorporated |
| ICU Medical |
| B. Braun SE |
| Medtronic |
| AngioDynamics |
| Terumo Corporation |
| Cook Medical |
| Merit Medical Systems |
| Others |
Supply Flow & Price Mechanics
The Trans-Siberian rail corridor's freight economics link German polymer feedstock costs to catheter price differentiation across European acute care networks, concentrating margin pressure on manufacturers without captive resin supply or regional distribution density.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs catheter procurement, with antimicrobial-coated and power-injection compatible devices commanding spreads based on ISO 10555 certification tier and after-sales service bundling. Cost compression in standard polyurethane catheters is intensifying because hospital group purchasing organizations are consolidating volume through dual-source contracts. Ambulatory surgical centers exhibit the highest price sensitivity due to rapid-turn inventory requirements, while oncology units in academic medical centers show the least sensitivity given CMS penalty exposure for bloodstream infections.
Supply Chain Analysis
Contract manufacturing for silicone catheter components concentrates in Jiangsu and Zhejiang province facilities serving multinational OEMs, while finished device assembly anchors in German and U.S. plants. Medical-grade polyurethane and silicone resin feedstocks draw from petrochemical complexes in Germany, China, and Japan, with formulation expertise resting on proprietary catalyst systems. Single-source vulnerability in German production clusters creates geographic risk exposure for European hospital procurement. Distribution runs through integrated delivery network warehouse networks in Texas and California, supplemented by B. Braun SE and Becton Dickinson regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from closed-system drug-transfer devices and ambulatory infusion technologies that could displace traditional catheter lines in oncology workflows.
For Market Incumbents: Build regulatory certification moats by accelerating FDA 510(k) submissions for power-injection compatible midlines and needlefree connector systems. Secure backward integration into medical-grade polyurethane production to insulate margins from petrochemical volatility. Anchor hospital system partnerships through GPO contracts that bundle safety-engineered catheters with infusion pump service agreements. For New Entrants and Emerging Players: Home care infusion services in the United States represent the most penetrable entry point, with portable pump and simplified maintenance protocol demand outpacing incumbent supply capacity. Target antimicrobial-impregnated catheter white space in community hospitals trailing academic medical center adoption by 18-24 months. Pursue private-label manufacturing contracts with regional hospital systems seeking dual-source security outside Becton Dickinson and B. Braun SE networks. For Investors and Strategic Acquirers: Formulation-driven specialists with proprietary polyurethane blends and validated silicone alternatives under REACH compliance offer the strongest acquisition profile for portfolio diversification. Long-term viability hinges on catheter manufacturers' ability to capture ambulatory volume as reimbursement shifts accelerate. Watch FDA guidance on closed-system transfer devices as the inflection signal for premium pricing sustainability in oncology infusion sets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Power-Injection Catheters | Unlocks diagnostic imaging workflow penetration and commands premium positioning in hospital ICUs. |
| Backward Integration into Polyurethane Resin Production | Captures margin pools and insulates against petrochemical feedstock volatility squeezing competitors. |
| Hospital System Partnership through GPO Contracts | Locks in volume security across integrated delivery networks consolidating procurement in Texas and California. |
| REACH-Compliant Silicone Formulation Development | Opens European market access as phthalate-plasticized PVC faces ECHA restriction pressure. |
| Software Companion for Infusion Pump Connectivity | Enables remote monitoring capabilities that differentiate offerings in expanding home care channels. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, hospital procurement databases, CMS Medicare reimbursement data, and GPO contract disclosures. Interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at catheter manufacturers informed demand-side and supply-side dynamics. Bottom-up modeling of catheter unit volumes across acute care, home care, and ambulatory surgical center channels triangulates against top-down market sizing from trade flow analysis.
Forecast inputs include segmented modeling across product type, end user, delivery mode, and material composition dimensions. Growth trajectories derive from elasticity analysis of reimbursement shifts, regulatory compliance cost burdens, and polymer feedstock price sensitivity. Power-injection compatibility adoption curves, antimicrobial coating diffusion patterns from academic to community hospitals, and EUDAMED database integration timelines inform the projection framework across the analysis window.
Stress conditions across polymer resin price volatility, FDA clearance timeline delays, and hospital procurement consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on reimbursement policy continuity and regulatory harmonization progress. Quarterly review of GPO contract award announcements, FDA 510(k) clearance volumes, and REACH restriction implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
APAC Ablation Devices Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Autosamplers Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Eye Massage Device Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Implantable Collamer Lens Market
Medical Devices
Global External Fixators Market
Medical Devices
Otoscope Devices Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Single-Use Centrifuge System Market