
 Artificial Cornea and Corneal Implant Market | 2026-2036
Artificial Cornea and Corneal Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Cornea and Corneal Implant Market Intelligence
Hospital procurement of artificial corneas is rebalancing toward ambulatory surgery centers as outpatient ophthalmic procedures expand. CorNeat Vision leverages its synthetic cornea platform to compete in markets with donor tissue shortages. LinkoCare Life Sciences AB anchors European supply through its specialized manufacturing of keratoprosthesis devices. EyeYon Medical differentiates via drug-device combinations that address post-implant healing complications.
Artificial corneas and corneal implants are medical devices engineered from biocompatible polymers, collagen matrices, or hydrogel composites to replace or support damaged human corneal tissue and restore optical clarity. Keratoprosthesis devices fabricated from PMMA sustain permanent vision restoration in patients with severe corneal opacity who fail donor grafts. The product type category shows keratoprosthesis leading current volume while bioengineered implants represent the fastest-growing segment due to reduced rejection rates. Collagen-based materials command premium positioning in material selection as surgeons prioritize biointegration over synthetic alternatives.
FDA premarket approval requirements and the EU Medical Device Regulation shape device commercialization pathways on both sides of the Atlantic. ISO 14155 clinical investigation standards govern trial design for corneal implant studies, while REACH compliance affects hydrogel material sourcing for European manufacturers. Stakeholders must monitor reimbursement coding evolution for keratoprosthesis procedures as payer decisions will determine ambulatory adoption velocity.
Market Dynamics
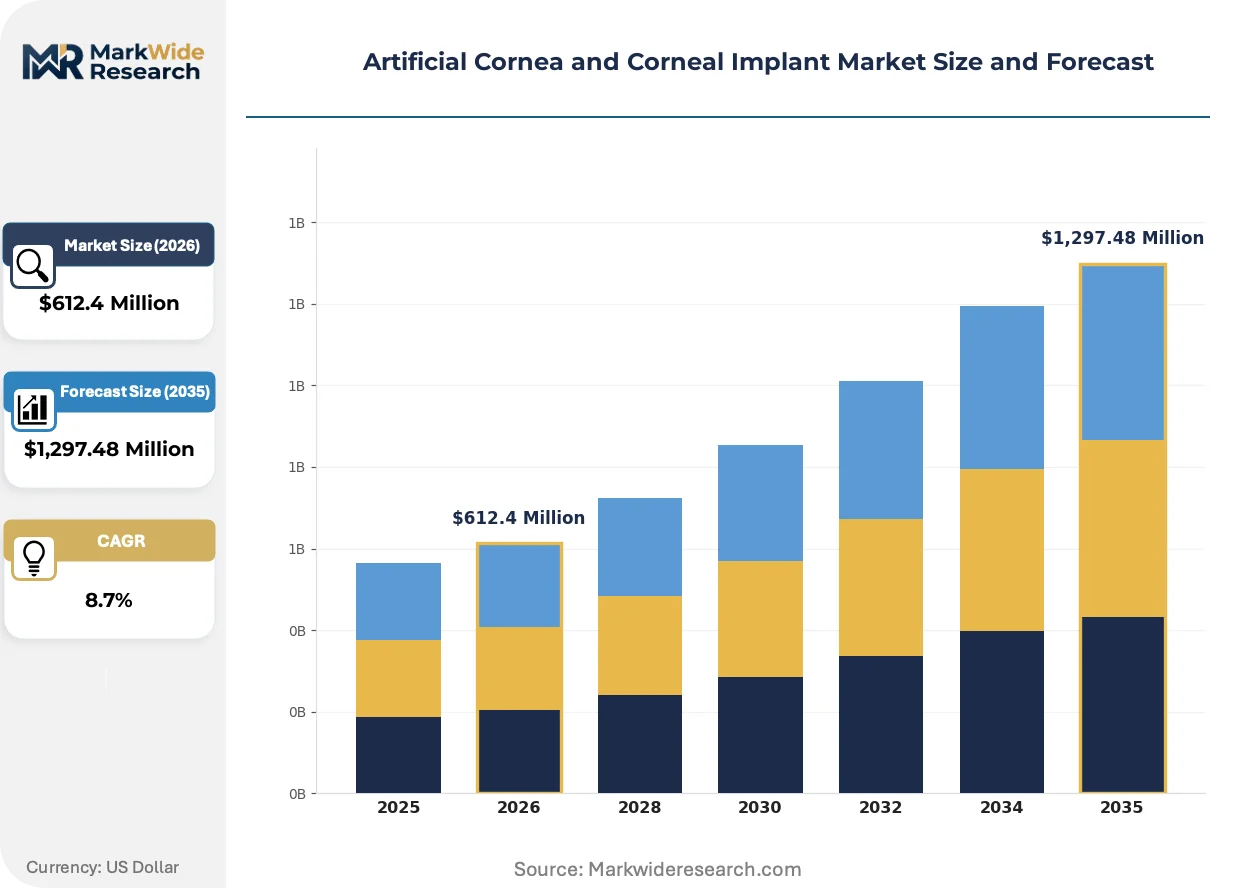
The artificial cornea market is rebalancing around biointegration capabilities as surgeons prioritize rejection-resistant materials over legacy synthetic platforms. Collagen-based matrices are displacing PMMA dominance in elective procedures while regulatory pathways harden for permanent keratoprosthesis devices.
Growth Catalysts
- Donor tissue scarcity:Chronic shortages of human corneal grafts in India and Brazil are accelerating synthetic substitute adoption in tertiary ophthalmic centers.
- EU Medical Device Regulation:MDR harmonization is streamlining cross-border clinical trial protocols for bioengineered implants across Germany, France, and Italy.
- Femtosecond laser integration:Precision cutting platforms are reducing surgical trauma during keratoprosthesis implantation, expanding eligible patient pools.
Market Restraints
- PMMA supply concentration:Optical-grade polymer production clusters in Germany and Japan, creating vulnerability to regional logistics disruptions.
- FDA premarket approval timelines:The PMA pathway for keratoprosthesis devices extends commercialization cycles to 36-48 months for novel materials.
- Allograft persistence:Penetrating keratoplasty remains the clinical default for non-severe opacity, limiting addressable market expansion.
Strategic Opportunities
- Ambulatory surgery centers:Outpatient ophthalmic infrastructure in the United States is creating dedicated reimbursement codes for same-day keratoprosthesis procedures.
- Drug-device convergence:Anti-fibrotic-eluting implants are opening post-operative complication management as a serviceable revenue layer.
- Japan's aging demographic:PMDA fast-track pathways for geriatric vision restoration technologies are compressing regulatory review periods.
Industry Challenges
- Ocular surface specialist shortage:Keratoprosthesis implantation requires fellowship-trained corneal surgeons, constraining procedure volume scaling.
- ISO 14155 compliance burden:Clinical investigation standards for corneal implants mandate multi-site trial designs that fragment patient recruitment.
- Post-implant monitoring infrastructure:Lifetime follow-up protocols strain ophthalmology clinic capacity in publicly funded health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Cornea and Corneal Implant Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Cornea, Corneal Ring, Bioengineered Implant, Keratoprosthesis End User: Hospitals, Ambulatory Surgery Centers, Eye Clinics, Academic Institutes Material: Silicone, Hydrogels, PMMA, Collagen Application: Vision Restoration, Treatment of Corneal Diseases, Research, Surgical Procedures |
| Companies Covered | LinkoCare Life Sciences AB, CorNeat Vision, AJL Ophthalmic S.A., Mediphacos, Addition Technology Inc., CorneaGen Inc., EyeYon Medical, Pantheon Vision, Aurolab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Cornea and Corneal Implant Market Strategic Shifts & Innovations
Biomaterial convergence is collapsing the traditional synthetic-versus-biological divide as manufacturers engineer composite matrices with tunable degradation profiles. Regulatory science and surgical technique are co-evolving around patient-specific implant geometries.
Collagen-PEG hydrogel composites are unifying optical clarity with cellular infiltration pathways. Academic medical centers in the United States and Switzerland are piloting these platforms for high-risk graft failures. The technology is unifying previously separate device and tissue-engineering supply chains into single-source manufacturing relationships.
REACH compliance requirements for hydrogel precursor chemicals are forcing European manufacturers to requalify Asian material suppliers. ECHA substance-of-very-high-concern listings are eliminating certain crosslinking agents from corneal implant formulations. German and Dutch producers are responding by vertically integrating polymer synthesis into captive facilities.
Hospital purchasing committees are consolidating keratoprosthesis procurement under value-analysis frameworks that bundle device, surgical training, and post-operative monitoring. United States ambulatory networks are displacing traditional distributor relationships with direct manufacturer contracts. This concentration is most visible in California and Texas multi-site ophthalmology platforms.
Artificial Cornea and Corneal Implant Market Segmentation
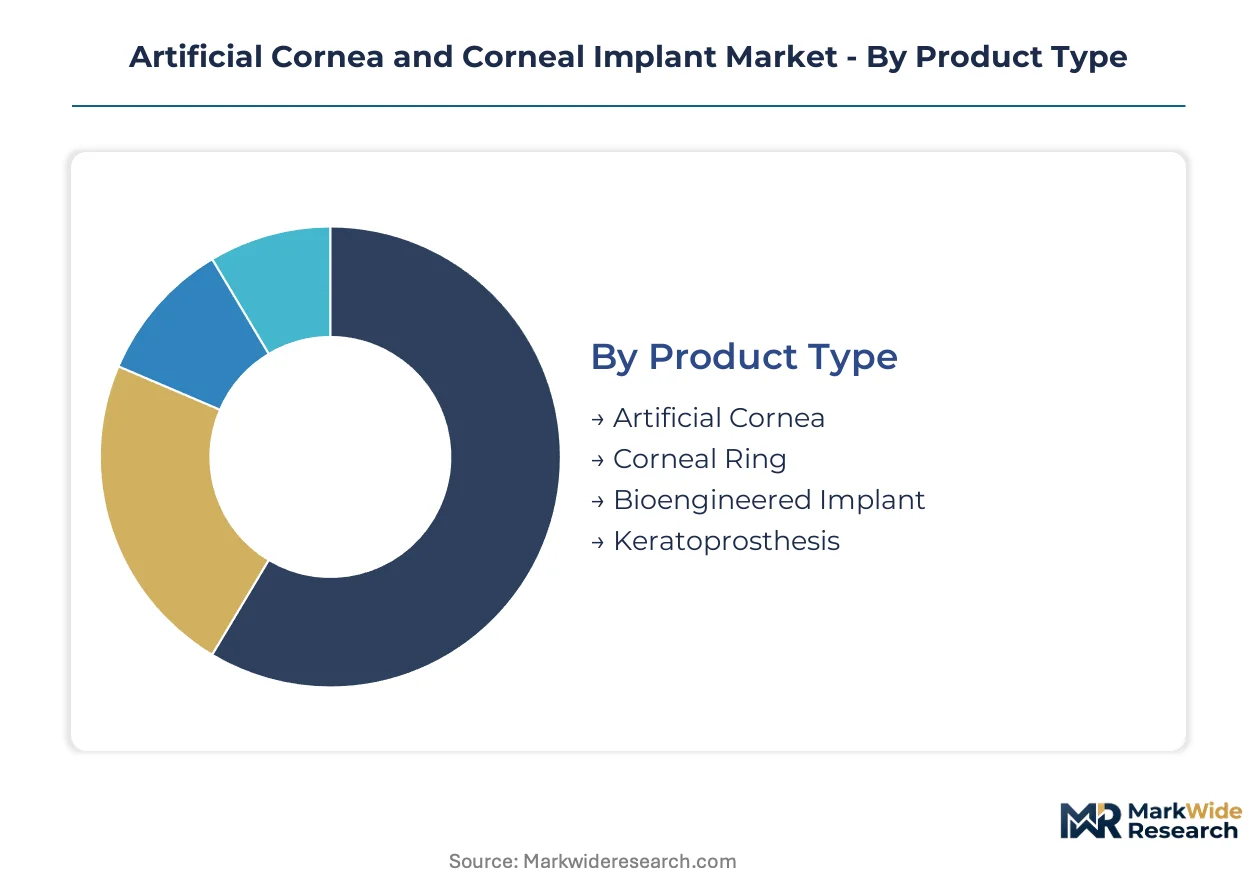
Device taxonomy in the artificial cornea market determines reimbursement pathways, surgical training requirements, and manufacturing scale economics. Each segmentation axis carries distinct regulatory implications and shapes competitive positioning across procurement channels.
Product Type:
Optical performance specifications and biointegration timelines define competitive differentiation across implant architectures.
- Keratoprosthesis:PMMA-based permanent devices deliver optical clarity in severe graft failure cases where donor tissue rejection is recurrent. Demand concentrates in tertiary ophthalmic centers across the United States and Germany due to FDA PMA pathway requirements and specialized surgical infrastructure needs.
- Bioengineered Implant:Collagen-PEG matrices enable cellular infiltration and gradual tissue remodeling, reducing long-term rejection risk. Adoption is accelerating fastest in Switzerland and academic medical centers piloting next-generation biointegration platforms.
- Artificial Cornea:Synthetic full-thickness replacements address total corneal opacity without donor dependency.
- Corneal Ring:Intrastromal inserts reshape corneal curvature for keratoconus management prior to advanced intervention.
Keratoprosthesis leads on scale; Bioengineered Implant leads on momentum.
End User:
Facility reimbursement status and surgical volume thresholds determine device procurement authority across care settings.
- Hospitals:Inpatient ophthalmology departments anchor complex keratoprosthesis volumes through bundled payment structures covering multi-day admission protocols. California and Texas health systems command disproportionate procurement leverage via consolidated value-analysis committees.
- Ambulatory Surgery Centers:Outpatient ophthalmic platforms in Florida and Arizona are securing dedicated CPT codes for same-day artificial cornea procedures, compressing total episode costs.
- Eye Clinics:Private corneal specialty practices handle pre-operative screening and post-implant monitoring.
- Academic Institutes:University-affiliated centers drive clinical trial enrollment and surgeon training pipelines.
Hospitals retain volume dominance; Ambulatory Surgery Centers are gaining share fastest through reimbursement innovation.
Material:
Biocompatibility certification and supply chain provenance shape material selection in implant manufacturing.
- Collagen:Purified extracellular matrices command premium positioning as surgeons prioritize host tissue integration over permanent synthetic residence. REACH compliance requirements for hydrogel precursors are forcing European manufacturers toward captive polymer synthesis.
- PMMA:Optical-grade polymethyl methacrylate sustains permanent keratoprosthesis fabrication with decades of clinical safety data. Production clusters in Germany and Japan create logistics vulnerability for device manufacturers.
- Hydrogels:Water-retentive networks enable tunable degradation profiles in resorbable implant designs.
- Silicone:Elastomeric formulations serve specialized ring and band applications requiring flexibility.
PMMA anchors current manufacturing scale; Collagen is climbing the fastest as biointegration priorities reshape material hierarchies.
Application:
Clinical indication severity and reimbursement coding specificity determine addressable procedure volumes.
- Vision Restoration:Functional sight recovery in bilateral corneal blindness represents the highest-value indication, with Medicare and commercial payers assigning distinct DRG codes based on implant type and surgical complexity.
- Treatment of Corneal Diseases:Therapeutic intervention for infectious keratitis, chemical injury, and autoimmune-mediated opacity spans acute and chronic care pathways with variable prior authorization requirements.
- Surgical Procedures:Technique refinement and device placement protocols support operative standardization.
- Research:Preclinical and clinical investigation drives next-generation platform development.
Vision Restoration commands revenue concentration; Treatment of Corneal Diseases is expanding most quickly as indication boundaries broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting keratoprosthesis manufacturing toward jurisdictions with streamlined clinical trial frameworks and lower cost-of-compliance structures. Germany and Switzerland retain premium positioning through captive polymer synthesis capabilities. Japan and the United States compete on reimbursement innovation rather than production cost.
United States
Medicare's DRG coding for keratoprosthesis procedures anchors hospital procurement volumes in California and Texas multi-site ophthalmology platforms. The FDA's PMA pathway for novel materials extends commercialization timelines to 36-48 months, favoring incumbent PMMA-based platforms. Florida and Arizona ambulatory surgery centers are securing dedicated CPT codes for same-day artificial cornea procedures.
Germany
Optical-grade PMMA production clusters in German chemical manufacturing zones create supply chain leverage for European device fabricators. REACH compliance requirements for hydrogel precursors are forcing manufacturers toward captive polymer synthesis in Baden-Württemberg and North Rhine-Westphalia. ECHA substance-of-very-high-concern listings are eliminating certain crosslinking agents from corneal implant formulations.
Switzerland
Academic medical centers in Zurich and Basel are piloting collagen-PEG hydrogel composites for high-risk graft failures. Swissmedic's alignment with EU MDR harmonization streamlines cross-border clinical trial protocols for bioengineered implants. The country's precision manufacturing heritage supports patient-specific implant geometries through advanced polymer processing.
Japan
PMDA fast-track pathways for geriatric vision restoration technologies are compressing regulatory review periods for keratoprosthesis innovators. Japan's aging demographic sustains demand for permanent vision restoration in bilateral corneal blindness cases. METI industrial policy supports domestic optical-grade polymer production to reduce import dependency.
India
Chronic donor tissue shortages in tertiary ophthalmic centers across Maharashtra and Karnataka are accelerating synthetic substitute adoption. CDSCO's evolving medical device regulations are creating compliance complexity for multinational manufacturers seeking market entry. Aurolab's presence in Tamil Nadu anchors regional supply for affordable keratoprosthesis devices.
Artificial Cornea and Corneal Implant Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium-tier collagen-based platforms commanding distinct procurement channels from scale-driven PMMA fabricators. The vendor base concentrates around three strategic archetypes: academic spinouts commercializing next-generation biointegration platforms, established ophthalmic device houses extending corneal portfolios, and regional manufacturers serving price-sensitive markets with standardized keratoprosthesis designs. Dominant competitive moves include backward integration into optical-grade polymer synthesis and strategic partnerships with ambulatory surgery center networks.
Among European-based fabricators, LinkoCare Life Sciences AB exemplifies the specialized keratoprosthesis manufacturer archetype through its Swedish corporate structure and focused device portfolio. CorNeat Vision and EyeYon Medical represent the innovation-driven tier, with company names signaling distinct technology positioning—CorNeat Vision's synthetic cornea platform and EyeYon Medical's drug-device convergence approach. These three entities occupy positions spanning the material spectrum from permanent PMMA-based solutions to bioresorbable matrices, illustrating the competitive segmentation between synthetic durability and biological integration priorities.
| Leading Market Players |
|---|
| LinkoCare Life Sciences AB |
| CorNeat Vision |
| AJL Ophthalmic S.A. |
| Mediphacos |
| Addition Technology Inc. |
| CorneaGen Inc. |
| EyeYon Medical |
| Pantheon Vision |
| Aurolab |
| Others |
Cost & Logistics Intelligence
Collagen-PEG hydrogel manufacturing is compressing production economics while fragmenting supplier power across European and North American polymer synthesis facilities. This platform shift simultaneously elevates material costs for biointegration-grade matrices and reduces dependence on legacy PMMA supply clusters in Germany and Japan.
Pricing Analysis
Distributor margins for keratoprosthesis devices are compressing as United States ambulatory surgery centers negotiate direct manufacturer contracts. Three-tier pricing structure across premium collagen-based implants, standard PMMA devices, and economy synthetic corneas reflects certification grade and surgical training bundling. Cost compression in the standard tier is intensifying because REACH compliance is forcing European manufacturers toward captive polymer synthesis. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, while publicly funded hospitals in India and Brazil face acute budget constraints.
Supply Chain Analysis
Returns and refurbishment flows for explanted keratoprosthesis devices remain minimal given permanent implant design, though explant analysis programs in Swiss and German academic centers are creating limited reverse logistics channels. Optical-grade PMMA production draws from Germany, Japan, and emerging domestic capacity in India under METI-supported technology transfer. Hydrogel precursor chemicals, collagen purification substrates, and femtosecond laser cutting platforms constitute critical input dependencies. Single-source vulnerability concentrates in German optical polymer manufacturing zones. Distribution runs through specialized ophthalmic device distributors in Europe and direct-to-hospital contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA PMA pathway milestones and EU MDR harmonization deadlines are accelerating procurement decisions ahead of compliance deadlines.
For Market Incumbents: Hedge PMMA revenue exposure by accelerating collagen-PEG platform development before biointegration standards harden. Secure backward integration into hydrogel precursor synthesis to neutralize REACH-driven supply disruption. Channel control through exclusive ambulatory surgery center partnerships in Florida and Arizona protects pricing power against emerging bioengineered competitors.
For New Entrants and Emerging Players: Capture the India and Brazil synthetic cornea opportunity where donor tissue scarcity meets limited incumbent presence. Prioritize CDSCO regulatory consulting capabilities and Aurolab-compatible manufacturing standards. A reimbursement-first go-to-market strategy targeting publicly funded tertiary ophthalmic centers outperforms premium positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized keratoprosthesis manufacturers with captive polymer synthesis but limited geographic diversification. The five-to-ten year viability window favors platforms with both PMA and MDR regulatory momentum rather than single-jurisdiction approvals. Watch for PMDA fast-track designations as inflection signals for Japan market entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submission for novel collagen-PEG matrices compresses competitive timelines against legacy PMMA incumbents. |
| EU MDR Harmonization | CE marking alignment streamlines cross-border trials across German, French, and Italian ophthalmic centers. |
| Hospital System Partnership | California and Texas multi-site platforms consolidate procurement under value-analysis frameworks favoring bundled offerings. |
| Software Companion Development | Post-implant monitoring applications reduce clinic capacity strain in publicly funded health systems. |
| Reimbursement Strategy | Dedicated CPT codes for ambulatory keratoprosthesis procedures in Florida and Arizona expand addressable volumes. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region weighted by procedural volume and regulatory maturity. The approach combines structured interviews with corneal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA PMA filings, EMA MDR submission databases, CMS Medicare reimbursement data, and ISO 14155 clinical investigation records. Bottom-up procedure volume estimates and top-down market sizing triangulate through manufacturer shipment data and hospital procurement records.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product architecture, material biocompatibility tier, end-user facility type, and regional regulatory cluster. CAGRs derive from surgical volume forecasts calibrated to demographic blindness prevalence and keratoplasty failure rates. Industry-specific inputs incorporate femtosecond laser adoption curves and collagen-PEG clinical trial enrollment trajectories.
Regulatory approval delays, reimbursement coding revisions, and supply chain disruptions from ECHA substance restrictions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about PMA pathway duration and MDR implementation consistency. Practitioners should monitor FDA advisory panel schedules and ECHA SVHC listing updates for early signals of timeline compression or extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Global Capnography Market
Medical Devices
Diabetes Devices Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Medical Pendant Market
Medical Devices
Vaginal Applicators Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Flow Diverters Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Transilluminators Market