
 Japan Hemostats Market | 2026-2036
Japan Hemostats Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Hemostats Market Insights
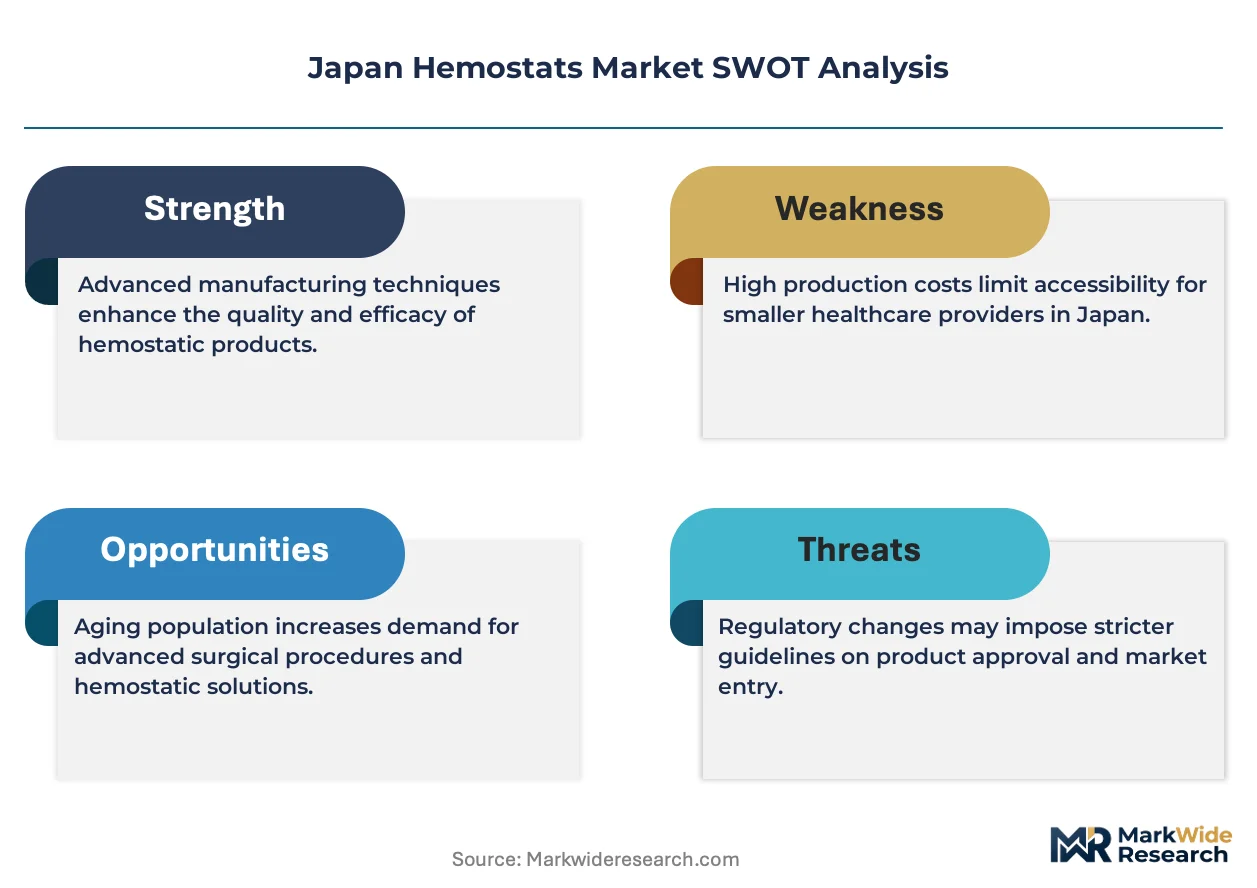
The gap between premium bioresorbable hemostats and commodity mechanical options is realigning procurement budgets across Japanese surgical wards. Johnson & Johnson Services, Inc. leverages its Ethicon franchise to dominate advanced oxidized cellulose segments. Baxter sustains leadership in thrombin-based platforms through hospital formulary control. B. Braun Melsungen AG anchors the mid-tier with gelatine sponge portfolios that compete on unit economics.
Hemostats are agents or devices that arrest bleeding through physical compression, chemical interaction, or biological activation of coagulation cascades, typically formulated as oxidized cellulose, gelatin matrices, or collagen sponges with specified absorption profiles measured in days. They serve to reduce intraoperative blood loss, shorten operative time, and minimize transfusion requirements across open and minimally invasive procedures. Disposable hemostats command the largest volume share due to infection control protocols, while spray delivery modes capture expanding preference in laparoscopic settings. Cardiac surgery applications generate the highest per-procedure value, though orthopedic surgery volumes are accelerating fastest as Japan's aging population drives joint replacement schedules.
PMDA's Class IV medical device review standards, JIS T 0313 biocompatibility requirements, and METI's regenerative medicine safety frameworks collectively shape product development timelines and clinical evidence thresholds for market entry. Manufacturers must navigate parallel compliance with MHLW reimbursement pricing rules that determine hospital purchasing incentives. Stakeholders should monitor PMDA's evolving guidance on combination hemostat-biologic products, as this regulatory boundary will determine which R&D pipelines secure priority review status.
Market Dynamics
PMDA's streamlined Class IV review pathways are compressing registration timelines for advanced hemostatic platforms, while cardiac surgery departments in Tokyo's tertiary hospitals accelerate procurement of bioresorbable agents over mechanical sponges.
Growth Catalysts
- Regulatory acceleration:PMDA's priority review framework for combination hemostat-biologic products is shortening time-to-market for next-generation platforms. Surgical device manufacturers now secure approvals faster than under legacy timelines.
- Demographic surgical load:Japan's aging population is expanding orthopedic joint replacement volumes in Osaka's surgical hub. Hospital procurement teams are scaling hemostat inventories to match procedure growth.
- Technology substitution:Spray-delivery oxidized cellulose is displacing traditional sponge formats in laparoscopic settings. Tokyo metropolitan hospitals lead this transition due to infection control protocols.
Market Restraints
- Input cost concentration:Purified collagen and recombinant thrombin supplies concentrate among North American biologics suppliers. Japanese manufacturers face currency exposure and supply security risks.
- Reimbursement compression:MHLW's biennial pricing revisions for surgical consumables are narrowing margins on premium hemostatic agents. Hospital purchasing committees prioritize unit economics over performance differentiation.
- Technical absorption limits:Gelatin-based matrices exhibit variable degradation rates in patients with coagulation disorders. Surgeons in high-complexity cardiac units report inconsistent hemostasis outcomes.
Strategic Opportunities
- Underpenetrated regional expansion:Fukuoka's emerging medical corridor lacks dedicated hemostat distribution infrastructure. Manufacturers can establish direct hospital contracts before competitor saturation.
- Technology convergence:Integration of hemostatic matrices with antimicrobial coatings addresses surgical site infection protocols. PMDA's combination product pathway offers priority review for dual-function platforms.
- Channel innovation:Specialized surgical device distributors in Nagoya are consolidating purchasing power for mid-tier hospitals. Partnership models with these aggregators reduce direct sales overhead.
Industry Challenges
- Specialized clinical affairs talent:PMDA submission requirements for Class IV devices demand expertise in JIS T 0313 biocompatibility documentation. Domestic regulatory affairs professionals command premium compensation.
- Legacy system integration:Hospital inventory management platforms in Japan's prefectural medical centers operate on fragmented ERP architectures. Real-time hemostat consumption tracking remains technically constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Hemostats Market |
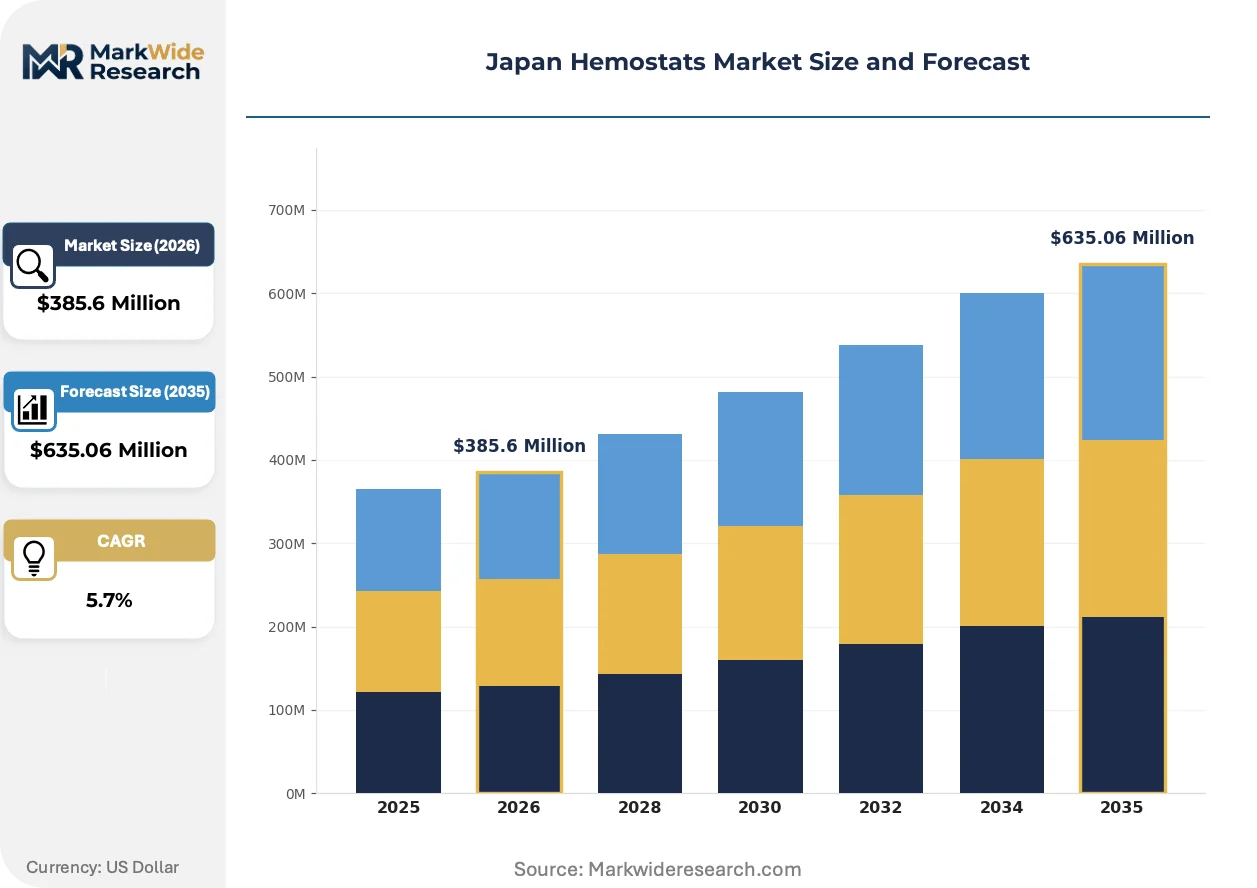
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $635.06 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Hemostats, Disposable Hemostats, Surgical Hemostats, Topical Hemostats Application: Cardiac Surgery, Orthopedic Surgery, General Surgery, Trauma Surgery Delivery Mode: Injectable, Sprays, Gels, Powders End User: Hospitals, Surgical Centers, Clinics, Emergency Departments |
| Companies Covered | Medtronic, Pfizer, Johnson & Johnson Services, Inc., CryoLife, Inc., Integra LifeSciences Corporation, B. Braun Melsungen AG, BD, Cohera Medical, Inc., Baxter, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Hemostats Market Trends and Innovations
Spray-applied hemostatic platforms are reconfiguring surgical workflow economics, while regulatory frameworks for combination products create new competitive moats. Device manufacturers must align R&D pipelines with PMDA's evolving guidance.
Flowable gelatin-thrombin composites is electrifying cardiac surgery departments in Tokyo's metropolitan cluster. Cardiovascular specialists at Keio University Hospital and adjacent tertiary centers have adopted spray delivery for median sternotomy procedures. This format is electrifying the shift from manual sponge compression to automated application systems, compressing operative time and reducing nursing labor intensity.
PMDA's 2023 guidance on regenerative medicine product classification is redefining hemostat-biologic boundaries. Manufacturers must now demonstrate distinct mechanism-of-action evidence for combination platforms seeking medical device rather than cellular therapy designation. Cardiac surgery applications face the steepest evidentiary requirements, with sponsors submitting expanded biocompatibility portfolios under JIS T 0313.
Hospital formulary consolidation is concentrating purchasing authority within Tokyo and Osaka procurement alliances. Independent surgical centers in Aichi and Hyogo prefectures are ceding autonomy to regional purchasing cooperatives that negotiate volume-based contracts. Kansai's orthopedic surgery networks exhibit the fastest migration toward centralized hemostat sourcing, displacing individual hospital preference cards.
Japan Hemostats Market Segmentation
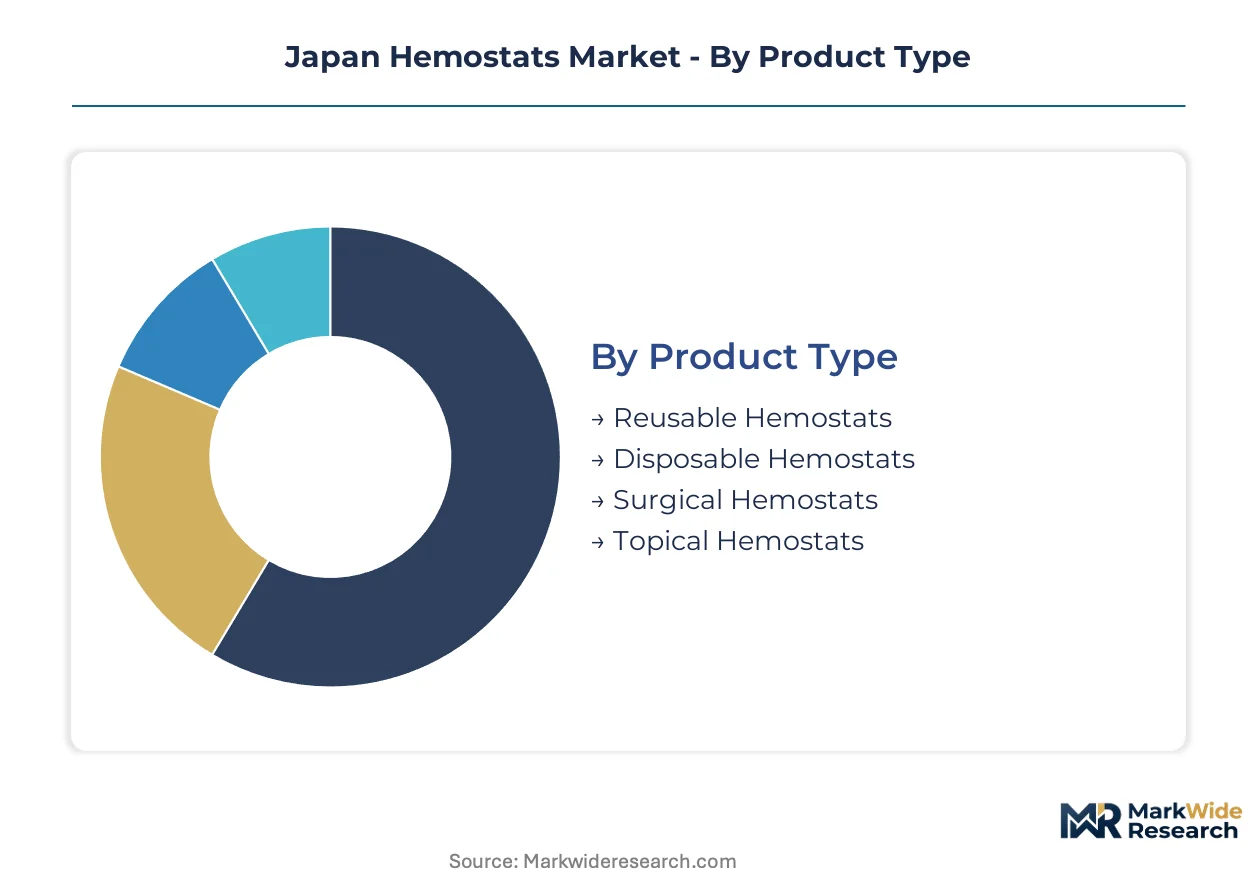
Japan's hemostat segmentation reveals distinct procurement patterns across infection control protocols, surgical complexity tiers, and reimbursement pathways. Understanding these divides exposes where premium bioresorbable platforms command pricing power versus where commodity formats dominate unit economics.
Product Type:
Standalone formats operate independently during procedures, while embedded systems integrate with broader surgical platforms and consumable kits.
- Disposable Hemostats:Single-use oxidized cellulose and gelatin sponges dominate Tokyo metropolitan hospital procurement due to strict infection control mandates. Cardiac surgery departments in Keio University Hospital and adjacent tertiary centers specify disposable formats exclusively, absorbing premium unit costs to eliminate cross-contamination risk.
- Surgical Hemostats:Flowable gelatin-thrombin composites and fibrin sealants integrate with automated application systems in laparoscopic settings. Osaka's surgical hub drives demand for these embedded platforms as orthopedic joint replacement volumes climb.
- Reusable Hemostats:Mechanical compression devices with sterilizable metal frames persist in select prefectural medical centers with constrained consumable budgets.
- Topical Hemostats:Surface-applied powders and films serve superficial wound management in emergency departments and outpatient clinics across Aichi prefecture.
Volume placements concentrate in Disposable Hemostats; the faster expansion belongs to Surgical Hemostats.
Application:
Procedure reimbursement tiers from MHLW create sharp demand stratification across surgical specialties.
- Cardiac Surgery:Median sternotomy and bypass procedures generate the highest per-procedure hemostat consumption in Japan. Tokyo's tertiary cluster specifies advanced bioresorbable matrices with recombinant thrombin, where PMDA Class IV approvals and JIS T 0313 compliance justify premium positioning.
- Orthopedic Surgery:Knee and hip arthroplasty volumes are climbing fastest as Japan's demographic profile ages. Osaka's surgical hub and Nagoya's consolidating distributor networks are scaling inventory to match joint replacement schedules.
- General Surgery:Appendectomy and cholecystectomy procedures in prefectural hospitals rely on standardized sponge formats with formulary-controlled pricing.
- Trauma Surgery:Emergency departments in Fukuoka's emerging medical corridor deploy rapid-application sprays for hemorrhage control in acute settings.
Revenue concentration sits with Cardiac Surgery; Orthopedic Surgery gains share most steeply.
Delivery Mode:
Application mechanics determine compatibility with open versus minimally invasive surgical workflows.
- Sprays:Aerosolized oxidized cellulose platforms are displacing manual sponge placement in laparoscopic procedures. Tokyo metropolitan hospitals lead adoption due to compressed operative time and reduced nursing labor intensity.
- Injectable:Flowable composites deliver through trocar ports during robotic-assisted surgery. High-complexity cardiac units at Keio University Hospital specify these formats for precise anatomical targeting.
- Gels:Viscous matrices conform to irregular tissue surfaces in general surgery applications across Hyogo prefecture.
- Powders:Dry particulate hemostats serve superficial trauma and battlefield-style emergency interventions.
Installed base favors Sprays; Injectable formats are climbing fastest in value terms.
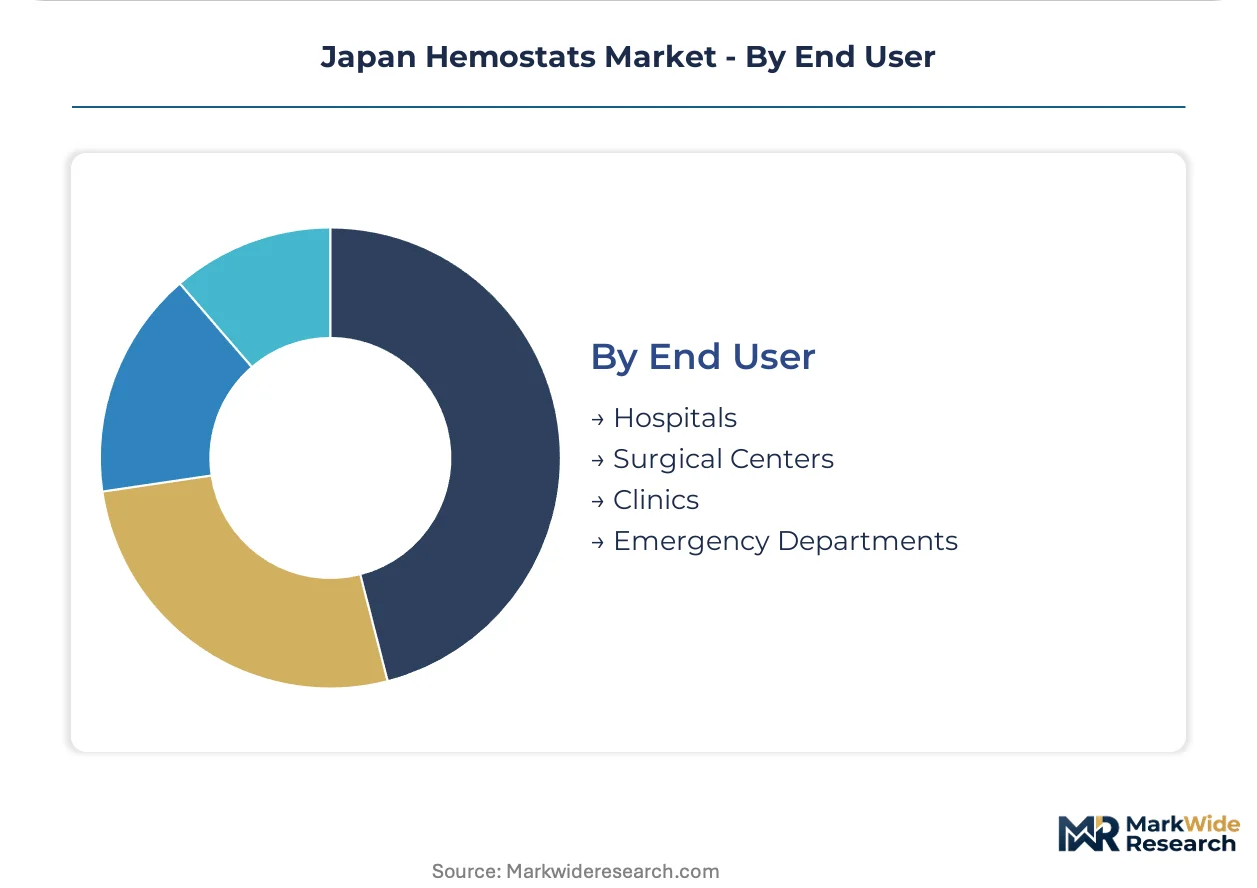
End User:
Institutional scale and case complexity dictate hemostat specification authority and volume commitment.
- Hospitals:Tertiary medical centers in Tokyo and Osaka wield centralized procurement power through regional purchasing alliances. These institutions specify advanced hemostatic platforms and negotiate volume-based contracts with direct manufacturer engagement.
- Surgical Centers:Specialized orthopedic and cardiovascular facilities in Kansi's network are migrating toward centralized hemostat sourcing, displacing individual preference cards.
- Emergency Departments:Acute care settings in Fukuoka's medical corridor and Aichi prefecture deploy rapid-application formats for trauma stabilization.
- Clinics:Outpatient surgical sites in prefectural centers operate on constrained consumable budgets with standardized mechanical sponge formats.
Purchasing authority concentrates in Hospitals; Surgical Centers are consolidating sourcing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's metropolitan hospital cluster commands the dominant share of hemostat procurement volume, with Keio University Hospital and adjacent tertiary centers specifying advanced bioresorbable platforms under centralized purchasing alliances.
Kanto/Tokyo
Cardiac surgery departments at Keio University Hospital and St. Luke's International Hospital drive demand for spray-delivery oxidized cellulose and recombinant thrombin matrices. PMDA's Class IV medical device review standards govern product registration timelines for these advanced platforms. The Tokyo metropolitan cluster leads Japan's shift from mechanical sponges to automated application systems.
Kansai/Osaka
Orthopedic joint replacement volumes climb fastest in Osaka's surgical hub as demographic aging accelerates knee and hip arthroplasty schedules. METI's regenerative medicine safety frameworks shape clinical evidence thresholds for hemostat-biologic combination products. Hospital procurement teams in the Kansai region scale inventories to match procedure growth while negotiating volume-based contracts.
Chubu/Nagoya
Specialized surgical device distributors in Nagoya consolidate purchasing power for mid-tier hospitals across Aichi and Gifu prefectures. MHLW's biennial pricing revisions for surgical consumables narrow margins on premium hemostatic agents. Regional purchasing cooperatives displace individual hospital preference cards, concentrating sourcing authority.
Kyushu/Fukuoka
Emergency departments in Fukuoka's emerging medical corridor deploy rapid-application sprays for trauma stabilization and hemorrhage control. The prefecture lacks dedicated hemostat distribution infrastructure, creating whitespace for direct manufacturer contracts. Fukuoka's medical corridor represents Japan's fastest-expanding surgical capacity outside the major metropolitan hubs.
Hokkaido
Prefectural medical centers in Hokkaido operate on constrained consumable budgets with standardized mechanical sponge formats. JIS T 0313 biocompatibility requirements apply equally to these lower-tier institutions despite limited procurement flexibility. Sapporo's regional hospitals maintain legacy inventory management platforms that constrain real-time consumption tracking.
Japan Hemostats Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's hemostat sector, with integrated medical device conglomerates holding formulary control against specialized biologics developers. The vendor base stratifies into three tiers: multinational platform holders with direct hospital contracts, mid-scale regional distributors serving prefectural networks, and emerging technology licensors seeking priority review pathways. Dominant competitive moves include portfolio diversification into combination hemostat-biologic products and strategic partnerships with Nagoya-based surgical device aggregators.
Among multinational platform holders, Johnson & Johnson Services, Inc., Baxter, and B. Braun Melsungen AG occupy positions across the premium, thrombin-based, and mid-tier gelatine segments respectively. Johnson & Johnson Services, Inc. exemplifies the integrated conglomerate archetype with centralized procurement relationships in Tokyo's tertiary cluster. Baxter represents the biologics-focused specialist model sustained through hospital formulary control. B. Braun Melsungen AG anchors the mid-tier distributor channel competing on unit economics in Osaka's orthopedic networks.
| Leading Market Players |
|---|
| Medtronic |
| Pfizer |
| Johnson & Johnson Services, Inc. |
| CryoLife, Inc. |
| Integra LifeSciences Corporation |
| B. Braun Melsungen AG |
| BD |
| Cohera Medical, Inc. |
| Baxter |
| Others |
Pricing and Supply Chain Analysis
Captive supply of purified collagen and recombinant thrombin anchors pricing power for Japanese manufacturers navigating PMDA Class IV compliance costs. Backward integration into biologics sourcing separates premium hemostat producers from commodity sponge competitors exposed to yen-denominated input volatility.
Pricing Analysis
Outcome-based pricing tied to operative time reduction and transfusion avoidance anchors premium positioning for advanced hemostatic platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by JIS T 0313 certification tier and thrombin concentration. Cost compression in the mid-tier gelatin sponge segment intensifies because MHLW biennial pricing revisions narrow hospital formulary margins. Prefectural medical centers exhibit highest price sensitivity, while Tokyo's tertiary cardiac surgery units prioritize performance differentiation over unit economics.
Supply Chain Analysis
Cold-chain logistics costs for thrombin-based biologics concentrate distribution economics around metropolitan hospital clusters. Purified collagen draws from North American biologics suppliers and selected European processors, while recombinant thrombin sources concentrate in US biotechnology manufacturing zones. Single-source vulnerability in recombinant protein supply creates exposure to currency fluctuation and export license restrictions. Distribution runs through specialized surgical device distributors in Nagoya and direct manufacturer contracts with Tokyo-Osaka purchasing alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PMDA's Class IV medical device review standards erect a cost-of-compliance barrier that rewards incumbent players with established JIS T 0313 documentation capabilities and penalizes undercapitalized entrants.
For Market Incumbents: Deploy formulary control as the primary defensive lever. Secure exclusive purchasing agreements with Tokyo's tertiary hospital cluster before competitor saturation in spray-delivery platforms. Expand JIS T 0313 biocompatibility documentation teams to accelerate combination product submissions under PMDA's priority review pathway. Counter emerging entrant pressure in Fukuoka's medical corridor by establishing direct hospital contracts ahead of distributor consolidation. For New Entrants and Emerging Players: Digital channel partnerships with Nagoya-based surgical device aggregators offer lower-friction market access than direct Tokyo sales force builds. Target Fukuoka's underpenetrated emergency department segment with rapid-application spray formats before incumbent distribution infrastructure arrives. Pursue white-label manufacturing relationships with established Class IV holders to bypass independent PMDA submission timelines. Prioritize antimicrobial-coated combination platforms eligible for priority review status. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational platform holders seeking PMDA-approved product portfolios and Tokyo hospital formulary relationships. Long-term viability hinges on sustained R&D investment in combination hemostat-biologic platforms aligned with METI's regenerative medicine safety frameworks. Acquisition target archetype: mid-scale Japanese manufacturers with captive collagen supply and existing JIS T 0313 documentation. Monitor PMDA guidance evolution on combination product classification as the critical inflection signal for pipeline valuation.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Class IV Submission Acceleration | Priority review status compresses time-to-market for combination hemostat-biologic platforms in cardiac surgery. |
| Hospital System Partnership | Direct contracts with Keio University Hospital and adjacent tertiary centers secure formulary placement against distributor competition. |
| JIS T 0313 Documentation Investment | Biocompatibility portfolio depth determines eligibility for premium pricing tiers in Tokyo metropolitan procurement. |
| Combination Product Development | Antimicrobial coating integration addresses surgical site infection protocols while qualifying for regulatory fast-track. |
| Regional Distributor Alliance | Partnerships with Nagoya aggregators reduce sales overhead in mid-tier prefectural hospital networks. |
Research Methodology
Document review covered PMDA medical device registration databases, MHLW reimbursement pricing circulars, and METI regenerative medicine guidance documents, complemented by interviews with cardiac surgery department heads, hospital procurement committee members, biomedical engineers at tertiary centers, and regulatory affairs specialists at Class IV device manufacturers. Secondary validation drew from JIS standard publications, surgical society procedure volume reports, and GPO contract disclosure filings. Bottom-up demand modeling from procedure-specific hemostat consumption rates triangulated against top-down market sizing from manufacturer shipment data.
Segment-level projections across product type, application, delivery mode, and end user dimensions informed value and volume outputs over the projection horizon. CAGRs derived from regression analysis of historical PMDA approval timelines, MHLW pricing revision impacts, and demographic surgical load projections. Industry-specific forecast inputs incorporated orthopedic joint replacement scheduling trends and spray-delivery technology substitution curves in laparoscopic settings.
Inputs from hospital procurement databases and distributor inventory records were available through the study window; gaps in real-time consumption tracking at prefectural medical centers introduce uncertainty bands around volume estimates. Forecasts reflect documented assumptions regarding PMDA review pathway stability and MHLW reimbursement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Coil Assisted Flow Diverters Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Memory Implants Market
Medical Devices
Global Positive Airway Pressure Devices Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Breathing Exercise Devices Market