
 Global Concussion Market | 2026-2036
Global Concussion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concussion Market Foresight
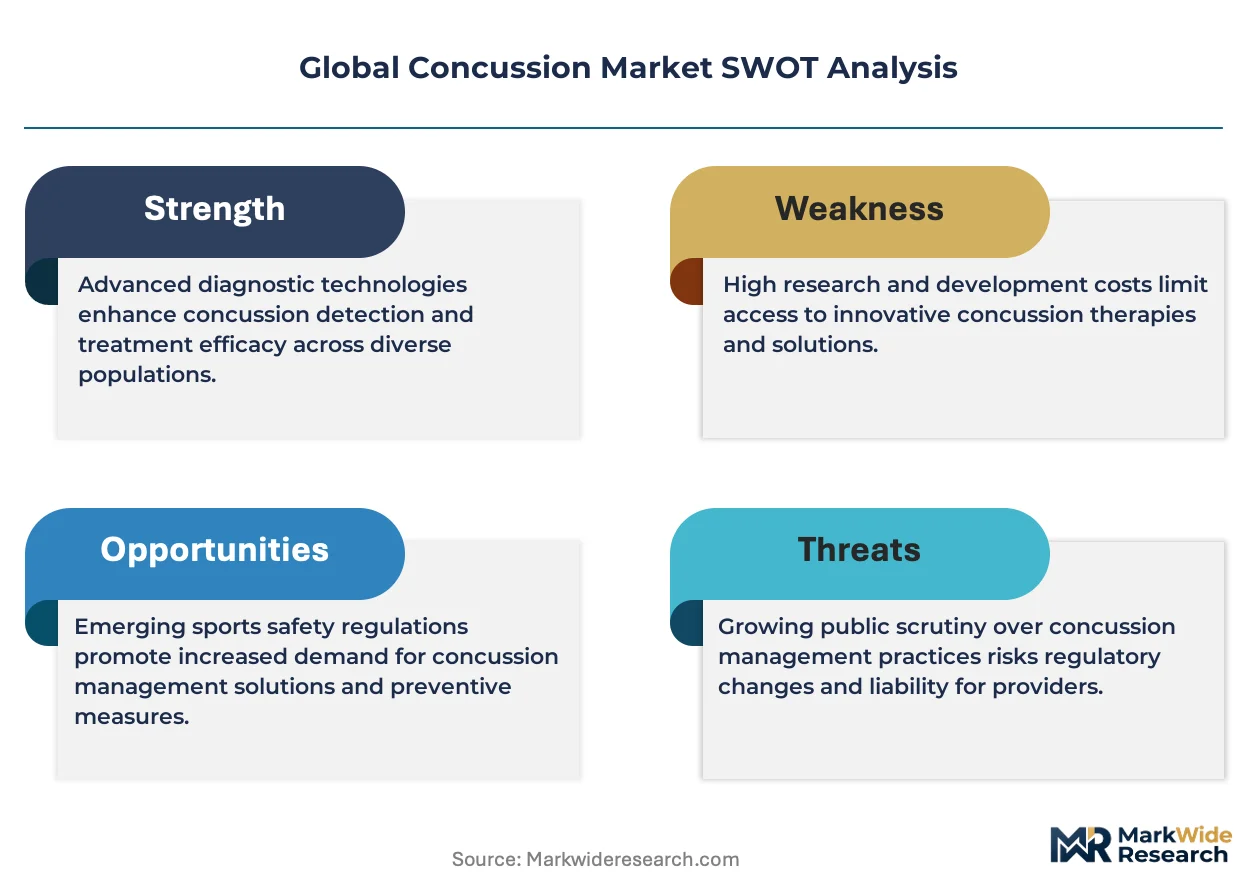
Hospital procurement of concussion diagnostic systems is tilting toward integrated platform vendors with full neuroimaging and monitoring stacks. Abbott leverages its point-of-care testing infrastructure to sustain placement in emergency departments across North America. Koninklijke Philips N.V. anchors its position through advanced imaging modalities that dominate trauma center radiology workflows. Siemens Healthineers differentiates via AI-enhanced CT and MRI reconstruction algorithms that reduce artifact interference in acute head injury reads.
Concussion constitutes a mild traumatic brain injury resulting from biomechanical force transmission to the cranium, typically assessed through Glasgow Coma Scale scoring, pupillary response evaluation, and quantitative electroencephalography when structural imaging proves inconclusive. Its primary purpose centers on rapid triage differentiation between benign cerebral contusion and life-threatening intracranial hemorrhage requiring surgical intervention. Imaging systems command the deepest margin pools due to capital intensity and recurring service contracts, while helmet sensors represent the fastest-expanding category as collegiate and professional sports programs mandate real-time impact telemetry. Cloud-based platforms for neurocognitive assessment are maturing fastest in deployment model adoption, with telemedicine solutions gaining traction in rural and military forward-operating environments.
FDA 510(k) clearance requirements shape portable diagnostic device commercialization timelines in the United States, while the EU MDR imposes stricter clinical evidence thresholds on neuroimaging software across European member states. Japan's PMDA accelerates conditional approval pathways for breakthrough concussion biomarker assays, creating regulatory arbitrage opportunities for multinationals. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payers recalibrate coverage for post-concussion syndrome management outside traditional clinical settings.
Market Dynamics
Professional sports leagues are mandating real-time impact telemetry systems, forcing diagnostic vendors to integrate hardware sensors with cloud-based neurocognitive platforms rather than selling discrete devices.
Growth Catalysts
- FDA 510(k) clearance pathways:The FDA's streamlined review for breakthrough diagnostic devices accelerates commercialization timelines for portable concussion assessment tools in emergency departments across the United States.
- Bundesliga club partnerships:German professional football clubs co-develop monitoring standards with university hospitals, creating validated deployment templates that diffuse to collegiate athletic programs.
- Quantitative electroencephalography:qEEG systems enable rapid triage differentiation when structural CT imaging returns inconclusive, expanding addressable cases in trauma centers.
Market Restraints
- Capital intensity of imaging systems:MRI and CT platforms require substantial upfront investment and recurring service contracts, limiting procurement to tier-one trauma centers and excluding rural hospitals.
- EU MDR clinical evidence thresholds:The Medical Device Regulation imposes stricter documentation requirements on neuroimaging software, extending approval timelines for AI-enhanced reconstruction algorithms.
- Helmet sensor technical limitations:Current accelerometer-based impact detection generates false positives from non-concussive forces, degrading clinical trust and adoption velocity in contact sports.
Strategic Opportunities
- Japan's PMDA conditional approval:Japan's pharmaceutical regulator accelerates pathways for breakthrough concussion biomarker assays, creating first-mover advantages for blood-based diagnostic developers.
- Military forward-operating environments:Telemedicine-enabled neurocognitive assessment platforms address unmet need in expeditionary medical units where specialist neurologists are unavailable.
- Convergence of AI and edge computing:On-device machine learning inference enables real-time concussion probability scoring without cloud latency, opening deployment in stadium sidelines and battlefield settings.
Industry Challenges
- Specialized neuroradiologist shortage:Acute head injury interpretation requires subspecialty expertise that concentrates in academic medical centers, creating diagnostic bottlenecks in community emergency departments.
- Interoperability with legacy EHR systems:Cloud-based neurocognitive platforms face integration friction with entrenched hospital information systems, extending sales cycles and implementation timelines.
- Reimbursement code uncertainty:Payers have not established consistent coverage for remote patient monitoring of post-concussion syndrome, compressing addressable revenue for digital health vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concussion Market |
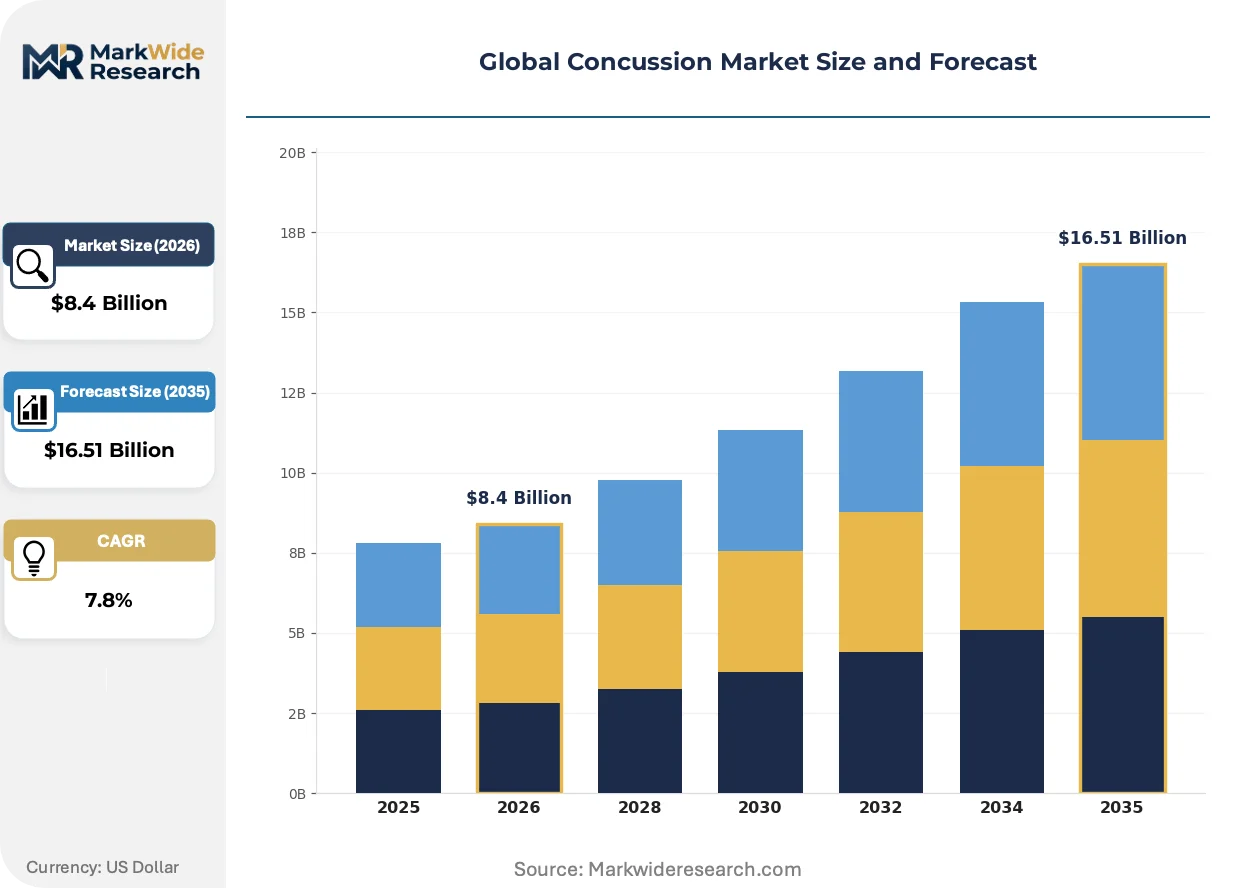
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmet Sensors, Impact Monitors, Neurocognitive Assessment Tools, Balance Testing Devices, Imaging Systems Application: Sports Safety, Military Training, Emergency Response, Rehabilitation Programs, Workplace Injury Prevention End User: Sports Teams, Defense Forces, Rehabilitation Centers, Occupational Health Providers, Paramedic Services Deployment Model: On-Premises Installations, Cloud-Based Platforms, Mobile Applications, Wearable Devices, Telemedicine Solutions |
| Companies Covered | Nihon Kohden Corporation, Integra LifeSciences, Abbott, BrainScope Company Inc., Compumedics Limited, Koninklijke Philips N.V., GE Healthcare, Medtronic plc, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concussion Market Shifts & Advancements
Diagnostic modalities are converging into integrated assessment workflows that combine physiological biomarkers, biomechanical sensors, and machine learning inference to replace sequential testing protocols.
Helmet-mounted sensor arrays is hybridizing with cloud analytics platforms to deliver real-time concussion probability alerts directly to sideline medical staff. NCAA Division I football programs and professional rugby leagues are deploying these systems at scale. The technology is compressing the window between impact occurrence and removal-from-play decisions, reducing secondary injury risk.
The EU MDR's stricter clinical evidence requirements for software-as-a-medical-device are forcing neuroimaging AI vendors to conduct prospective validation studies. Siemens Healthineers and Philips must demonstrate diagnostic accuracy gains in multi-center trials before CE marking. Trauma centers in Germany and France are delaying procurement of unvalidated reconstruction algorithms, favoring established modalities with cleared indications.
Hospital purchasing committees now demand full-stack vendors offering imaging hardware, neurocognitive software, and longitudinal monitoring in unified contracts. Discrete point-of-care device manufacturers face exclusion from large health system RFPs. This concentration is most visible in United States integrated delivery networks, where Abbott and Philips leverage existing emergency department relationships to capture expanded concussion protocol spending.
Global Concussion Market Segmentation
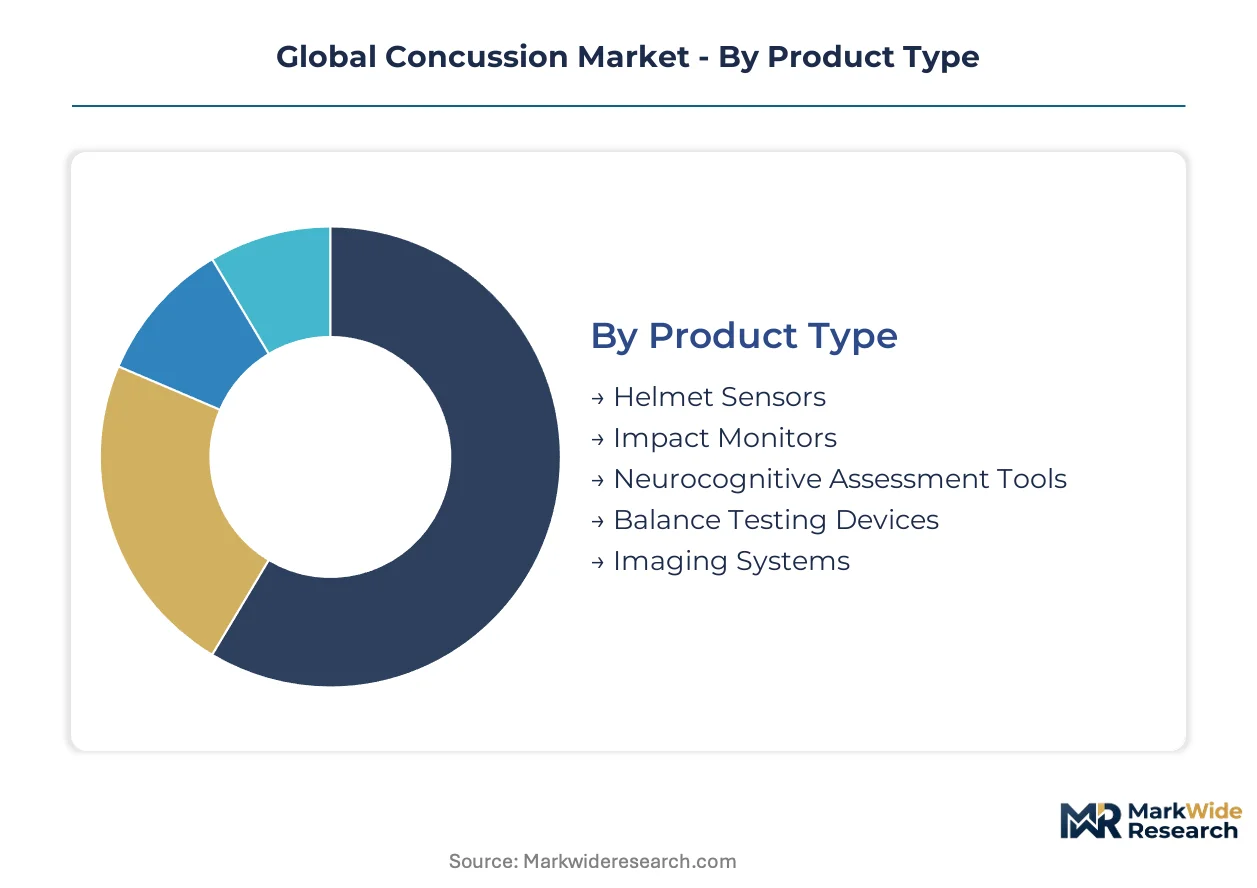
Concussion market segmentation reveals divergent commercial maturity across diagnostic modalities. Product architecture, deployment infrastructure, and end-user procurement authority create distinct margin profiles that vendors must navigate simultaneously.
Product Type:
Mature imaging hardware dominates capital expenditure while emerging sensor categories reshape competitive entry points.
- Imaging Systems:CT and MRI platforms deliver structural visualization for intracranial hemorrhage detection. German university hospitals and US trauma centers anchor procurement demand through bundled service contracts and AI-enhanced reconstruction subscriptions.
- Helmet Sensors:Accelerometer arrays capture real-time biomechanical force transmission during contact sports impact. NCAA Division I programs and Bundesliga clubs in Germany drive adoption despite false-positive calibration challenges that degrade clinical trust.
- Impact Monitors:Sideline-deployed devices measure linear and rotational acceleration at point of injury.
- Neurocognitive Assessment Tools:Computerized testing batteries evaluate attention, memory, and reaction latency.
- Balance Testing Devices:Force-plate systems quantify postural stability deficits.
Imaging Systems handle the majority of throughput; Helmet Sensors are expanding most quickly on share.
Application:
Customer risk tolerance varies sharply across institutional settings, with liability exposure dictating technology selection.
- Sports Safety:Professional leagues and collegiate athletic programs mandate baseline testing and real-time removal-from-play protocols. NFL and NCAA procurement standards diffuse to secondary school systems, creating cascade demand for integrated assessment platforms.
- Emergency Response:Emergency departments require rapid triage differentiation between benign concussion and surgical emergencies. US hospital networks prioritize FDA-cleared portable devices that integrate with existing trauma workflows.
- Military Training:Expeditionary medical units deploy telemedicine-enabled assessment for battlefield neurology.
- Rehabilitation Programs:Post-concussion syndrome management demands longitudinal monitoring capabilities.
- Workplace Injury Prevention:Construction and mining sectors adopt impact monitoring for occupational head trauma.
Emergency Response captures the deepest procurement budgets; Sports Safety is gaining share fastest.
End User:
Purchasing authority concentrates in institutions with dedicated medical staff and capital allocation flexibility.
- Sports Teams:Professional franchises and collegiate athletic departments command dedicated training facility infrastructure. US-based NFL clubs and German Bundesliga organizations co-develop monitoring standards that validate vendor technology.
- Defense Forces:Military medical services procure ruggedized field-deployable systems. US Department of Defense and NATO expeditionary units drive specifications for telemedicine-enabled neurocognitive platforms.
- Rehabilitation Centers:Specialized clinics manage post-concussion syndrome recovery protocols.
- Occupational Health Providers:Corporate medical services address workplace head injury liability.
- Paramedic Services:Pre-hospital providers require portable rapid-assessment tools.
Sports Teams handle the majority of throughput; Defense Forces are climbing the fastest on share.
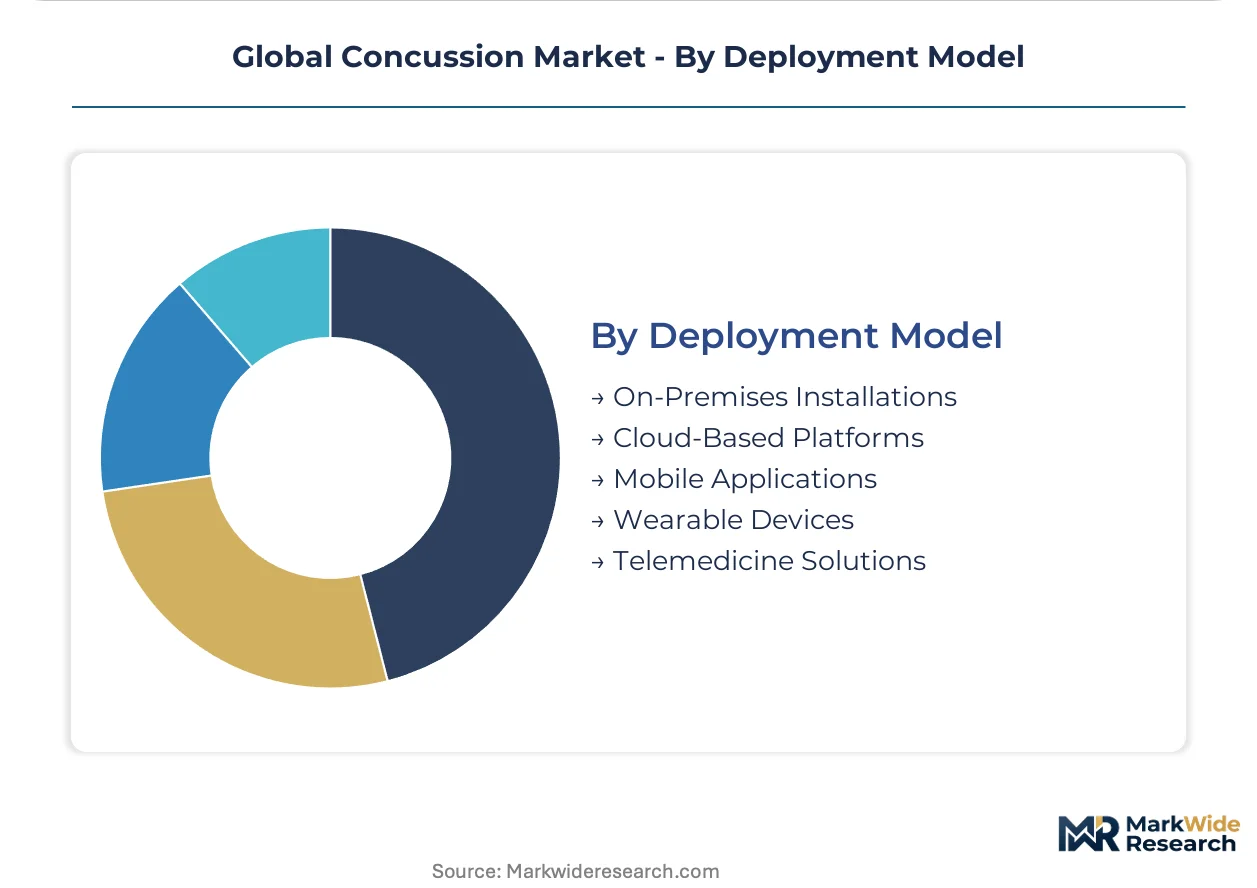
Deployment Model:
Cloud infrastructure maturity is displacing traditional capital expenditure models across diagnostic categories.
- Cloud-Based Platforms:Centralized neurocognitive assessment enables remote specialist consultation and longitudinal data aggregation. Rural US hospitals and military forward-operating environments adopt these systems to circumvent neuroradiologist shortages.
- Wearable Devices:Continuous physiological monitoring extends assessment beyond acute injury windows. Professional cycling teams and contact sports programs integrate biometric sensors with real-time alert systems.
- On-Premises Installations:Hospital-based imaging hardware requires dedicated physical infrastructure.
- Mobile Applications:Smartphone-delivered cognitive testing democratizes baseline assessment access.
- Telemedicine Solutions:Video-enabled specialist consultation bridges geographic expertise gaps.
On-Premises Installations handle the majority of throughput; Cloud-Based Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics corridor underwrites European distribution networks for concussion diagnostic hardware. German university hospitals and US trauma centers anchor procurement demand through integrated neuroimaging contracts.
United States
NFL and NCAA procurement standards diffuse concussion monitoring protocols to collegiate athletic programs nationwide. FDA 510(k) clearance pathways accelerate commercialization timelines for portable diagnostic devices in emergency departments. Boston's medical technology cluster concentrates trauma center radiology workflows and point-of-care testing infrastructure.
Germany
Bundesliga clubs co-develop monitoring standards with university hospitals, creating validated deployment templates for contact sports. EU MDR imposes stricter clinical evidence thresholds on neuroimaging software, extending approval timelines for AI-enhanced reconstruction algorithms. Munich and Berlin anchor trauma center networks where Siemens Healthineers and Philips dominate capital procurement.
Japan
PMDA conditional approval pathways accelerate breakthrough concussion biomarker assays through regulatory arbitrage opportunities. METI funding programs support telemedicine-enabled neurocognitive platforms for rural hospital networks. Tokyo's academic medical centers concentrate neuroradiologist expertise that community emergency departments cannot replicate.
United Kingdom
NHS procurement frameworks prioritize integrated platform vendors with full neuroimaging and longitudinal monitoring stacks. MHRA alignment with EU MDR transitional provisions creates temporary regulatory flexibility for software-as-a-medical-device vendors. London's trauma center networks demand AI-enhanced CT reconstruction algorithms that reduce artifact interference in acute head injury reads.
Australia
TGA approval pathways for wearable impact monitors support adoption across Australian Football League and rugby union programs. State-level sporting federations mandate baseline neurocognitive testing for amateur contact sports participation. Melbourne's medical research institutes collaborate with defense forces on field-deployable assessment systems for expeditionary environments.
Global Concussion Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors that bundle imaging hardware, neurocognitive software, and longitudinal monitoring capabilities. Discrete point-of-care device manufacturers face exclusion from large health system procurement frameworks. Two strategic archetypes dominate: diversified medical technology conglomerates leveraging existing hospital relationships, and specialized neurodiagnostic firms pursuing regulatory-first differentiation. Competitive moves concentrate on M&A to fill portfolio gaps and strategic partnerships with professional sports leagues to validate deployment templates.
Within the diversified conglomerate tier, Koninklijke Philips N.V. and Siemens Healthineers exemplify capital-intensive positioning through advanced imaging modalities and AI-enhanced reconstruction algorithms. Abbott occupies a position in point-of-care testing infrastructure that sustains emergency department placement across North American health networks.
| Leading Market Players |
|---|
| Nihon Kohden Corporation |
| Integra LifeSciences |
| Abbott |
| BrainScope Company Inc. |
| Compumedics Limited |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic plc |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Semiconductor foundry concentration in Taiwan and South Korea feeds directly into margin capture at the imaging systems tier, where AI-enhanced CT and MRI reconstruction modules command recurring subscription premiums from trauma center networks in Germany and the United States.
Pricing Analysis
Volume-discount tiering structures separate enterprise health system contracts from discrete device procurement by collegiate athletic programs. Pricing stratifies across premium imaging platforms with full AI reconstruction stacks, standard neurocognitive assessment bundles, and economy helmet sensor arrays with limited cloud analytics integration. Cost compression in the sensor tier is intensifying because NCAA procurement committees demand false-positive calibration guarantees that inflate R&D amortization. Emergency departments demonstrate lowest price sensitivity due to liability exposure from missed intracranial hemorrhage diagnoses, while secondary school athletic programs exhibit acute budget constraints.
Supply Chain Analysis
Upstream feedstock of high-purity silicon wafers and rare-earth magnet materials draws from Taiwan, China, and Japan for sensor fabrication and imaging system components. German precision optics manufacturers and South Korean display panel suppliers anchor the neuroimaging hardware tier. Single-source vulnerability concentrates in EUV lithography equipment for AI chipsets powering edge-computing inference modules. Distribution runs through hospital group purchasing organizations in North America and specialized medical device distributors serving Bundesliga training facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where FDA 510(k) clearance pathways create regulatory entrenchment that locks out unvalidated competitors from emergency department procurement cycles.
For Market Incumbents: Insulate installed base relationships through backward integration into cloud-based neurocognitive platforms that capture longitudinal monitoring revenue from post-concussion syndrome patients. Deepen switching costs by embedding AI reconstruction algorithms into radiology workflow software that trauma centers cannot easily extract. Emerging sensor entrants with superior false-positive calibration threaten the helmet monitoring tier. For New Entrants and Emerging Players: Rural Japanese hospital networks present the most penetrable geography for telemedicine-enabled neurocognitive assessment platforms that circumvent neuroradiologist shortages. Military forward-operating environments in NATO expeditionary units offer parallel white-space demand for ruggedized field-deployable systems. Pursue conditional PMDA approval pathways to establish clinical validation credentials before FDA submission. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neurodiagnostic specialists that have achieved CE marking under EU MDR transitional provisions but lack US market access. Five-to-ten year viability hinges on successful navigation of reimbursement code establishment for remote patient monitoring. Watch for FDA breakthrough device designation announcements as inflection indicators for blood-based biomarker assay developers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for portable diagnostic devices in US emergency departments. |
| Hospital System Partnership | Locks in integrated platform procurement through bundled imaging and neurocognitive assessment contracts. |
| CE Marking Pathway | Validates AI-enhanced reconstruction algorithms for EU MDR compliance across German trauma centers. |
| Software Companion Development | Enables real-time concussion probability scoring via on-device machine learning inference at stadium sidelines. |
| Reimbursement Strategy | Secures coverage codes for remote patient monitoring of post-concussion syndrome outside clinical settings. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation, and professional sports league procurement records preceded structured interviews with neuroradiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, Bundesliga club partnership announcements, and PMDA conditional approval filings. Bottom-up triangulation across device shipment estimates and top-down reconciliation against health system capital expenditure surveys anchored market sizing.
Assumptions held FDA clearance timelines and EU MDR clinical evidence thresholds fixed at observed regulatory patterns, while helmet sensor adoption curves and cloud platform migration rates varied across sensitivity scenarios. Segmentation modeling spanned product architecture tiers, deployment infrastructure types, and end-user procurement authority levels. CAGRs derived from regression analysis against historical imaging system replacement cycles and sports safety mandate diffusion patterns. Trauma center radiology workflow integration timelines and military telemedicine procurement cycles served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by blood-based biomarker assay developers or edge-computing hardware specialists would shift outcomes substantially. Cross-checking against TGA approval timelines for wearable impact monitors and NHS procurement framework awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Foley Catheters Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Depression Devices Market