
 Interphalangeal Fusion Market | 2026-2036
Interphalangeal Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Interphalangeal Fusion Market Analytics
ISO 13485 certification is reorganizing competitive standing among interphalangeal fusion suppliers, filtering out contract manufacturers lacking quality management rigor. Arthrex leverages its vertically integrated graft-to-implant portfolio to control surgeon preference across the toe and finger fusion workflow. Zimmer Biomet anchors its position through scale advantages in stainless steel and titanium fixation hardware. Stryker differentiates via dedicated extremity sales infrastructure that reaches ambulatory settings beyond hospital purchasing committees.
Interphalangeal fusion denotes the surgical arthrodesis of adjacent phalangeal bones, typically employing compression screws, plates, or allograft/autograft matrices to achieve osseous union across the proximal or distal interphalangeal joint, with fusion angles calibrated to preserve digit function and grip mechanics. Fixation devices command the largest product share due to reusable instrument sets and implant recurrence revenue, while implants with biomaterials represent the fastest-expanding technology segment as osteobiologic coatings improve union rates in osteoporotic bone. Ambulatory surgical centers are capturing disproportionate case volume growth as anesthesia protocols and tourniquet techniques enable same-day discharge for isolated digit procedures.
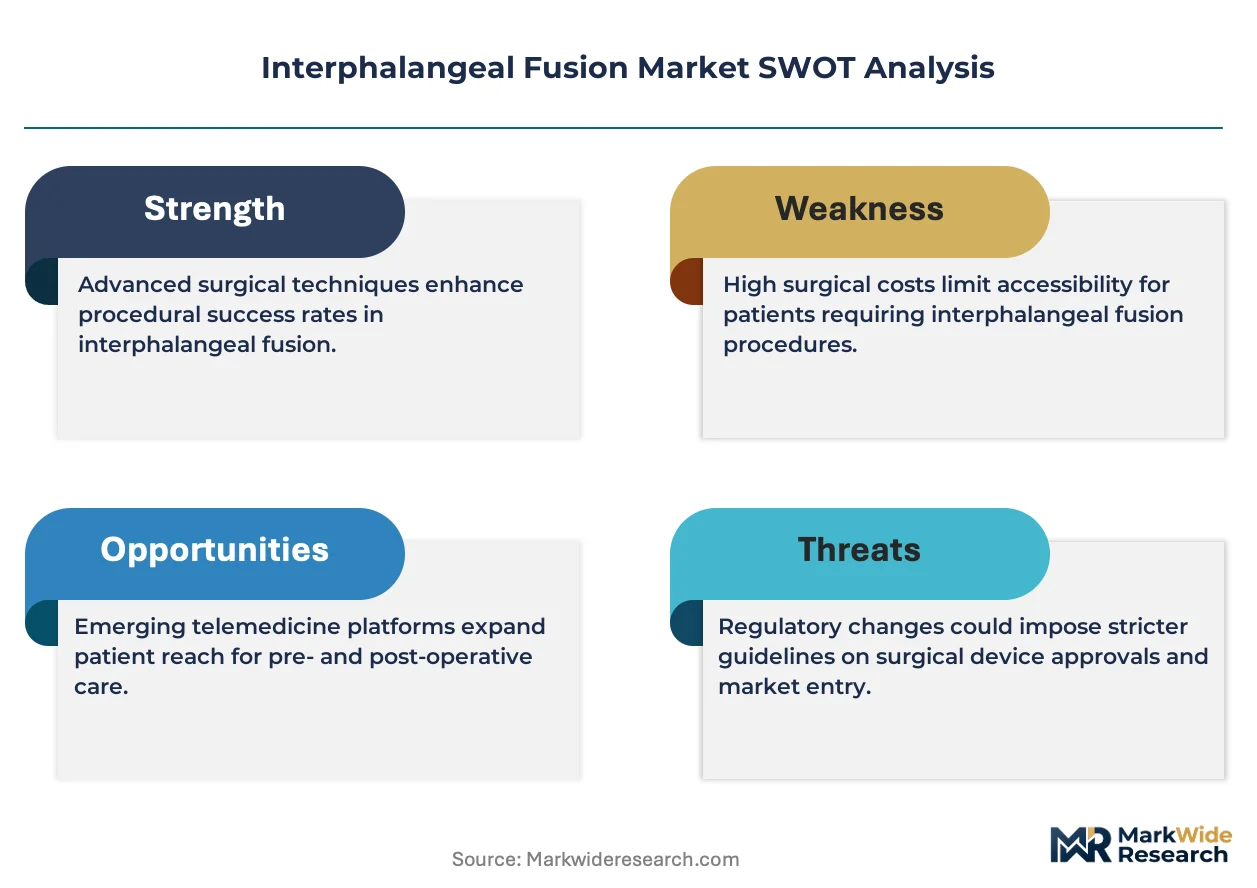
FDA 510(k) premarket notification requirements govern implant clearance timelines, while the EU Medical Device Regulation (MDR) intensifies clinical evidence burdens for CE-marked extremity fixation systems. ISO 14155 clinical investigation standards further constrain trial design for novel fusion constructs, extending development cycles for biodegradable interference screws. Stakeholders must monitor reimbursement parity between inpatient and outpatient settings, as site-of-service differentials increasingly determine where surgeons perform interphalangeal arthrodesis.
Market Dynamics
The migration of interphalangeal fusion procedures from inpatient hospitals to ambulatory surgical centers is compressing purchasing timelines and forcing implant manufacturers to restructure their sales coverage models around same-day discharge protocols.
Growth Catalysts
- Aging demographics in the United States:The expanding Medicare-eligible population sustains procedure volume for degenerative joint conditions in digits, with orthopedic clinics reporting elevated patient intake for hammertoe and arthritis-related fusions.
- FDA 510(k) clearance pathway:The streamlined premarket notification process accelerates commercialization timelines for extremity fixation devices, enabling faster market entry for novel compression screw designs.
- Osteobiologic coatings:Advanced surface treatments on titanium and stainless steel implants improve osseointegration rates in osteoporotic bone, expanding the treatable patient population for digit arthrodesis.
Market Restraints
- Titanium price volatility:Raw material cost fluctuations for aerospace-grade titanium feedstock compress margins on premium fixation hardware and constrain pricing flexibility for mid-tier manufacturers.
- EU MDR clinical evidence requirements:The intensified burden for CE-marked extremity implants extends development cycles and raises regulatory compliance costs for European market access.
- Non-operative alternatives:Orthotic bracing and injectable therapies for early-stage digit deformities delay surgical intervention and reduce addressable procedure volume in conservative-treatment markets.
Strategic Opportunities
- Biodegradable interference screws:Convergence of polymer science and orthopedic fixation creates white space for resorbable implants that eliminate hardware removal surgeries in pediatric and active adult populations.
- Ambulatory surgical center penetration:Same-day discharge protocols enable case volume capture outside hospital purchasing committees, rewarding suppliers with dedicated extremity sales infrastructure.
- PLI scheme incentives in India:Production-linked incentives for medical device manufacturing attract contract manufacturers seeking cost-competitive production bases for export markets.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for contract manufacturers create bottlenecks in supplier qualification, delaying product launches for emerging implant brands.
- Surgeon training requirements:Minimally invasive arthrodesis techniques demand specialized cadaveric instruction and proctored cases, limiting adoption velocity outside major orthopedic training centers.
- Reimbursement parity disputes:Site-of-service payment differentials between inpatient and outpatient settings create administrative friction for surgical scheduling and facility selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interphalangeal Fusion Market |
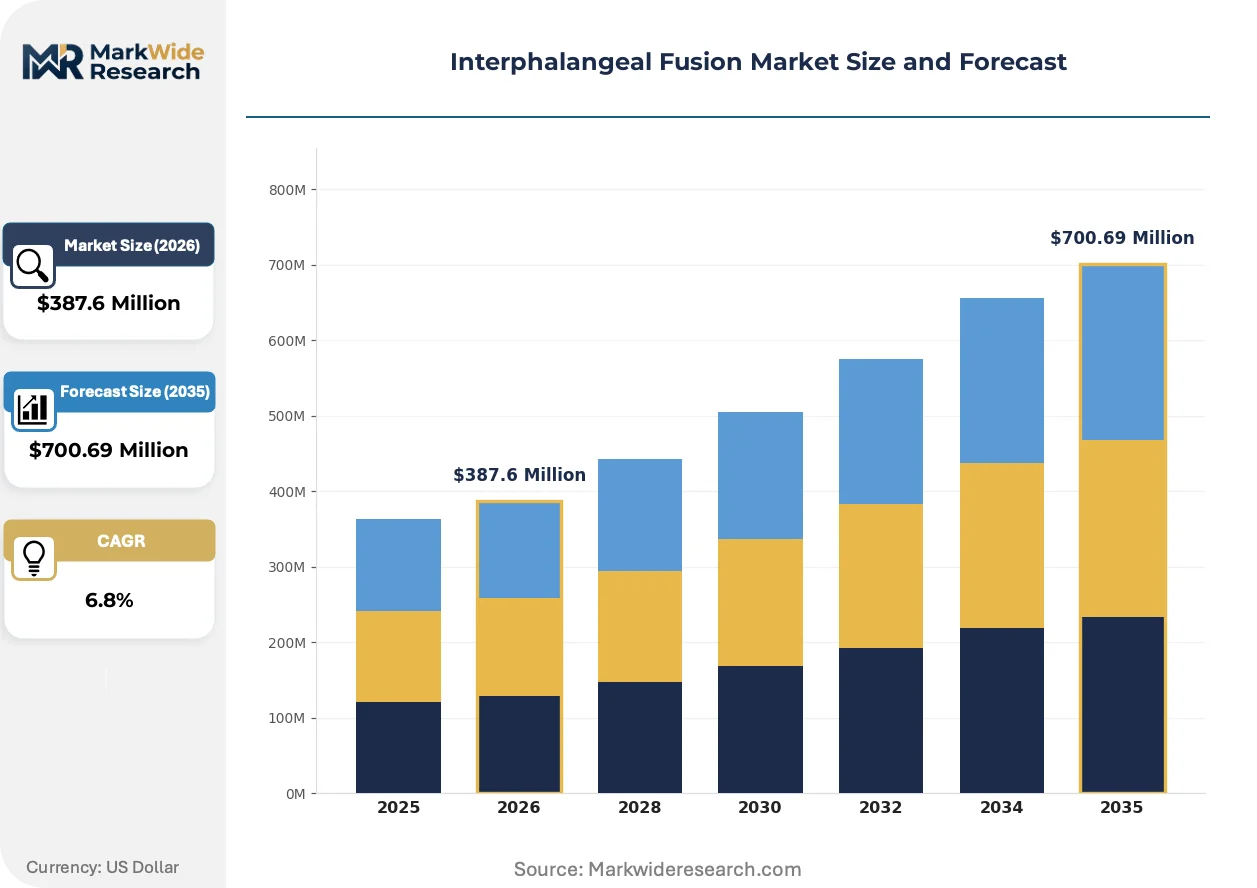
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Graft, Fixation Devices, Implants, Surgical Instruments End User: Hospitals, Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Application: Trauma Surgery, Sports Injuries, Arthritis Treatment, Congenital Deformities Technology: Minimally Invasive Surgery, Robotic Assistance, Implants with Biomaterials, 3D Printing |
| Companies Covered | Arthrex, Zimmer Biomet, Acumed, Stryker, Paragon 28, Nextremity Solutions, Arthrosurface, Centric Medical, Extremity Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interphalangeal Fusion Market Evolving Landscape
Three convergent forces are restructuring how interphalangeal fusion products reach surgeons and patients: biodegradable materials science, regulatory harmonization pressures, and the operational redesign of surgical delivery.
Biodegradable polymer fixation is fragmenting the traditional metal-dominant implant landscape. Polylactic acid and polyglycolic acid interference screws now offer compression stability without secondary removal procedures. Ambulatory centers in the United States are adopting these devices for younger, active patients seeking reduced surgical burden. The technology is fragmenting purchasing patterns as surgeons maintain parallel inventory for metal and resorbable options based on patient age and bone quality.
EU MDR implementation timelines are compressing legacy product registrations across European markets. The regulation mandates updated clinical evidence for Class IIa and IIb extremity implants previously cleared under the Medical Device Directive. Manufacturers with grandfathered CE certificates face portfolio rationalization decisions. Smaller suppliers are exiting the European market rather than absorbing retrospective clinical trial costs for mature fixation systems.
Surgeon ownership in ambulatory surgical facilities is altering procurement authority structures. Physician-investors in United States outpatient centers negotiate directly with implant vendors, bypassing hospital value analysis committees. Device suppliers now maintain dual sales forces for institutional and physician-owned accounts. This behavioral shift concentrates purchasing leverage among high-volume digit fusion specialists in metropolitan markets.
Interphalangeal Fusion Market Segmentation
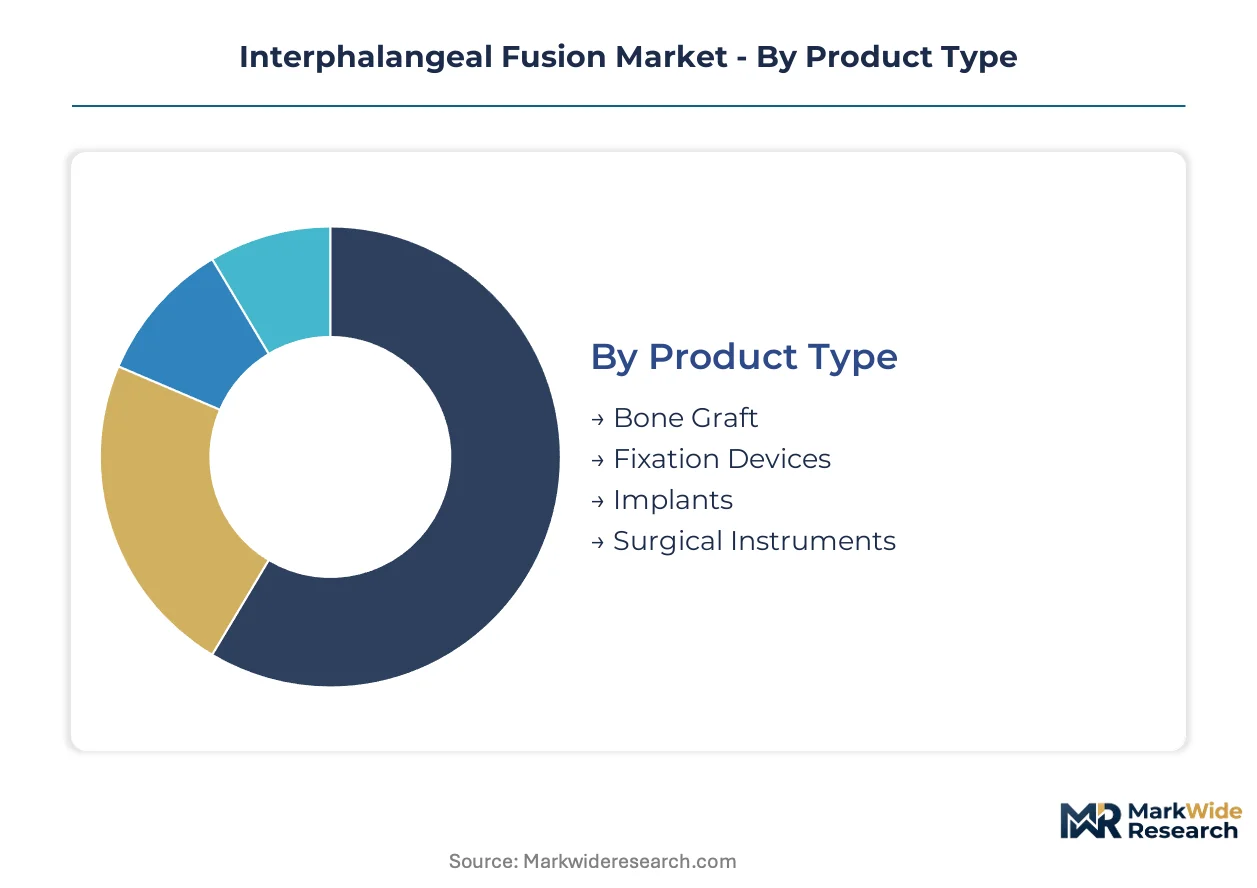
Interphalangeal fusion product portfolios fragment across four intersecting dimensions. Surgeons select fixation hardware based on bone quality, deformity severity, and discharge setting. Manufacturers must align R&D priorities with the specific reimbursement and procurement logic governing each segment intersection.
Product Type:
Margin pools concentrate in implantable hardware with recurring revenue from instrument sets and revision procedures.
- Fixation Devices:Compression screws, plates, and staples manufactured from titanium or stainless steel deliver mechanical stability across proximal and distal interphalangeal joints. Demand clusters in ambulatory surgical centers across the United States where same-day discharge protocols favor reliable fixation with minimal postoperative adjustment.
- Implants:Permanent prosthetic components including headless compression screws and anatomically contoured plates integrate with native bone through threaded or press-fit designs. Orthopedic clinics in Medicare-dense metropolitan markets drive procurement volume for osteoporotic patient populations requiring enhanced pullout resistance.
- Bone Graft:Allograft and autograft matrices provide osteoconductive scaffolding for union acceleration.
- Surgical Instruments:Reusable retractors, saws, and drill guides complete the procedural kit.
Fixation Devices hold installed capacity. Implants are rotating up the share rankings.
End User:
Procurement authority splits between institutional purchasing committees and physician-owned facility investors.
- Ambulatory Surgical Centers:Outpatient facilities specializing in extremity procedures leverage streamlined anesthesia protocols and tourniquet techniques to discharge digit fusion patients within hours. Surgeon-investors in United States metropolitan markets negotiate directly with vendors, bypassing hospital value analysis committees and compressing sales cycles.
- Orthopedic Clinics:Dedicated hand and foot surgery practices maintain captive surgical suites for straightforward arthrodesis cases. Patient intake for hammertoe and arthritis-related fusions sustains procedure frequency in aging suburban demographics.
- Hospitals:Inpatient facilities retain complex trauma and revision cases requiring overnight observation.
- Rehabilitation Centers:Postoperative therapy providers influence hardware selection through recovery outcome feedback.
Ambulatory Surgical Centers are expanding the fastest. Orthopedic Clinics defend established referral relationships.
Application:
Clinical indication determines fusion angle calibration and fixation rigidity requirements.
- Arthritis Treatment:Degenerative joint disease in digits necessitates arthrodesis when cartilage loss produces painful motion. Medicare-eligible populations in the United States generate sustained case volume as proximal interphalangeal joint destruction progresses through radiographic stages.
- Trauma Surgery:Acute fracture-dislocations and comminuted phalangeal injuries require immediate stabilization. Level I trauma centers prioritize implant systems with broad size matrices to address variable bone fragmentation patterns.
- Sports Injuries:Athletic digit trauma from ball-handling or collision contact drives younger patient demand.
- Congenital Deformities:Pediatric phalangeal anomalies require specialized small-fragment fixation.
Arthritis Treatment anchors procedure volume. Sports Injuries are climbing the fastest.
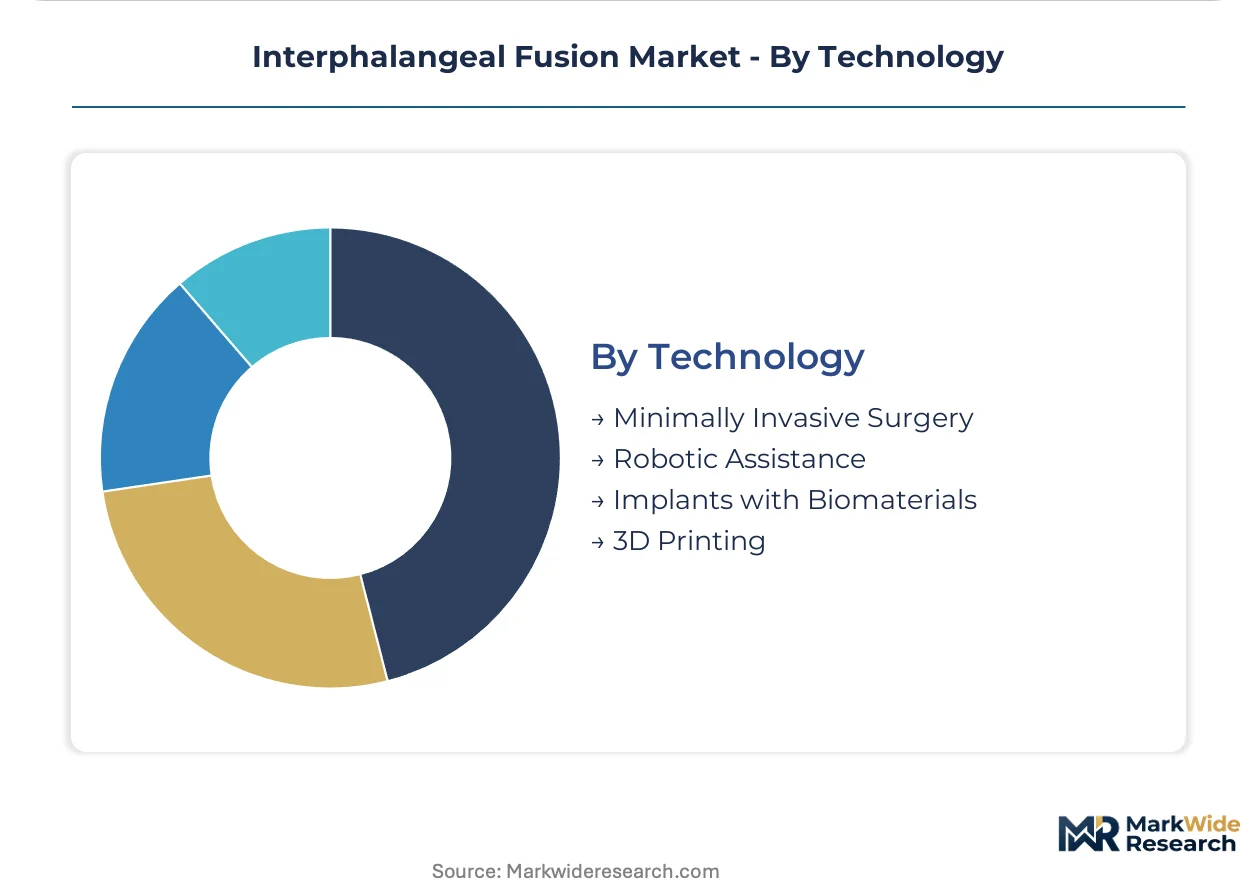
Technology:
Development investment flows toward modalities reducing surgical morbidity and accelerating union.
- Implants with Biomaterials:Surface-engineered titanium and stainless steel devices incorporate hydroxyapatite or osteoinductive coatings to enhance osseointegration. The technology addresses elevated nonunion risk in osteoporotic bone, expanding treatable patient populations beyond conventional bone quality thresholds.
- Minimally Invasive Surgery:Percutaneous screw placement through limited incisions preserves soft tissue envelope and reduces postoperative edema. Cadaveric training requirements constrain adoption velocity outside major orthopedic residency programs.
- Robotic Assistance:Navigation systems enable precise tunnel placement for headless screw fixation.
- 3D Printing:Patient-specific guides and custom implants address complex revision anatomy.
Implants with Biomaterials hold technology leadership. Minimally Invasive Surgery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing committees and surgeon-investors in ambulatory surgical centers constitute distinct buyer archetypes across national markets. Medicare reimbursement protocols in the United States and NHS commissioning frameworks in the United Kingdom shape procurement authority distribution differently.
United States
Surgeon-owned ambulatory surgical centers in metropolitan markets negotiate directly with implant vendors, bypassing traditional hospital value analysis committees. FDA 510(k) clearance pathways accelerate commercialization timelines for extremity fixation devices. The Phoenix and Dallas orthopedic surgery clusters concentrate high-volume digit fusion specialists driving hardware procurement.
Germany
Statutory health insurance funds maintain stringent reimbursement controls on arthrodesis procedures performed in outpatient settings. EU MDR implementation mandates updated clinical evidence for Class IIb extremity implants previously cleared under the Medical Device Directive. The Baden-Württemberg medical technology corridor hosts precision machining suppliers serving orthopedic fixation manufacturers.
Japan
Aging demographics sustain procedure volume for degenerative digit conditions among the world's oldest population cohort. PMDA regulatory reviews emphasize long-term clinical follow-up data for permanent implants. The Kansai region around Osaka maintains concentration of hand surgery specialists influencing fixation hardware preferences.
India
Production-linked incentive schemes attract contract manufacturers seeking cost-competitive titanium machining capacity for export markets. CDSCO medical device regulations harmonize with international standards while maintaining domestic manufacturing requirements. The Maharashtra medical device cluster near Mumbai expands precision component fabrication for extremity implants.
United Kingdom
NHS England procurement frameworks consolidate purchasing power for orthopedic implants across hospital trusts. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining national approval pathways. The London and Southeast corridor concentrates hand surgery referral centers driving arthrodesis procedure volume.
Interphalangeal Fusion Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with dedicated extremity divisions alongside specialized foot-and-ankle focused firms. Market structure exhibits moderate consolidation around scale-driven hardware manufacturers and biomaterials innovators. Strategic archetypes include vertically integrated graft-to-implant suppliers, stainless steel fixation specialists, and ambulatory-focused sales infrastructure builders. Dominant competitive moves encompass portfolio diversification into resorbable polymers and geographic expansion through distributor partnerships in Asia-Pacific markets.
Within the diversified orthopedic tier, Arthrex, Zimmer Biomet, and Stryker exemplify contrasting strategic positions. Arthrex represents the vertically integrated archetype controlling surgeon preference across procedural workflows. Zimmer Biomet anchors the scale-driven manufacturing position with captive supply of titanium and stainless steel feedstock. Stryker occupies the ambulatory infrastructure specialist role with dedicated extremity sales coverage reaching physician-owned surgical facilities.
| Leading Market Players |
|---|
| Arthrex |
| Zimmer Biomet |
| Acumed |
| Stryker |
| Paragon 28 |
| Nextremity Solutions |
| Arthrosurface |
| Centric Medical |
| Extremity Medical |
| Others |
Value Network & Pricing Analysis
Biodegradable polymer screws replacing titanium fixation hardware are redrawing procurement geography toward polymer compounders in Germany and the United States while compressing price premiums previously sustained by aerospace-grade metal feedstock. This substitution dynamic simultaneously elevates batch-consistency requirements for medical-grade PLA and fragments volume discounts that metal-dominant suppliers once commanded.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation for titanium feedstock dominate procurement between implant manufacturers and aerospace-grade suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified producers from contract manufacturers lacking quality management rigor. Price erosion runs through the mid-tier as Indian machining capacity enters the market under PLI scheme incentives. Ambulatory surgical centers exhibit highest price sensitivity due to surgeon-investor direct negotiation, while hospital value analysis committees sustain premium tolerance for established brands.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and Asia-Europe container availability constraints are elevating landed costs for precision-machined fixation components sourced from contract manufacturers. Supply concentrates in Switzerland for high-precision screw machining, India for titanium component fabrication, and the United States for osteobiologic coating application. Raw material dependencies rest on aerospace-grade titanium billet, medical-grade polylactic acid resin, and hydroxyapatite powder. Single-source vulnerability pervades the Swiss precision machining tier. Distribution runs through orthopedic distributor networks serving ambulatory surgical centers and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of EU MDR clinical evidence capabilities is concentrating competitive position among suppliers with retrospective trial infrastructure, leaving smaller manufacturers exposed to portfolio rationalization.
For Market Incumbents: Consolidate control over surgeon training infrastructure to defend against biodegradable polymer entrants seeking to displace metal fixation share. Deepen backward integration into titanium billet sourcing to buffer aerospace-grade feedstock price volatility. Prioritize ISO 14155-compliant clinical investigation capacity to accelerate EU MDR recertification timelines for legacy implant portfolios. For New Entrants and Emerging Players: Lead with ambulatory surgical center-focused sales infrastructure targeting surgeon-investors in United States metropolitan markets where purchasing authority has shifted outside hospital committees. Target the biodegradable interference screw segment for pediatric and active adult populations seeking hardware removal avoidance. Deploy direct-to-physician sampling programs bypassing traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors vertically integrated suppliers with captive clinical evidence generation capabilities. Long-term viability hinges on portfolio breadth spanning metal fixation, resorbable polymers, and osteobiologic matrices. Watch EU MDR implementation velocity as the inflection signal determining which grandfathered CE certificates survive portfolio rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements determine market access survival for extremity implant portfolios. |
| Hospital System Partnership | GPO contract consolidation favors suppliers with scale to meet formulary standardization demands. |
| Biodegradable Implant Development | PLA-PGA polymer science convergence creates white space for resorbable fixation in active patient segments. |
| Reimbursement Strategy | Site-of-service parity advocacy shapes where surgeons perform interphalangeal arthrodesis procedures. |
| Software Companion Development | Preoperative planning tools for minimally invasive screw placement differentiate training-intensive techniques. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, and hospital procurement contract filings preceded structured interviews with orthopedic surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary validation against ISO certification registries, titanium trade flow data, and Medicare procedure volume records. Bottom-up procedure volume estimates triangulated against top-down implant manufacturer revenue segmentation.
Variance decomposition across product type, end-user facility category, clinical indication, and surface technology modality structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic healthcare expenditure trends. Forecast inputs incorporated aging demographic projections, sports injury incidence patterns, and ambulatory surgery migration rates.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR implementation timelines; material policy shifts would require re-modeling. Specific risks include titanium price volatility, reimbursement site-of-service disputes, and non-operative alternative therapy advancement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Venous Stents Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Lacrimal Duct Stent Tube Market