
 China Space Propulsion System Market | 2026-2036
China Space Propulsion System Market Size, Share, and Industry Trends Forecast 2026-2036
China Space Propulsion System Market Insights
Domestic supply channels for propulsion subsystems is fragmenting as private launch startups bypass traditional state procurement hierarchies. China Aerospace Science and Technology Corporation anchors the institutional segment through captive production of liquid oxygen-kerosene engines. Deep Blue Aerospace competes on reusable methane-oxygen architectures. LandSpace Technology specializes in medium-lift vehicles with indigenous thrust chambers.
A space propulsion system generates thrust through controlled expulsion of propellant mass to alter spacecraft velocity, trajectory, or attitude; specific impulse and thrust-to-weight ratio define operational envelopes for chemical, electric, and hybrid architectures. Chemical propulsion dominates current satellite launch applications due to mature turbopump manufacturing and hypergolic ignition reliability. Electric propulsion leads orbital maneuvering where high specific impulse offsets low thrust penalties for station-keeping. Government agencies command the largest end-user value pool through crewed spaceflight and deep space exploration budgets.
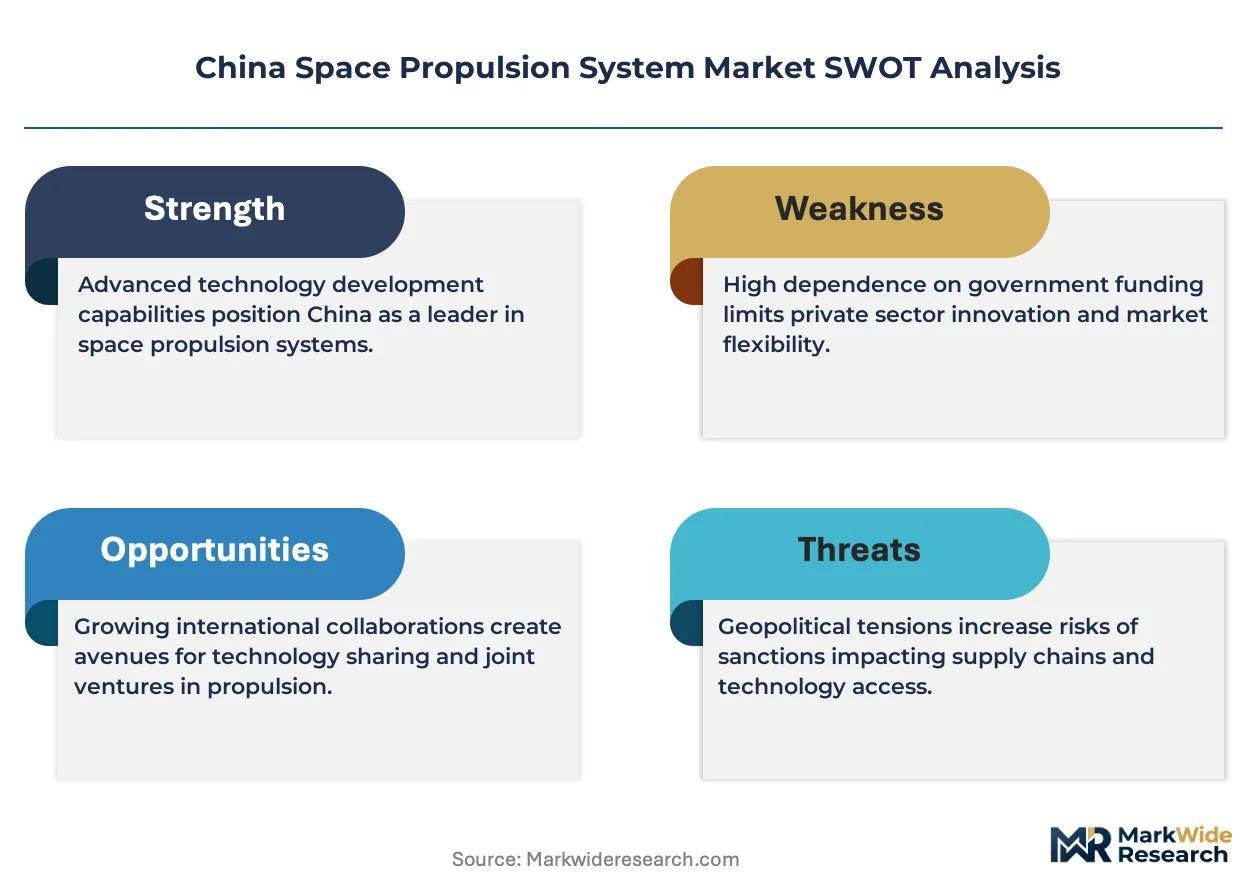
MIIT certification requirements for launch vehicle propulsion and SAMR quality standards for pressure-bearing components shape product development timelines and supplier qualification costs. China's dual carbon goals are forcing kerosene-based systems toward methane alternatives with cleaner combustion profiles. Stakeholders must monitor how NMPA-adjacent aerospace material approvals and evolving GB standards for propellant storage will redistribute compliance burdens between state incumbents and commercial challengers.
Market Dynamics
MIIT's dual carbon goals are compressing development timelines for methane-oxygen architectures while fragmenting procurement hierarchies as private launch startups bypass CASC's traditional supply channels. This regulatory-technological tension is redistributing competitive leverage between state incumbents and commercial challengers.
Growth Catalysts
- Electric Thruster Adoption:Commercial satellite constellation operators are scaling procurement of Hall-effect and gridded ion thrusters for station-keeping maneuvers, displacing chemical alternatives in geostationary orbit maintenance.
- Dual Carbon Policy Pressure:MIIT emissions mandates are accelerating methane-oxygen engine development as kerosene-based systems face compliance headwinds in manufacturing and test operations.
- Beijing Aerospace Corridor Concentration:State and private laboratory clustering in Beijing's aerospace corridor is compressing R&D cycle times through co-located propulsion testing and turbopump manufacturing.
Market Restraints
- High-Purity Tantalum Supply Concentration:Thrust chamber fabrication depends on tantalum supply chains concentrated in Central African mining regions, exposing manufacturers to price volatility and export restriction risks.
- SAMR Pressure Vessel Certification:Quality standards for pressure-bearing components extend supplier qualification timelines by 18-24 months, freezing out early-stage component vendors.
- Hypergolic Propellant Substitution:Green propellant formulations are displacing hydrazine-based systems in new satellite designs, stranding legacy production capacity and specialized handling infrastructure.
Strategic Opportunities
- Reusable First-Stage Architectures:Methane-oxygen engine recovery and rapid refurbishment protocols are opening service-based revenue models for launch providers with vertical landing capabilities.
- Guangdong Manufacturing Base Expansion:Underpenetrated southern China propulsion testing infrastructure offers greenfield site advantages for commercial challengers seeking distance from Beijing's state-laboratory orbit.
- NMPA-Adjacent Material Approvals:Evolving aerospace material standards are creating first-mover advantages for domestic suppliers achieving dual-use certification for propellant storage systems.
Industry Challenges
- Turbopump Precision Manufacturing Talent Gap:Domestic supply of machinists capable of superalloy turbine blade finishing remains concentrated at CASC subsidiaries, constraining private startup scaling.
- GB Standards Harmonization Delays:Inconsistent provincial implementation of national propellant storage standards is fragmenting compliance requirements across test site locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Space Propulsion System Market |
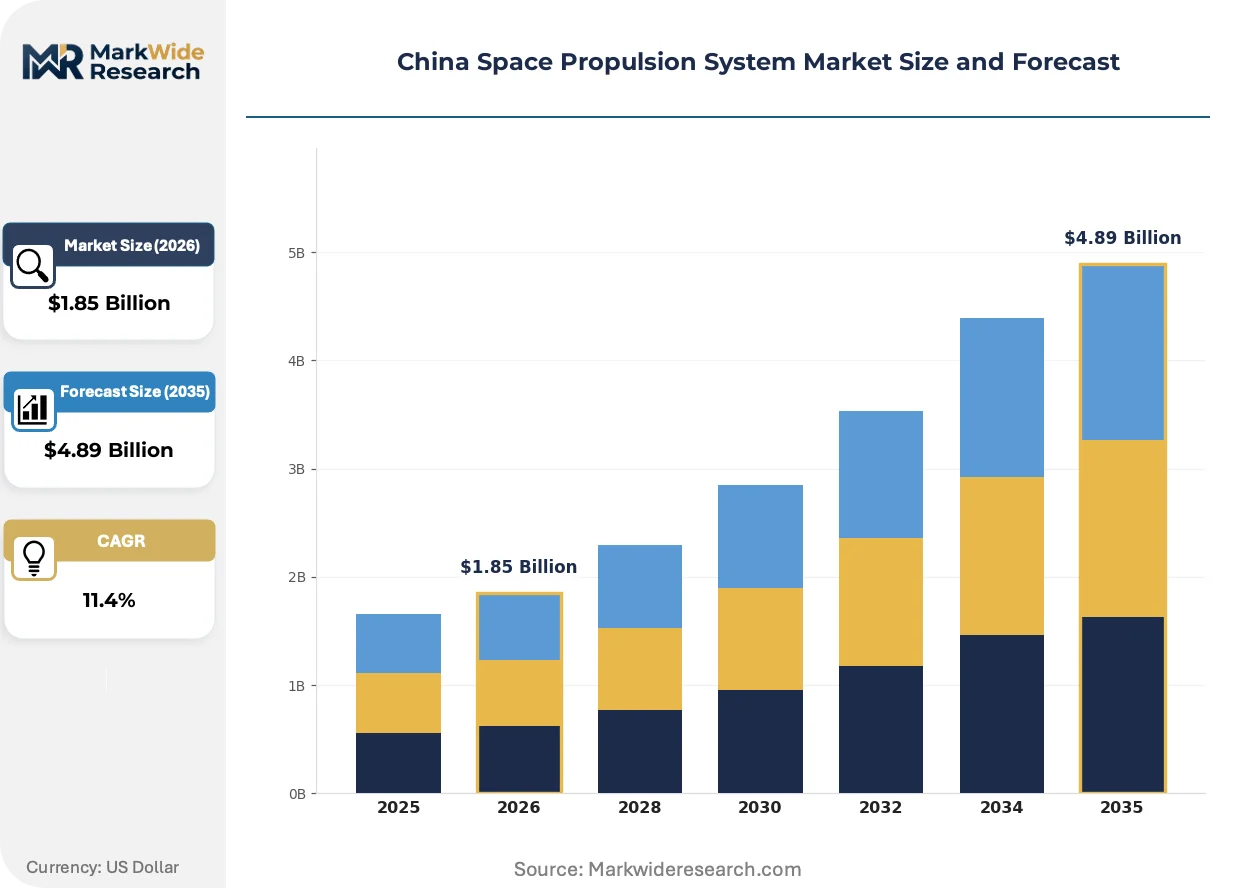
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chemical Propulsion, Electric Propulsion, Hybrid Propulsion, Cold Gas Propulsion Application: Satellite Launch, Deep Space Exploration, Orbital Maneuvering, Space Debris Mitigation End User: Government Agencies, Commercial Providers, Research Institutions, Defense Organizations Fuel Type: Liquid Oxygen, Liquid Hydrogen, Hypergolic Propellants, Kerosene |
| Companies Covered | Beijing Interstellar Glory Space Technology, Deep Blue Aerospace, China Aerospace Science and Technology Corporation, CAS Space, Orienspace, China Aerospace Science and Industry Corporation, Tianbing Technology, OneSpace, LandSpace Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Space Propulsion System Market Trends and Innovations
Propulsion architectures are bifurcating between reusable chemical systems for launch and electric systems for orbital maneuvering, with hybrid approaches emerging for deep-space missions. This technological divergence is reshaping supplier specialization and certification pathways.
Gridded ion thrusters are migrating from geostationary satellite station-keeping to low-earth orbit constellation orbit-raising applications. Mega-constellation operators are integrating these systems as primary propulsion for orbital insertion after rideshare deployment. The technology is migrating from high-margin custom builds toward standardized, high-volume production lines with compressed delivery timelines.
MIIT certification requirements for launch vehicle propulsion are tightening test documentation and traceability standards for turbopump assemblies. Manufacturers must now submit real-time combustion stability data from hot-fire testing, extending pre-qualification preparation periods. Private launch startups are responding by building captive test stands in Inner Mongolia and Shandong to reduce dependency on state-owned facilities.
Long-term service contracts are displacing unit-based engine sales for reusable vehicle operators. i-Space and Galactic Energy are negotiating multi-flight maintenance agreements covering engine refurbishment and component replacement. This model is most visible among Beijing-based commercial launch providers seeking to lock in predictable cost structures across flight manifest backlogs.
China Space Propulsion System Market Segmentation
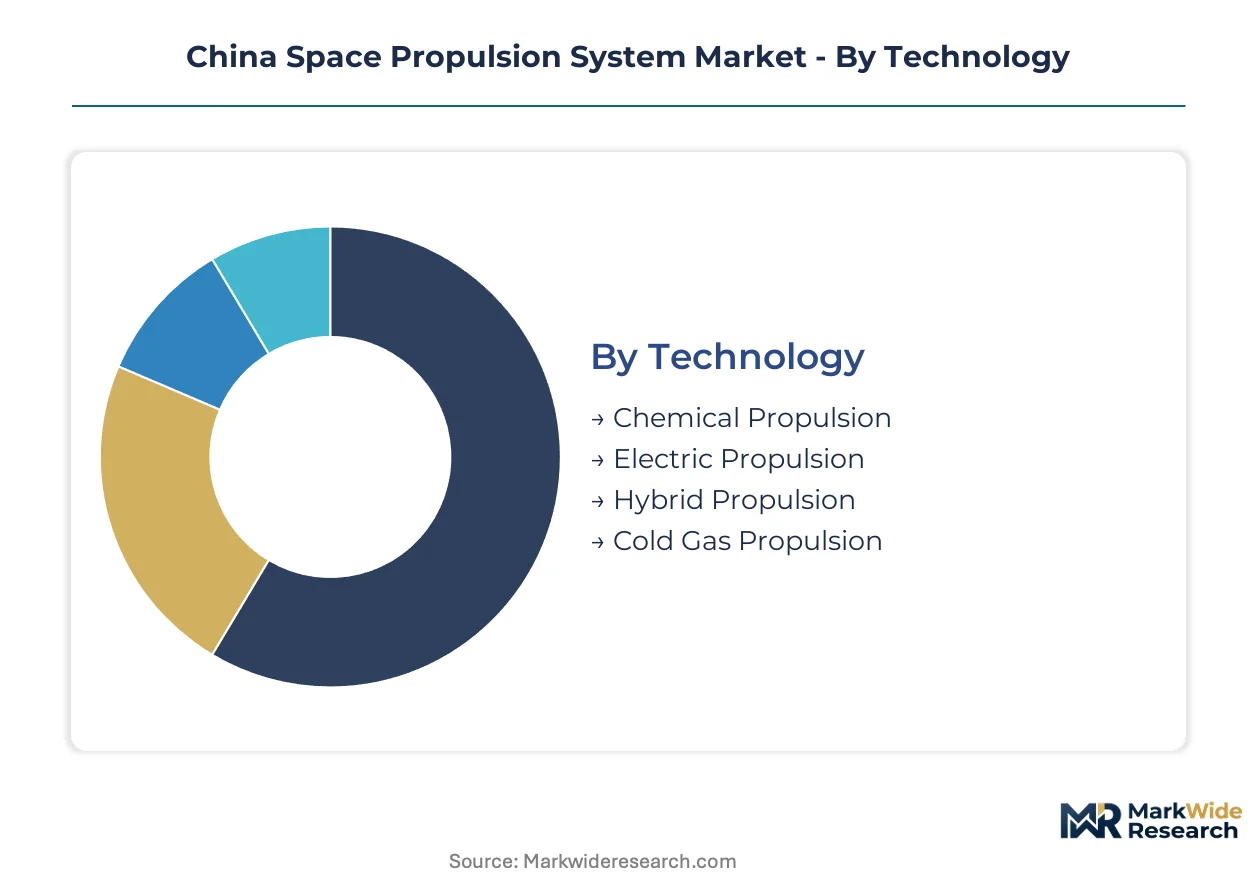
Segmentation in China's space propulsion market exposes divergent procurement rhythms across technology generations. Electric thrusters refresh on constellation replacement cycles while chemical engines tie to launch vehicle development timelines spanning multiple years.
Technology:
Cycle times vary dramatically across propulsion architectures, with electric systems turning over fastest as satellite operators refresh constellations, while chemical platforms anchor long-duration launch vehicle programs.
- Chemical Propulsion:Liquid and solid rocket engines generate thrust through controlled combustion of propellants, delivering high thrust-to-weight ratios essential for launch vehicle first stages. Demand concentrates in Beijing's aerospace corridor where CASC subsidiaries operate captive turbopump manufacturing for Long March family vehicles, though private startups are fragmenting procurement hierarchies with methane-oxygen alternatives.
- Electric Propulsion:Hall-effect and gridded ion thrusters accelerate ions through electromagnetic fields to produce high specific impulse with minimal propellant mass. Commercial satellite constellation operators in Shanghai and Shenzhen are scaling procurement for station-keeping and orbit-raising maneuvers, displacing chemical alternatives in geostationary applications as MIIT efficiency mandates tighten.
- Hybrid Propulsion:Combined chemical-electric systems optimize thrust profiles across mission phases.
- Cold Gas Propulsion:Compressed nitrogen or helium thrusters provide precise attitude control for small satellites.
Chemical propulsion dominates installed base. Electric propulsion is where expansion concentrates.
Application:
Cost tiers separate high-budget government exploration programs from commercial launch services operating on compressed margins and rapid iteration cycles.
- Satellite Launch:First and second stage propulsion systems deliver payloads to targeted orbital insertions, with reusable architectures reshaping cost structures. Commercial providers in Beijing and Guangdong are negotiating multi-flight service contracts covering engine refurbishment, locking in predictable cost structures across manifest backlogs.
- Deep Space Exploration:High-impulse chemical and nuclear-electric hybrid systems enable interplanetary trajectory maneuvers and planetary landing sequences. Government agencies command this value pool through crewed lunar and Mars mission budgets concentrated at CASC research institutes in Beijing and Xi'an.
- Orbital Maneuvering:Station-keeping, phasing, and deorbit burns for operational spacecraft.
- Space Debris Mitigation:End-of-life deorbiting and active removal propulsion systems.
Satellite launch commands the largest revenue pool. Deep space exploration carries the steepest technology barriers.
End User:
Customer type determines qualification timelines, with government agencies demanding exhaustive test documentation while commercial operators prioritize speed to manifest.
- Government Agencies:CASC and national space administration programs fund crewed spaceflight, lunar exploration, and strategic launch infrastructure. Procurement flows through centralized hierarchies with MIIT certification requirements extending pre-qualification preparation through multi-year hot-fire test campaigns.
- Commercial Providers:Private launch startups and satellite operators including i-Space, Galactic Energy, and constellation ventures are bypassing traditional state channels. These customers demand rapid engine delivery and are building captive test stands in Inner Mongolia and Shandong to reduce dependency on state-owned facilities.
- Research Institutions:Universities and national laboratories developing experimental propulsion concepts.
- Defense Organizations:Military satellite and responsive launch requirements with classified specifications.
Government agencies anchor procurement volume. Commercial providers are gaining share fastest.
Fuel Type:
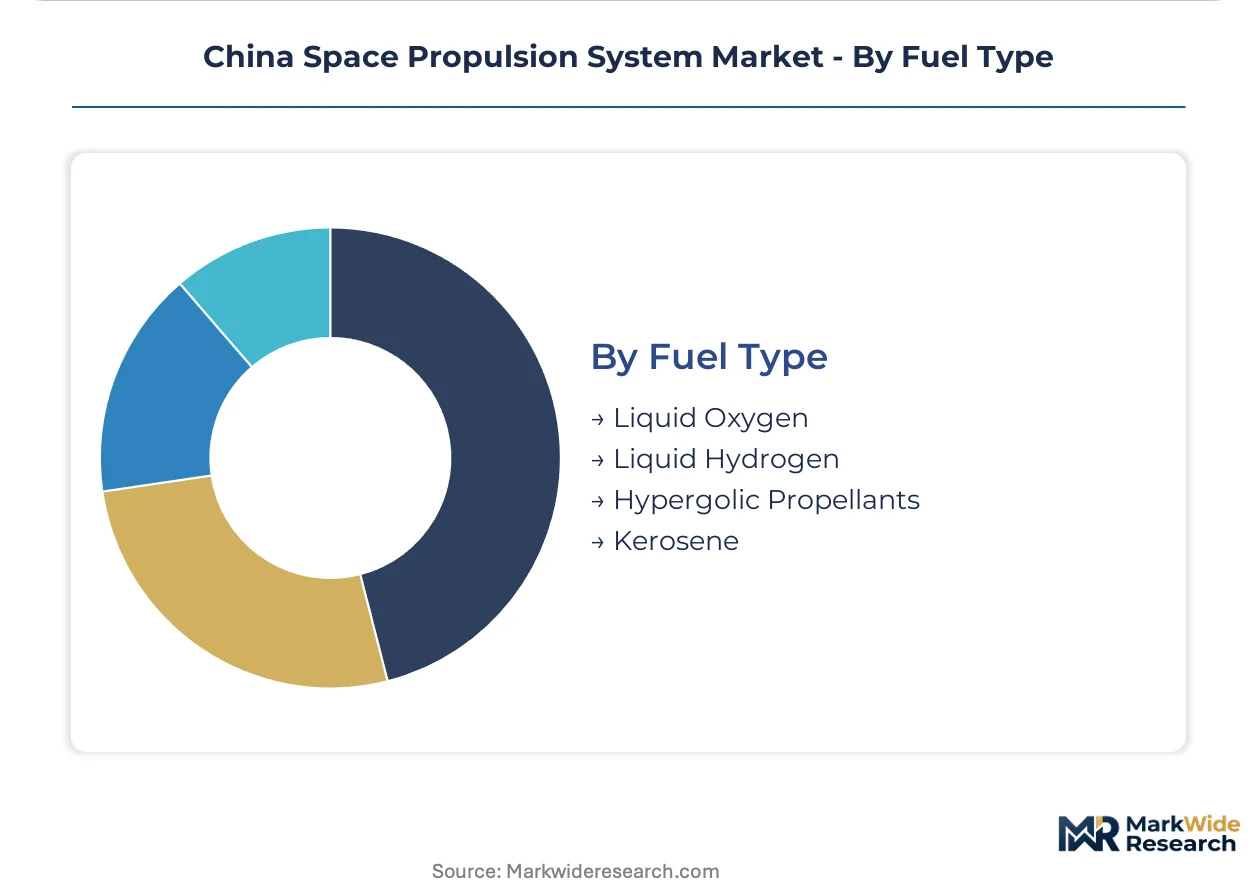
Supply concentration and MIIT emissions mandates are reshaping fuel preferences, with methane alternatives climbing as kerosene faces dual carbon compliance headwinds.
- Liquid Oxygen:Cryogenic oxidizer paired with kerosene, methane, or hydrogen fuels in staged combustion cycles. Beijing-based manufacturers are expanding production capacity to support both CASC's Long March 5/7 series and private startup methane engines, with storage infrastructure clustering in northern test sites.
- Kerosene:RP-1 refined petroleum fuel powers workhorse launch vehicles including Long March 2/3/4 families. MIIT dual carbon goals are compressing development timelines for methane alternatives as kerosene-based systems face emissions compliance headwinds in manufacturing and test operations.
- Liquid Hydrogen:High-performance fuel for upper stages and deep space missions requiring maximum specific impulse.
- Hypergolic Propellants:Self-igniting hydrazine derivatives for orbital maneuvering and attitude control.
Kerosene retains the largest installed base. Liquid oxygen is where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing's aerospace corridor anchors national propulsion development through co-located state laboratories and private test facilities. The concentration of MIIT-certified test stands and turbopump manufacturing infrastructure in northern China compresses R&D cycle times for methane-oxygen engine development.
Beijing-Tianjin-Hebei
CASC research institutes and captive production facilities dominate liquid oxygen-kerosene engine manufacturing for Long March vehicles. MIIT certification requirements for launch vehicle propulsion concentrate hot-fire testing documentation at state-owned facilities in the capital region. Private startups including Deep Blue Aerospace and LandSpace Technology are establishing parallel test capabilities to bypass traditional procurement hierarchies.
Shandong Peninsula
Commercial launch providers are constructing captive test stands in Yantai and Qingdao to reduce dependency on Beijing's state-owned infrastructure. SAMR pressure vessel certification timelines remain consistent with national standards, though provincial authorities offer streamlined environmental permitting for rocket engine test sites. The region's port infrastructure supports propellant logistics for sea launch platforms under development.
Inner Mongolia
The Jiuquan Satellite Launch Center's surrounding territory hosts expanding private test facilities for reusable engine validation. MIIT dual carbon compliance requirements apply uniformly, though lower population density permits extended-duration hot-fire campaigns without urban proximity constraints. i-Space and Galactic Energy operate dedicated test stands for methane-oxygen engine qualification.
Guangdong Province
Underpenetrated propulsion testing infrastructure in southern China offers greenfield site advantages for commercial challengers. Provincial industrial policy prioritizes aerospace manufacturing diversification beyond traditional northern concentrations. Shenzhen-based satellite constellation operators are driving demand for electric thruster procurement, with suppliers establishing southern assembly capabilities to serve this customer base.
Sichuan-Chongqing
Xi'an's aerospace research institutes maintain deep space exploration propulsion development programs for crewed lunar missions. GB standards for propellant storage implementation varies provincially, creating compliance navigation challenges for multi-site operators. The western region's titanium and superalloy processing capabilities support thrust chamber fabrication supply chains.
China Space Propulsion System Market Competitive Landscape
On the supply side, the industry is bifurcating between state incumbents with captive manufacturing infrastructure and private challengers building parallel test capabilities. CASC subsidiaries control turbopump precision manufacturing capacity and Long March vehicle integration pathways. Three strategic archetypes dominate: state conglomerates with institutional procurement lock-in, commercial launch startups with reusable architecture focus, and electric thruster specialists serving constellation operators. Competitive moves center on captive test stand construction and multi-flight service contract negotiation to lock in predictable cost structures.
Among Beijing-based commercial launch ventures, Deep Blue Aerospace, LandSpace Technology, and i-Space occupy positions exemplifying the reusable-first archetype. Deep Blue Aerospace represents commercial challengers pursuing methane-oxygen architectures outside CASC's kerosene-based legacy. LandSpace Technology anchors medium-lift vehicle specialization with indigenous thrust chamber development. i-Space exemplifies providers negotiating long-term engine refurbishment agreements to secure manifest backlogs. These entities collectively demonstrate how private startups fragment traditional procurement hierarchies through vertical landing capabilities and rapid refurbishment protocols.
| Leading Market Players |
|---|
| Beijing Interstellar Glory Space Technology |
| Deep Blue Aerospace |
| China Aerospace Science and Technology Corporation |
| CAS Space |
| Orienspace |
| China Aerospace Science and Industry Corporation |
| Tianbing Technology |
| OneSpace |
| LandSpace Technology |
| Others |
Pricing and Supply Chain Analysis
Tantalum supply concentration in Central African mining regions dictates both the cost spread between domestic and imported thrust chamber materials and the geographic clustering of precision manufacturing capacity around Beijing's state laboratories. MIIT certification timelines for pressure-bearing components further compress margin structures for early-stage vendors unable to absorb eighteen-month qualification delays.
Pricing Analysis
Volume-discount tiering structures separate CASC's institutional procurement blocks from commercial startup spot purchases, with the former commanding standard-grade kerosene engine pricing and the latter paying premiums for rapid-delivery methane-oxygen turbopump assemblies. Price differentiation rests on MIIT certification status and captive test stand ownership, with Beijing corridor incumbents least sensitive to cost escalation while Guangdong-based challengers face acute margin pressure from logistics and qualification burdens. Cost compression in commercial launch tiers is intensifying as private providers negotiate multi-flight service contracts to lock in predictable refurbishment economics.
Supply Chain Analysis
Upstream feedstock for superalloy turbine blades draws from titanium processing corridors in Sichuan and imported tantalum concentrates from Rwanda and the Democratic Republic of Congo. Liquid oxygen production clusters in northern China's industrial belt, with methane sourcing increasingly tethered to domestic shale gas developments in Sichuan and Xinjiang. Single-source vulnerability runs through Central African tantalum supply, where export restrictions propagate price volatility into thrust chamber fabrication. Distribution runs through CASC's captive procurement hierarchies for state missions, while commercial operators build direct supplier relationships with Inner Mongolia and Shandong test site operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: MIIT certification requirements and SAMR pressure vessel standards create multi-year barriers that state incumbents navigate with institutional fluency while commercial challengers absorb qualification delays.
For Market Incumbents: Pre-empt private startup encroachment by accelerating methane-oxygen engine qualification timelines and consolidating turbopump precision manufacturing talent within CASC subsidiary networks. Deepen backward integration into superalloy processing to offset tantalum price volatility exposure from Central African supply disruptions.
For New Entrants and Emerging Players: Build out captive test stand infrastructure in Shandong and Inner Mongolia to bypass Beijing's state-laboratory dependency and compress MIIT certification preparation periods. The most penetrable white-space sits in Guangdong's underdeveloped propulsion testing corridor, where provincial industrial policy prioritizes aerospace manufacturing diversification beyond traditional northern concentrations.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors electric thruster specialists with standardized production lines over custom chemical engine builders. Long-term viability across the next decade hinges on constellation replacement cycle capture. Monitor Hall-effect thruster procurement volumes from Shenzhen-based satellite operators as the primary inflection signal for electric propulsion demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Test Stand Construction | Reduces MIIT certification dependency on CASC facilities in Beijing corridor. |
| Methane-Oxygen Engine Qualification | Aligns with dual carbon mandates while displacing kerosene legacy systems. |
| Multi-Flight Service Contract Negotiation | Locks predictable cost structures for reusable vehicle operators across manifest backlogs. |
| Electric Thruster Production Standardization | Migrates Hall-effect systems from custom builds to high-volume constellation supply. |
| Superalloy Backward Integration | Secures thrust chamber fabrication capacity against tantalum supply volatility. |
Research Methodology
Initial hypotheses were tested against primary input from propulsion system engineering directors, MIIT certification officers, commercial launch procurement leads, and satellite constellation operations managers, then refined through secondary validation against MIIT industry bulletins, SAMR quality standard filings, customs data on superalloy imports, and CASC annual procurement disclosures. Bottom-up segment sizing triangulated with top-down market envelope checks.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across propulsion technology, application mission profile, end-user procurement type, and fuel chemistry architecture. CAGRs were derived from installed base turnover rates and replacement cycle analysis, incorporating electric thruster adoption curves from constellation operator procurement timelines and methane-oxygen engine development milestones from private launch startup test campaigns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Beijing-based commercial challengers or accelerated MIIT certification streamlining would shift outcomes beyond modeled ranges. Cross-checking against SAMR pressure vessel approval databases and MIIT green propellant formulation roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
LAMEA Space As a Service Market
Space
US Reusable Launch Vehicle Market
Space
Space Mining Market
Space
UK Space Electronics Market
Space
Deep Space Robotics Market
Space
Space Robots Market
Space
South Korea Space Electronics Market
Space
Spacesuit Market
Space
Space Management Solutions Market
Space
Space Traffic Management Market
Space
Space-Based Smart Sensors Market
Space
Space-Based Solar Power Market
Space
Space Blanket Market
Space
Space Radar Market
Space
Europe Space Electronics Market
Space
Space Designing Market