
 Global Functional Proteins Market | 2026-2036
Global Functional Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Functional Proteins Market Foresight
North American whey processing capacity is decoupling from traditional dairy commodity cycles as specialty fractionation investments multiply. Cargill leverages its oilseed processing footprint to anchor plant-protein extraction economics in the Midwest. Glanbia plc sustains R&D intensity around bioactive peptide isolation at its Irish innovation center. Kerry Group plc competes through flavor-protein integration systems that mask off-notes in high-concentration formulations.
Functional proteins are biologically active macromolecules composed of amino acid chains folded into specific three-dimensional conformations that enable catalytic, structural, or signaling functions, typically manufactured through enzymatic hydrolysis, microbial fermentation, or membrane filtration to achieve defined molecular weight profiles and activity levels. Their primary commercial purpose centers on delivering measurable physiological benefits—muscle protein synthesis, enzymatic catalysis, or nutrient transport—beyond basic nutritional value. Enzymes dominate value pools due to premium pricing in pharmaceutical and food processing applications, while structural proteins gain share in regenerative medicine scaffolds. Powder forms lead volume throughput in dietary supplement manufacturing, though liquid concentrates are displacing dry blends in ready-to-drink applications where solubility and mouthfeel determine formulation acceptance.
FDA nutrition labeling rules, EFSA novel food assessments, and China's NMPA biologically active substance registrations collectively shape product approval timelines and substantiation requirements for health claims across major commercial jurisdictions. REACH and F-Gas Regulation compliance in Europe adds cost layers to solvent-based extraction processes, advantaging aqueous and enzymatic methods. Stakeholders must monitor regulatory divergence on precision fermentation-derived proteins, where jurisdiction-specific classification as novel food or traditional ingredient will determine market access speed and capital allocation priority.
Market Dynamics
Precision fermentation capacity expansion is fragmenting traditional protein supply hierarchies as microbial-derived isolates achieve cost parity with dairy and soy fractions, forcing incumbents to reposition around bioactive differentiation rather than commodity scale.
Growth Catalysts
- EFSA novel food assessments:Streamlined approval pathways for precision fermentation proteins accelerate European commercialization timelines, reducing capital lock-up periods for biotech entrants.
- Clinical nutrition formulators:Hospital and long-term care facilities in Japan and South Korea are specifying condition-specific protein matrices for sarcopenia and post-surgical recovery protocols.
- Membrane filtration advances:Ceramic microfiltration systems now achieve 95% protein recovery rates from alternative oilseed streams, opening underutilized feedstocks to commercial extraction.
Market Restraints
- Input cost volatility:Organic pea and fava bean protein concentrates face margin compression from Black Sea region supply disruptions and fertilizer cost spikes.
- Regulatory friction:China's NMPA biologically active substance registration requirements impose 18-24 month approval timelines for imported functional protein ingredients.
- Substitution threat:Synthetic biology-derived amino acid blends are displacing whole-protein formulations in sports nutrition applications where leucine content drives purchasing decisions.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA regulatory modernization is opening pathways for whey protein hydrolysates in pediatric and geriatric medical foods.
- Technology convergence:AI-driven protein structure prediction combined with cell-free expression systems enables rapid prototyping of custom bioactive peptides for pharmaceutical partnerships.
- Regulatory tailwind:The US FDA's updated protein quality labeling framework creates first-mover advantage for suppliers with validated digestibility data from human clinical trials.
Industry Challenges
- Skill gap in bioprocess engineering:Precision fermentation scale-up requires hybrid expertise in metabolic engineering and industrial bioprocessing that remains scarce outside Boston and Basel talent clusters.
- Capex intensity:GMP-compliant fermentation facilities demand $200-400 million per 10,000-liter production train, constraining mid-tier participants to toll manufacturing arrangements.
- Certification timeline:Organic and non-GMO supply chain verification creates 12-18 month lag between formulation decisions and commercial availability for clean-label positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Functional Proteins Market |
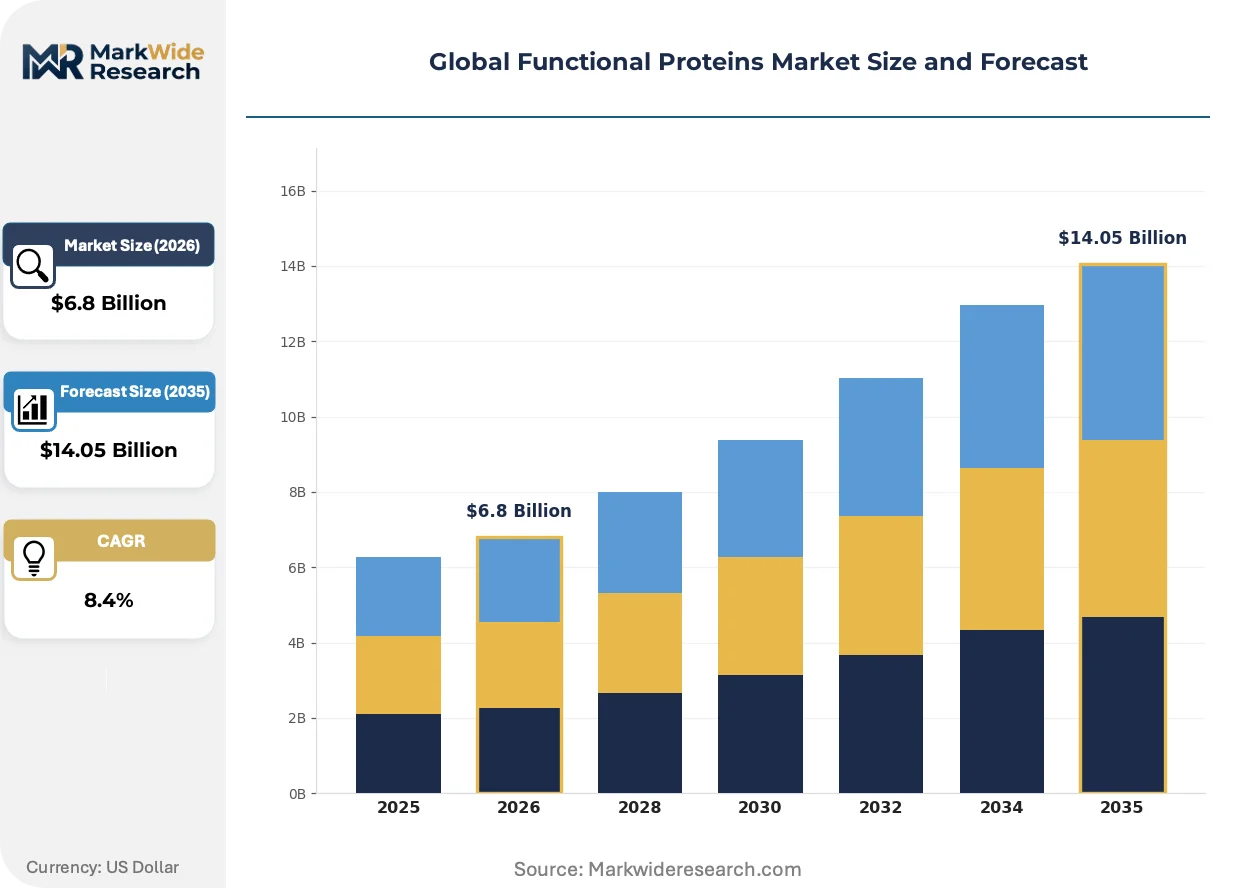
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Structural Proteins, Transport Proteins, Storage Proteins, Regulatory Proteins Application: Food & Beverage, Animal Nutrition, Pharmaceuticals, Cosmetics, Biotechnology End User: Dietary Supplement Manufacturers, Animal Feed Producers, Pharmaceutical Companies, Cosmetic Firms, Research Labs Form: Powder, Liquid, Concentrate, Granules, Capsules |
| Companies Covered | Archer Daniels Midland Company, Cargill, Glanbia plc, Kerry Group plc, Roquette Frères, DuPont Nutrition, DSM, Fonterra Co-operative Group, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Functional Proteins Market Shifts & Advancements
Biomanufacturing platforms are converging with digital quality systems to compress development cycles, while regulatory jurisdictions compete to establish approval precedents that attract protein technology investment.
Precision fermentation is absorbing capital and technical talent from traditional extraction infrastructure as microbial chassis achieve gram-per-liter titers for whey-identical proteins. Contract manufacturers in Denmark and Singapore are commissioning 100,000-liter bioreactor trains to serve CPG brand demand for animal-free dairy analogs. This capacity buildout is compressing cost curves for lactoferrin and glycomacropeptide equivalents that previously required dairy fractionation.
REACH and the EU F-Gas Regulation are tightening solvent recovery requirements for hexane-based oilseed protein extraction, advantaging aqueous enzymatic methods in European supply chains. The regulatory burden falls heaviest on mid-scale soy and rapeseed processors without integrated solvent recycling infrastructure. German and Dutch facilities are retrofitting with supercritical CO2 and enzyme-assisted aqueous systems to maintain operating licenses.
Long-term offtake agreements are displacing spot purchasing in North American sports nutrition channels as brands seek supply security for differentiated isolates. Tier-one contract manufacturers now require 24-36 month volume commitments to reserve fractionation capacity. This contracting evolution concentrates procurement leverage among scaled finished goods producers while squeezing formulation flexibility for emerging brands.
Global Functional Proteins Market Segmentation
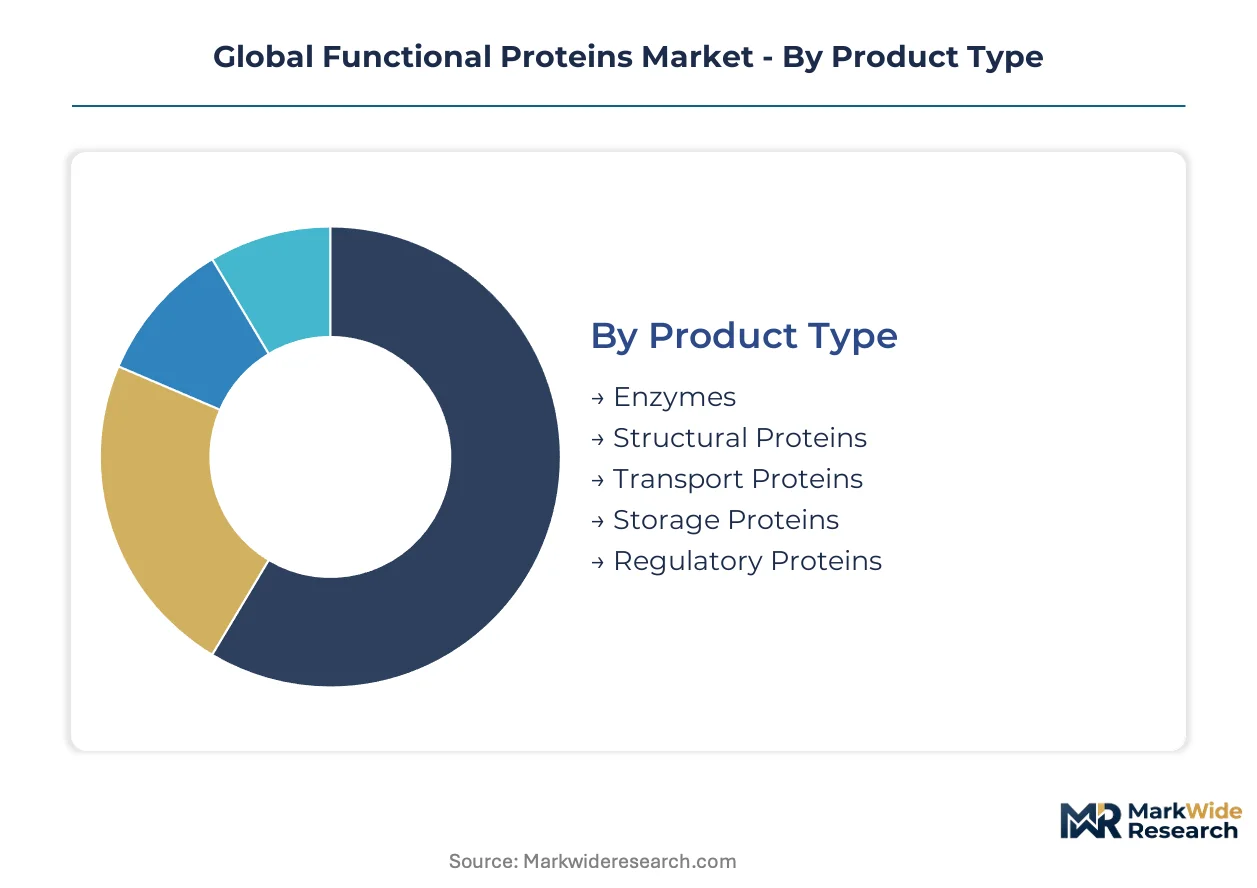
Functional proteins fragment across distinct value pools where enzymatic catalysis commands pharmaceutical premiums, while structural and transport categories scale through food and clinical nutrition channels. Understanding these segment boundaries clarifies where formulation expertise, regulatory burden, and capital intensity concentrate for suppliers and buyers alike.
Product Type:
Enzymes dominate value capture through specialty pricing, yet structural proteins are accelerating volume expansion in regenerative medicine and alternative protein scaffolding.
- Enzymes:Catalytic proteins with defined active sites and substrate specificity, manufactured through microbial fermentation or extraction. Pharmaceutical formulators in Germany and Switzerland specify proteases and lipases for drug synthesis and digestive therapeutics, paying premiums for GMP-certified batches with documented activity units.
- Structural Proteins:Collagen, elastin, and keratin variants providing mechanical integrity to tissues and scaffolds. Tissue engineering startups in Boston and Basel are procuring recombinant collagen for 3D bioprinting applications, driven by FDA and EMA pathways for regenerative medicine approvals.
- Transport Proteins:Hemoglobin, transferrin, and albumin variants facilitating nutrient and gas movement. Blood fractionators in the US and Japan maintain plasma-derived supply chains for clinical nutrition and cell culture media.
- Storage Proteins:Ferritin, casein, and ovalbumin sequestering minerals and amino acids for metabolic release. Dairy cooperatives in New Zealand and the Netherlands fractionate casein micelles for infant formula and sports nutrition matrices.
- Regulatory Proteins:Transcription factors, hormones, and signaling peptides modulating cellular processes. Gene therapy developers in California and Massachusetts contract for recombinant growth factors under FDA CBER guidance.
Today's leader: Enzymes. Tomorrow's challenger: Structural Proteins.
Application:
Food and beverage absorbs the highest tonnage, though pharmaceutical applications sustain the steepest margin structures through regulatory-validated bioactivity claims.
- Food & Beverage:Protein fortification, texturization, and enzymatic processing across bakery, dairy, and beverage categories. CPG brands in the US and Germany are specifying whey hydrolysates and pea isolates for clean-label positioning, responding to FDA protein quality labeling and EFSA health claim substantiation requirements.
- Animal Nutrition:Aquaculture feeds, pet food, and livestock supplements utilizing fish meal alternatives and insect protein concentrates. Norwegian salmon farmers and Thai shrimp processors are trialing single-cell proteins from precision fermentation to reduce wild-catch dependency.
- Pharmaceuticals:Parenteral nutrition, enzyme replacement therapies, and vaccine adjuvants requiring documented purity and endotoxin control. Injectable-grade albumin and immunoglobulin production concentrates in US and Irish plasma fractionation facilities under FDA and EMA inspection regimes.
- Cosmetics:Collagen peptides, keratin derivatives, and silk proteins for topical anti-aging and hair repair. Korean and French formulators are integrating fermented collagen fragments with documented dermal penetration data.
- Biotechnology:Cell culture media, diagnostic reagents, and biocatalysts for industrial bioprocessing. Contract manufacturers in Singapore and Denmark are scaling serum-free media formulations using recombinant transport proteins.
Food & Beverage commands current volume leadership. Pharmaceuticals maintain the most durable pricing power.
End User:
Procurement sophistication varies sharply: pharmaceutical companies impose the most stringent qualification protocols, while research labs tolerate higher variability for experimental flexibility.
- Dietary Supplement Manufacturers:Sports nutrition and wellness brands sourcing isolates and hydrolysates for powder and capsule formulations. US and UK contract manufacturers are consolidating supplier bases to secure 24-month volume commitments for differentiated whey fractions.
- Animal Feed Producers:Aquaculture, poultry, and pet food compounders optimizing amino acid profiles and digestibility. Brazilian and Vietnamese feed mills are substituting soy concentrates with microbial proteins as ANVISA and local regulators clarify novel ingredient pathways.
- Pharmaceutical Companies:Developers of parenteral solutions, biologics, and enzyme therapies requiring GMP documentation and pharmacopeial compliance. Swiss and Japanese innovators dominate high-purity cytokine and growth factor procurement.
- Cosmetic Firms:Skincare and haircare brands specifying molecular weight fractions for claimed bioactivity. French and Korean beauty houses are validating collagen peptide absorption through clinical endpoint studies.
- Research Labs:Academic and commercial R&D facilities sourcing reagent-grade proteins for assay development and mechanism studies. US and Chinese institutions drive demand for CRISPR-associated enzymes and labeled antibodies.
Pharmaceutical companies anchor premium tier demand. Research labs represent the most price-elastic segment.
Form:
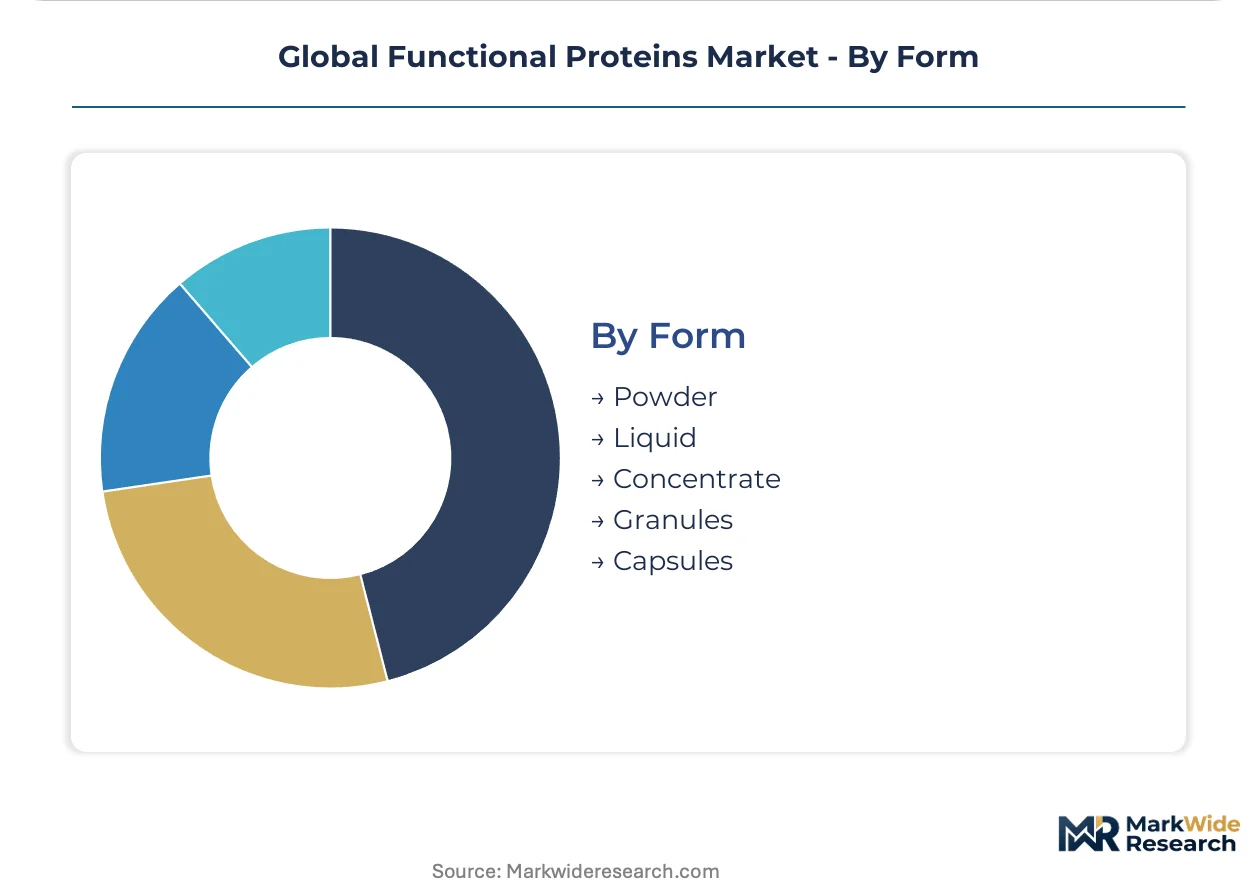
Powder forms maximize shelf stability and shipping economics, while liquid concentrates are displacing dry blends in ready-to-drink applications where solubility kinetics determine consumer acceptance.
- Powder:Spray-dried and freeze-dried isolates with defined particle size distributions for reconstitution. Dietary supplement manufacturers in the US and Germany prefer agglomerated powders for instant dispersibility in shaker bottles.
- Liquid:Concentrated solutions and suspensions with preserved activity for immediate use. Beverage formulators in Japan and Australia are specifying UHT-treated protein beverages with 12-month ambient stability.
- Concentrate:Intermediate purity streams requiring further dilution or formulation. Dairy processors in Ireland and New Zealand trade whey protein concentrates prior to final fractionation.
- Granules:Agglomerated particles for controlled-release and tableting applications. Pharmaceutical developers in Germany and Italy specify granulated collagen for effervescent and chewable formats.
- Capsules:Pre-measured gelatin or HPMC shells containing protein powders or granules. US and UK supplement brands are migrating to plant-based capsules to align with vegan positioning claims.
Powder retains manufacturing dominance. Liquid concentrates are gaining share fastest in beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in functional protein procurement patterns, with German precision fermentation startups scaling microbial capacity while US sports nutrition brands consolidate whey isolate supply chains.
United States
FDA's updated protein quality labeling framework is pressuring suppliers to substantiate digestibility claims through human clinical trials. Sports nutrition contract manufacturers in the Midwest are securing 24-36 month offtake agreements for differentiated whey fractions. Cargill leverages its oilseed processing footprint to anchor plant-protein extraction economics across Minnesota and Iowa.
Germany
EFSA novel food assessments are streamlining approval pathways for precision fermentation proteins, reducing capital lock-up periods for biotech entrants. The F-Gas Regulation and REACH compliance requirements are tightening solvent recovery standards, advantaging aqueous enzymatic methods. Precision fermentation startups in the Munich and Berlin clusters are scaling alternative protein capacity alongside dairy cooperatives in Bavaria.
China
NMPA biologically active substance registration requirements impose 18-24 month approval timelines for imported functional protein ingredients. Domestic clinical nutrition formulators are specifying condition-specific protein matrices for post-surgical recovery protocols. Yangtze River Delta bioprocessing hubs are commissioning cell-free expression systems for rapid peptide prototyping.
Japan
Hospital and long-term care facilities are driving procurement of sarcopenia-targeted protein matrices for geriatric nutrition. METI and PMDA oversight shapes pharmaceutical-grade protein specifications for parenteral applications. Osaka-based beverage formulators are specifying UHT-treated protein concentrates with extended ambient stability.
Brazil
ANVISA regulatory modernization is opening pathways for whey protein hydrolysates in pediatric and geriatric medical foods. Animal feed producers are substituting soy concentrates with microbial proteins as novel ingredient pathways clarify. São Paulo and Minas Gerais processing facilities are retrofitting with enzymatic extraction systems to maintain export certification.
Global Functional Proteins Market Competitive Landscape
North American producers anchor one tier; European specialists hold differentiated positions in precision fermentation and dairy fractionation. The vendor base organizes around three strategic archetypes: diversified agribusiness conglomerates with oilseed and dairy processing scale, dedicated nutrition ingredient specialists with R&D intensity, and emerging biotech platforms leveraging microbial chassis. Competitive moves concentrate on long-term offtake contracting and GMP-compliant capacity expansion.
Within the diversified agribusiness tier, Archer Daniels Midland Company and Cargill occupy positions shaped by integrated oilseed processing infrastructure and Midwest supply chain density. Kerry Group plc exemplifies the flavor-protein integration specialist archetype, while Glanbia plc represents the dairy-derived nutrition platform model with Irish innovation center concentration. DSM and DuPont Nutrition sit within the biotechnology-enabled ingredient segment, though their strategic positioning reflects divergent heritage in microbial fermentation versus chemical processing.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Glanbia plc |
| Kerry Group plc |
| Roquette Frères |
| DuPont Nutrition |
| DSM |
| Fonterra Co-operative Group |
| Arla Foods |
| Others |
Supply & Pricing Matrix
Sports nutrition contract manufacturers in the US Midwest anchor procurement leverage through 24-36 month offtake agreements, locking in tiered pricing structures that stratify across pharmaceutical-grade isolates, food-grade concentrates, and feed-grade fractions.
Pricing Analysis
Capacity additions in Germany and Denmark are reshaping price floors for precision fermentation-derived isolates as microbial whey-identical proteins achieve cost parity with dairy fractions. Three-tier pricing structure across pharmaceutical certification, food-grade standard, and feed-grade economy levels differentiates batches by GMP compliance and documented bioactivity units. Cost compression in plant-derived concentrates is intensifying because Black Sea supply disruptions and fertilizer cost spikes squeeze organic pea and fava bean processors. Animal feed producers exhibit the highest price sensitivity due to volume scale and substitution elasticity, while pharmaceutical companies tolerate premium pricing for validated endotoxin control and pharmacopeial compliance.
Supply Chain Analysis
Freight costs for temperature-controlled whey isolate shipments from Ireland and New Zealand to North American contract manufacturers have become a decisive factor in supplier selection. Supply concentrates in the United States, Germany, and Ireland for dairy-derived fractions, while China and India anchor enzymatic processing capacity for pharmaceutical-grade isolates. Raw material flows draw from Midwest dairy cooperatives, Yangtze River Delta bioprocessing hubs, and Bavarian precision fermentation clusters. Single-source vulnerability persists for GMP-certified lactoferrin and glycomacropeptide equivalents until Danish and Singaporean bioreactor trains reach commercial scale. Distribution runs through long-term offtake contracting with tier-one finished goods producers rather than spot purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where procurement is shifting toward digestibility-validated isolates with human clinical trial backing, rewarding suppliers with substantiated bioactivity claims under FDA and EFSA frameworks.
For Market Incumbents: Hedge against precision fermentation displacement by deepening captive supply of bioactive peptide fractions through Irish and Bavarian innovation center expansion. Anchor plant-protein extraction economics through backward integration into oilseed crushing infrastructure across Minnesota and Iowa. Defend margin position against synthetic biology-derived amino acid blends by accelerating GMP-certified capacity for pharmaceutical partnerships. For New Entrants and Emerging Players: AI-driven protein structure prediction offers a technology-first wedge for rapid custom peptide prototyping targeting Boston and Basel pharmaceutical developers. Brazil's ANVISA regulatory modernization presents the most penetrable geography for whey hydrolysates in pediatric medical foods. Cell-free expression systems enable a contract research service model that bypasses the $200-400 million capex barrier for GMP fermentation facilities. For Investors and Strategic Acquirers: Mid-cap dairy fractionators with established GMP infrastructure are the most active acquirer targets for CPG conglomerates seeking supply security. The five-to-ten year viability window favors platforms with validated precision fermentation titers and regulatory approval precedents in multiple jurisdictions. Watch for EFSA novel food assessment timelines as the signal indicating which microbial chassis will secure first-mover advantage in European commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Danish and Singaporean contract manufacturers commission 100,000-liter bioreactor trains to serve CPG brand demand. |
| Regulatory Approval Pathway | EFSA novel food streamlining reduces capital lock-up periods for Munich and Berlin biotech clusters. |
| Long-term Supply Agreement | US Midwest sports nutrition brands secure 24-36 month offtake commitments for differentiated whey fractions. |
| Backward Integration | Cargill leverages oilseed processing footprint to anchor plant-protein extraction economics in Minnesota and Iowa. |
| Green Manufacturing Transition | German and Dutch facilities retrofit with supercritical CO2 systems to meet REACH and F-Gas Regulation compliance. |
Research Methodology
Bottom-up dietary supplement and clinical nutrition modeling reconciled against top-down precision fermentation capacity tracking forms the analytical core of this study. Primary interviews with bioprocess engineering directors, regulatory affairs leads at precision fermentation startups, sports nutrition procurement managers, and pharmaceutical formulation scientists combined with secondary validation from FDA protein quality labeling filings, EFSA novel food assessment registers, and NMPA biologically active substance registration databases. Trade data from Irish and New Zealand dairy export statistics, SEC 10-K disclosures from diversified agribusiness conglomerates, and customs records for whey isolate shipments triangulate supply-side estimates against demand-side consumption patterns.
Historical trendline analysis of whey processing capacity expansion, plant-protein extraction economics, and microbial fermentation titer improvements informed the projection framework across the analysis window. Segmentation dimensions modeled include enzymatic versus structural versus transport protein categories, pharmaceutical versus food versus feed application tiers, powder versus liquid versus concentrate form factors, and geographic regulatory clusters spanning FDA, EFSA, and NMPA jurisdictions. CAGRs derive from regression analysis of capacity utilization rates, approval timeline compressions, and substitution elasticity parameters for synthetic biology alternatives.
The model holds under stable regulatory classification for precision fermentation-derived proteins; deviation in jurisdiction-specific novel food determinations or digestibility labeling enforcement would shift commercialization timelines and capital allocation priorities. Stakeholders should weight assumptions against their own operating context and risk tolerance for bioprocess engineering talent scarcity and GMP facility certification delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market