
 Global Functional Foods Market | 2026-2036
Global Functional Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Functional Foods Market Analysis
Supermarket shelf space allocation for fortified products is narrowing as online retail platforms capture higher-margin direct-to-consumer sales. Nestlé S.A. leverages its pharmaceutical-grade manufacturing infrastructure to dominate clinical nutrition channels. Danone S.A. anchors its position through specialized fermentation capabilities in probiotic dairy. PepsiCo Inc. extends its beverage distribution network into functional hydration segments.
Functional foods are processed consumables containing bioactive compounds such as live microbial cultures, omega-3 fatty acids, or phytosterols at clinically relevant dosages, manufactured through controlled fermentation, microencapsulation, or cold-pressing to preserve therapeutic activity, with the primary purpose of delivering measurable physiological benefits beyond basic nutrition. Probiotics command the largest revenue pool due to established gut-health clinical evidence and refrigerated supply chain maturity, while omega fatty acids represent the fastest-expanding category driven by cardiovascular wellness positioning in aging populations. Digestive health applications sustain premium pricing power through physician endorsement, whereas immune support formulations compete on ingredient transparency and third-party certification.
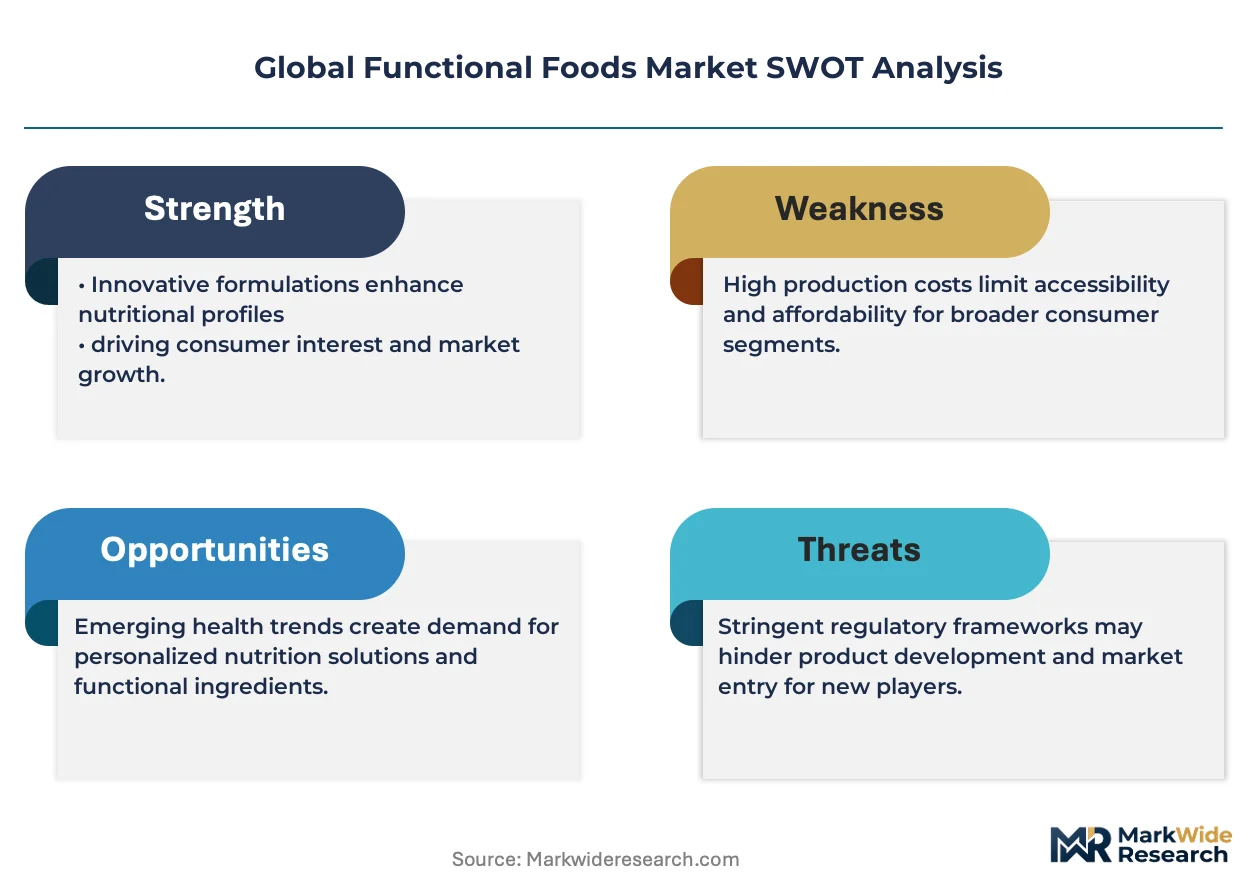
EFSA novel food assessments, FDA qualified health claims, and Japan's FOSHU regulatory framework collectively determine market access timelines and permissible efficacy messaging across jurisdictions. Compliance with EFSA's substantiation requirements demands human intervention studies that filter out unsubstantiated entrants and concentrate margin pools with established clinical trial sponsors. Stakeholders must monitor evolving probiotic strain-specific approval precedents and adapt R&D pipelines accordingly.
Market Dynamics
Clinical substantiation requirements under EFSA's novel food framework are filtering out unsubstantiated entrants and concentrating margin pools with established trial sponsors who possess pharmaceutical-grade manufacturing infrastructure.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined safety assessments for microbial biomass and plant extracts accelerate ingredient approvals across EU member states, reducing time-to-market for fermentation-derived bioactives.
- Amateur Sports Nutrition:Recreational athletes in Brazil's urban wellness corridors adopt protein-fortified and probiotic-enhanced recovery products, expanding addressable consumer base beyond professional segments.
- Microencapsulation Maturation:Cold-pressing and lipid-shell technologies preserve therapeutic activity of omega-3 fatty acids through gastric transit, enabling cardiovascular wellness positioning in aging populations.
Market Restraints
- Refrigerated Supply Chain Concentration:Probiotic viability demands cold-chain infrastructure that clusters distribution around São Paulo, Mumbai, and Frankfurt logistics hubs, limiting rural penetration.
- Fish Oil Input Volatility:Peruvian anchovy catch fluctuations and marine oil refining capacity constraints create raw material price instability for DHA/EPA concentrate producers.
- FOSHU Substantiation Burden:Japan's Ministry of Health, Labour and Welfare requires human intervention studies that extend approval timelines and exclude smaller R&D sponsors without clinical trial capabilities.
Strategic Opportunities
- Direct-to-Consumer Platforms:Online retail channels capture higher-margin sales of personalized microbiome testing kits paired with strain-specific probiotic subscriptions, bypassing supermarket shelf space contraction.
- Postbiotic Formulations:Heat-inactivated microbial metabolites circumvent refrigeration requirements and open shelf-stable applications in functional beverages and ambient snacks.
- PLI Scheme Alignment:India's production-linked incentive scheme for food processing infrastructure supports contract manufacturing scale-up for export-oriented probiotic dairy operations.
Industry Challenges
- Strain-Specific IP Complexity:Proprietary bacterial strain deposits and patent thickets around Lactobacillus and Bifidobacterium species create licensing friction for new market entrants.
- Third-Party Certification Backlogs:NSF International and Informed Sport testing queues extend go-to-market timelines for sports nutrition applications by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Functional Foods Market |
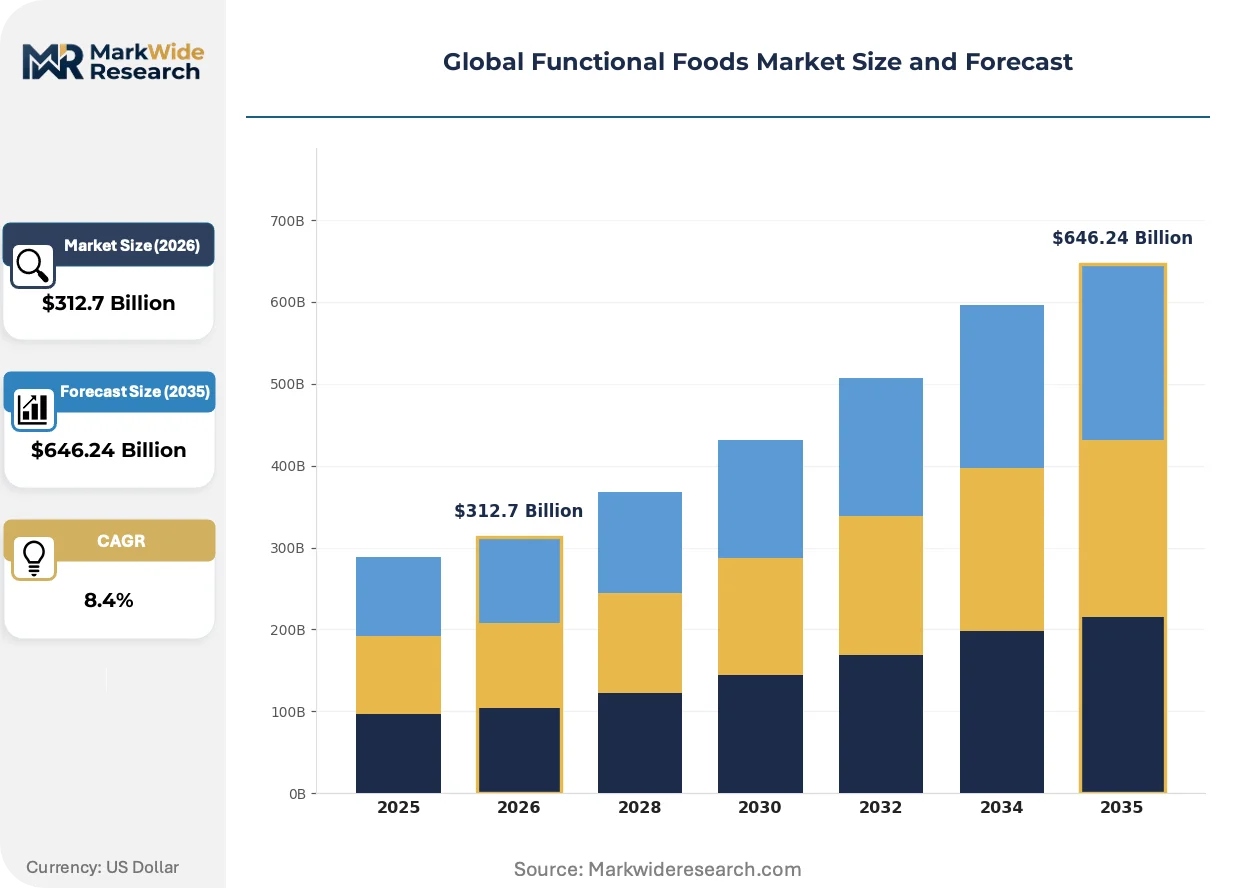
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prebiotics, Probiotics, Omega Fatty Acids, Plant Sterols Application: Weight Management, Heart Health, Immune Support, Digestive Health End User: Health-Conscious Consumers, Athletes, Elderly, Diabetics Distribution Channel: Supermarkets, Online Retail, Health Stores, Pharmacies |
| Companies Covered | Nestlé S.A., Danone S.A., PepsiCo Inc., General Mills, Inc., Kellogg Company, Glanbia Plc, Archer Daniels Midland Company, The Coca-Cola Company, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Functional Foods Market Emerging Trajectories
Bioactive delivery systems and regulatory science capabilities are separating scalable platforms from commodity ingredient suppliers, with clinical trial sponsorship emerging as the primary competitive moat.
Microencapsulation technology is migrating from pharmaceutical applications into functional food matrices, enabling lipid-shell protection of sensitive compounds through gastric transit. Sports nutrition manufacturers in Germany and Australia adopt these platforms to fortify ambient protein bars with live cultures previously limited to refrigerated formats. The shift compresses supply chain complexity for ambient distribution while expanding probiotic addressable markets beyond cold-chain dependent dairy.
EFSA's 2023 guidance on microbial biomass safety assessments tightens genotoxicity testing requirements for novel probiotic strains seeking EU market access. Fermentation specialists must now submit whole-genome sequencing data and antibiotic resistance profiling, raising R&D barriers for mid-tier ingredient suppliers. Strain-specific approval precedents established by Danish and Dutch trial sponsors are reshaping partnership dynamics between biotech developers and CPG formulators.
Physician endorsement programs for digestive health applications are displacing influencer-driven marketing in premium pricing tiers. Gastroenterology clinic networks in Switzerland and South Korea now stock pharmacist-recommended synbiotic formulations, creating parallel distribution channels distinct from mass retail. This certification-driven preference shift concentrates brand equity with sponsors of randomized controlled trials published in peer-reviewed journals.
Global Functional Foods Market Segmentation
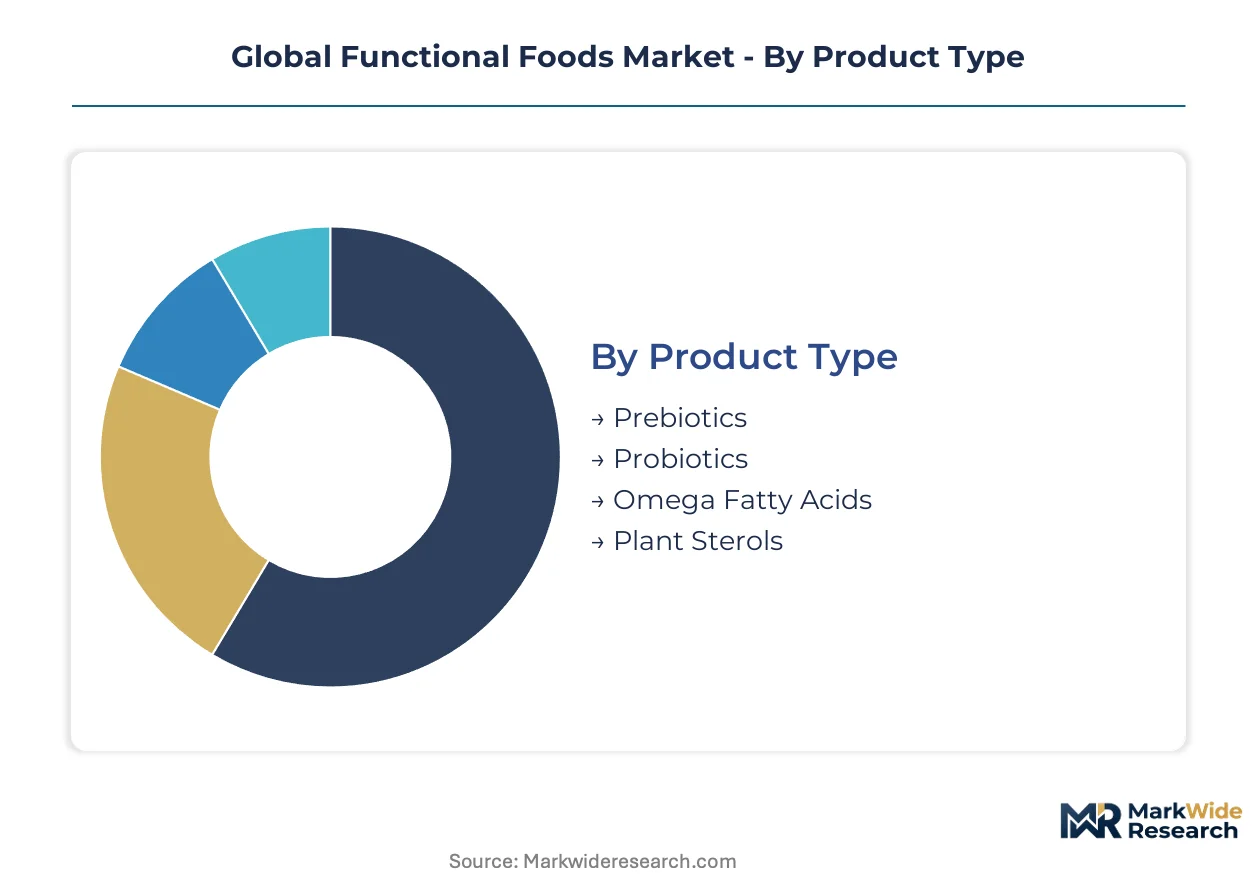
Functional foods markets fragment across bioactive compound categories, physiological applications, and consumer risk profiles that dictate formulation complexity and channel strategy. Segmentation clarity determines whether manufacturers pursue refrigerated probiotic dairy, ambient omega-3 fortification, or clinical nutrition partnerships.
Product Type:
Mature fermentation-derived categories dominate revenue pools while plant-extract segments accelerate through novel food approvals.
- Prebiotics:Non-digestible oligosaccharides—fructooligosaccharides, galactooligosaccharides, and inulin—selectively nourish beneficial colonic bacteria. German ingredient suppliers concentrate production around enzymatic synthesis from chicory root and beet sugar feedstocks.
- Probiotics:Live microbial cultures including Lactobacillus and Bifidobacterium species deliver measurable gut microbiome modulation at colony-forming unit thresholds. Swiss and Dutch clinical trial sponsors anchor physician endorsement networks through refrigerated synbiotic formulations.
- Omega Fatty Acids:DHA and EPA concentrates from marine and algal sources target cardiovascular and cognitive wellness positioning. Peruvian anchovy catch cycles and algal fermentation capacity in Germany constrain input cost stability.
- Plant Sterols:Phytosterol and phytostanol esters derived from tall oil and vegetable oils inhibit intestinal cholesterol absorption. Finnish and Swedish forestry-chemical integration secures tall oil sterol supply for EU fortification applications.
Probiotics retain volume leadership; omega fatty acids hold the steepest expansion curve.
Application:
Physiological benefit claims stratify across regulatory substantiation burden and pricing power.
- Weight Management:Protein fortification and satiety-enhancing fiber blends target metabolic wellness. Brazilian urban wellness corridors drive adoption of meal-replacement formats with glycemic control positioning.
- Heart Health:EFSA-approved cholesterol reduction claims for plant sterol doses anchor clinical credibility. Japanese FOSHU substantiation requirements extend approval timelines for novel bioactive entrants.
- Immune Support:Beta-glucans, zinc fortification, and specific probiotic strains compete on third-party certification transparency. South Korean pharmacist-recommended formulations displace influencer marketing in premium tiers.
- Digestive Health:Established gut-health clinical evidence sustains physician endorsement and synbiotic premium pricing. Swiss gastroenterology clinic networks stock trial-backed formulations distinct from mass retail channels.
Digestive health commands margin premiums; immune support gains share fastest through certification-driven consumer preference.
End User:
Consumer risk profiles determine formulation specificity, dosing precision, and distribution channel selection.
- Health-Conscious Consumers:General wellness seekers purchase fortified beverages and ambient snacks through supermarkets and online platforms. Direct-to-consumer microbiome testing subscriptions pair with strain-specific probiotic recommendations.
- Athletes:Amateur recreational athletes in Brazil and Germany adopt protein-fortified recovery products and probiotic-enhanced hydration formats. NSF International and Informed Sport certification queues extend sports nutrition go-to-market timelines.
- Elderly:Aging populations in Japan and Switzerland drive cardiovascular wellness positioning for omega-3 and plant sterol fortification. Texture-modified formats address swallowing difficulty in clinical nutrition segments.
- Diabetics:Glycemic control formulations with specific fiber blends and low-glycemic carbohydrate profiles target metabolic disease management. India's FSSAI regulatory framework governs medical food positioning for diabetic nutrition.
Health-conscious consumers anchor volume; athletes represent the most rapidly expanding addressable base.
Distribution Channel:
Channel economics reshape competitive positioning as shelf space contracts and direct relationships proliferate.
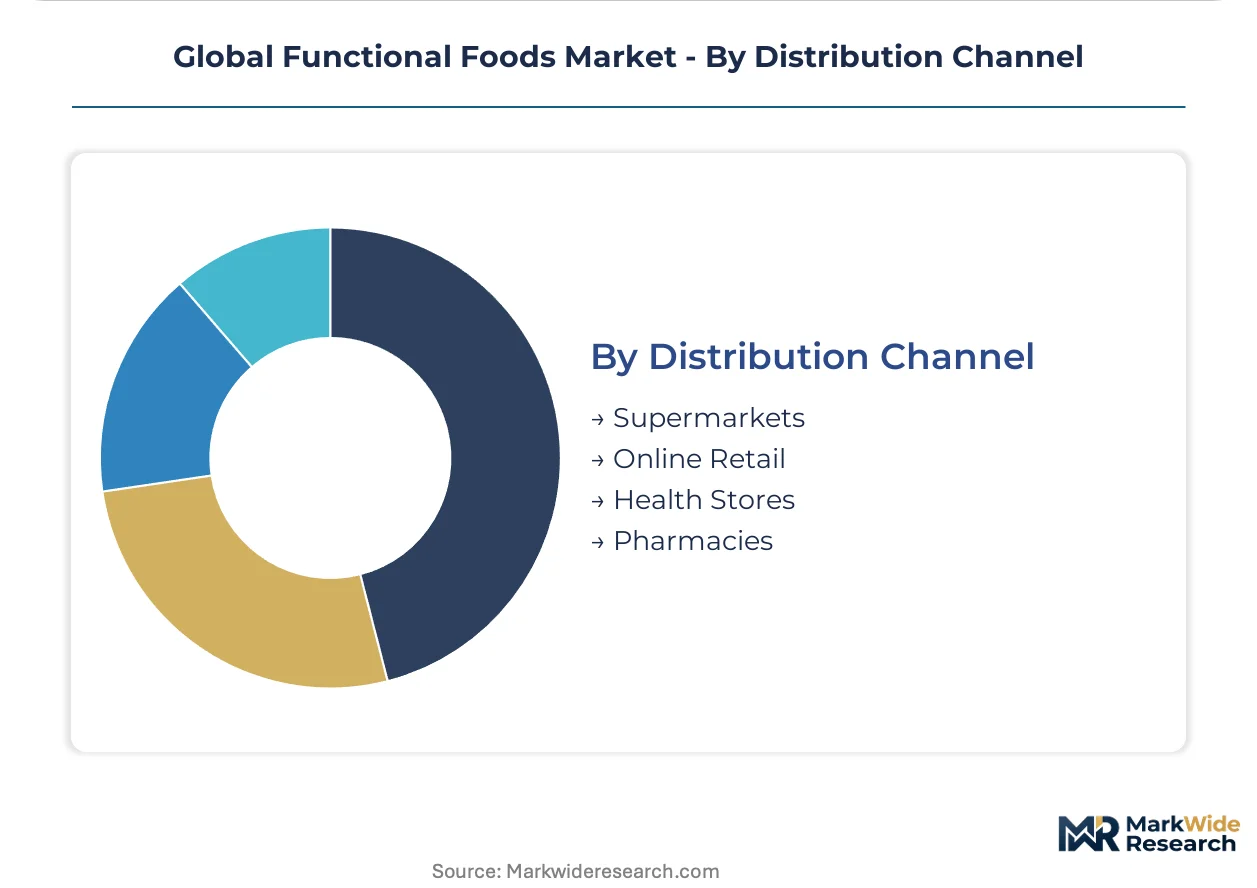
- Supermarkets:Refrigerated dairy cases and ambient fortified aisles face narrowing shelf space allocation. German and Brazilian retail consolidation pressures supplier margin terms.
- Online Retail:Higher-margin direct-to-consumer sales capture personalized subscription models and microbiome testing integration. Cold-chain logistics partnerships with São Paulo and Frankfurt hubs enable probiotic viability guarantees.
- Health Stores:Specialty retailers emphasize third-party certified and organic-positioned formats. Australian and Swiss health store networks prioritize local fermentation-derived probiotic suppliers.
- Pharmacies:Pharmacist-recommended synbiotics and clinical nutrition products command premium pricing through healthcare professional endorsement. South Korean and Swiss pharmacy chains stock trial-backed digestive health formulations.
Supermarkets retain transaction volume leadership; online retail posts the steepest value growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics corridors anchor European probiotic distribution, while Brazil's BR-116 highway network funnels fortified products from São Paulo's manufacturing belt into urban wellness corridors.
United States
FDA qualified health claims for soluble fiber and plant sterols drive cardiovascular wellness positioning among aging populations. The agency's enforcement discretion letters permit limited structure-function claims for probiotics. Chicago and Minneapolis logistics clusters concentrate refrigerated distribution infrastructure for live culture dairy.
Germany
EFSA novel food assessments for microbial biomass filter ingredient approvals through pharmaceutical-grade manufacturing standards. The country's enzymatic synthesis capabilities from chicory root feedstocks dominate prebiotic oligosaccharide supply. Bavarian fermentation specialists anchor clinical trial sponsorship networks for synbiotic formulations.
Brazil
ANVISA's consolidated health food regulations govern probiotic strain registration and glycemic control claims for diabetic nutrition. São Paulo's urban wellness corridors concentrate amateur athlete demand for protein-fortified recovery products. The PLI scheme alignment supports contract manufacturing scale-up for export-oriented operations.
Japan
FOSHU substantiation requirements from the Ministry of Health, Labour and Welfare demand human intervention studies that extend approval timelines. Tokyo and Osaka pharmacy chains stock trial-backed digestive health formulations with physician endorsement. Aging populations drive texture-modified clinical nutrition segments.
India
FSSAI regulatory frameworks govern medical food positioning for metabolic disease management. Maharashtra and Gujarat contract manufacturing clusters scale probiotic dairy operations under production-linked incentive schemes. Mumbai's logistics hubs enable cold-chain viability guarantees for refrigerated distribution.
Global Functional Foods Market Vendor Landscape
On the supply side, the industry is consolidating around pharmaceutical-grade manufacturing infrastructure and clinical trial sponsorship capabilities. Tiered competitive positioning separates fermentation-derived ingredient specialists from beverage distribution network extenders. Three archetypes dominate: diversified nutrition conglomerates with pharmaceutical manufacturing assets, dairy-centric probiotic formulators with specialized fermentation capabilities, and beverage network operators expanding into functional hydration. Competitive moves concentrate on M&A for strain-specific IP portfolios and strategic partnerships for microbiome testing platform integration.
Within the diversified nutrition tier, Nestlé S.A. and Danone S.A. represent archetypal positioning around pharmaceutical-grade infrastructure and specialized fermentation capabilities respectively. PepsiCo Inc. occupies a distinct vector as a beverage network operator extending distribution into functional hydration segments. These three Swiss, French, and US-based entities exemplify how manufacturing asset profiles and channel control determine margin capture in clinically substantiated product categories.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| PepsiCo Inc. |
| General Mills, Inc. |
| Kellogg Company |
| Glanbia Plc |
| Archer Daniels Midland Company |
| The Coca-Cola Company |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
São Paulo's probiotic manufacturing belt anchors global fermentation capacity, and its cold-chain logistics partnerships with Frankfurt and Mumbai determine downstream margin capture for refrigerated synbiotic formulations. Pricing power concentrates with sponsors of EFSA-compliant clinical trials who command physician endorsement premiums, while commodity-grade plant sterol suppliers face compression from tall oil input volatility.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade clinical nutrition from mass-market fortified beverages. Three-tier pricing stratifies across premium physician-endorsed synbiotics, standard refrigerated dairy probiotics, and economy ambient fortification. Price differentiation hinges on EFSA novel food approval status and third-party certification grade. Cost compression in the economy tier intensifies as Brazilian and Indian contract manufacturers scale fermentation capacity. Amateur athletes in Germany and Brazil exhibit lowest price sensitivity due to NSF certification requirements, while health-conscious supermarket shoppers drive standard-tier negotiation.
Supply Chain Analysis
Export-control regimes limiting algal omega-3 technology flows constrain DHA/EPA concentrate supply diversification. Manufacturing gravity centers on Germany for enzymatic prebiotic synthesis, Switzerland for pharmaceutical-grade probiotic fermentation, and Peru for marine oil refining. Raw material dependencies include Peruvian anchovy catch cycles, chicory root feedstocks from Belgian suppliers, and tall oil derivatives from Nordic forestry operations. Single-source vulnerability runs through the Frankfurt-São Paulo refrigerated corridor for live culture viability. Distribution runs through direct-to-consumer platforms capturing subscription revenue alongside pharmacy and health store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional foods market is entering a cyclical recovery phase as EFSA's streamlined microbial biomass assessments reduce approval bottlenecks that constrained ingredient supply through the prior regulatory tightening cycle.
For Market Incumbents: Build clinical trial sponsorship moats by securing strain-specific IP deposits for Lactobacillus and Bifidobacterium species before patent thickets harden. Expand pharmaceutical-grade manufacturing capacity in Bavarian and Swiss fermentation clusters to capture physician endorsement premiums. Defensive consolidation through microbiome testing platform partnerships counters direct-to-consumer subscription entrants.
For New Entrants and Emerging Players: Rural India and secondary Brazilian cities beyond São Paulo's wellness corridors offer white-space penetration for ambient postbiotic formulations circumventing refrigeration requirements. Target India's PLI-aligned contract manufacturing for export-oriented probiotic dairy scale-up. Go-to-market leverage rests on pharmacist channel partnerships in South Korean and Swiss clinic networks displacing influencer-driven marketing.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory science play because EFSA novel food substantiation requirements filter out unsubstantiated entrants and concentrate margin pools with established trial sponsors. Acquisition targets include mid-tier fermentation specialists with pharmaceutical-grade infrastructure gaps and strain-specific IP portfolios. Watch for inflection when Japanese FOSHU approval timelines compress or EFSA genotoxicity testing requirements ease for postbiotic categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Sponsorship | EFSA-compliant human intervention studies anchor physician endorsement networks and premium pricing tiers. |
| Strain-Specific IP Acquisition | Proprietary bacterial deposits in international culture collections create licensing barriers against commodity competitors. |
| Direct-to-Consumer Platform Launch | Microbiome testing integration captures subscription revenue bypassing supermarket shelf space contraction. |
| Postbiotic Formulation Development | Heat-inactivated metabolites enable ambient distribution without refrigerated supply chain dependency. |
| Pharmacy Channel Partnership | Swiss and South Korean clinic networks stock trial-backed formulations at premium price points. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation technology directors, regulatory affairs specialists at EFSA and FDA, pharmacy chain procurement managers, and clinical nutrition brand managers, then refined through secondary validation against EFSA novel food assessment databases, FOSHU approval registries, customs trade data for omega-3 concentrate flows, and SEC filings from diversified nutrition conglomerates. Bottom-up segment sizing triangulated with top-down macroeconomic drivers across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling consumption patterns across bioactive compound categories, physiological application segments, consumer risk profiles, and distribution channel economics. CAGRs derived from segment-level growth trajectories calibrated to regulatory approval timelines, cold-chain infrastructure expansion rates, and amateur sports nutrition adoption curves. Inputs included EFSA assessment queue data, refrigerated logistics capacity buildouts in São Paulo and Mumbai, and third-party certification testing backlogs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algal omega-3 technology licensors or postbiotic platform entrants would shift outcomes. Material shifts in EFSA genotoxicity testing requirements, Peruvian anchovy catch regulations, or India's PLI scheme terms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Japan Functional Drinks Market