
 Instant Protein Beverages Market | 2026-2036
Instant Protein Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Protein Beverages Market Foresight
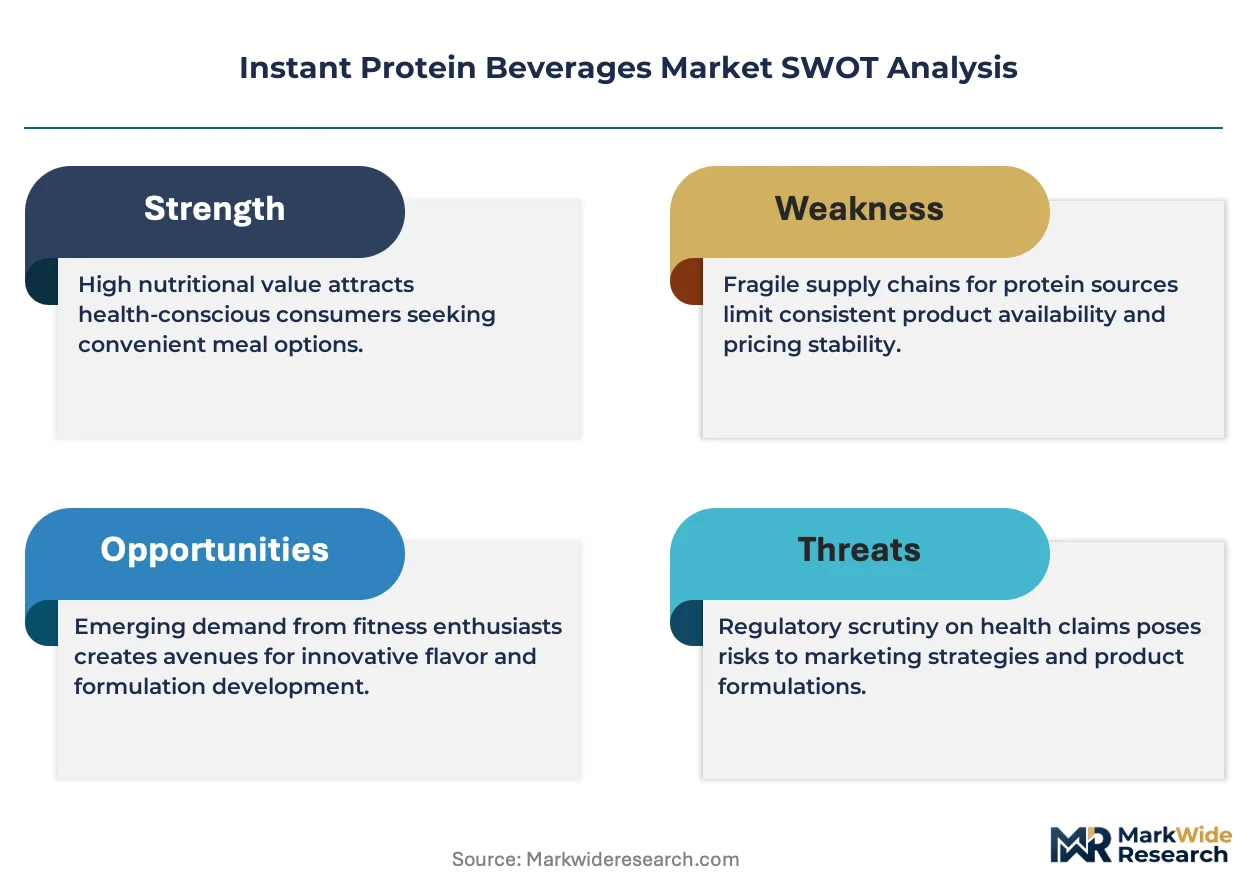
Post-workout recovery among fitness facility operators is pivoting toward shelf-stable, single-serve formats that eliminate refrigeration dependency. Abbott Laboratories leverages clinical credibility to anchor hospital discharge and senior nutrition channels. Glanbia competes through backward integration into dairy protein sourcing, securing supply continuity for whey-based formulations. PepsiCo extends beverage distribution infrastructure into convenience retail, occupying shelf space ahead of specialist entrants.
Instant protein beverages comprise water-dispersible protein concentrates or isolates, typically delivering 15–30 grams of protein per 250–500 ml serving through spray-dried or agglomerated powder matrices that reconstitute within 30 seconds. The category serves commercial purposes spanning athletic recovery, meal substitution, and clinical nutrition support where rapid preparation outweighs fresh-food preparation time. Ready-to-drink formats command premium shelf positioning and higher per-unit margins despite elevated logistics costs, while powder segments sustain volume leadership through lower price points and flavor customization. Whey protein dominates ingredient sourcing due to complete amino acid profiles and rapid absorption kinetics, though pea protein isolates gain traction among flexitarian consumers seeking reduced dairy dependency.
The US FDA enforces protein content labeling accuracy through nutrition facts panel regulations, while EFSA in Europe mandates novel food approvals for emerging plant protein sources such as insect or algae derivatives. ISO 22000 and FSSC 22000 certification increasingly function as market access prerequisites for contract manufacturing partnerships with multinational brands. Stakeholders must monitor evolving front-of-pack labeling schemes across jurisdictions, as traffic-light systems and Nutri-Score implementations directly influence consumer trial and repeat purchase behavior.
Market Dynamics
Post-workout recovery protocols among fitness facility operators are pivoting toward shelf-stable formats, compressing cold-chain dependency while expanding addressable retail channels beyond traditional refrigerated sets.
Growth Catalysts
- FDA protein labeling enforcement:Tightened verification requirements are pushing manufacturers toward third-party certification, elevating quality barriers that favor established producers with analytical capabilities.
- Convenience retail expansion:Beverage distributors are securing shelf space in gas stations and pharmacies, placing instant protein adjacent to impulse purchase categories with high foot traffic.
- Spray-drying agglomeration:Advanced powder engineering achieves sub-30-second reconstitution, eliminating clumping failures that previously deterred casual users from powder formats.
Market Restraints
- Whey protein input volatility:Dairy commodity price swings transmit directly into manufacturing cost structures, compressing margins during feed-cost inflation cycles without immediate pricing recourse.
- Supply concentration in US dairy belts:Whey isolate production clusters in Wisconsin and Idaho, creating geographic vulnerability to weather-driven milk supply disruptions.
- Pea protein technical limitations:Incomplete amino acid profiles and residual flavor compounds restrict substitution rates among performance-oriented consumers despite flexitarian demand growth.
Strategic Opportunities
- Hospital discharge nutrition protocols:Clinical channels remain underpenetrated by instant formats, presenting white space for shelf-stable alternatives to refrigerated medical foods.
- EFSA novel food approvals:Emerging protein sources including algae and insect derivatives await regulatory clearance, with first-mover advantage accruing to dossier-ready applicants.
- Direct-to-fitness-facility distribution:Bypassing retail markup through bulk dispensing systems in gym chains captures recurring consumption with reduced packaging costs.
Industry Challenges
- FSSC 22000 certification timelines:Contract manufacturers face 12-18 month approval cycles to qualify for multinational brand partnerships, constraining capacity expansion velocity.
- Flavor masking R&D bottlenecks:Pea and emerging plant proteins require sophisticated off-note suppression, stretching formulation teams thin across multiple base material transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Protein Beverages Market |
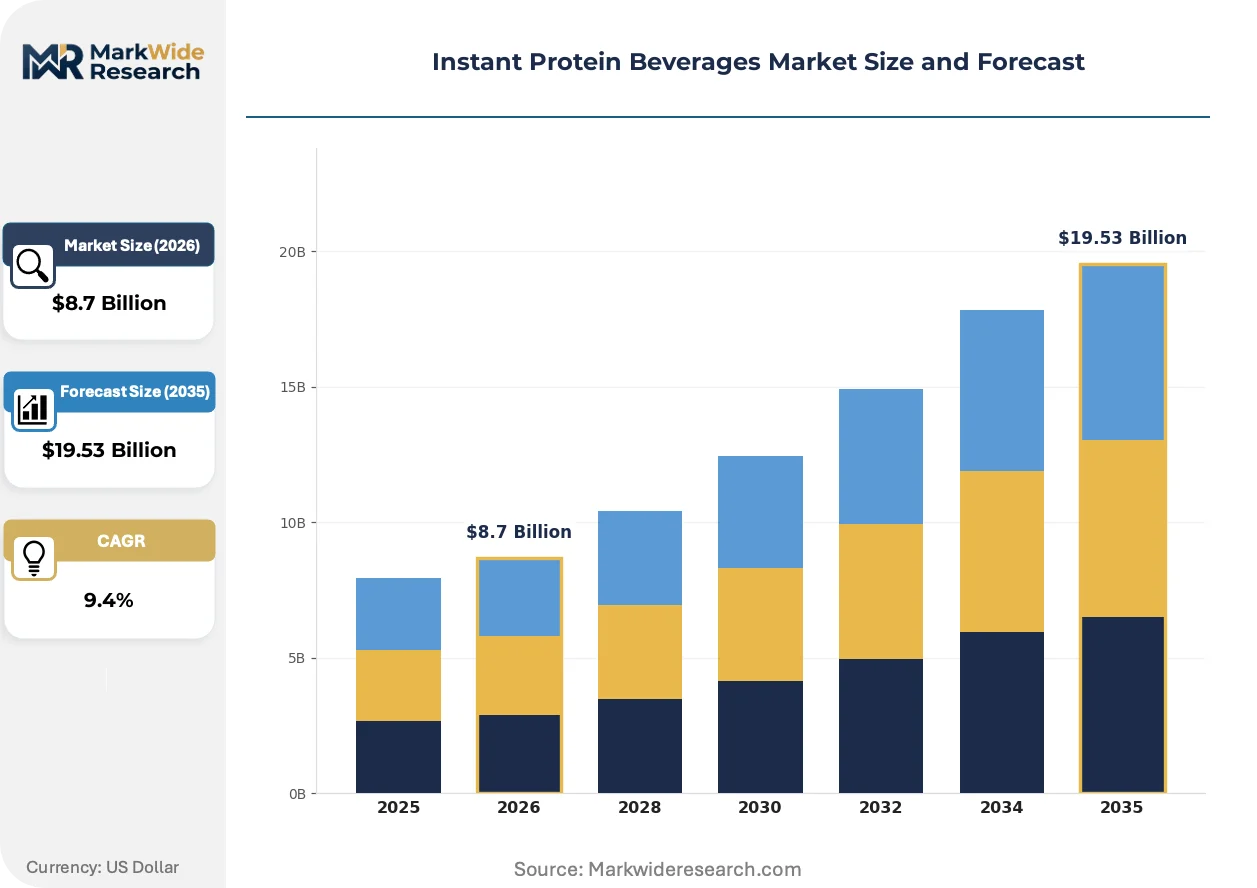
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shakes, Powders, Bars, Ready-to-Drink Ingredient Source: Whey, Soy, Pea, Casein Formulation Type: High Protein, Low Carb, Meal Replacement, Weight Management End User: Athletes, Gym Enthusiasts, Health-Conscious Consumers, Busy Professionals |
| Companies Covered | Nestlé, PepsiCo, Abbott Laboratories, Glanbia, The Coca-Cola Company, Danone, Amway, Herbalife Nutrition, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Protein Beverages Market Shifts & Advancements
Technology convergence between powder engineering and beverage formulation is dissolving format boundaries, enabling protein delivery systems that combine shelf stability with sensory performance previously exclusive to fresh products.
Cold-agnostic agglomeration technology is electrifying powder reconstitution performance. Modified lecithin coating systems and controlled particle porosity achieve complete dispersion in ambient water without mechanical mixing. Fitness facility operators are adopting these formats for locker room provisioning at accelerating rates. The technology is electrifying competition between ready-to-drink and powder segments by narrowing the convenience gap while preserving powder economics.
EFSA front-of-pack labeling mandates through Nutri-Score implementation are restructuring formulation priorities. Protein density thresholds now determine color-grade positioning, pressuring manufacturers to optimize protein-to-calorie ratios. Ready-to-drink formats in France and Germany face particular pressure as sugar content penalties offset protein benefits in scoring algorithms.
Subscription-based replenishment models are displacing single-unit trial purchases among repeat consumers. Direct channels capture consumption data that enables flavor rotation and timing optimization, while retail partners respond with loyalty program integrations. The United States exhibits the most advanced adoption, where convenience culture normalizes automated reordering for routine nutrition categories.
Instant Protein Beverages Market Segmentation
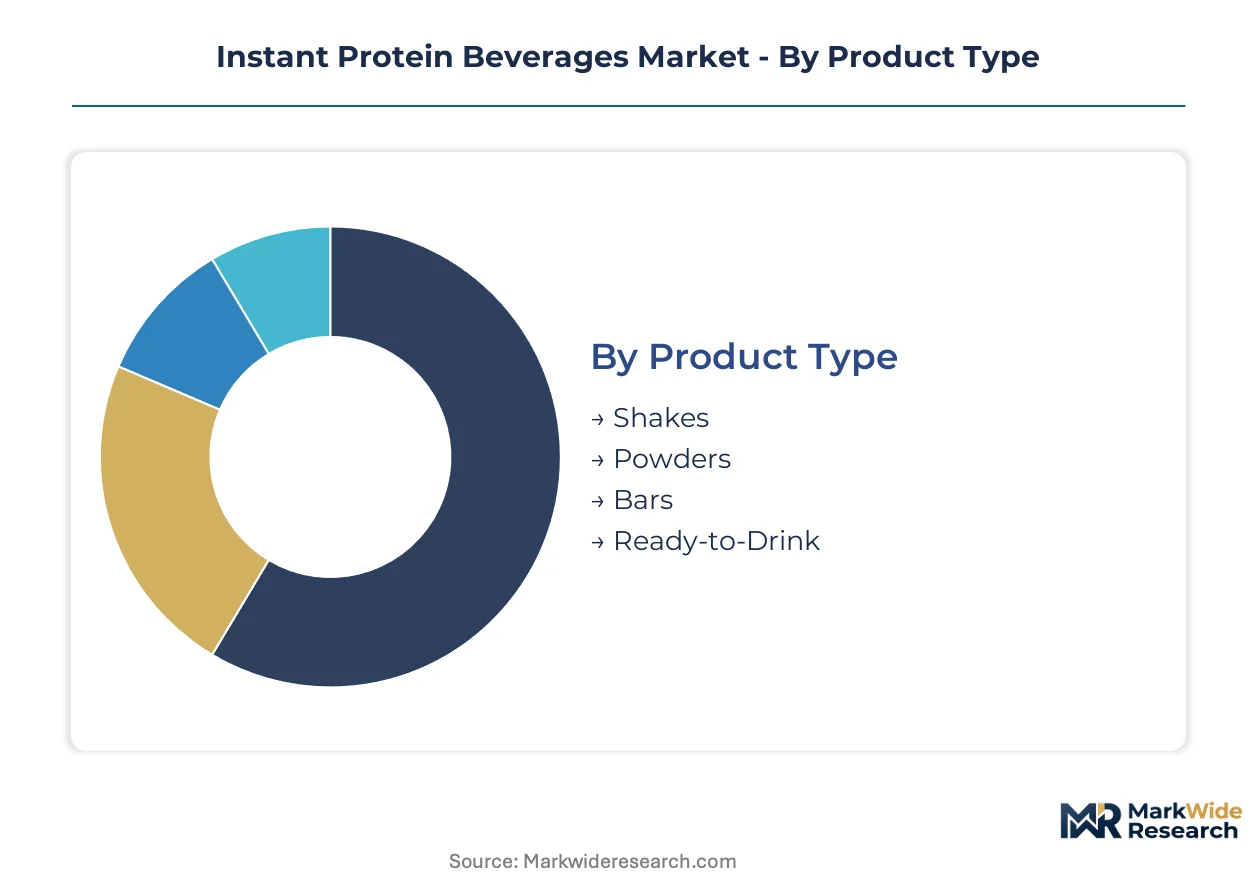
Instant protein beverages fragment across four intersecting dimensions that determine manufacturing investment, regulatory pathway, and distribution strategy. Product format dictates shelf-life engineering and cold-chain requirements, while ingredient sourcing shapes margin exposure to commodity cycles and certification complexity.
Product Type:
Capital intensity peaks with aseptic filling lines for liquid formats, whereas powder agglomeration requires spray-drying towers with lower per-unit throughput but faster product changeover.
- Shakes:Pre-mixed emulsions stabilized by hydrocolloids and phosphates, typically requiring refrigerated distribution or UHT processing for ambient stability. Demand concentrates in hospital discharge protocols and senior nutrition programs where preparation barriers exclude powder formats.
- Powders:Spray-dried or agglomerated protein matrices achieving 15-30 gram protein per 30-gram serving through controlled particle porosity. Fitness facility operators are adopting locker-room dispensing systems for these formats, eliminating single-use packaging while preserving consumer control over dilution ratios.
- Bars:Extruded or cold-pressed matrices combining protein with binding syrups and lipid coatings for structural integrity.
- Ready-to-Drink:Aseptically processed beverages in multilayer PET or aluminum formats, commanding premium shelf positioning in convenience retail.
Most installed capacity flows through Powders. Expansion is steepest in Ready-to-Drink.
Ingredient Source:
Supply security and price volatility separate these segments, with dairy-derived inputs tethered to feed-cost inflation while plant proteins face novel food regulatory timelines.
- Whey:Complete amino acid profile with rapid absorption kinetics, sourced as concentrate or isolate from cheese production streams. Production clusters in Wisconsin and Idaho create geographic concentration risk during drought-driven milk supply disruptions.
- Soy:Cost-competitive complete protein with established GRAS status in the US, though allergen labeling requirements and phytoestrogen concerns limit penetration in pediatric and clinical segments.
- Pea:Isolates from yellow split peas gaining traction among flexitarian consumers, constrained by methionine deficiency and residual grassy off-notes requiring sophisticated flavor masking.
- Casein:Slow-digesting micellar structures enabling sustained amino acid release, preferred in overnight recovery formulations and medical foods for sarcopenia management.
Ingredient sourcing is consolidating around Whey for performance applications. Pea is climbing the fastest among emerging alternatives awaiting EFSA novel food dossier resolutions.
Formulation Type:
Margin structure varies with clinical validation requirements and reimbursement eligibility, separating medical nutrition from lifestyle positioning.
- High Protein:Formulations delivering 25-40 grams protein per serving through protein fortification beyond base matrix, targeting strength athletes and post-surgical recovery protocols.
- Low Carb:Ketogenic-compliant profiles with sub-5 gram net carbohydrates, positioned for metabolic management and weight loss maintenance.
- Meal Replacement:Nutritionally complete profiles meeting micronutrient thresholds for substitution of full meals, requiring vitamin and mineral premix integration.
- Weight Management:Calorie-controlled formats with appetite-modulating fiber inclusions, positioned for clinical obesity protocols and consumer self-directed dieting.
Meal Replacement captures the most shelf space in pharmacy channels. High Protein is gaining share fastest among gym-based subscription models.
End User:
Channel strategy diverges sharply across these segments, from institutional procurement in athletic programs to impulse retail for time-constrained professionals.
- Athletes:Competitive and recreational competitors with performance-validated dosing requirements, served through specialty retail and direct-to-team distribution.
- Gym Enthusiasts:Regular fitness facility attendees prioritizing post-workout recovery timing, driving adoption of locker-room dispensing and subscription replenishment.
- Health-Conscious Consumers:Wellness-oriented purchasers seeking protein fortification for general nutrition, sensitive to clean-label positioning and sustainability claims.
- Busy Professionals:Time-constrained white-collar workers substituting meals during travel or compressed schedules, purchasing through convenience retail and airport concessions.
Gym Enthusiasts generate the highest purchase frequency. Busy Professionals are expanding most quickly as hybrid work patterns normalize on-the-go nutrition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as manufacturers relocate powder agglomeration capacity toward jurisdictions with streamlined novel-food approval pathways. Cost-of-compliance gaps between the FDA's GRAS self-affirmation and EFSA's centralized authorization are accelerating facility investment decisions.
United States
Fitness facility operators and convenience retail chains drive powder and ready-to-drink consumption across California, Texas, and Florida. The FDA enforces protein labeling accuracy through nutrition facts panel regulations, pushing manufacturers toward third-party certification. Wisconsin and Idaho host concentrated whey isolate production clusters vulnerable to drought-driven milk supply disruptions.
Germany
Gym chains and pharmacy channels sustain strong demand for meal replacement and clinical nutrition formats. EFSA mandates novel food approvals for emerging plant protein sources, with Nutri-Score front-of-pack labeling pressuring protein-to-calorie ratio optimization. Bavaria hosts spray-drying equipment manufacturing and dairy processing infrastructure serving Central European distribution.
China
Urban professional demand for portable nutrition accelerates ready-to-drink adoption in Shanghai, Beijing, and Shenzhen. SAMR oversees protein content labeling under GB standards, while dairy import dependence creates formulation flexibility toward domestic soy and pea sourcing. Yangtze River Delta clusters concentrate contract manufacturing capacity for Asia-Pacific brand partners.
Brazil
Sports nutrition normalization among gym enthusiasts expands addressable consumer base beyond elite athletes. ANVISA regulates protein supplement claims and novel ingredient safety assessments, with approval timelines influencing product launch sequencing. São Paulo anchors distribution infrastructure serving Mercosur markets with shelf-stable powder formats.
United Kingdom
Subscription replenishment models penetrate London and Southeast England professional demographics fastest. Post-Brexit regulatory divergence from EFSA creates parallel approval requirements for novel proteins, increasing compliance overhead for pan-European launches. Midlands manufacturing corridors host powder blending and packaging operations serving domestic and Irish retail channels.
Instant Protein Beverages Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ready-to-drink formats consolidating around beverage multinationals while powder categories sustain fragmentation. The vendor base organizes into three tiers: global nutrition conglomerates with clinical credibility, dairy cooperatives with backward integration into protein sourcing, and flexitarian-focused challengers betting on plant protein transitions. Dominant competitive moves include M&A to secure novel protein technology pipelines and capacity expansion into spray-drying agglomeration serving fitness facility direct distribution.
Among diversified nutrition conglomerates, Nestlé and Abbott Laboratories occupy positions spanning clinical and lifestyle channels, with the former leveraging global beverage infrastructure and the latter anchoring hospital discharge protocols. PepsiCo exemplifies beverage-led expansion into convenience retail shelf space. These three represent contrasting archetypes: Nestlé the packaged goods integrator, Abbott the clinical credibility specialist, and PepsiCo the distribution infrastructure deployer.
| Leading Market Players |
|---|
| Nestlé |
| PepsiCo |
| Abbott Laboratories |
| Glanbia |
| The Coca-Cola Company |
| Danone |
| Amway |
| Herbalife Nutrition |
| Arla Foods |
| Others |
Supply & Pricing Matrix
Whey protein futures on the Chicago Mercantile Exchange cascade through manufacturing cost structures into three-tier pricing stratification across premium isolate, standard concentrate, and economy blend tiers. Fitness facility operators and hospital procurement committees face divergent margin pressures as dairy commodity volatility transmits unevenly across shelf-stable powder and refrigerated ready-to-drink formats.
Pricing Analysis
Distributor markup layers compress as direct-to-fitness-facility bulk dispensing displaces retail intermediation. Price differentiation separates third-party certified NSF Sport formulations from self-affirmed GRAS tiers, with volume scale and flavor customization depth as secondary drivers. Pricing pressure intensifies in ready-to-drink segments as beverage multinationals leverage existing route-to-market infrastructure. Hospital discharge protocols exhibit lowest price sensitivity due to reimbursement eligibility, while convenience retail trial purchasers demonstrate highest elasticity.
Supply Chain Analysis
FSSC 22000 and ISO 22000 certification gating constrains contract manufacturer qualification timelines to 12-18 months, elevating switching costs for multinational brand partnerships. Geographic supply concentration clusters in Wisconsin and Idaho for whey isolate, with spray-drying equipment manufacturing anchored in Germany and China. Raw material dependencies center on dairy milk streams, pea protein isolates from Canadian prairie processing, and modified lecithin emulsifiers. Single-source vulnerability runs through drought-exposed US dairy belts. Distribution runs through beverage distributor networks for ready-to-drink, fitness facility direct channels for powder, and pharmacy wholesalers for clinical nutrition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in spray-drying agglomeration technology adoption and clinical channel premiumization, with cold-chain elimination driving cost-down capture across fitness facility direct distribution.
For Market Incumbents: Anticipate pea protein substitution pressure by securing backward integration into dairy protein sourcing and accelerating FSSC 22000 certification coverage across contract manufacturing networks. Defend hospital discharge channel positioning through clinical validation investments that emerging plant protein challengers cannot replicate without multi-year dossier timelines. Prioritize spray-drying capacity addition in jurisdictions with streamlined novel food approval pathways to outpace regulatory arbitrage by flexitarian-focused entrants. For New Entrants and Emerging Players: EFSA novel food approval pathways in Europe open a window for algae and insect protein first-movers with dossier-ready applications. Target hospital discharge nutrition protocols as the most underpenetrated white space, where refrigerated medical food incumbents face shelf-stable format displacement vulnerability. Pursue direct-to-fitness-facility bulk dispensing partnerships as the lowest customer acquisition cost channel, bypassing retail slotting fee barriers that beverage multinationals dominate. For Investors and Strategic Acquirers: Asymmetric upside sits with spray-drying agglomeration technology specialists and EFSA dossier-ready novel protein developers across a multi-year regulatory clearance horizon. Acquisition candidates with captive dairy protein supply or clinical nutrition reimbursement pathways offer defensive cash flow profiles. Watch EFSA novel food approval announcements as the critical inflection signal for plant protein substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Spray-Drying Agglomeration Capacity Expansion | Cold-agnostic powder engineering narrows the convenience gap with ready-to-drink formats while preserving margin structures. |
| EFSA Novel Food Dossier Submission | First-mover clearance for algae or insect protein isolates unlocks premium positioning ahead of regulatory parity. |
| Fitness Facility Direct Distribution Partnership | Bypassing retail markup through locker-room dispensing systems captures recurring consumption with reduced packaging costs. |
| Clinical Nutrition Reimbursement Pathway Development | Shelf-stable hospital discharge formats displace refrigerated medical foods where preparation barriers exclude powder alternatives. |
| Third-Party Certification Investment | NSF Sport and Informed Choice verification satisfies FDA enforcement pressure and differentiates from uncertified competitors. |
Research Methodology
Multiple input streams — executive interviews with spray-drying equipment manufacturers, procurement directors at fitness facility chains, and regulatory affairs leads at dairy cooperatives — were reconciled against FDA GRAS notification databases, EFSA novel food register entries, and customs trade data on whey protein concentrate flows. Secondary validation drew from FSSC 22000 certification body disclosures, hospital formulary databases, and Nielsen retail audit data. Bottom-up facility capacity modeling and top-down consumption elasticity estimates were triangulated to cross-verify volume assumptions.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling spanning product format, ingredient source, formulation type, and end-user archetype. CAGRs were derived from elasticity-adjusted penetration curves and per-capita consumption benchmarks. Forecast inputs incorporated spray-drying technology adoption rates, EFSA approval timeline distributions, and fitness facility operator procurement shift patterns.
Revisions become necessary when EFSA novel food approval timelines extend beyond baseline assumptions, dairy commodity price volatility exceeds historical bands, or FDA labeling enforcement intensity shifts materially. Deviation in certification body capacity constraints or drought-driven milk supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Keto Ice Cream Market