
 Japan Functional Drinks Market | 2026-2036
Japan Functional Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Functional Drinks Market Intelligence
Single-serve functional shot formats is recalibrating buyer choice across convenience channels, shifting preference away from multi-serve bottles toward portable, occasion-specific consumption. Kirin Holdings leverages its pharmaceutical heritage to anchor credibility in condition-specific formulations. Suntory Beverage & Food Ltd. sustains category leadership through deep channel control in vending and convenience retail. Otsuka Pharmaceutical differentiates by occupying the medical-nutrition boundary with clinically positioned electrolyte and amino acid products.
Japan functional drinks comprise non-alcoholic beverages formulated with bioactive compounds—vitamins, amino acids, probiotics, or natural extracts—engineered to deliver physiological benefits beyond basic hydration, typically standardized at specific efficacious doses validated for claims under national labeling frameworks. Sports drinks retain mature volume dominance through established hydration protocols among fitness enthusiasts and amateur athletes, while nutraceutical beverages represent the fastest-expanding margin pool as older adults seek targeted cognitive and joint-health solutions. Probiotic ingredient types command premium positioning due to Yakult Honsha's decades-long consumer education legacy and the country's entrenched gut-health culture.
PMDA oversight of pharmaceutical-adjacent claims and METI's Food with Function Claims framework jointly shape product development pathways, with the latter enabling faster market entry for science-backed functional statements compared to full health-claim approval processes. JIS standards for beverage safety and quality testing further constrain formulation flexibility but reinforce export credibility for Japanese manufacturers. Stakeholders must monitor evolving FFC claim categories and ingredient-specific safety reviews to anticipate which functional territories will open or constrict.
Market Dynamics
METI's Food with Function Claims system compresses product development cycles by bypassing full pharmaceutical approval pathways, while aging demographics concentrate demand for condition-specific nutraceutical formulations targeting mobility and cognitive support.
Growth Catalysts
- FFC Framework Acceleration:METI's streamlined claims process reduces time-to-market for science-backed functional beverages compared to PMDA's full pharmaceutical review, incentivizing R&D investment in validated bioactive formulations.
- Urban Health Consciousness:Consumers in Tokyo and Osaka prioritize preventive wellness solutions, creating sustained pull for probiotic and amino acid beverages with demonstrable physiological benefits.
- Gut-Health Cultural Embeddedness:Decades of consumer education around fermented foods and microbiome science normalize premium pricing for live-culture functional drinks across all adult age cohorts.
Market Restraints
- Ingredient Supply Concentration:Specialized probiotic strain production clusters with a limited set of domestic biotechnology suppliers, creating vulnerability to capacity constraints and quality variability.
- JIS Compliance Burden:Mandatory beverage safety and quality testing standards impose fixed formulation costs that disadvantage smaller entrants lacking scale economies in laboratory validation.
- Pharmaceutical Adjacency Risk:PMDA oversight of condition-specific claims creates regulatory uncertainty at the boundary between functional foods and medical nutrition, chilling investment in high-efficacy formulations.
Strategic Opportunities
- Single-Serve Format Expansion:Portable shot-sized packaging captures occasion-specific consumption moments in convenience channels, displacing multi-serve bottles among time-constrained urban professionals.
- Silver Economy Deepening:Japan's super-aged population structure opens white space for beverages targeting sarcopenia prevention, bone density maintenance, and mild cognitive impairment support.
- Export Credibility Leverage:JIS certification and METI-backed FFC validation create differentiated positioning in Southeast Asian markets seeking trusted Japanese functional food imports.
Industry Challenges
- Clinical Validation Talent Scarcity:Shortage of researchers trained in both food science and human intervention study design slows evidence generation for novel functional claims.
- Legacy Vending Integration:Refrigerated supply chain requirements for live-culture products conflict with ambient-temperature vending infrastructure dominating Japanese beverage distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Functional Drinks Market |
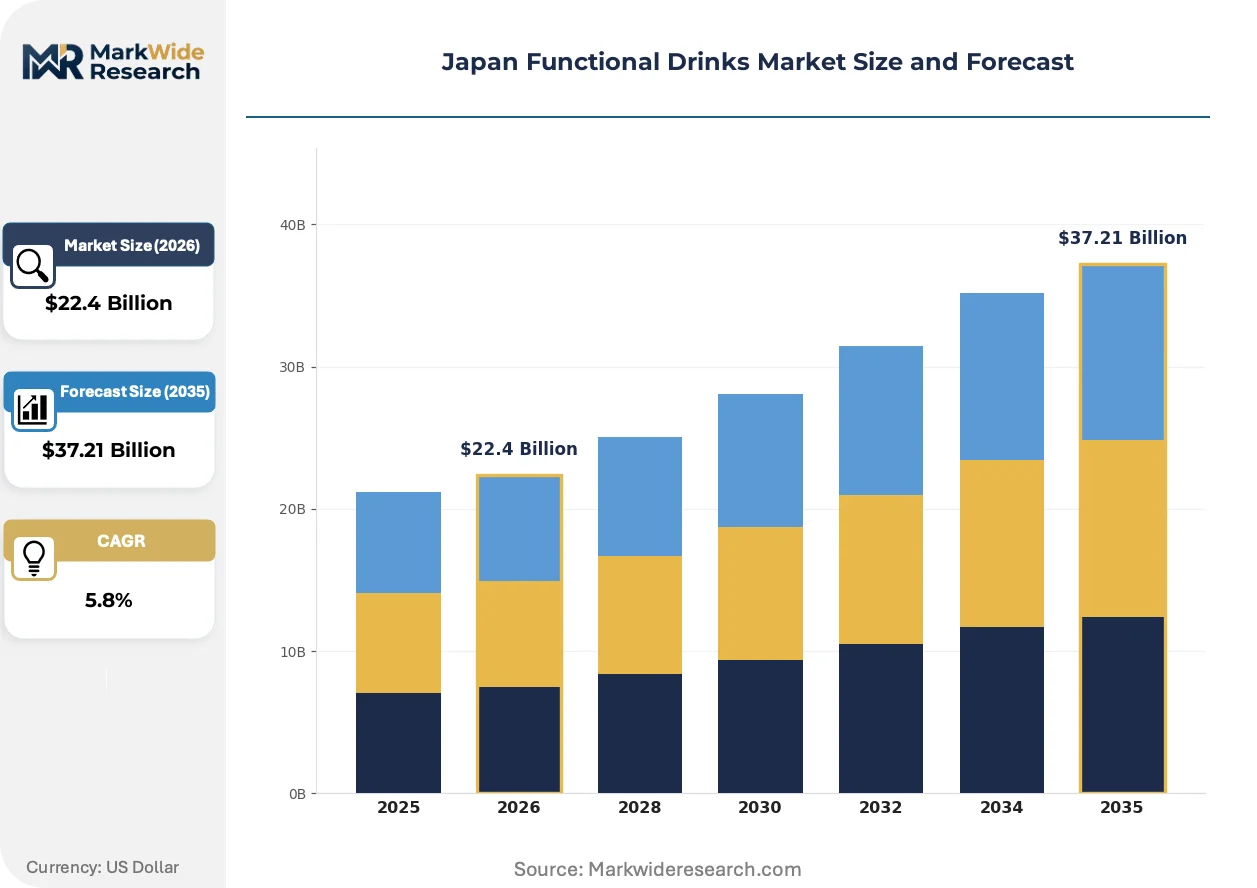
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $37.21 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Drinks, Nutraceutical Beverages, Herbal Infusions End User: Fitness Enthusiasts, Health-Conscious Consumers, Older Adults, Students Ingredient Type: Vitamins, Amino Acids, Probiotics, Natural Extracts Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores |
| Companies Covered | Kirin Holdings, Coca-Cola Bottlers Japan Inc., Suntory Beverage & Food Ltd., Otsuka Pharmaceutical, Taisho Pharmaceutical Co. Ltd., Asahi Soft Drinks Co. Ltd., ITO EN, Monster Energy, Yakult Honsha, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Functional Drinks Market Strategic Shifts & Innovations
Functional beverage innovation in Japan converges on precision nutrition, with formulation science and delivery mechanisms advancing in parallel to match specific physiological targets with validated bioactive dosing.
Microencapsulation technology for probiotic stability is consolidating shelf-life performance across ambient retail channels. Manufacturers adopting this process expand distribution beyond refrigerated convenience stores into vending machines and pharmacy shelves. The technology is compressing the historical trade-off between live-culture efficacy and logistical flexibility that constrained market penetration.
PMDA's evolving guidance on pharmaceutical-adjacent claims is tightening the evidentiary threshold for condition-specific marketing. Beverage developers must now commission human intervention studies meeting medical-nutrition standards to support cognitive or mobility benefit statements. Older adult-targeted nutraceutical segments face the steepest compliance cost escalation as claims migrate toward clinical positioning.
Channel disintermediation through direct-to-consumer subscription models is fragmenting traditional convenience retail dominance. Urban professionals in Tokyo and Osaka increasingly replenish personalized functional shot regimens via automated delivery rather than vending purchase. Pharmacy chains and specialized wellness platforms capture disproportionate growth in this behavioral shift away from impulse-driven single-serve acquisition.
Japan Functional Drinks Market Segmentation
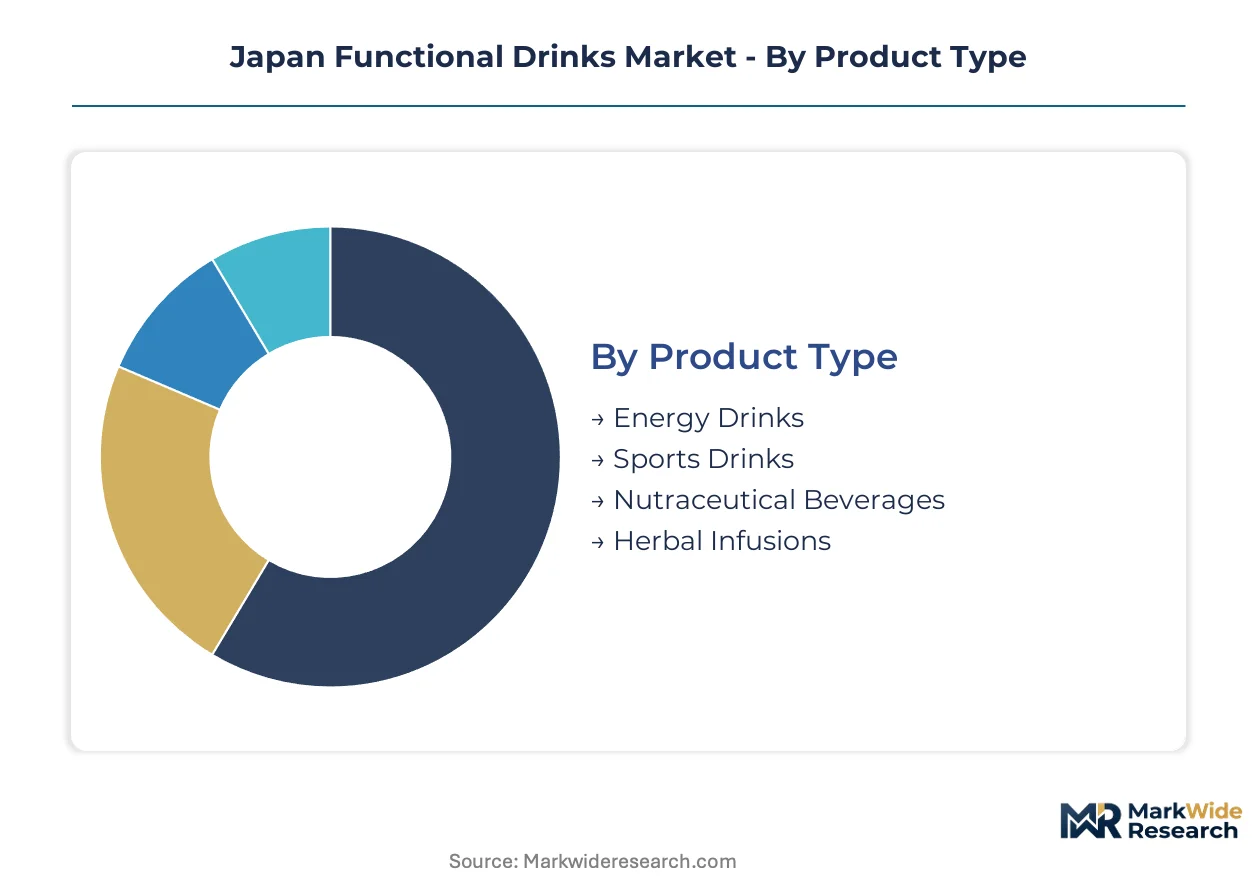
Functional drinks in Japan demand precise segmentation because METI's Food with Function Claims system rewards condition-specific positioning. Manufacturers must align formulation science, target physiology, and channel logistics to capture premium pricing under this regulatory framework.
Product Type:
Standalone beverage formats dominate shelf space, while embedded functional systems in food-service channels remain underdeveloped relative to Western markets.
- Sports Drinks:Electrolyte-balanced formulations with sodium-potassium ratios optimized for Japanese humidity and exercise protocols. Volume concentrates among amateur athletes in Kanto prefectures where hydration science education penetrates deepest.
- Nutraceutical Beverages:Condition-specific drinks targeting sarcopenia prevention, mild cognitive impairment, and joint mobility with validated amino acid or polyphenol dosing. Demand clusters in Osaka and Nagoya among adults over 65 seeking PMDA-adjacent efficacy claims.
- Energy Drinks:Caffeine-taurine blends with B-vitamin complexes for mental alertness.
- Herbal Infusions:Traditional kampo-inspired botanical extracts in ready-to-drink formats.
Volume placements concentrate in Sports Drinks; the faster expansion belongs to Nutraceutical Beverages.
End User:
Cost-tier stratification separates premium clinical-positioned products from mass-market hydration solutions, with pricing bandwidth spanning 300% between entry and specialty tiers.
- Older Adults:Consumers over 65 purchasing condition-specific beverages for mobility preservation and cognitive maintenance. Demand concentrates in suburban Osaka and Fukuoka where pharmacy-chain distribution of medical-nutrition adjacent products penetrates deepest.
- Fitness Enthusiasts:Amateur and semi-professional athletes following structured hydration protocols with electrolyte monitoring. Volume clusters in Tokyo's 23 wards where gym density and sports club membership rates peak nationally.
- Health-Conscious Consumers:Preventive wellness seekers across adult age cohorts prioritizing gut health and immune support.
- Students:Examination-period purchasers of cognitive-enhancement and alertness formulations.
Revenue gravity centers on Older Adults; the steepest volume climb occurs among Fitness Enthusiasts.
Ingredient Type:
Application-specific efficacy requirements dictate formulation architecture, with condition-targeted ingredients commanding manufacturing complexity premiums over general wellness additives.
- Probiotics:Live-culture strains with documented CFU stability through shelf life, microencapsulated for ambient distribution. Demand concentrates in Tokyo and Yokohama where Yakult Honsha's consumer education legacy supports premium pricing across all adult demographics.
- Amino Acids:Branched-chain and conditionally essential formulations for muscle protein synthesis and cognitive precursor delivery. Volume clusters among older adults in Kansai region seeking sarcopenia prevention with clinically referenced dosing.
- Vitamins:Water-soluble B-complex and antioxidant C and E formulations for metabolic support.
- Natural Extracts:Polyphenol-rich green tea catechins and ginkgo biloba for vascular and cognitive claims.
Probiotics anchor current margin pools; amino acid applications are expanding most quickly as clinical validation accumulates.
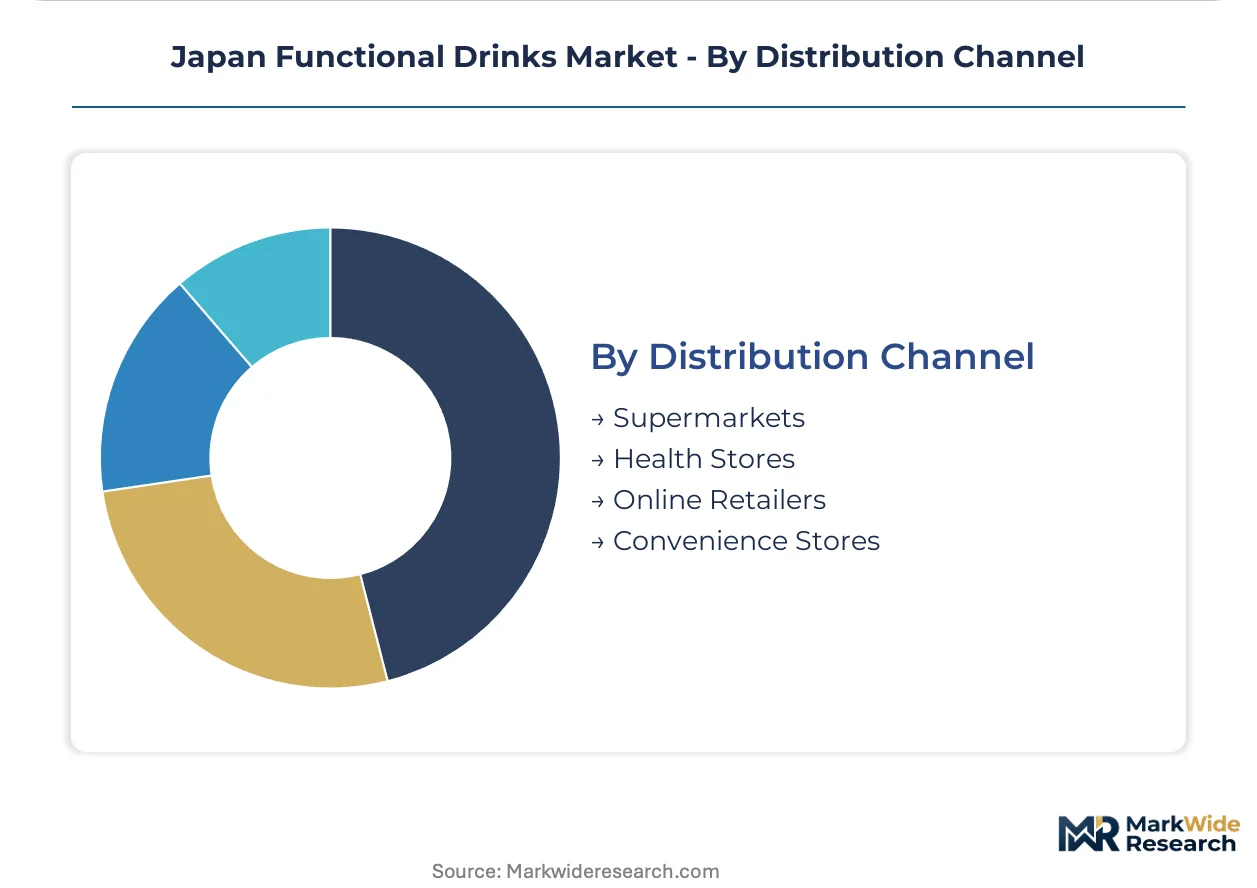
Distribution Channel:
Customer-type fragmentation separates impulse purchasers in convenience channels from planned buyers in health-specialty and subscription formats, with loyalty economics diverging sharply.
- Convenience Stores:Refrigerated single-serve functional shots and probiotic beverages in 7-Eleven, Lawson, and FamilyMart networks. Volume concentrates in Tokyo's dense urban wards where time-constrained professionals favor grab-and-go replenishment.
- Online Retailers:Direct-to-consumer subscription platforms and pharmacy-chain e-commerce for personalized regimen delivery. Growth clusters among Osaka's urban professionals seeking automated replenishment of condition-specific formulations.
- Supermarkets:Multi-serve bottles and family-pack functional beverages in Aeon and Ito-Yokado banners.
- Health Stores:Pharmacy-shelf and specialized wellness retail with trained staff consultation.
Transaction density peaks in Convenience Stores; the fastest share gain belongs to Online Retailers as subscription models fragment traditional channel control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's functional drinks production clusters in Kanto and Kansai industrial corridors, while consumption concentrates in aging suburban prefectures where pharmacy-chain distribution penetrates deepest. This geographic split shapes logistics architecture and channel strategy across the market.
Kanto/Tokyo
Tokyo's 23 wards generate the steepest volume demand for fitness-oriented sports drinks and probiotic beverages among time-constrained professionals. METI's FFC framework receives its most aggressive utilization here as manufacturers pilot novel claims before national rollout. Shibuya and Shinjuku convenience networks serve as testing grounds for single-serve functional shot formats targeting urban commuters.
Kansai/Osaka
Osaka anchors demand for condition-specific nutraceutical beverages targeting sarcopenia prevention and cognitive maintenance among adults over 65. PMDA's pharmaceutical-adjacent oversight tightens evidentiary requirements for products marketed through pharmacy chains in suburban Osaka and Kobe. The region's older demographic structure supports premium pricing for clinically positioned amino acid formulations.
Chubu/Nagoya
Nagoya's manufacturing base supplies microencapsulation technology enabling probiotic stability in ambient distribution channels. Automotive industry professionals drive demand for energy and alertness formulations during shift-work schedules. JIS beverage safety standards are enforced most stringently here due to the region's export-oriented production facilities.
Kyushu
Fukuoka's pharmacy-chain networks concentrate distribution of medical-nutrition adjacent products for mobility preservation among retirees. Regional biotechnology suppliers cultivate specialized probiotic strains under contract to national beverage manufacturers. The city's younger demographic relative to other regions sustains volume in traditional sports drink categories.
Hokkaido
Sapporo's distinct seasonal consumption patterns create demand spikes for immune-support formulations during harsh winter months. Local dairy cooperatives supply fermented culture expertise that informs regional probiotic beverage development. Distribution challenges from geographic isolation favor multi-serve bottle formats over single-serve convenience packaging.
Japan Functional Drinks Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Japan's functional drinks landscape, creating a tiered structure where pharmaceutical heritage confers regulatory navigation advantages. Beverage conglomerates leverage vending infrastructure and convenience retail relationships to defend volume positions. Pharmaceutical-origin players occupy the medical-nutrition boundary with clinically positioned formulations. Beverage pure-plays anchor mass-market penetration through gut-health consumer education legacies. Dominant competitive moves include single-serve format innovation and direct-to-consumer subscription channel development.
Within the pharmaceutical-origin tier, Kirin Holdings and Otsuka Pharmaceutical exemplify condition-specific credibility strategies, while Suntory Beverage & Food Ltd. represents diversified beverage conglomerate control over traditional retail channels. Yakult Honsha occupies a distinctive position as a pure-play specialist whose decades of consumer education have normalized premium probiotic pricing across all adult demographics.
| Leading Market Players |
|---|
| Kirin Holdings |
| Coca-Cola Bottlers Japan Inc. |
| Suntory Beverage & Food Ltd. |
| Otsuka Pharmaceutical |
| Taisho Pharmaceutical Co. Ltd. |
| Asahi Soft Drinks Co. Ltd. |
| ITO EN |
| Monster Energy |
| Yakult Honsha |
| Others |
Cost & Logistics Intelligence
Urban professionals' preference for automated subscription replenishment over impulse vending purchases forces manufacturers to reconfigure distribution economics and absorb last-mile fulfillment costs that compress net realized prices.
Pricing Analysis
Margin tightening in premium nutraceutical tiers reflects escalating clinical validation burdens under PMDA's pharmaceutical-adjacent oversight. Three-tier pricing structure across premium clinical-positioned, standard wellness, and economy hydration levels separates condition-specific amino acid formulations from basic electrolyte replacements. Cost compression accelerates in mass-market sports drinks as vending channel operators extract slotting fee concessions. Fitness enthusiasts in Tokyo's 23 wards exhibit lowest price sensitivity for validated hydration protocols, while suburban older adults prioritize efficacy-per-yen in sarcopenia-targeted beverages.
Supply Chain Analysis
Refrigerated last-mile logistics from Kanto and Kansai production corridors to Tokyo convenience networks consumes disproportionate cost share versus ambient distribution. Probiotic strain cultivation clusters with domestic biotechnology suppliers in Kyushu and Chubu, while amino acid precursors draw from specialized fermentation facilities in Osaka and Nagoya. Single-source vulnerability concentrates in live-culture strain banks, where limited qualified suppliers create qualification bottlenecks for new entrants. Distribution runs through refrigerated convenience store networks and pharmacy-chain cold chains, with ambient microencapsulated formats displacing legacy chilled dependence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized probiotic strain production capacity constraints prop pricing power for validated live-culture suppliers, creating durable margin pools for incumbents with captive biotechnology relationships.
For Market Incumbents: To counter direct-to-consumer subscription disintermediation, Kirin Holdings and Suntory Beverage should deepen pharmacy-chain exclusivity arrangements for condition-specific formulations while backward-integrating into microencapsulation technology to capture ambient distribution economics from refrigerated infrastructure dependence. For New Entrants and Emerging Players: Capture white space in single-serve functional shot formats targeting examination-period students and shift-work professionals in Nagoya's automotive corridor, leveraging online subscription platforms to bypass entrenched vending channel control held by beverage conglomerates. For Investors and Strategic Acquirers: The window for entry favors biotechnology specialists with validated strain libraries and JIS-certified production assets, as METI's FFC framework rewards science-backed positioning over marketing expenditure; monitor PMDA guidance expansion into cognitive claims as inflection signal for medical-nutrition boundary migration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Adoption | Enables probiotic stability in ambient vending channels, expanding distribution beyond refrigerated convenience stores. |
| Direct-to-Consumer Subscription Launch | Captures urban professional replenishment behavior away from impulse-driven single-serve vending purchase. |
| Clinical Validation Investment | Satisfies PMDA's tightening evidentiary thresholds for condition-specific cognitive and mobility claims. |
| Pharmacy-Chain Partnership Expansion | Secures preferred shelf positioning for medical-nutrition adjacent products targeting older adults. |
| Specialized Strain Development Program | Builds defensible supply security against domestic biotechnology supplier concentration risks. |
Research Approach
Multi-period observation of METI FFC claim registrations, PMDA guidance evolution, and vending channel SKU rotations anchored the trend analysis, supplemented by interviews with beverage brand managers, pharmacy-chain category buyers, biotechnology R&D directors, and convenience store operations heads. Secondary validation drew from METI public filings, PMDA pharmaceutical-adjacent claim databases, JIS standard revision notices, and customs records of functional ingredient imports. Bottom-up channel volume estimates triangulated against top-down manufacturer revenue disclosures.
Input-output matrices modeled demand across product type, end-user demographic, ingredient category, and distribution channel dimensions over the projection horizon. CAGRs derived from segment-level growth rate convergence analysis incorporating aging demographic trajectories, regulatory claim category expansion, and channel shift elasticity parameters. Forecast inputs included probiotic strain approval timelines and microencapsulation technology adoption curves.
The model holds under stable METI FFC framework continuity and gradual PMDA guidance evolution; deviation in pharmaceutical reclassification triggers or biotechnology supplier consolidation would shift growth trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market