
 Europe Probiotic Drinks Market | 2026-2036
Europe Probiotic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Probiotic Drinks Market Foresight
Single-serve and on-the-go packaging configurations is broadening consumer trial across convenience channels. Danone S.A. leverages its dairy infrastructure to anchor probiotic drink distribution in Western European supermarkets. Yakult Honsha Co., Ltd. sustains its specialized delivery system model through dedicated refrigerated logistics networks. PepsiCo Inc. competes by extending its beverage portfolio into functional gut-health categories via existing retail partnerships.
Europe probiotic drinks are non-alcoholic, fermented beverages containing live microbial cultures—typically Lactobacillus and Bifidobacterium strains—delivered in liquid matrices with colony-forming unit counts ranging from one billion to over fifty billion per serving, designed to support gastrointestinal microbiome balance. Kefir and kombucha segments lead volume contribution due to established production knowledge and consumer familiarity, while yogurt drinks capture margin pools through premium positioning and probiotic strain differentiation. Distribution through health food stores and online retail represents the fastest-growing structural channel as direct-to-consumer subscription models reduce intermediary costs and build repeat purchase behavior.
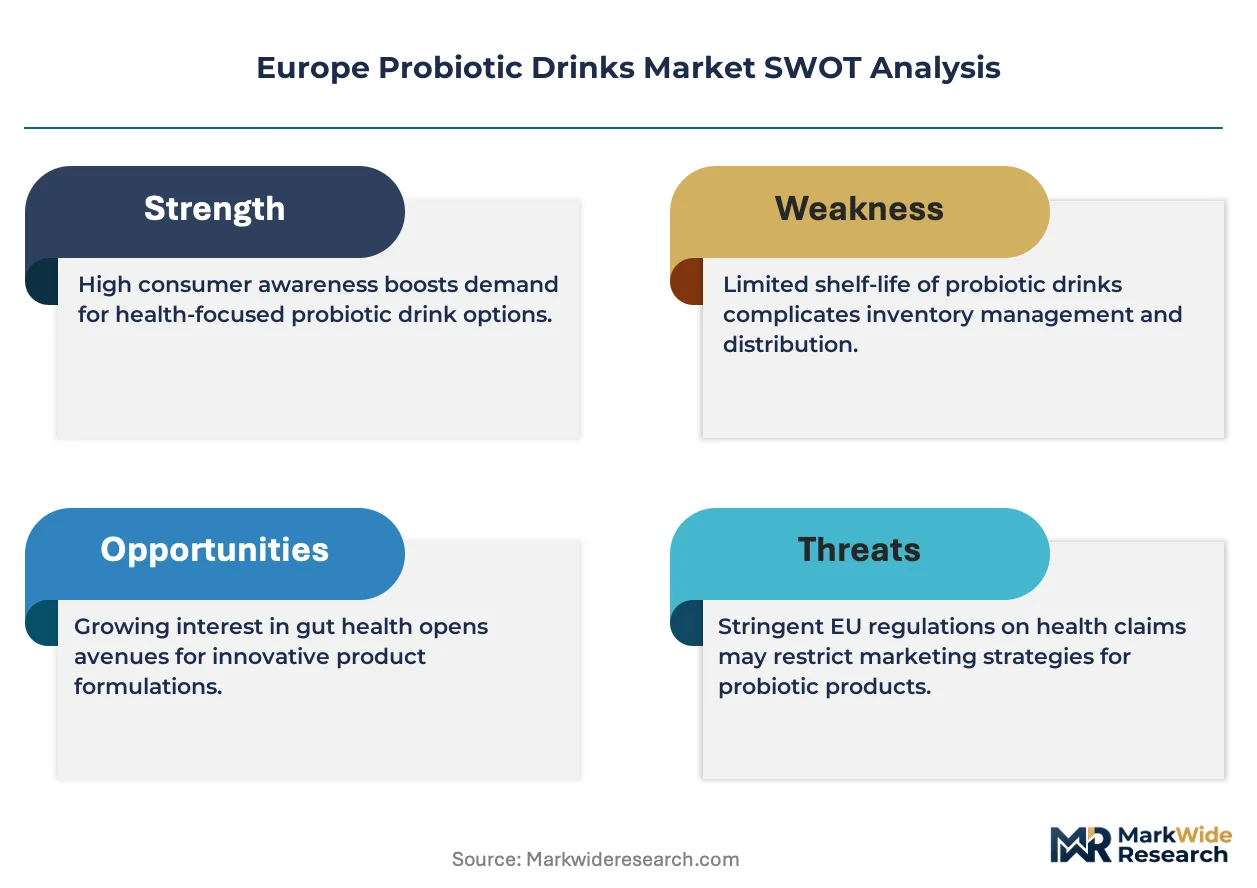
EFSA health claim regulations and EU Food Information to Consumers labeling standards shape product development by demanding strain-specific clinical evidence before immunity or digestive benefit claims appear on packaging. The EU Green Deal and national sustainability frameworks in Germany and France are pressuring manufacturers to reformulate supply chains around lower-carbon dairy sourcing and recyclable packaging materials. Stakeholders must monitor evolving EFSA opinions on novel probiotic strains and preemptive compliance investments in biodegradable packaging to maintain shelf access across major European retail networks.
Market Dynamics
EFSA health claim substantiation requirements are compressing formulation pipelines as manufacturers strain-validate clinical evidence for immunity and digestive benefit claims before packaging authorization.
Growth Catalysts
- EU Green Deal packaging mandates:National sustainability frameworks in Germany and France are accelerating biodegradable material adoption, creating first-mover advantages for compliant suppliers across major retail networks.
- Fermented beverage cultural infrastructure:Established kefir and kombucha production knowledge in France and the Netherlands reduces consumer education costs and accelerates trial-to-repeat conversion rates.
- Direct-to-consumer subscription models:Health food stores and online retail channels are capturing margin previously lost to distributor intermediaries while building predictable recurring revenue streams.
Market Restraints
- Strain-specific clinical validation costs:EFSA regulations demand expensive randomized controlled trials for novel Lactobacillus and Bifidobacterium variants before health claims receive regulatory clearance.
- Refrigerated logistics concentration:Cold-chain dependency limits distribution reach to urban centers with reliable temperature-controlled infrastructure, excluding rural and peripheral markets.
- Dairy input price volatility:Milk and whey protein costs fluctuate with agricultural commodity cycles, compressing margin stability for functional dairy-based formulations.
Strategic Opportunities
- Polish and Romanian convenience channel penetration:Underdeveloped probiotic drink shelf space in Eastern European supermarkets offers expansion runway for single-serve and on-the-go packaging configurations.
- Plant-based fermentation matrices:Oat, coconut, and almond milk substrates are opening gut-health positioning to lactose-intolerant and vegan consumer segments previously excluded from dairy-centric offerings.
- CSRD-aligned carbon accounting:Early compliance with corporate sustainability reporting requirements positions suppliers favorably for ESG-mandated procurement decisions by institutional retail buyers.
Industry Challenges
- Microbiome stability engineering:Maintaining viable colony-forming unit counts through shelf life requires specialized formulation expertise that outpaces current technical talent pipelines.
- Cross-border labeling harmonization:Divergent national interpretations of EU Food Information to Consumers standards create compliance fragmentation for multi-market product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Probiotic Drinks Market |
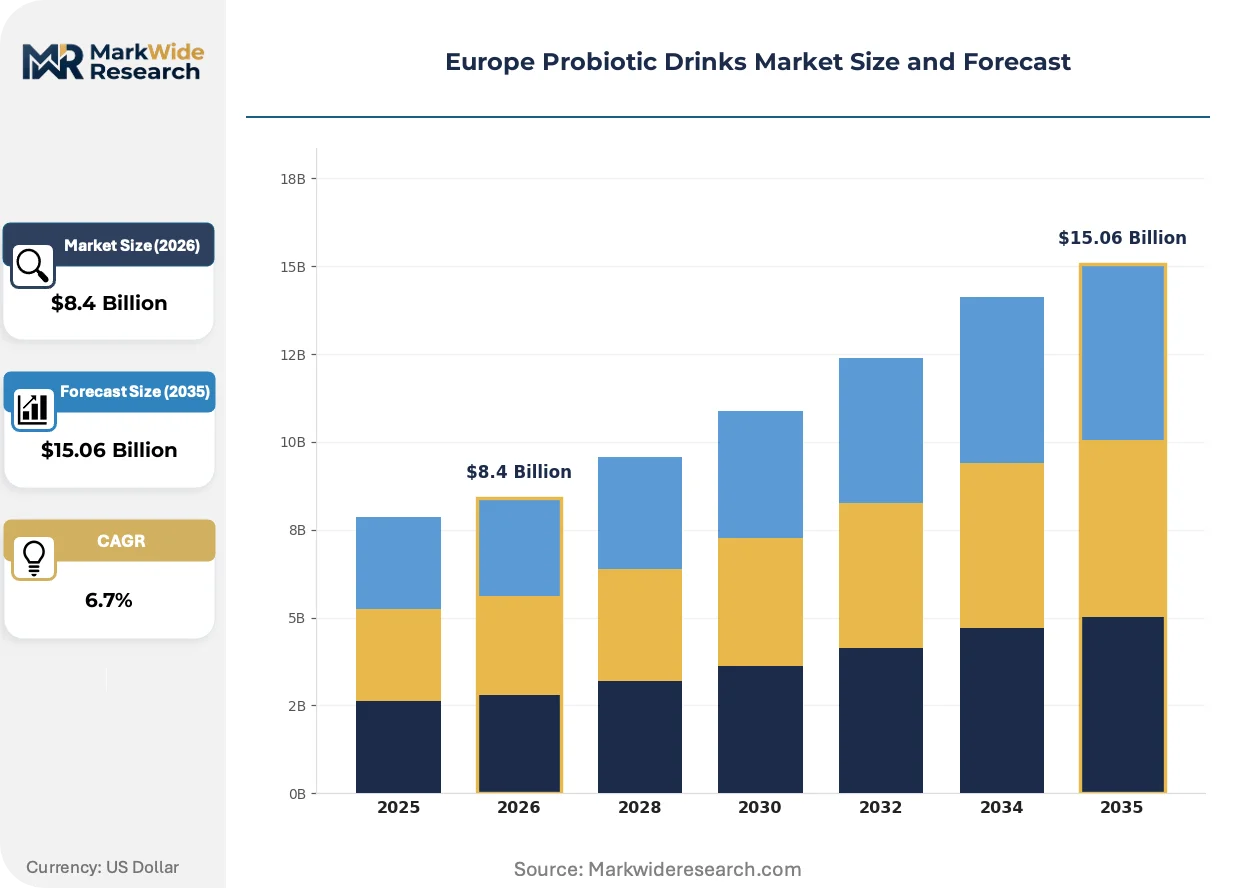
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Yogurt Drinks, Functional Dairy Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Restaurants Flavor Profile: Fruity, Herbal, Spicy, Plain Target Audience: Health Enthusiasts, Athletes, Families, Seniors |
| Companies Covered | Lifeway Foods, Nourish Kefir, Yakult Honsha Co., Ltd., Bio-K Plus International Inc., Yeo Valley Group Limited, PepsiCo Inc., Archer Daniels Midland Company, GT's Living Foods, Danone S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Probiotic Drinks Market Shifts & Advancements
Live culture stabilization technologies and strain-specific clinical differentiation are compressing competitive moats while reshaping procurement criteria for retail buyers and ingredient suppliers.
Microencapsulation and cryoprotectant formulation is consolidating shelf-stable probiotic viability as German and Dutch dairy processors adopt protective matrix technologies that extend ambient-temperature distribution windows. Small-batch kombucha brewers and kefir specialists are licensing these stabilization methods to access convenience retail channels previously blocked by refrigeration requirements. The technology is consolidating supply chain requirements around fewer specialized ingredient vendors capable of delivering validated protective cultures.
EFSA's evolving opinions on novel probiotic strains are tightening clinical evidence thresholds before immunity or digestive benefit claims appear on packaging. Manufacturers must now commission randomized controlled trials for each strain-variant combination, extending product development timelines and raising capital requirements for formulation pipelines. French and German regulators are scrutinizing kombucha alcohol content thresholds more aggressively, forcing producers to reformulate fermentation protocols or relabel as alcoholic beverages.
Health-conscious consumers are prioritizing strain-specific transparency over generic "probiotic" labeling, demanding packaging disclosure of Lactobacillus rhamnosus or Bifidobacterium animalis subspecies with documented clinical outcomes. This behavioral pivot is displacing undifferentiated yogurt drinks in Netherlands and Belgium supermarkets while elevating premium-positioned kefir and kombucha with substantiated strain portfolios. Pharmacy and parapharmacy channels in France are capturing this demand rotation through pharmacist-curated gut-health assortments that emphasize clinical credibility over taste positioning.
Europe Probiotic Drinks Market Segmentation
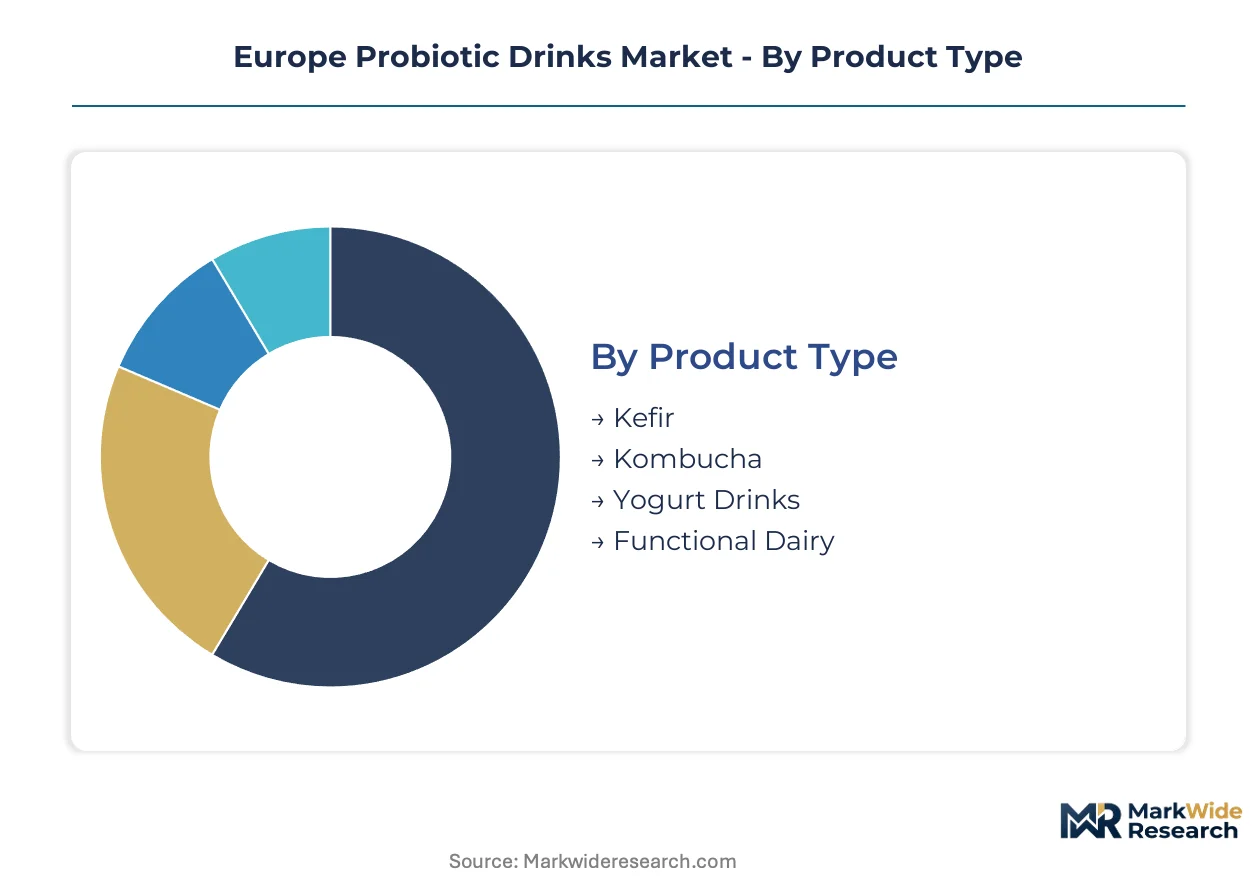
Strategic segmentation reveals how formulation matrices, channel infrastructure, and demographic targeting intersect to determine margin capture across European probiotic drink categories. Manufacturers align R&D investment and distribution partnerships to specific segment characteristics rather than pursuing undifferentiated mass-market positioning.
Product Type:
Consumer willingness to pay for functional benefits drives product type selection, with clinical substantiation and cultural familiarity determining price elasticity across formats.
- Kefir:Fermented milk beverage containing Lactobacillus kefiri and kefir grains, delivering 10-50 billion CFU per serving with established production protocols in Eastern European dairy traditions. French and Dutch households sustain repeat purchase through pharmacy and supermarket channels where EFSA-compliant digestive health claims support premium positioning against commodity dairy.
- Kombucha:Tea-based fermentation utilizing SCOBY cultures with acetic acid and glucuronic acid metabolites, requiring alcohol content monitoring under tightened French and German regulatory thresholds. German wellness retailers and Dutch organic chains capture demand from health-conscious millennials seeking non-dairy gut health alternatives with transparent ingredient sourcing.
- Yogurt Drinks:Drinkable fermented dairy with standardized Lactobacillus delbrueckii subsp. bulgaricus and Streptococcus thermophilus cultures, leveraging existing cold-chain infrastructure across Western European supermarkets.
- Functional Dairy:Enhanced milk beverages with added probiotic strains beyond traditional yogurt cultures, targeting immunity positioning through strain-specific clinical differentiation in pharmacy channels.
Volume sits with yogurt drinks; growth tilts toward kombucha.
Distribution Channel:
Channel selection determines margin structure and consumer education burden, with refrigerated logistics requirements filtering viable participants.
- Supermarkets:Mass-market penetration vehicle with dedicated chilled dairy aisles in Carrefour, REWE, and Albert Heijn networks, capturing family segment volume through promotional pricing and multi-pack configurations. German and French retailers demand EFSA-compliant labeling and sustainable packaging certifications as listing prerequisites.
- Health Food Stores:Curated assortment environment with pharmacist or trained staff consultation, supporting premium pricing for clinically substantiated strains in French parapharmacy and Dutch organic retail networks.
- Online Retail:Direct-to-consumer subscription models bypassing distributor margins, building predictable recurring revenue through personalized strain recommendations and home delivery convenience.
- Restaurants:Foodservice integration through beverage menu placement, requiring ambient-stable formulations or dedicated refrigerated storage partnerships with hospitality distributors.
Supermarkets dominate transaction volume; online retail climbs fastest.
Flavor Profile:
Taste positioning signals target demographic and occasions of use, with formulation complexity affecting culture viability through shelf life.
- Fruity:Berry, citrus, and tropical fruit infusions masking fermented acidity, dominating children's and family-oriented product lines in Netherlands and Belgian supermarkets where palatability drives trial conversion.
- Herbal:Botanical additions such as ginger, turmeric, and adaptogenic herbs supporting functional positioning in German wellness retail and French pharmacy channels.
- Spicy:Chili, pepper, and warming spice formulations differentiating kombucha and kefir variants for adventurous adult palates in urban UK and Scandinavian markets.
- Plain:Unflavored traditional formulations appealing to purist consumers and culinary applications, sustaining share in Eastern European heritage markets and clean-label positioning.
Fruity formulations anchor volume; herbal profiles expand most quickly.
Target Audience:
Demographic targeting shapes strain selection, packaging format, and communication strategy with distinct regulatory and channel implications.
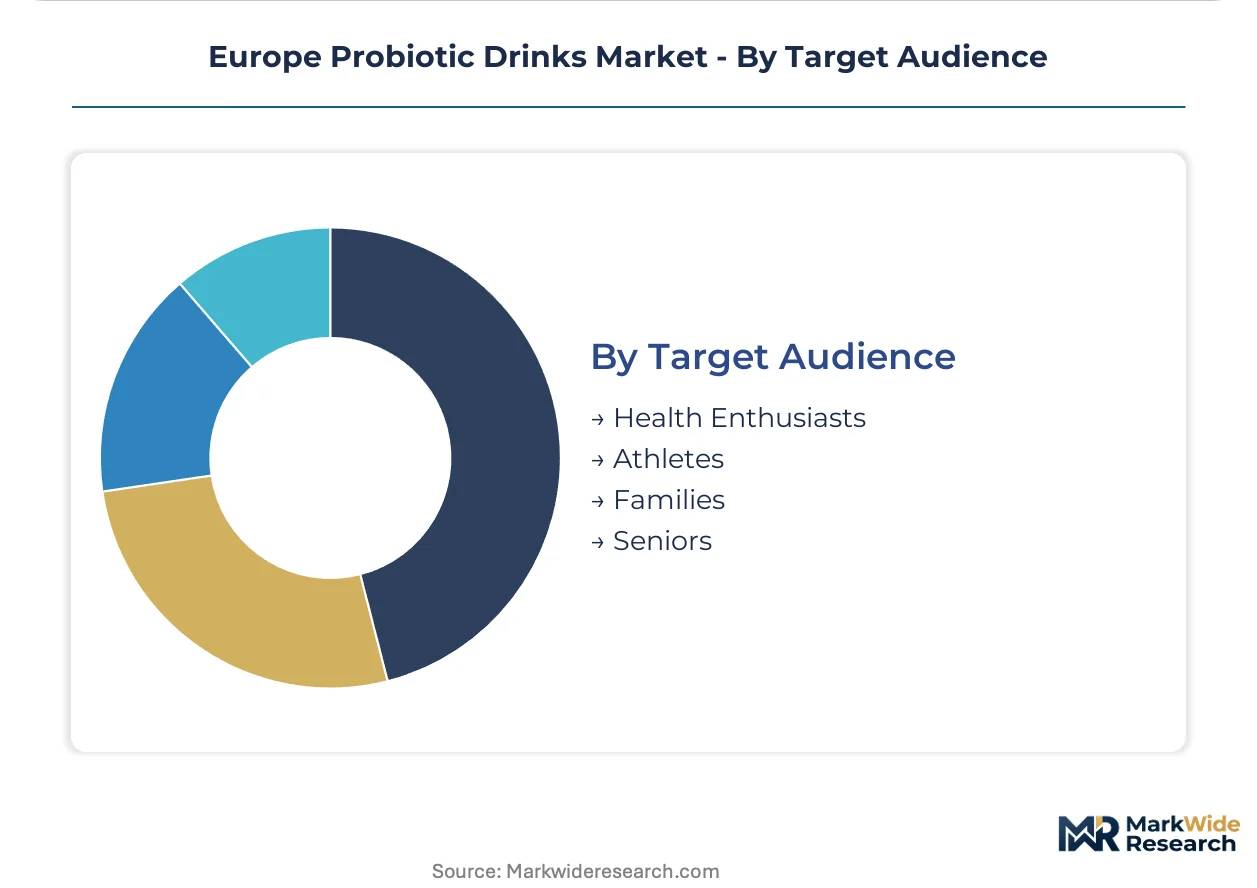
- Health Enthusiasts:Information-seeking consumers prioritizing strain-specific transparency and clinical substantiation, concentrated in French pharmacy channels and German organic retail where EFSA-compliant claims justify premium pricing.
- Athletes:Performance-oriented segment seeking gut health support for nutrient absorption and immune resilience during training cycles, targeted through sports nutrition retail and team sponsorship partnerships.
- Families:Multi-generational households prioritizing convenience and palatability for children, captured through supermarket multi-packs and school-compatible portion formats in Netherlands and UK.
- Seniors:Age-related digestive health concerns driving demand for high-CFU count formulations with constipation and immunity positioning, accessed through pharmacy recommendation and healthcare professional endorsement.
Families generate the largest transaction base; health enthusiasts command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tax incentives for sustainable food processing have concentrated probiotic drink manufacturing in Lower Saxony and Bavaria, drawing investment toward EFSA-compliant production facilities.
Germany
Wellness retail expansion and pharmacy channel integration drive probiotic drink demand across German metropolitan areas. The EU Green Deal packaging mandates accelerate biodegradable material adoption in national supply chains. Bavaria's dairy processing clusters around Munich host specialized kefir and functional dairy production lines serving Western European distribution networks.
France
Deep-rooted fermented beverage culture supports kombucha and kefir consumption through parapharmacy and organic retail channels. ANSM and DGCCRF regulators enforce tightened alcohol content thresholds for kombucha formulations. The Île-de-France region anchors production gravity with Paris-based startups licensing live culture stabilization technologies for ambient-stable distribution.
Netherlands
High per-capita dairy consumption and health-conscious urban populations sustain yogurt drink and kefir demand through Albert Heijn and Jumbo supermarket networks. EFSA health claim substantiation requirements shape product development timelines for Amsterdam-based formulation labs. The Randstad corridor concentrates cold-chain logistics infrastructure enabling refrigerated distribution across Benelux markets.
United Kingdom
Functional beverage trial rates climb through health food store expansion and direct-to-consumer subscription models in Greater London. The Food Standards Agency monitors novel probiotic strain approvals under retained EU regulations post-Brexit. Urban brewing collectives in Bristol and Manchester pioneer small-batch kombucha production with pharmacy retail partnerships.
Poland
Eastern Europe's underdeveloped probiotic drink shelf space offers expansion runway for single-serve packaging configurations in Warsaw and Kraków convenience channels. National alignment with EU Food Information to Consumers standards simplifies cross-border labeling compliance. Silesian dairy cooperatives leverage existing fermentation expertise to enter functional beverage categories through modern retail partnerships.
Europe Probiotic Drinks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's probiotic drink landscape, producing a tiered structure where scale advantages clash with strain-specific expertise. Market concentration clusters around dairy heritage players with existing cold-chain infrastructure and beverage multinationals extending into functional gut-health categories. Three archetypes dominate: integrated dairy processors with probiotic line extensions, dedicated fermentation specialists with clinical substantiation capabilities, and beverage conglomerates leveraging retail partnerships for category entry. Competitive dynamics center on M&A activity targeting regional kefir and kombucha brands, plus capacity expansion into plant-based fermentation matrices.
Among the dedicated specialists, Yakult Honsha Co., Ltd. and Bio-K Plus International Inc. exemplify the clinical-substantiation archetype through strain-specific positioning and pharmacy channel penetration. Danone S.A. anchors the integrated dairy processor tier, leveraging existing refrigerated logistics networks across Western European supermarkets. PepsiCo Inc. represents beverage conglomerate entry into functional categories, utilizing established retail relationships to secure shelf space for gut-health portfolio extensions.
| Leading Market Players |
|---|
| Lifeway Foods |
| Nourish Kefir |
| Yakult Honsha Co., Ltd. |
| Bio-K Plus International Inc. |
| Yeo Valley Group Limited |
| PepsiCo Inc. |
| Archer Daniels Midland Company |
| GT's Living Foods |
| Danone S.A. |
| Others |
Supply & Pricing Matrix
Pharmacy and parapharmacy buyers in France command premium positioning for EFSA-validated strains, anchoring a subscription-tiered pricing model that rewards clinical substantiation over commodity dairy alternatives. German supermarket procurement teams leverage volume scale to compress margins on yogurt drinks while tolerating higher per-unit costs for refrigerated logistics compliance.
Pricing Analysis
Short lead-time premiums attach to direct-to-consumer subscription channels where personalized strain curation and home delivery convenience justify recurring payment structures above retail shelf pricing. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-positioned kefir with documented CFU counts from supermarket multi-packs and private-label yogurt drinks. Cost compression in the standard tier is intensifying because EFSA validation requirements extend development timelines and raise capital barriers for novel strain introductions. Family segment buyers in Netherlands supermarkets exhibit highest price sensitivity, while health enthusiasts in French organic retail demonstrate lowest elasticity for clinically substantiated kombucha and kefir variants.
Supply Chain Analysis
Workforce availability constraints in Bavarian dairy processing clusters and Paris-region fermentation startups are tightening technical talent competition for microbiome stability engineers and cold-chain logistics specialists. Manufacturing gravity centers on Germany, France, and the Netherlands where EFSA-compliant production facilities cluster around established dairy heritage infrastructure. Raw material dependencies rest on milk and whey protein inputs from agricultural cooperatives, SCOBY cultures from specialized fermentation laboratories, and protective matrix technologies from German ingredient vendors. Single-source vulnerability concentrates in live culture suppliers capable of delivering validated cryoprotectant formulations. Distribution runs through refrigerated logistics networks anchored in the Randstad corridor and Rhine-Ruhr metropolitan regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live culture stabilization technologies are displacing legacy refrigerated-only distribution models, enabling ambient-stable probiotic viability that restructures channel economics and geographic reach across European markets.
For Market Incumbents: Anticipate margin compression from plant-based fermentation specialists by securing exclusive licensing agreements for protective matrix technologies and expanding in-house production of oat and coconut milk substrates. Channel control through pharmacy partnerships in France and Germany remains a critical defensive lever against direct-to-consumer subscription entrants. EFSA opinion evolution on novel strains constitutes the primary regulatory threat requiring preemptive clinical trial investment. For New Entrants and Emerging Players: Begin with underdeveloped convenience channel shelf space in Polish and Romanian supermarkets where single-serve packaging configurations face limited incumbent competition. The most penetrable segment sits with lactose-intolerant and vegan consumers previously excluded from dairy-centric offerings. A targeted go-to-market angle leverages direct-to-consumer subscription models with personalized strain recommendations to bypass established retail listing barriers. For Investors and Strategic Acquirers: The window for entry favors clinical-substantiation specialists with validated strain portfolios and pharmacy channel relationships over undifferentiated commodity dairy processors. Long-term viability hinges on capabilities spanning live culture stabilization, EFSA-compliant health claim substantiation, and plant-based matrix formulation expertise. The signal to watch is EFSA opinion publication timelines for novel Lactobacillus and Bifidobacterium variants, which will determine which strain portfolios capture premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Live Culture Stabilization Licensing | Enables ambient distribution through pharmacy and convenience channels previously blocked by refrigeration requirements. |
| Plant-Based Matrix Expansion | Opens gut-health positioning to lactose-intolerant and vegan segments in German and Dutch urban markets. |
| EFSA Health Claim Pre-Submission | Secures regulatory clearance for immunity and digestive benefit claims before competitor strain validation completes. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket listing fees and builds predictable recurring revenue through personalized strain curation. |
| CSRD-Aligned Carbon Accounting | Positions suppliers favorably for ESG-mandated procurement decisions by institutional retail buyers in France and Germany. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with dairy processing executives, pharmacy category managers, cold-chain logistics operators, and EFSA regulatory affairs specialists. EFSA opinion databases, EU Food Information to Consumers enforcement records, national sustainability framework disclosures, and refrigerated transport customs classifications supplied quantitative validation. Bottom-up strain-level demand modeling and top-down category value estimation were reconciled through iterative triangulation.
Data-stream reconciliation across production volume surveys, retail audit data, and channel margin structures informed the analytical framework applied across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, flavor profile, and target audience demographics with regional regulatory cluster differentiation. CAGRs were derived from growth rate convergence analysis applied to historical trajectory patterns and structural driver elasticity estimates. Forecast inputs incorporated EFSA opinion timeline assumptions and EU Green Deal packaging mandate compliance cost curves.
Underlying measurement precision varies by segment; yogurt drinks and kefir carry tighter precision than emerging kombucha variants due to established production reporting conventions. Forecasts reflect assumptions regarding EFSA regulatory trajectory, cold-chain infrastructure expansion, and plant-based substrate cost curves. Material deviation in EFSA opinion publication schedules or EU packaging mandate enforcement timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Powdered Soft Drinks Market
Beverages
Japan Energy Drink Market
Beverages
North America Cold Pressed Juices Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
South America Energy Drink Market
Beverages
United States Recovery Drinks Market
Beverages
India Cafes & Bars Market
Beverages
Root Beer Market
Beverages
Peanut Oil Market
Beverages
Italy Probiotic Drinks Market
Beverages
Fermented Foods and Beverages Market
Beverages
Collagen Drinks Market
Beverages
Victorian Jars Market
Beverages
Germany Probiotic Drinks Market
Beverages
Orange Juice Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market