
 Clean Label Pectin Market | 2026-2036
Clean Label Pectin Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Pectin Market Outlook
Citrus peel processors in Brazil and Mexico is recalibrating supply chains to serve the clean-label shift. Cargill, Incorporated leverages backward integration into citrus sourcing to secure raw material consistency. Herbstreith & Fox anchors European supply through specialized pectin extraction technology. CP Kelco competes in seaweed-derived alternatives, extending its portfolio beyond conventional fruit sources.
Clean label pectin is a high-methoxyl or low-methoxyl polysaccharide extracted from citrus peels or apple pomace, functioning as a gelling agent, stabilizer, or thickener in food systems at specific pH and soluble solids levels. Its primary commercial purpose is to replace synthetic hydrocolloids in processed foods while maintaining texture and shelf stability. Powder formulations dominate manufacturing scale due to handling efficiency and extended shelf life, while liquid pectin captures premium positioning in beverage applications requiring rapid dispersion. Citrus-derived pectin sustains the largest source share, though apple-based extraction is gaining traction among European suppliers responding to regional fruit availability.
EFSA evaluates pectin safety and labeling claims under EU food additive frameworks, while the FDA governs GRAS status and identity standards in the United States. India's FSSAI is tightening clean-label disclosure norms for imported hydrocolloids, affecting market access for non-domestic suppliers. Stakeholders must monitor evolving enzyme-extraction patents and regional organic certification requirements to protect formulation flexibility and sourcing economics.
Market Dynamics
Clean label pectin supply chains are restructuring around citrus peel sourcing concentration in Brazil and Mexico, while European formulators face tightening EFSA disclosure mandates that eliminate synthetic hydrocolloid alternatives.
Growth Catalysts
- EU Green Deal additive rules:EFSA guidance on clean-label disclosure is compelling bakery and dairy processors across Germany, France, and Italy to reformulate with plant-derived stabilizers.
- Beverage manufacturer demand:Formulators in juice and functional drink categories are replacing synthetic hydrocolloids with high-methoxyl pectin for rapid dispersion and clean-label positioning.
- Enzyme extraction patents:Novel enzymatic processing technologies are reducing extraction time and improving pectin yield from apple pomace and citrus peels.
Market Restraints
- Citrus peel supply volatility:Weather-dependent harvests in Brazil and Florida concentrate raw material risk for processors dependent on orange and lemon peel feedstock.
- Seaweed-derived hydrocolloid substitution:Alginate and carrageenan alternatives from CP Kelco and other suppliers compete on cost in specific gelling applications.
- FSSAI import disclosure norms:India's tightening clean-label requirements for imported hydrocolloids create regulatory friction for non-domestic suppliers seeking market access.
Strategic Opportunities
- India clean-label penetration:FSSAI's evolving standards create first-mover advantage for suppliers establishing local formulation partnerships before full enforcement.
- Organic certification convergence:EU organic regulations and USDA NOP alignment enables dual-certified pectin sourcing for multinational food manufacturers.
- Precision fermentation pectin:Cell-culture production methods are emerging as a pathway to decouple pectin supply from agricultural commodity cycles.
Industry Challenges
- Organic certification timeline compression:Three-year transition requirements for orchards strain supplier planning horizons as clean-label demand accelerates.
- Legacy equipment retrofit costs:Powder-to-liquid pectin processing line conversions require capital outlays that mid-scale manufacturers defer.
- IP licensing complexity:Patent thickets around specific enzyme extraction methods constrain technology access for smaller regional processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Pectin Market |
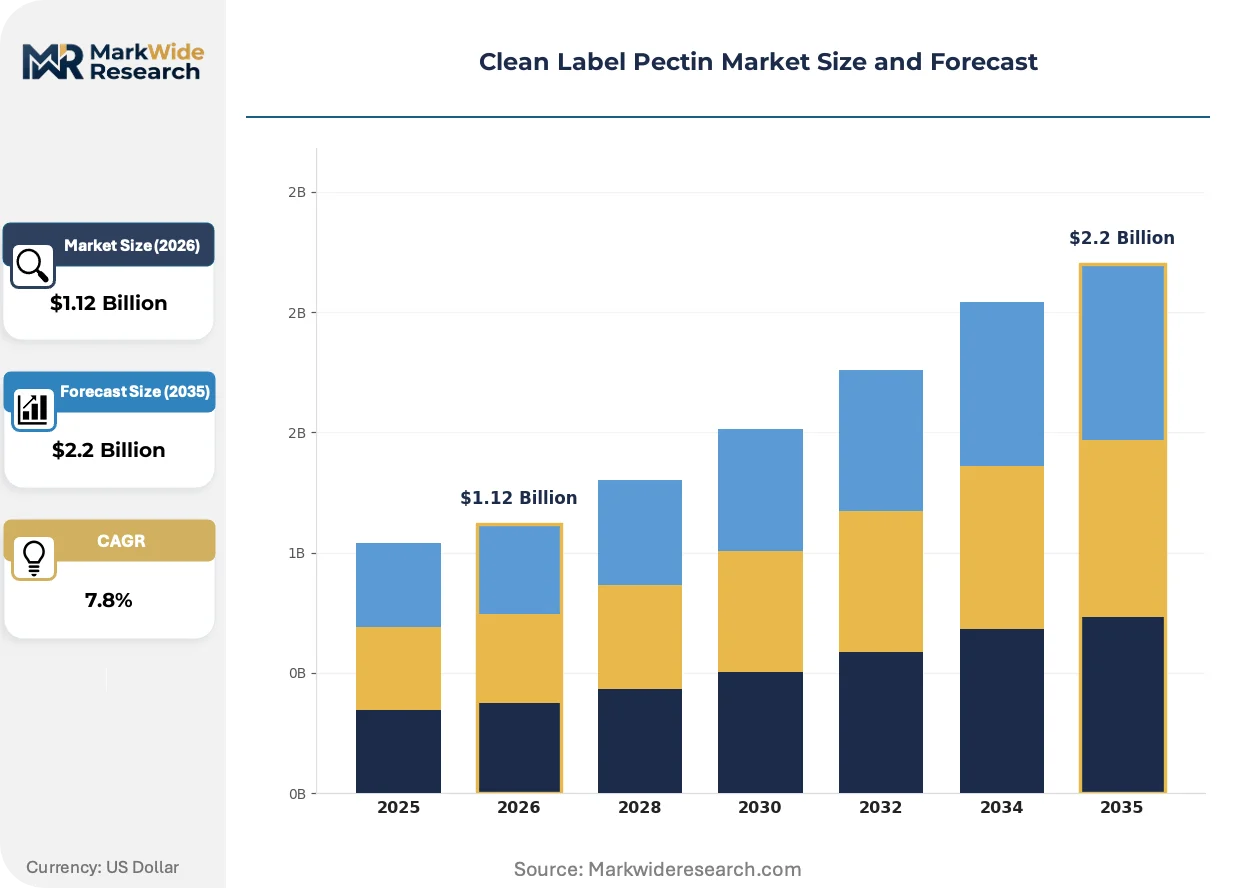
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.2 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Gel, Granulated Application: Dairy Products, Bakery, Confectionery, Beverages Source: Citrus Fruits, Apples, Seaweed, Others End User: Food Industry, Beverage Manufacturers, Pharmaceutical, Nutraceutical |
| Companies Covered | Cargill, Incorporated, DuPont, Herbstreith & Fox, CP Kelco, Naturex, Ceamsa, Silvateam, Lucid Colloids Ltd., DSM Andre Pectin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Pectin Market Strategic Shifts
Clean label pectin innovation is pivoting toward extraction efficiency and application-specific functionalization, with regulatory compliance and supply security now co-equal priorities alongside traditional performance metrics.
Enzymatic extraction technology is absorbing capital allocation from conventional acid-hydrolysis methods. Citrus processors in Brazil and Mexico are deploying cellulase and pectinase cocktails to improve yield and reduce processing waste. Beverage manufacturers are capturing the output for rapid-dispersion liquid pectin formulations that synthetic stabilizers previously dominated.
EFSA's evolving food additive frameworks are compressing formulation timelines for European processors. The EU Green Deal's tightening disclosure requirements are eliminating grandfathered synthetic hydrocolloid approvals in specific categories. German bakery and dairy suppliers are responding with accelerated reformulation programs to meet retailer clean-shelf standards ahead of enforcement deadlines.
Buyer concentration among multinational beverage and dairy manufacturers is consolidating procurement leverage. Tier-one formulators are unbundling technical service from material supply, demanding application-specific pectin grades with documented provenance. This pattern is most visible in Germany and the Netherlands, where retail chain clean-label mandates cascade through supplier tiers.
Clean Label Pectin Market Segmentation
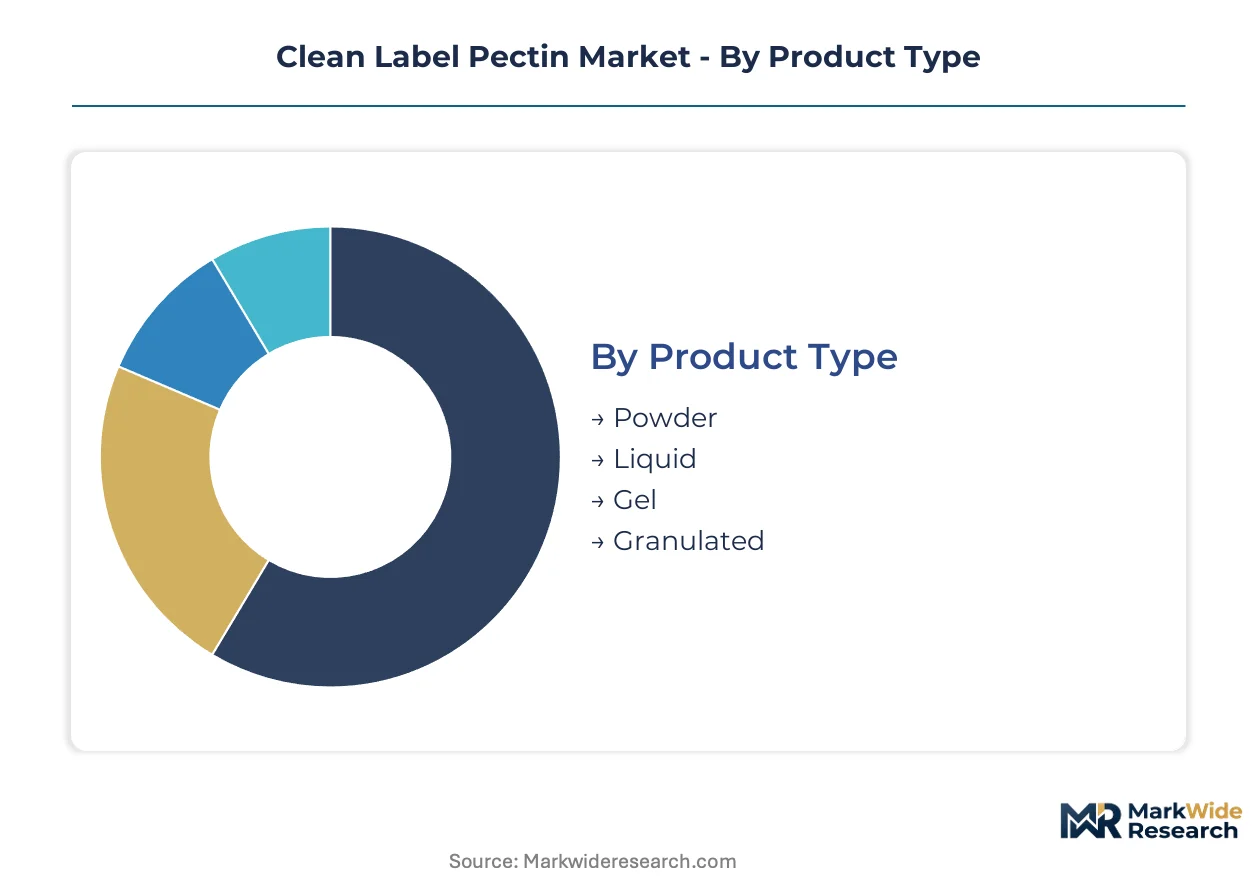
Clean label pectin procurement decisions hinge on functional performance in specific food matrices, extraction provenance, and regulatory compliance documentation. Manufacturers segment demand across four critical dimensions that determine formulation flexibility and supply security.
Product Type:
Formulators select physical formats based on processing line compatibility and hydration kinetics in target applications.
- Powder:Dominates manufacturing scale due to extended shelf stability and bulk handling efficiency. German dairy processors specify powder grades for standardized gelling control in yogurt and fermented milk production.
- Liquid:Captures premium positioning in beverage applications requiring rapid dispersion without high-shear mixing equipment. Juice formulators in the Netherlands favor liquid pectin for clean-label stabilization of pulpy drinks.
- Gel:Pre-hydrated formats reduce production time for small-batch confectionery manufacturers with limited processing infrastructure.
- Granulated:Flow-enhanced particle engineering prevents clumping in automated dosing systems for industrial bakery operations.
Volume sits with powder; growth tilts toward liquid.
Application:
End-use category determines methoxyl content requirements and regulatory scrutiny intensity.
- Beverages:High-methoxyl pectin stabilizes pulp suspension and cloud retention in juice systems. EFSA's evolving additive disclosure rules are compelling German and French formulators to replace synthetic hydrocolloids ahead of enforcement deadlines.
- Dairy Products:Low-methoxyl grades provide calcium-reactive gelling for protein stabilization. Italian yogurt manufacturers are reformulating with citrus-derived pectin to meet retailer clean-shelf mandates.
- Bakery:Fillings and glazes utilize rapid-set pectin for thermal stability during baking cycles.
- Confectionery:Specific DE-value pectin enables controlled gel strength in reduced-sugar jelly applications.
Beverage procurement concentrates volume share; dairy reformulation is climbing the fastest.
Source:
Raw material provenance shapes organic certification eligibility and supply chain risk profiles.
- Citrus Fruits:Orange and lemon peel extraction sustains the largest commercial supply base. Brazilian processors dominate feedstock availability, though Florida grapefruit peel offers alternative sourcing for North American manufacturers.
- Apples:Pomace-derived pectin aligns with European regional fruit availability and shorter supply chains for EU organic certification. Polish and German apple processors are expanding extraction capacity.
- Seaweed:Alginate-carrageenan blends from CP Kelco and competitors compete on cost in specific gelling applications where clean-label status is less critical.
- Others:Sugar beet and sunflower head pectin serve niche regional markets with localized raw material access.
Citrus anchors procurement volume; apple sourcing is expanding most quickly.
End User:
Customer scale and technical capability determine service bundling requirements and contract structures.
- Food Industry:Multinational bakery and dairy manufacturers demand application-specific grades with full provenance documentation. Buyer consolidation in Germany and the Netherlands is unbundling technical service from material supply.
- Beverage Manufacturers:Tier-one juice and functional drink formulators specify rapid-dispersion liquid pectin with validated clean-label positioning for retail chain compliance.
- Pharmaceutical:USP-grade pectin for controlled-release tablet matrices requires enhanced purity certification and batch documentation.
- Nutraceutical:Modified citrus pectin for dietary supplement applications commands premium pricing based on molecular weight fractionation.
Food industry procurement holds volume concentration; nutraceutical applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian citrus peel processors anchor raw material flows for clean label pectin extraction, while regulatory divergence across key consuming markets reshapes regional demand patterns. Supply chain configuration varies significantly by geography, driven by local fruit availability, processing infrastructure density, and additive disclosure mandates.
Germany
Bakery and dairy processors in Bavaria and North Rhine-Westphalia are accelerating reformulation programs to meet retailer clean-shelf standards. EFSA's evolving clean-label guidance under the EU Green Deal is compressing formulation timelines for synthetic hydrocolloid replacement. The Stuttgart-Munich corridor concentrates pectin procurement leverage among multinational food manufacturers demanding full provenance documentation.
United States
Florida grapefruit peel offers alternative citrus sourcing for North American manufacturers seeking supply chain resilience. FDA GRAS status and identity standards govern pectin safety classifications, though state-level organic certification requirements add compliance layers. Chicago and Minneapolis-St. Paul serve as distribution hubs for beverage manufacturers specifying rapid-dispersion liquid grades.
Brazil
Orange and lemon peel extraction sustains the largest commercial supply base for global pectin production. São Paulo state processors deploy cellulase and pectinase cocktails to improve yield and reduce processing waste. Campinas and Ribeirão Preto anchor the citrus processing cluster serving export markets.
India
FSSAI is tightening clean-label disclosure norms for imported hydrocolloids, creating regulatory friction for non-domestic suppliers. Maharashtra and Gujarat food processors represent emerging demand centers as local formulation partnerships develop. Mumbai-Pune corridor manufacturers are evaluating pectin alternatives ahead of full enforcement timelines.
Netherlands
Rotterdam and Amsterdam serve as import gateways for liquid pectin destined to juice formulators across Northwestern Europe. Dutch beverage manufacturers favor rapid-dispersion formats for clean-label stabilization of pulpy drinks. The Randstad logistics network enables just-in-time delivery to tier-one formulators with retail chain compliance mandates.
Clean Label Pectin Market Competitive Environment
Global majors compete with regional champions across extraction technology and raw material access. The vendor base clusters around three tiers: integrated agribusiness conglomerates with captive citrus supply, specialized European pectin extractors with proprietary enzyme platforms, and diversified hydrocolloid suppliers extending portfolios beyond fruit-derived sources. Dominant competitive moves include backward integration into citrus sourcing and patent licensing for enzymatic processing methods.
Within the integrated agribusiness tier, Cargill, Incorporated anchors supply security through upstream control over Brazilian citrus peel flows. Herbstreith & Fox exemplifies the specialized European extractor archetype, occupying a position tied to regional fruit availability and application-specific grade development. CP Kelco represents the diversified hydrocolloid supplier model, competing across seaweed-derived alternatives while maintaining pectin exposure.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DuPont |
| Herbstreith & Fox |
| CP Kelco |
| Naturex |
| Ceamsa |
| Silvateam |
| Lucid Colloids Ltd. |
| DSM Andre Pectin |
| Others |
Value Chain & Pricing Dynamics
Tier-one beverage and dairy manufacturers in Germany and the Netherlands concentrate procurement leverage, forcing unbundling of technical service from material supply and compressing margins for standard-grade pectin suppliers. This buyer consolidation anchors contract-based long-term offtake agreements with volume-scaled discounts, while application-specific grades with full provenance documentation command residual premiums.
Pricing Analysis
Technical service bundling distinguishes contract structures, with multinational food manufacturers increasingly separating formulation support from base material supply to drive cost transparency. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status, methoxyl content precision, and extraction method transparency. Pricing pressure stems from enzyme-extraction patent licensing fees that smaller regional processors cannot absorb. Mid-scale bakery manufacturers exhibit highest price sensitivity, while pharmaceutical and nutraceutical buyers prioritize purity certification over unit cost.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale demand from integrated agribusiness conglomerates, while specialized distributors serve regional formulators requiring smaller batch flexibility. Raw material flows concentrate in Brazil, Mexico, and Poland, with citrus peel from São Paulo state and apple pomace from Polish orchards feeding extraction facilities. Supply chains draw from weather-dependent agricultural feedstocks, enzyme processing inputs, and organic certification infrastructure. Single-source vulnerability in Brazilian citrus peel exposes processors to climate-driven harvest volatility. Distribution runs through Rotterdam and Campinas as primary consolidation hubs for European and North American markets respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EFSA's evolving clean-label disclosure mandates under the EU Green Deal erect regulatory moats favoring suppliers with established organic certification infrastructure and documented provenance systems.
For Market Incumbents: Cement supply security through backward integration into Brazilian citrus sourcing and accelerated organic certification timelines for captive orchards. Seaweed-derived hydrocolloid substitution from CP Kelco and alginate competitors threatens margin position in cost-sensitive gelling applications. Prioritize enzyme-extraction patent licensing to regional processors to monetize technology lead while constraining rival capacity expansion. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian clean-label penetration offers viable entry trajectory ahead of full FSSAI enforcement. Maharashtra and Gujarat food processors represent the most penetrable demand centers, with local formulation partnerships serving as essential go-to-market mechanism. Target rapid-dispersion liquid pectin for beverage manufacturers seeking retail chain compliance without high-shear mixing infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European apple processors with stranded extraction capacity and pending organic certification in Poland and Germany. Long-term viability hinges on cell-culture production methods decoupling supply from agricultural commodity cycles. Monitor precision fermentation pectin pilot announcements as inflection indicator for technology disruption timeline.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Sourcing | Cargill's upstream control over Brazilian peel flows secures raw material consistency against climate volatility. |
| Enzyme Extraction Patent Licensing | Herbstreith & Fox proprietary platforms constrain technology access for smaller regional processors. |
| Organic Certification Convergence | EU organic regulations and USDA NOP alignment enables dual-certified sourcing for multinational manufacturers. |
| Precision Fermentation Development | Cell-culture production methods emerging as pathway to decouple supply from agricultural commodity cycles. |
| Local Formulation Partnerships | FSSAI's evolving standards create first-mover advantage for suppliers establishing India-based technical service. |
Study Parameters
Document review covered EFSA additive framework guidance, FSSAI import disclosure drafts, and EU Green Deal implementation documents, complemented by interviews with citrus peel processors, bakery procurement leads, beverage formulators, and enzyme technology suppliers. Secondary validation drew from customs trade data, organic certification registries, and patent filings. Bottom-up volume modeling triangulated against top-down demand aggregation across end-use categories.
Cross-referencing historical extraction capacity expansion patterns against expert panel input on enzyme adoption timelines shaped the analytical framework. Segmentation dimensions modeled include physical format, methoxyl content grade, raw material provenance, and end-user technical capability tier across the projection horizon. CAGRs derived from supply-demand balance analysis incorporating organic certification transition timelines and reformulation program acceleration rates. Industry-specific inputs captured EFSA enforcement phase-in assumptions and FSSAI compliance cost estimates.
Inputs from EFSA working group minutes and Brazilian agricultural ministry harvest reports were available through the study window; gaps in precision fermentation commercialization timelines introduce uncertainty bands around cell-culture supply projections. Forecasts reflect documented assumptions regarding regulatory enforcement pacing and organic orchard transition completion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market