
 Food Coating Market | 2026-2036
Food Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Food Coating Market Analysis
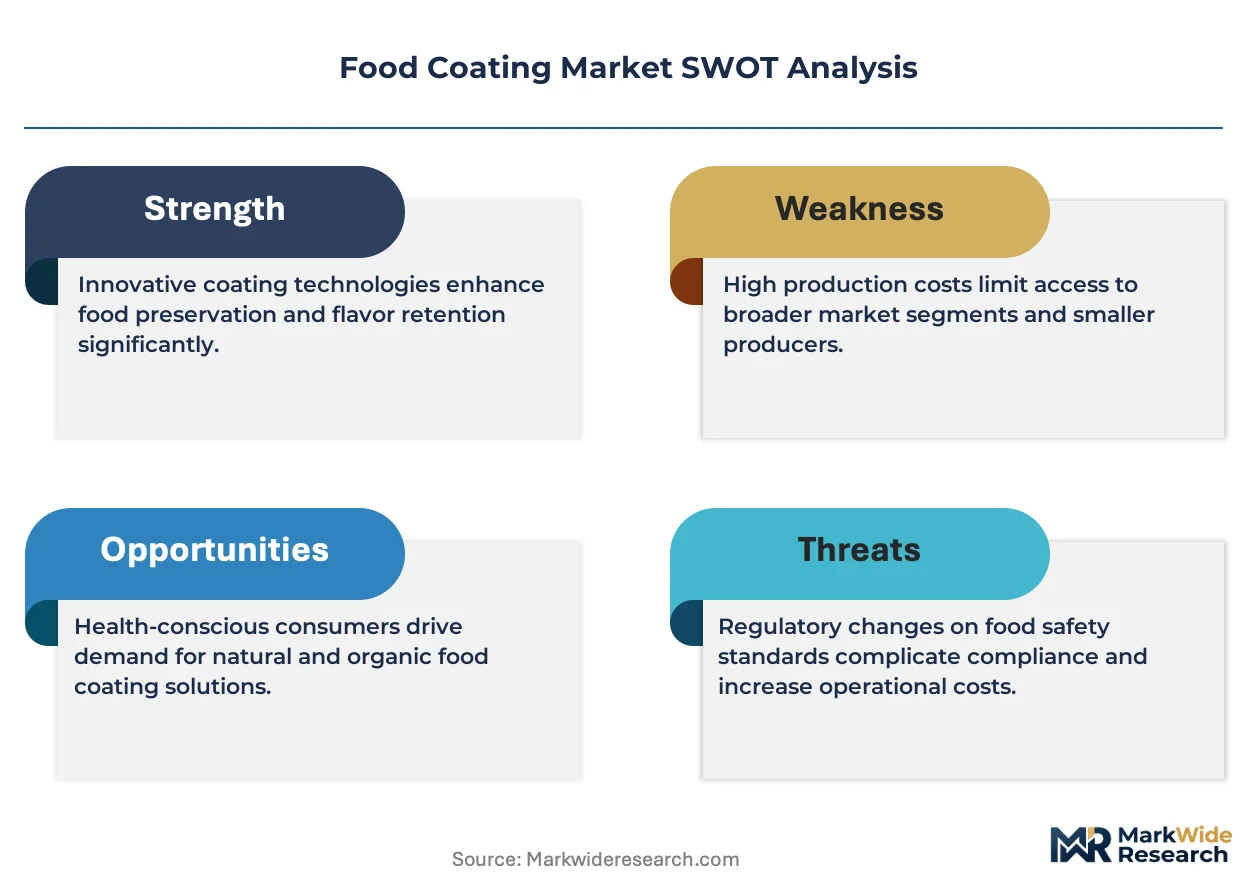
Plant-based protein adhesion technology is tilting formulation priorities across the food coating industry. Kerry Group PLC leverages its hydrocolloid research infrastructure to anchor premium clean-label positions in European snack applications. Cargill, Incorporated sustains supply security through backward integration into modified starch production across North American grain belts. Tate & Lyle PLC differentiates via specialty texturant portfolios targeting reduced-fat fried products.
Food coating encompasses the controlled deposition of edible layers—starches, gums, proteins, or lipid-based suspensions—onto substrates to modify texture, moisture barrier properties, or visual appeal, typically applied through dipping, spraying, or drum tumbling at controlled temperatures between 40°C and 180°C depending on the set mechanism. The industrial purpose centers on extending shelf stability, enabling fat reduction, and delivering standardized sensory profiles across high-volume prepared food operations. Dry coating formulations dominate volume throughput in salty snack manufacturing where tumble-drum application achieves uniform adhesion at line speeds exceeding 200 kg per hour. Liquid coating systems capture expanding margin pools in protein processing as brine-injection and vacuum-tumbling methods penetrate poultry and red-meat operations seeking yield optimization. Spray coating technology leads growth trajectories in precision confectionery and functional ingredient microencapsulation where droplet-size control determines bioactive retention.
The FDA oversees GRAS self-affirmation pathways that determine which novel coating ingredients achieve rapid commercialization versus prolonged safety review cycles. EFSA's evolving guidance on clean-label claims and additive-free positioning is compressing formulation freedom for exporters targeting European retail channels. India's FSSAI import clearance requirements for food-grade gums and starches create procedural friction for suppliers without localized certification infrastructure. Stakeholders must monitor how divergent national approval timelines for emerging fermentation-derived coating materials reshape competitive access across priority export corridors.
Market Dynamics
Clean-label ingredient adoption is compressing formulation freedom while simultaneously opening premium positioning for suppliers with verified supply chains and fermentation-derived alternatives. EFSA's tightening additive-free guidelines and FDA's evolving GRAS pathways are forcing simultaneous compliance investments across multiple export corridors.
Growth Catalysts
- EFSA Clean-Label Guidelines:European snack manufacturers are accelerating reformulation to meet additive-free positioning requirements, creating pull-through demand for hydrocolloid and protein-based coating systems.
- Poultry Processing Yield Optimization:Vacuum-tumbling and brine-injection coating methods are penetrating red-meat and poultry operations seeking moisture retention and cook-yield improvements.
- Germany's Industrial Bakery Corridor:Concentrated demand from high-volume baked goods manufacturers is anchoring regional production capacity for specialty starch and gum coatings.
Market Restraints
- Modified Starch Input Volatility:North American grain belt weather patterns and biofuel diversion are creating price instability for the coating industry's largest volume input.
- FSSAI Import Friction:India's food-grade gum and starch clearance requirements impose procedural delays on suppliers lacking localized certification infrastructure.
- Thermal Set Limitations:Temperature-sensitive bioactive ingredients face retention losses above 120°C, constraining functional coating applications in high-heat processing.
Strategic Opportunities
- Netherlands Food Technology Cluster:Precision microencapsulation capabilities in Dutch research corridors offer white space for bioactive and probiotic coating applications.
- IRA Clean Manufacturing Incentives:US domestic production credits for sustainable food processing equipment lower capex barriers for coating line upgrades.
- Plant-Protein Adhesion Convergence:Cross-linking between enzymatic protein modification and electrostatic deposition is enabling fat-mimetic textures in reduced-oil fried products.
Industry Challenges
- Fermentation-Derived Material Approval Timelines:Divergent national safety review cycles for novel coating substrates create competitive access gaps across priority export markets.
- Legacy Drum-Tumbling System Integration:Retrofitting continuous spray and precision deposition equipment into existing salty snack lines requires substantial downtime and line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Coating Market |
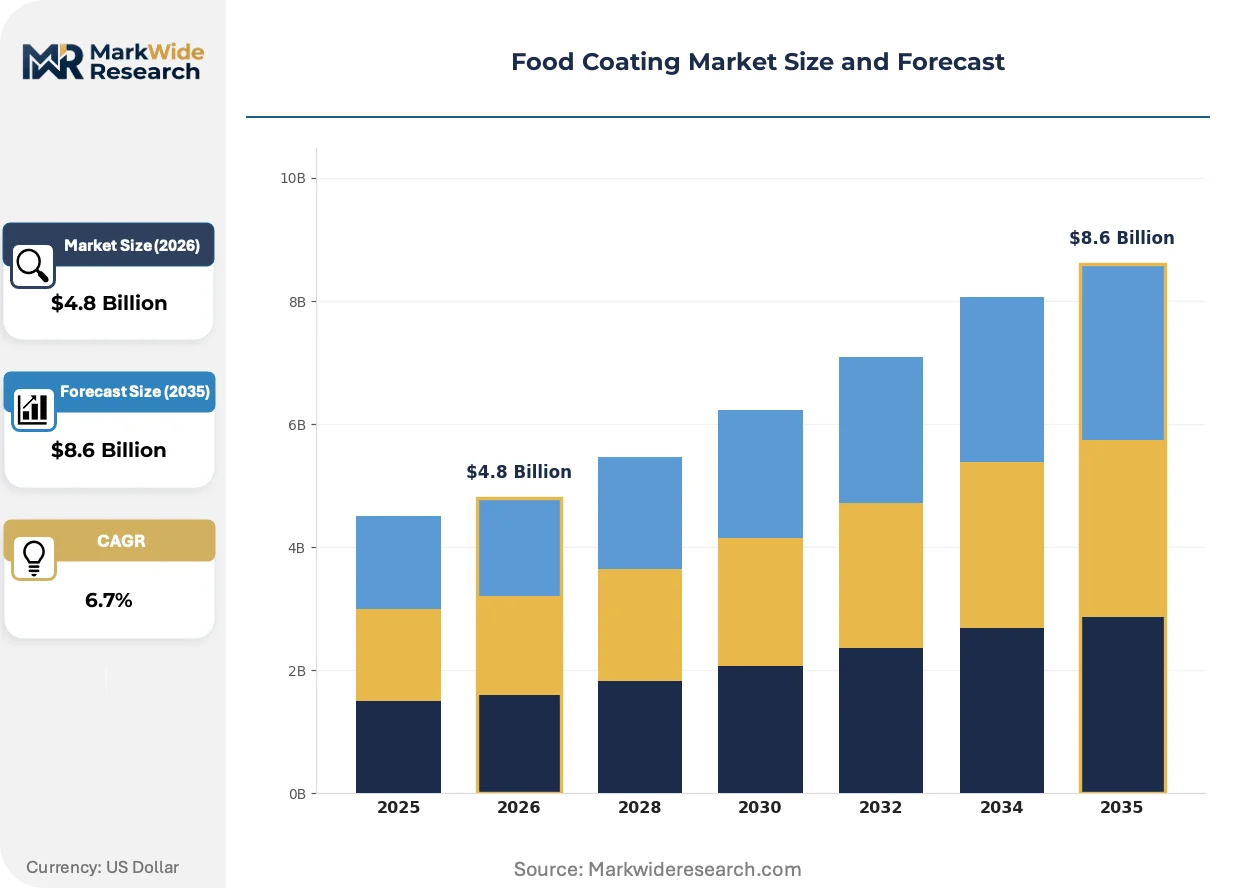
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Coating, Liquid Coating, Heat-treated Coating, Spray Coating Application: Snacks, Meat Products, Bakery Goods, Dairy Items Coating Material: Starch, Pectin, Gelatin, Gum Arabic Distribution Channel: Direct Sales, Online Retail, Supermarkets, Specialty Stores |
| Companies Covered | Bunge Limited, Kerry Group PLC, Cargill, Incorporated, Newly Weds Foods, Corbion N.V., Archer Daniels Midland Company, Tate & Lyle PLC, Döhler GmbH, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Coating Market Emerging Trajectories
Formulation science is pivoting toward bio-based adhesion mechanisms and precision deposition control, with regulatory compliance emerging as a parallel innovation axis rather than a downstream constraint.
Electrostatic powder coating is migrating from industrial metal finishing into food applications through modified tribo-charging systems designed for organic substrate adhesion. European confectionery manufacturers are piloting this technology for uniform cocoa butter replacement coatings at reduced application temperatures. The shift is compressing thermal damage to heat-sensitive bioactives while enabling thinner, more consistent lipid barrier layers.
REACH restrictions on microplastics are forcing coating suppliers to eliminate synthetic polymer carriers from European-bound formulations. ECHA's 2023 restriction proposal covers intentionally added microplastics in all food contact applications. Suppliers are responding with starch-based and cellulose-derived carrier systems, though these require reformulated rheology profiles to maintain line-speed performance.
Direct supplier-contract manufacturer relationships are displacing traditional ingredient distributor networks in high-volume snack manufacturing. Large salty snack producers in Germany and the Netherlands are consolidating procurement through single-source coating system partnerships. This concentration is most visible in industrial bakery and extruded snack segments where formulation consistency and supply security outweigh price elasticity considerations.
Food Coating Market Segmentation
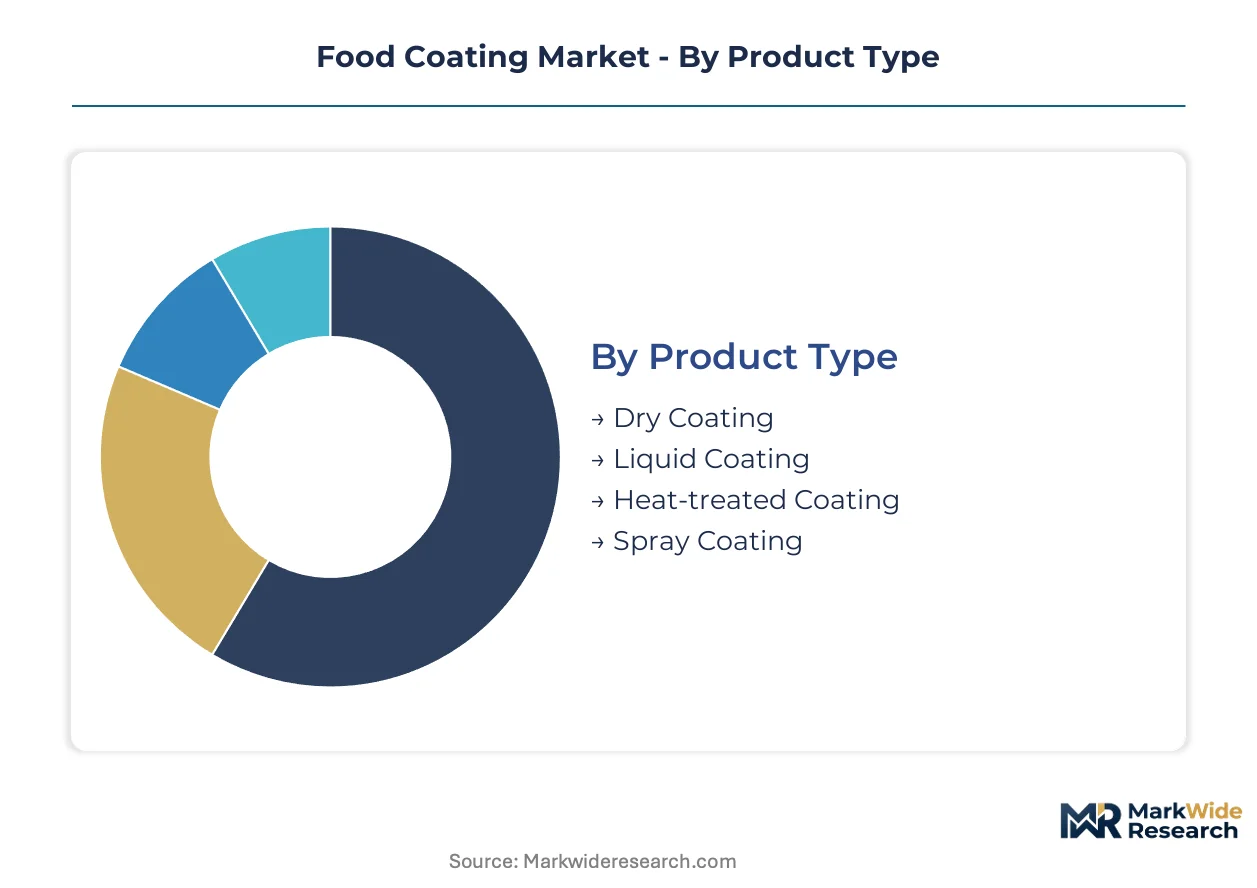
Segmentation in food coating reveals how formulation chemistry, application physics, and channel economics intersect. Each dimension exposes different margin pools and competitive moats for suppliers navigating tightening regulatory corridors.
Product Type:
Dry coating systems dominate high-throughput snack manufacturing where tumble-drum adhesion achieves uniform coverage at line speeds exceeding 200 kg per hour.
- Dry Coating:Powdered starch and seasoning blends deposited via rotary drums form the volume backbone of salty snack operations. Demand concentrates in Germany's industrial bakery corridor where EFSA clean-label guidelines are forcing rapid reformulation away from synthetic carriers.
- Liquid Coating:Aqueous suspensions and emulsions enable precise viscosity control for moisture-barrier applications. Vacuum-tumbling and brine-injection methods are penetrating poultry processing operations in the Netherlands seeking cook-yield optimization above 15%.
- Heat-treated Coating:Thermal-set systems using modified starches and proteins create crispy textures through controlled gelatinization.
- Spray Coating:Atomized deposition achieves droplet-size precision for functional ingredient microencapsulation in confectionery.
Established volume favors Dry Coating; emerging adoption favors Spray Coating.
Application:
End-use concentration determines formulation complexity and regulatory exposure across coating procurement decisions.
- Snacks:Extruded and fried products require adhesion systems that survive high-shear tumbling and rapid oil absorption. Clean-label starch alternatives are displacing modified systems in European retail channels facing EFSA additive-free positioning requirements.
- Meat Products:Poultry and red-meat operations deploy brine-injected coatings for moisture retention and yield protection. Vacuum-tumbling penetration is climbing fastest in Netherlands processing facilities integrating precision deposition control.
- Bakery Goods:Glaze and sealing applications for shelf-stable bread and pastries.
- Dairy Items:Protective coatings for cheese rinds and yogurt inclusions.
Snacks anchor procurement volume; Meat Products show steepest expansion trajectory from yield-optimization investments.
Coating Material:
Raw material selection increasingly hinges on fermentation-derived alternatives and verified supply chain documentation rather than functional performance alone.
- Starch:Native and modified starches constitute the largest volume input, sourced from North American grain belts facing weather-driven price instability. Backward integration into captive starch production is becoming a competitive necessity for supply security.
- Pectin:Citrus and apple-derived hydrocolloids enable clean-label gelling in reduced-sugar confectionery. Dutch research corridors are pioneering precision pectin esterification for tailored gel-strength profiles.
- Gelatin:Collagen-derived films and capsules for pharmaceutical-nutraceutical crossover applications.
- Gum Arabic:Acacia-sourced emulsifier and encapsulant facing FSSAI import friction for suppliers without India-localized certification infrastructure.
Starch maintains cost-position dominance; Pectin is gaining share fastest from clean-label confectionery demand.
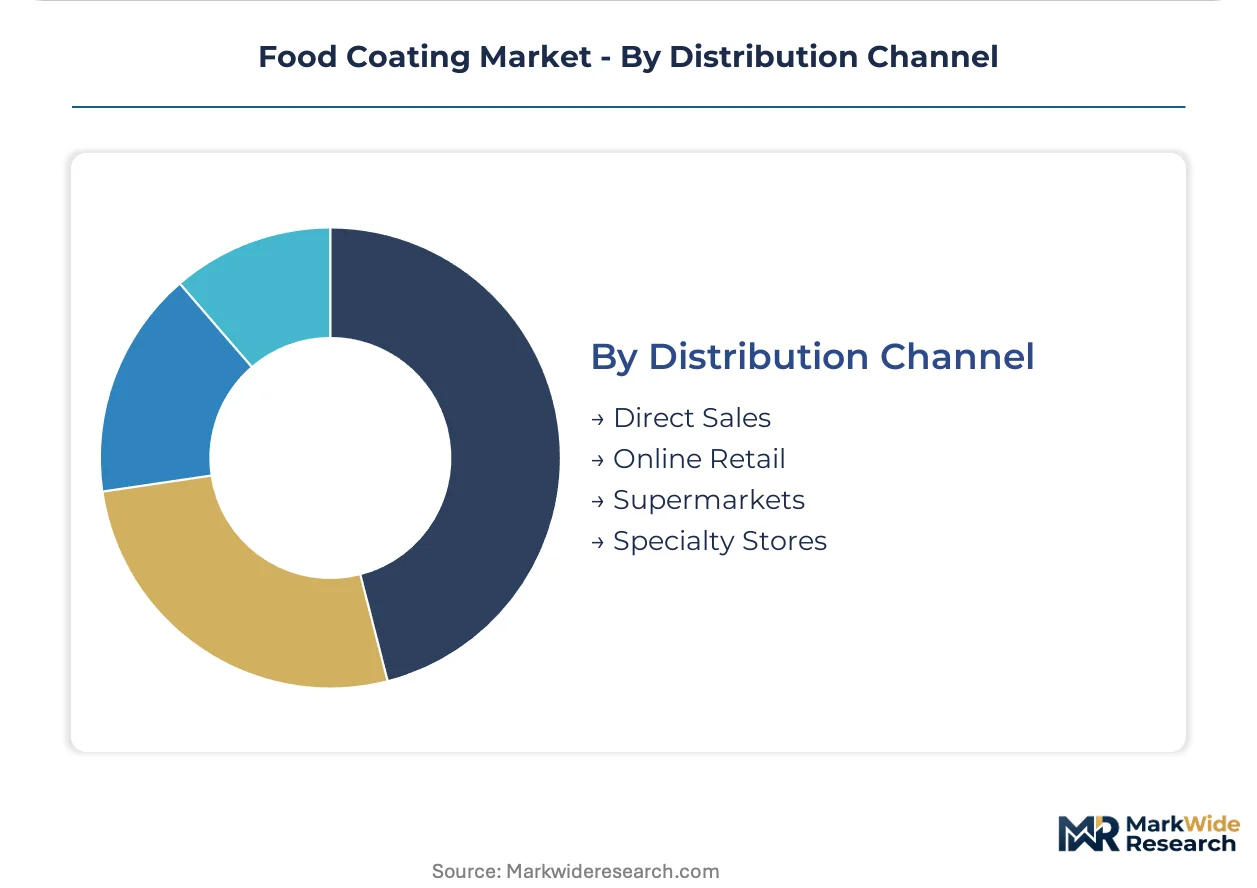
Distribution Channel:
Channel structure is concentrating around direct supplier-manufacturer relationships that collapse traditional distributor margins in high-volume segments.
- Direct Sales:Single-source coating system partnerships are displacing ingredient distributors in German and Netherlands snack manufacturing. Formulation consistency and supply security now outweigh price elasticity for industrial bakery and extruded snack procurement.
- Online Retail:Digital procurement platforms are emerging for specialty and small-batch coating ingredients.
- Supermarkets:Private-label coating kits for home cooking and small commercial kitchens.
- Specialty Stores:Artisan and craft food ingredient suppliers serving boutique confectionery and bakery operations.
Direct Sales commands margin concentration; Online Retail shows emerging traction from procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial snack manufacturers in Germany's bakery corridor and precision food technologists in the Netherlands anchor procurement concentration for advanced coating systems. EFSA clean-label enforcement and FDA GRAS pathway evolution are reshaping supplier access across Atlantic export corridors.
Germany
EFSA additive-free guidelines are compressing formulation freedom for extruded snack producers in North Rhine-Westphalia. The country's Federal Office of Consumer Protection and Food Safety enforces strict contaminant thresholds for starch-based coatings. Cologne-Düsseldorf industrial bakeries are consolidating procurement through single-source coating partnerships to secure supply continuity.
United States
Modified starch demand from Midwest grain belt processors faces price volatility from biofuel diversion and weather pattern disruption. FDA GRAS self-affirmation pathways determine commercialization speed for novel fermentation-derived coating substrates. Chicago corridor meatpacking operations are deploying vacuum-tumbling systems for poultry yield optimization above fifteen percent.
Netherlands
Precision microencapsulation demand from Wageningen research corridors is accelerating bioactive coating adoption in confectionery applications. REACH restrictions on microplastic carriers force reformulation toward cellulose-derived alternatives. Eindhoven-Tilburg food technology clusters are pioneering electrostatic deposition for reduced-temperature lipid barrier applications.
India
FSSAI import clearance friction for food-grade gums and starches disadvantages suppliers without localized certification infrastructure. The regulator's procedural delays compress competitive access timelines for European and North American exporters. Maharashtra and Gujarat snack manufacturing hubs are driving domestic sourcing mandates for clean-label hydrocolloid alternatives.
China
SAMR food contact material standards are tightening safety documentation requirements for imported coating substrates. The regulator's evolving GB standards for starch modifications create compliance complexity for foreign suppliers. Yangtze River Delta processed food manufacturers are integrating domestic modified starch production to reduce import dependency.
Food Coating Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Consolidation pressures concentrate around direct manufacturer partnerships that displace traditional ingredient distributors in high-volume snack segments. Three archetypes dominate: integrated agribusiness operators with captive starch supply, hydrocolloid research specialists targeting clean-label premium positioning, and regional formulation houses serving boutique confectionery. Competitive moves center on backward integration into grain processing assets and single-source partnership contracting with industrial bakery customers.
Among Irish-registered multinationals, Kerry Group PLC exemplifies the research-intensive archetype leveraging hydrocolloid infrastructure for European snack applications. US-based agribusiness operators Cargill, Incorporated and Archer Daniels Midland Company anchor positions through upstream control over North American grain belt starch production. Netherlands-registered Corbion N.V. occupies a specialty position within fermentation-derived ingredient supply, reflecting the geographic clustering of precision food technology capabilities around Dutch research corridors.
| Leading Market Players |
|---|
| Bunge Limited |
| Kerry Group PLC |
| Cargill, Incorporated |
| Newly Weds Foods |
| Corbion N.V. |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Döhler GmbH |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Overcapacity in North American modified starch production is compressing supplier margins while simultaneously accelerating consolidation toward backward-integrated grain processors. This utilization imbalance feeds pricing volatility that ripples through coating formulation costs and procurement contract structures.
Pricing Analysis
Cost-plus contracts indexed to Chicago Board of Trade grain futures dominate modified starch procurement in the coating industry. Three-tier pricing structure across premium clean-label, standard modified, and economy native starches separates suppliers by EFSA certification status and supply chain traceability. Pricing pressure stems from biofuel diversion competing for corn feedstock in US grain belts. Industrial snack manufacturers in Germany exhibit lowest price sensitivity, prioritizing formulation consistency and regulatory compliance over unit cost optimization.
Supply Chain Analysis
Contract manufacturing concentration rests with Cargill's captive starch facilities, Kerry Group's hydrocolloid research infrastructure, and Tate & Lyle's specialty texturant production. Geographic supply concentration centers on the United States, Germany, and the Netherlands. Raw material dependencies draw from North American grain belts for starch, Southeast Asian acacia plantations for gum arabic, and Dutch fermentation facilities for novel protein coatings. Single-source vulnerability persists for EFSA-certified clean-label hydrocolloids. Distribution runs through direct supplier-manufacturer partnerships that displace traditional ingredient distributors in high-volume snack segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived coating substrates present a substitution threat that incumbent suppliers must navigate through accelerated certification investments and research partnerships.
For Market Incumbents: Build regulatory certification moats by securing parallel EFSA and FDA approvals for fermentation-derived alternatives before novel entrants achieve commercial scale. Deepen backward integration into North American grain processing assets to insulate margin positions from biofuel-driven feedstock competition. Anchor single-source partnerships with German industrial bakery corridor manufacturers to lock out challenger suppliers. For New Entrants and Emerging Players: Precision microencapsulation capabilities in Netherlands research corridors represent the most penetrable entry point for bioactive and probiotic coating applications underserved by established suppliers. Target FSSAI certification infrastructure investment to bypass procedural delays blocking European and North American competitors in Maharashtra and Gujarat snack manufacturing hubs. Pursue co-development partnerships with Wageningen University research clusters to access proprietary deposition technology. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-derived coating substrate production as bioreactor scale-up requirements exceed traditional chemical processing thresholds. Long-term viability favors suppliers with demonstrated regulatory navigation across multiple jurisdictions rather than single-market specialists. Acquisition target archetype: mid-cap hydrocolloid specialists with EFSA clean-label certification and established relationships in German snack manufacturing. Monitor FSSAI import clearance timeline compression as inflection signal for competitive access shifts in Indian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Production | Cargill's captive grain processing secures supply continuity against biofuel diversion pressures. |
| EFSA Clean-Label Certification Investment | Kerry Group's hydrocolloid research infrastructure anchors premium positioning in additive-free European retail. |
| Precision Microencapsulation Partnership | Dutch research corridor collaborations enable reduced-temperature bioactive deposition for confectionery applications. |
| FSSAI Localized Certification Infrastructure | India-localized compliance capabilities bypass procedural delays blocking gum arabic and starch imports. |
| Single-Source Coating System Contracting | Direct partnerships with Cologne-Düsseldorf industrial bakeries displace distributor networks and lock formulation consistency. |
Methodological Framework
Initial hypotheses were tested against primary input from coating formulation scientists, snack manufacturing procurement directors, regulatory affairs specialists at hydrocolloid suppliers, and food technology researchers at Wageningen University clusters, then refined through secondary validation. Primary interviews combined with trade data from US Grains Council and FEFAC, SEC filings from agribusiness operators, EFSA guidance documents, and FSSAI import clearance records. Bottom-up volume modeling across application segments triangulated against top-down market sizing from grain processing capacity data.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include coating material chemistry, application physics, distribution channel structure, and regional regulatory cluster alignment. CAGRs were derived from capacity utilization trends and substitution elasticity estimates. Forecast inputs incorporated EFSA clean-label enforcement trajectory, FDA GRAS pathway evolution, and biofuel policy impacts on grain feedstock availability.
Macroeconomic conditions sit as an overlay; deviation in energy costs, currency volatility, and trade tariff regimes would shift the trajectory of coating ingredient trade flows and regional production economics. Forecasts reflect documented assumptions regarding regulatory approval timelines and substitution rates. Quarterly review of EFSA guidance updates, FSSAI clearance velocity, and North American grain belt planting forecasts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Food Texture Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Food Grade Silica Market