
 Argentina Food Hydrocolloids Market | 2026-2036
Argentina Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Food Hydrocolloids Market Outlook
Multi-source procurement among Argentine food manufacturers is realigning supply chain risk profiles across the hydrocolloid sector. Cargill, Incorporated leverages its grain-processing infrastructure to secure guar gum supply chains into the Pampas region. Kerry Group plc anchors its position through specialized texturizing systems tailored to local dairy and meat processors. Tate & Lyle PLC competes on clean-label positioning, drawing beverage formulators seeking reduced additive complexity.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify viscosity, gelation, and water-binding properties, typically functioning at concentrations between 0.1% and 2.0% by weight. These functional ingredients serve primarily as stabilizers, thickeners, and emulsifiers across processed food matrices. Guar gum dominates volume flows through the Argentine market due to regional oilseed processing proximity and cost-efficient supply logistics. Xanthan gum captures premium positioning within gluten-free bakery and beverage applications where cold-soluble rheology control commands higher formulation value. Carrageenan maintains entrenched demand in dairy products, particularly flan and dulce de leche production, though plant-based alternatives are displacing share in certain clean-label segments.
Argentina's national food safety regulator enforces CODEX Alimentarius-aligned additive maximum limits, while the Mercosur GMC resolutions standardize cross-border hydrocolloid approvals across the Southern Common Market. BIS-equivalent conformity assessments for imported hydrocolloid batches create entry friction for non-regional suppliers, privileging Mercosur-sourced materials. ANMAT's evolving stance on novel microbial fermentation-derived hydrocolloids will determine whether domestic biotech entrants can access commercial pathways previously reserved for established plant and seaweed extracts. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and Argentina's unilateral additive review timelines.
Market Dynamics
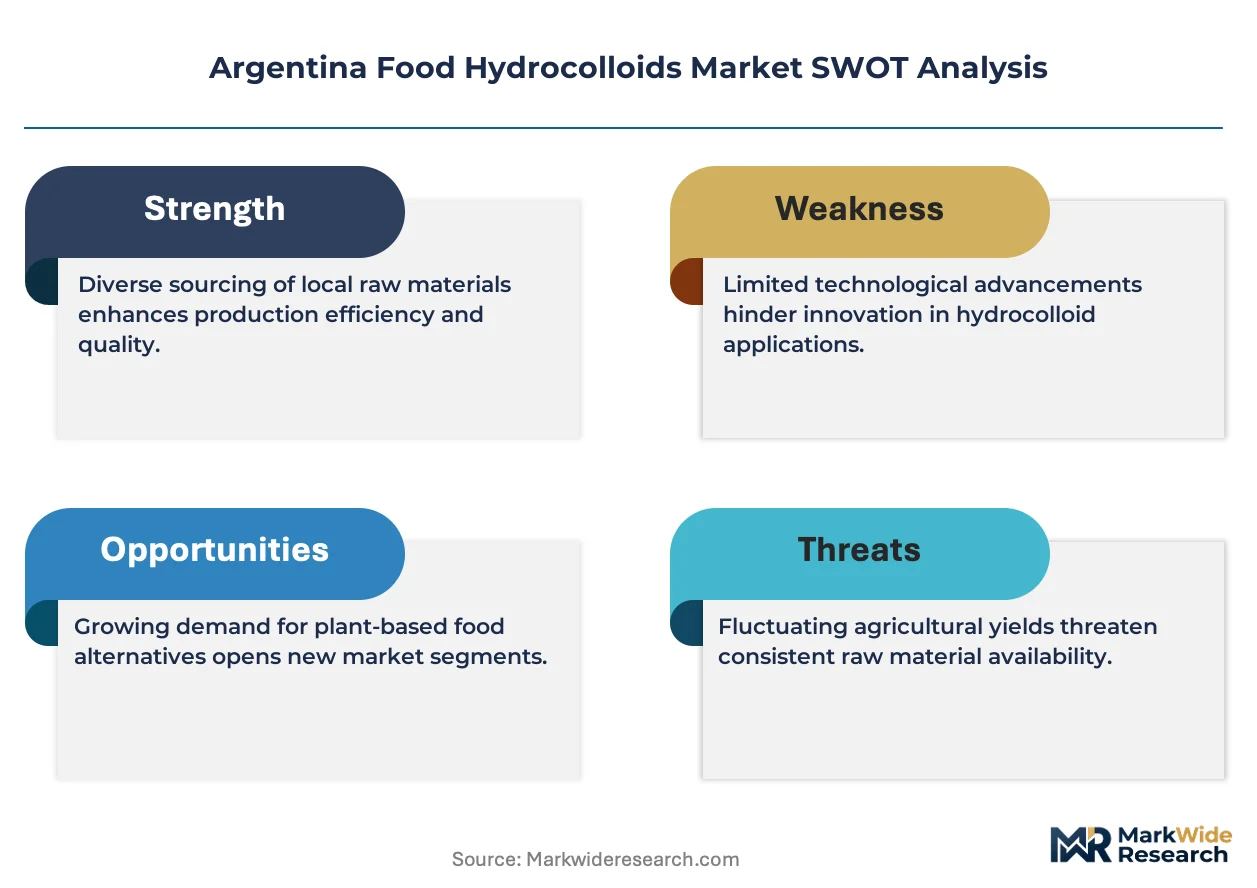
ANMAT's evolving stance on microbial fermentation-derived hydrocolloids is compressing approval timelines for domestic biotech entrants, forcing established suppliers to defend formulation relationships with dairy and meat processors across the Pampas belt.
Growth Catalysts
- Mercosur GMC Resolution harmonization:Cross-border additive approvals now standardize hydrocolloid specifications across Argentina, Brazil, and Uruguay, reducing formulation re-registration costs for regional manufacturers.
- Dairy texture stabilization demand:Dulce de leche and flan producers are expanding carrageenan and guar gum inclusions to achieve consistent thermal stability in high-sugar matrices.
- Pampas grain belt concentration:Food processing clusters in Buenos Aires and Santa Fe provinces generate concentrated procurement volumes that justify dedicated hydrocolloid distribution infrastructure.
Market Restraints
- Guar seed price volatility:Argentina's dependence on imported guar splits from India and Pakistan exposes formulators to currency-driven input cost swings.
- CODEX-aligned maximum limits:ANMAT's strict additive ceilings constrain high-performance hydrocolloid dosages in reduced-fat dairy applications.
- Seaweed extract supply concentration:Carrageenan processors face limited regional kelp sourcing, forcing reliance on Chilean and Southeast Asian suppliers.
Strategic Opportunities
- Cordoba province penetration:Emerging meat processing facilities in Argentina's second-largest dairy region remain underserved by specialized texturizing system providers.
- Clean-label fermentation pathways:ANMAT's anticipated novel food consultations for microbial cellulose and gellan variants could unlock premium positioning in beverage stabilization.
- Direct-to-processor digital channels:Specialized ingredient distributors are bypassing traditional Buenos Aires-based importers to serve Santa Fe formulators through platform-based procurement.
Industry Challenges
- Rheology technician scarcity:Argentine universities produce limited graduates trained in hydrocolloid hydration kinetics and synergistic blending protocols.
- BIS-equivalent conformity backlog:Import batch testing delays at ANMAT laboratories extend lead times for non-Mercosur hydrocolloid suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Food Hydrocolloids Market |
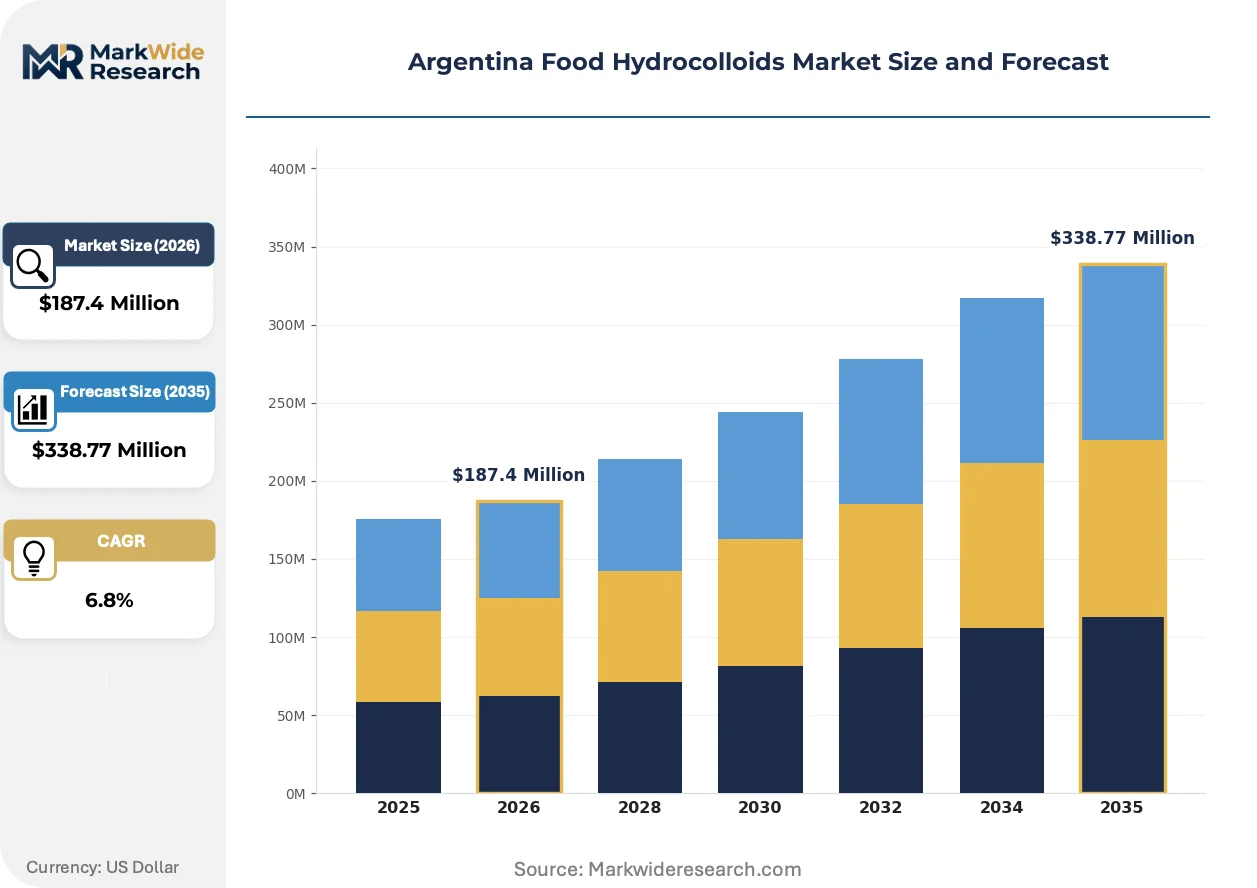
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Guar Gum, Xanthan Gum, Carrageenan Application: Dairy Products, Bakery, Meat Processing, Beverages Source: Plant-based, Seaweed-based, Microbial, Synthetic End User: Food Manufacturers, Beverage Companies, Restaurants, Catering Services |
| Companies Covered | CP Kelco, Tate & Lyle PLC, Cargill, Incorporated, Ashland Global Holdings Inc., Kerry Group plc, Ingredion Incorporated, W Hydrocolloids, Inc, FMC Corporation, DuPont, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Food Hydrocolloids Market Strategic Shifts
Formulation science is pivoting toward cold-process hydration systems that reduce energy inputs while expanding hydrocolloid functionality in heat-sensitive applications across Argentine dairy and beverage manufacturing.
Enzyme-modified guar derivatives are modularizing texturizing system architectures by enabling single-ingredient solutions that previously required three-component blends. Argentine yogurt and spreadable cheese processors are adopting these grades at accelerating rates. This compression is displacing traditional hydrocolloid combinations in mid-tier dairy formulations.
ANMAT's alignment with CODEX Alimentarius additive specifications is tightening maximum permitted levels for carrageenan in infant nutrition and specialized medical foods. Industrial consequence includes forced reformulation of legacy dairy matrices and accelerated substitution trials with locust bean gum and tara gum alternatives. Pediatric and clinical nutrition segments are responding by diversifying supplier qualifications across Mercosur-sourced hydrocolloids.
Ingredient specification workflows are compressing as Argentine food manufacturers consolidate approved vendor lists and mandate dual-source redundancy for critical texturizing inputs. Traditional Buenos Aires-based importer-distributors are losing share to direct technical service relationships with hydrocolloid producers. This channel restructuring is most visible among large-scale flan and dulce de leche manufacturers in Greater Buenos Aires seeking formulation partnership rather than commodity supply.
Argentina Food Hydrocolloids Market Segmentation
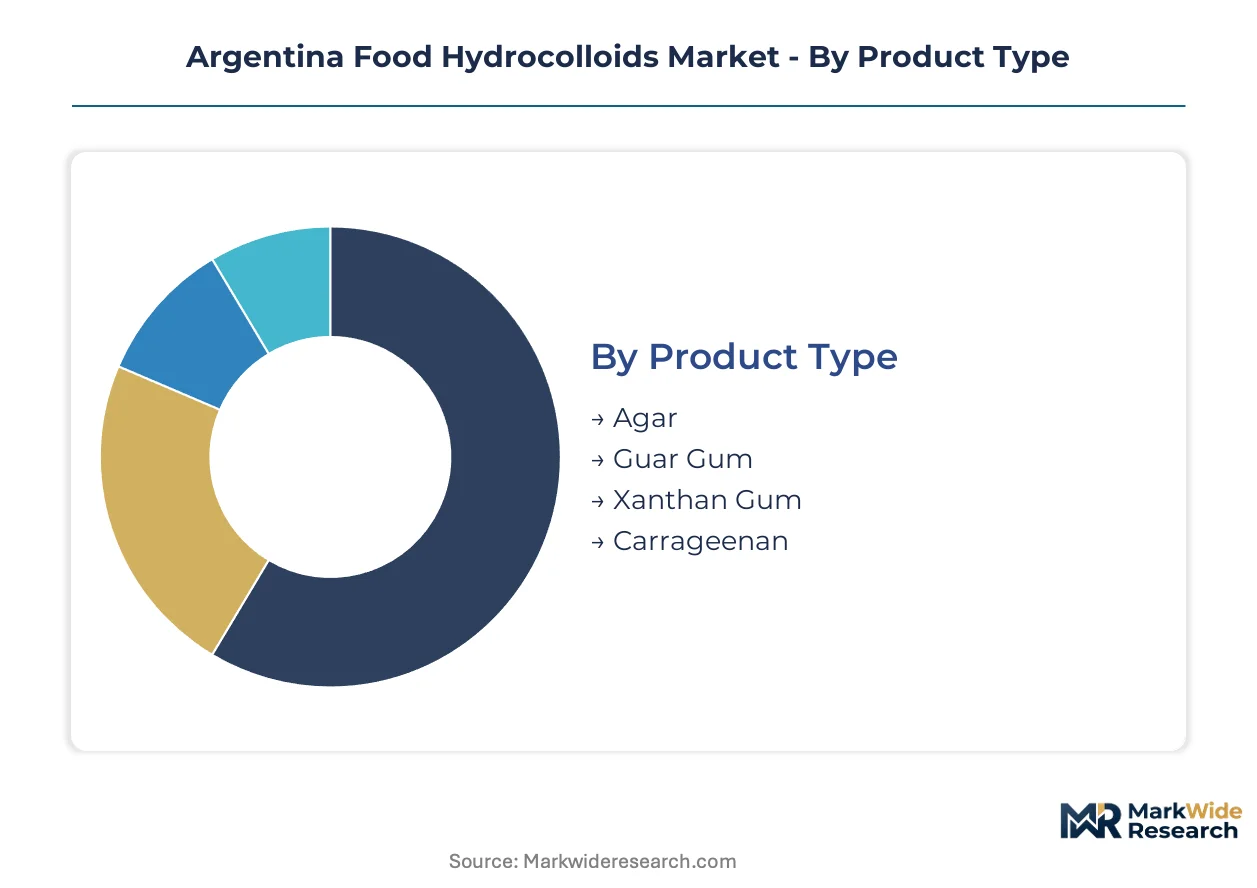
Hydrocolloid procurement decisions in Argentina hinge on functional performance in high-sugar dairy matrices, clean-label positioning, and ANMAT compliance pathways. Formulators balance cost efficiency against regulatory risk across four intersecting dimensions.
Product Type:
Buyers prioritize hydration kinetics and synergy profiles when specifying hydrocolloids for thermal processing environments.
- Guar Gum:Cold-water-soluble galactomannan derived from Cyamopsis tetragonoloba seeds. Pampas oilseed processing infrastructure enables competitive landed costs for Buenos Aires dairy clusters facing margin compression.
- Carrageenan:Sulfated polysaccharide extracted from red algae (Chondrus crispus, Gigartina species). Dulce de leche and flan manufacturers in Greater Buenos Aires specify kappa and iota grades for thermoreversible gelation, though ANMAT's CODEX-aligned limits constrain dosage ceilings in reduced-fat applications.
- Xanthan Gum:Microbial exopolysaccharide from Xanthomonas campestris fermentation. Gluten-free bakery formulators in Córdoba and Santa Fe provinces pay premium spreads for cold-soluble rheology control.
- Agar:Gel-forming polysaccharide from Gracilaria and Gelidium seaweeds. Limited Argentine demand concentrates in confectionery and specialized dessert applications with firm gel requirements.
Guar gum leads on scale; xanthan gum leads on momentum.
Application:
Processing technology and matrix composition determine hydrocolloid selection across Argentine food manufacturing.
- Dairy Products:Flan, dulce de leche, yogurt, and spreadable cheese matrices require carrageenan-guar synergies for thermal stability and mouthfeel. Santa Fe processors are expanding enzyme-modified guar adoption to simplify formulations.
- Bakery:Gluten-free bread and pastry segments in Córdoba specify xanthan gum for dough elasticity and moisture retention without wheat protein networks.
- Meat Processing:Reformed and emulsified meat applications in Buenos Aires province utilize carrageenan and modified starches for water-binding and sliceability.
- Beverages:Shelf-stable juices and flavored dairy drinks demand xanthan gum for pulp suspension and viscosity stability through pasteurization cycles.
Dairy applications anchor procurement volumes; bakery applications are climbing the fastest.
Source:
Supply chain provenance shapes regulatory pathway efficiency and clean-label market access.
- Plant-based:Guar, locust bean, and tara gums from Mercosur-sourced seeds face streamlined ANMAT approvals. Pampas grain belt processors prefer these for label simplicity.
- Seaweed-based:Carrageenan and agar from Chilean and Southeast Asian kelp harvests. Import documentation and BIS-equivalent testing create friction for non-regional suppliers.
- Microbial:Xanthan, gellan, and cellulose from controlled fermentation. ANMAT's evolving novel food consultations for domestic biotech production could unlock premium positioning.
- Synthetic:Chemically modified cellulose derivatives. Limited Argentine food use due to clean-label displacement and stricter additive scrutiny.
Plant-based sources dominate current procurement; microbial sources show steepest expansion trajectory.
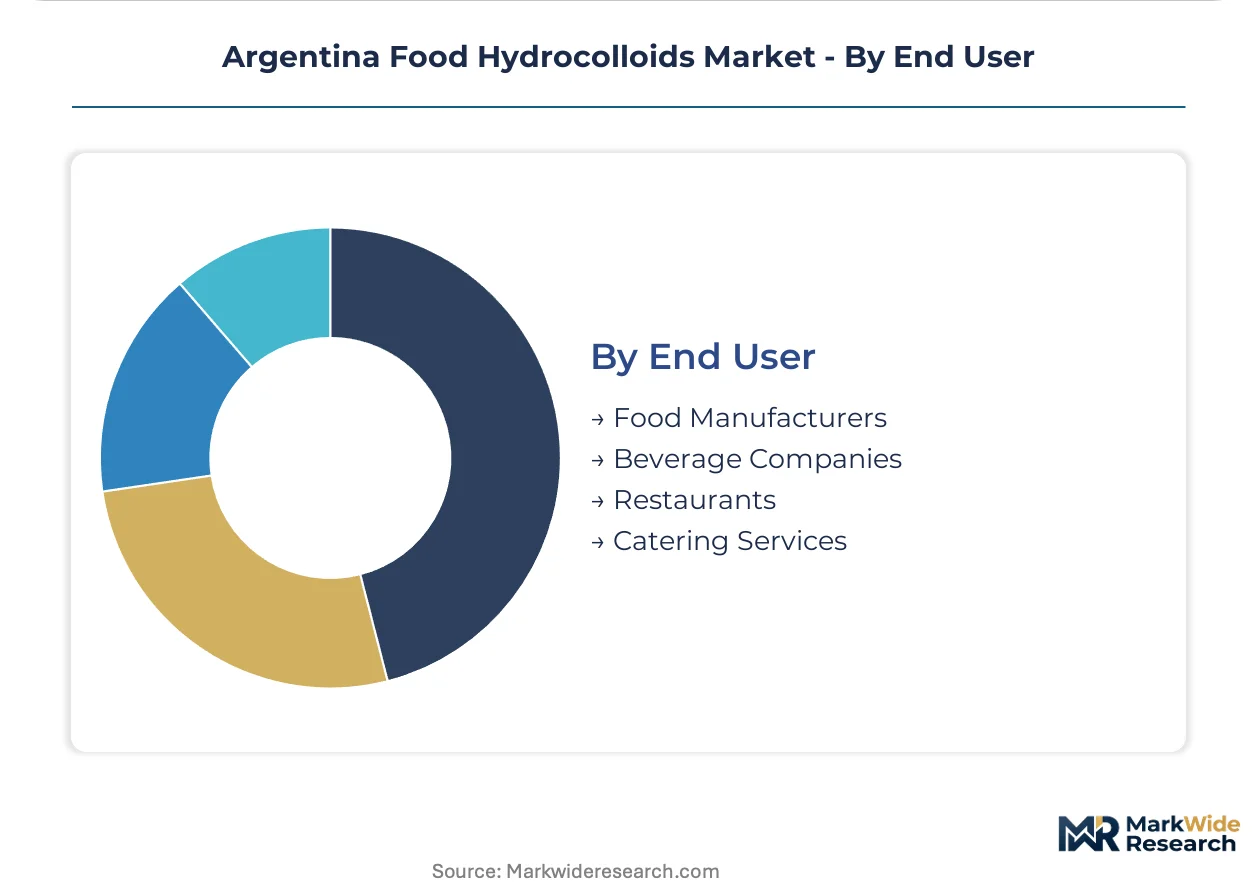
End User:
Scale and technical capability segment hydrocolloid service requirements across the Argentine market.
- Food Manufacturers:Industrial dairy, bakery, and meat processors in Buenos Aires and Santa Fe provinces drive bulk procurement. Large flan and dulce de leche producers are consolidating vendor lists and demanding direct technical partnerships.
- Beverage Companies:Carbonated soft drink and juice formulators specify hydrocolloids for stability and texture. Greater Buenos Aires concentration supports dedicated distribution infrastructure.
- Restaurants:Limited direct hydrocolloid procurement; primarily through prepared sauce and dessert mix suppliers.
- Catering Services:Institutional food service operators source through broadline distributors with limited technical specification involvement.
Food manufacturers command supply chain attention; beverage companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage opportunities in South America are concentrating hydrocolloid procurement decisions around Mercosur-aligned compliance pathways, with Argentine manufacturers leveraging cross-border additive approvals to reduce re-registration costs relative to non-regional importers.
Buenos Aires Province
Dulce de leche and flan manufacturers in Greater Buenos Aires drive concentrated demand for carrageenan-guar synergies. ANMAT's CODEX-aligned additive ceilings shape maximum dosage formulations across high-sugar dairy matrices. La Plata and Avellaneda industrial corridors host dedicated distribution infrastructure serving large-scale processors consolidating vendor lists.
Santa Fe Province
Enzyme-modified guar adoption is accelerating among yogurt and spreadable cheese processors seeking simplified single-ingredient solutions. Mercosur GMC Resolution harmonization streamlines cross-border approvals with Brazilian and Uruguayan suppliers. Rosario's agro-industrial cluster anchors regional procurement volumes for Pampas grain belt food manufacturers.
Córdoba Province
Gluten-free bakery formulators specify xanthan gum for dough elasticity in wheat-free bread and pastry applications. The country's national food safety authority enforces BIS-equivalent conformity assessments that create entry friction for non-regional hydrocolloid suppliers. Emerging meat processing facilities in the province remain underserved by specialized texturizing system providers.
Entre Ríos and Southern Pampas
Seaweed extract demand concentrates in confectionery applications requiring firm gel structures from agar and carrageenan. Limited regional kelp sourcing forces reliance on Chilean suppliers subject to import documentation delays. Paraná and Gualeguaychú processing nodes handle smaller-volume specialty hydrocolloid distribution to regional dessert manufacturers.
Argentina Food Hydrocolloids Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue microbial fermentation-derived positioning to capture premium clean-label segments. The Argentine market exhibits moderate concentration, with multinational ingredient houses anchoring supply relationships through technical service partnerships rather than pure commodity distribution. Three archetypes dominate: grain-processing conglomerates leveraging upstream infrastructure, specialized texturizing system formulators, and clean-label positioning specialists. Competitive dynamics center on direct-to-processor digital channel development and dual-source redundancy mandates from large-scale dairy manufacturers.
Among the named suppliers, Cargill, Incorporated exemplifies the grain-processing archetype through Pampas region infrastructure integration. Tate & Lyle PLC and Kerry Group plc occupy differentiated positioning tiers, with the former representing clean-label formulation partnerships and the latter anchoring specialized dairy and meat processing technical relationships. These three companies illustrate the competitive spectrum from commodity-scale supply to value-added formulation collaboration.
| Leading Market Players |
|---|
| CP Kelco |
| Tate & Lyle PLC |
| Cargill, Incorporated |
| Ashland Global Holdings Inc. |
| Kerry Group plc |
| Ingredion Incorporated |
| W Hydrocolloids, Inc |
| FMC Corporation |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Large-scale flan and dulce de leche manufacturers in Greater Buenos Aires are consolidating vendor lists and demanding direct technical partnerships, forcing hydrocolloid suppliers to absorb service costs and compress margins on commodity-grade guar and carrageenan offerings. This procurement concentration is reshaping pricing power dynamics across the Argentine market.
Pricing Analysis
Input-cost pass-through from guar seed and kelp raw materials dominates Argentine hydrocolloid pricing structures, with Indian and Pakistani guar split volatility transmitting directly to Pampas dairy processor contracts. Three-tier pricing structure across premium, standard, and economy levels separates enzyme-modified guar derivatives from commodity grades and imported xanthan gum. Pricing pressure stems from currency-driven input cost swings and buyer consolidation in Greater Buenos Aires. Mid-tier dairy processors exhibit highest price sensitivity, while gluten-free bakery formulators in Córdoba accept premium spreads for cold-soluble rheology control.
Supply Chain Analysis
Ocean freight costs from Indian guar processing hubs and Chilean kelp harvesting regions anchor landed cost structures for Argentine hydrocolloid distributors. Supply concentrates in India, Pakistan, and Chile for guar splits, carrageenan, and agar raw materials, with domestic Pampas oilseed infrastructure providing limited regional sourcing. Raw material dependencies include guar seeds, red algae biomass, and fermentation feedstocks for microbial gums. Single-source vulnerability pervades kelp extract supply chains. Distribution runs through Buenos Aires-based importer-distributors and emerging direct-to-processor digital channels serving Santa Fe formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's food hydrocolloid market has entered a late-cycle quality phase, with enzyme-modified guar derivatives and microbial fermentation pathways commanding formulation partnerships as dairy processors abandon commodity procurement.
For Market Incumbents: Lock in long-term supply agreements with Pampas grain belt processors before ANMAT completes novel food consultations for domestic biotech entrants. Secure dual-source redundancy mandates from large-scale flan manufacturers by investing in Cordoba province technical service infrastructure. Defend against clean-label displacement by accelerating fermentation-derived hydrocolloid registration timelines. For New Entrants and Emerging Players: Launch via direct-to-processor digital channels targeting Santa Fe yogurt and spreadable cheese processors underserved by traditional Buenos Aires importers. Penetrate the gluten-free bakery segment in Córdoba through technical partnerships with xanthan gum formulators seeking local supply alternatives. Exploit ANMAT's compressed approval timelines for microbial cellulose and gellan variants. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized texturizing system formulators possessing Mercosur GMC Resolution harmonization expertise and direct technical relationships with Pampas dairy clusters. Over a multi-year horizon, consolidation rewards players bridging commodity supply and formulation partnership capabilities. Monitor ANMAT's stance on novel microbial fermentation-derived hydrocolloids as the critical inflection signal for premium segment access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Seed Processing | Cargill leverages Pampas grain infrastructure to secure supply chains against Indian import volatility. |
| Enzyme-Modified Guar R&D Investment | Kerry Group anchors dairy partnerships through single-ingredient solutions displacing three-component blends. |
| Mercosur GMC Resolution Harmonization | Tate & Lyle reduces re-registration costs for clean-label beverage formulators across Argentina, Brazil, and Uruguay. |
| Direct-to-Processor Digital Channel Development | Specialized distributors bypass Buenos Aires importers to serve Santa Fe formulators through platform-based procurement. |
| Novel Food Consultation Preparation | Domestic biotech entrants position for ANMAT approval pathways previously reserved for plant and seaweed extracts. |
Study Parameters
Coverage spans Buenos Aires, Santa Fe, Córdoba, and Entre Ríos provinces, with primary inputs from each region's food processing clusters. The analysis combines primary interviews with dairy formulation managers, meat processing procurement leads, hydrocolloid distributor technical directors, and ANMAT regulatory affairs specialists with secondary validation. Secondary sources include ANMAT additive registration databases, Mercosur GMC Resolution filings, CODEX Alimentarius standards, and Argentine customs trade records. Bottom-up procurement volume estimates triangulate against top-down market sizing from industry association data.
Granularity-level modeling disaggregates the Argentine market by product type, application matrix, source origin, and end-user scale across the projection horizon. Segmentation dimensions include hydrocolloid chemistry, thermal processing requirements, regulatory compliance pathway, and processor technical capability tier. CAGRs derive from trend extrapolation of enzyme-modified guar adoption rates and microbial fermentation pathway penetration assumptions. Forecast inputs incorporate ANMAT consultation timelines and Mercosur harmonization progress.
Several conditions sit outside the modeled scope, including unilateral Argentine regulatory divergences from Mercosur, extreme guar seed price volatility events, and biotech production scale-up failures. Forecasts reflect assumptions about ANMAT's evolving stance on novel hydrocolloids and processor willingness to reformulate legacy matrices. Stakeholders should weight assumptions against their own operating context and regulatory risk tolerance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market