
 Fermentation Defoamer Market | 2026-2036
Fermentation Defoamer Market Size, Share, and Industry Trends Forecast 2026-2036
Fermentation Defoamer Market Analysis
Specialty pharmaceutical manufacturers are redrawing the buyer landscape for fermentation defoamers as biologics capacity expands worldwide. Dow Inc. leverages its silicone supply chain to dominate high-purity pharmaceutical grades. BASF SE anchors its position through backward integration into polyether polyols for organic defoamer variants. Wacker Chemie AG specializes in emulsion technologies that serve brewing and beverage clients across Europe.
Fermentation defoamers are surface-active formulations, typically silicone oils, polyethers, or organic compounds, engineered to collapse foam lamellae in aerobic bioprocesses by reducing interfacial tension below critical thresholds. They maintain oxygen transfer rates and prevent vessel overflow in stirred-tank reactors operating at volumes exceeding 10,000 liters. Silicone-based formulations command the largest share due to thermal stability and rapid knockdown performance, while polyether types represent the fastest-growing category as biofuel producers seek biodegradable alternatives compatible with downstream processing. Liquid formulations occupy the dominant position in automated dosing systems, though emulsion concentrates are gaining share where water-based dilution reduces shipping costs and handling hazards.
EPA effluent guidelines under the Clean Water Act constrain silicone discharge limits from fermentation facilities in the United States, pushing reformulation toward organo-modified siloxanes with improved biodegradation profiles. REACH registration requirements in Europe mandate full toxicological dossiers for polyether amines and copolymer surfactants above one-tonne annual thresholds, elevating compliance costs for imported formulations. China's MEE enforces stricter volatile organic compound limits on solvent-based defoamer carriers, favoring aqueous emulsion technologies in domestic production. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global product platforms offer superior returns.
Market Dynamics
Silicone supply concentration in Germany and China is forcing biofuel and pharmaceutical manufacturers to dual-source defoamer formulations, restructuring procurement relationships and elevating backward integration incentives among large-scale fermentation operators.
Growth Catalysts
- REACH Registration Thresholds:ECHA's one-tonne annual dossier requirements for polyether amines are accelerating compliance investments, filtering out low-volume importers and consolidating supplier bases among qualified European formulators.
- Biofuel Mandate Expansion:Renewable fuel obligations across EU member states are pulling silicone and biodegradable polyether defoamers into new ethanol and biogas facilities at commercial scale.
- Stainless Steel Reactor Proliferation:10,000+ liter stirred-tank installations in China and the United States are automating defoamer dosing systems, embedding continuous demand for liquid formulation compatibility.
Market Restraints
- Silicone Feedstock Concentration:Chlorosilane precursor supply clusters in the German Rhineland and China's Jiangsu province create geographic vulnerability for Western formulators lacking captive silicon metal sourcing.
- EPA Effluent Limits:Clean Water Act discharge constraints on siloxane residues are adding treatment capital burdens to US fermentation facilities, compressing operating margins for smaller biofuel producers.
- Polyether Biodegradability Trade-offs:Enhanced environmental degradability in organic defoamers correlates with reduced thermal stability above 80°C, limiting applicability in high-temperature pharmaceutical fermentation.
Strategic Opportunities
- India Biologics Capacity:CDSCO's streamlined biologics approval pathways are attracting contract manufacturing investment, creating virgin territory for pharmaceutical-grade defoamer penetration.
- Aqueous Emulsion Technologies:Water-based carrier systems compatible with China's MEE volatile organic compound limits are opening substitution windows against solvent-based legacy formulations.
- Precision Fermentation:Cell-cultured protein and dairy alternatives are emerging as defoamer-intensive applications, with oxygen transfer requirements matching traditional biofuel scale.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in organo-modified siloxane synthesis and polyether copolymer design concentrates among retiring specialists in Germany and the United States, constraining R&D pipeline velocity.
- REACH Dossier Timelines:Full toxicological registration for novel polyether structures requires 18-24 month ECHA review cycles, delaying product launch windows and freezing formulation innovation.
- Legacy Dosing System Retrofit:Automated injection infrastructure at existing fermentation facilities demands mechanical compatibility validation, extending sales cycles and inflating technical service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermentation Defoamer Market |
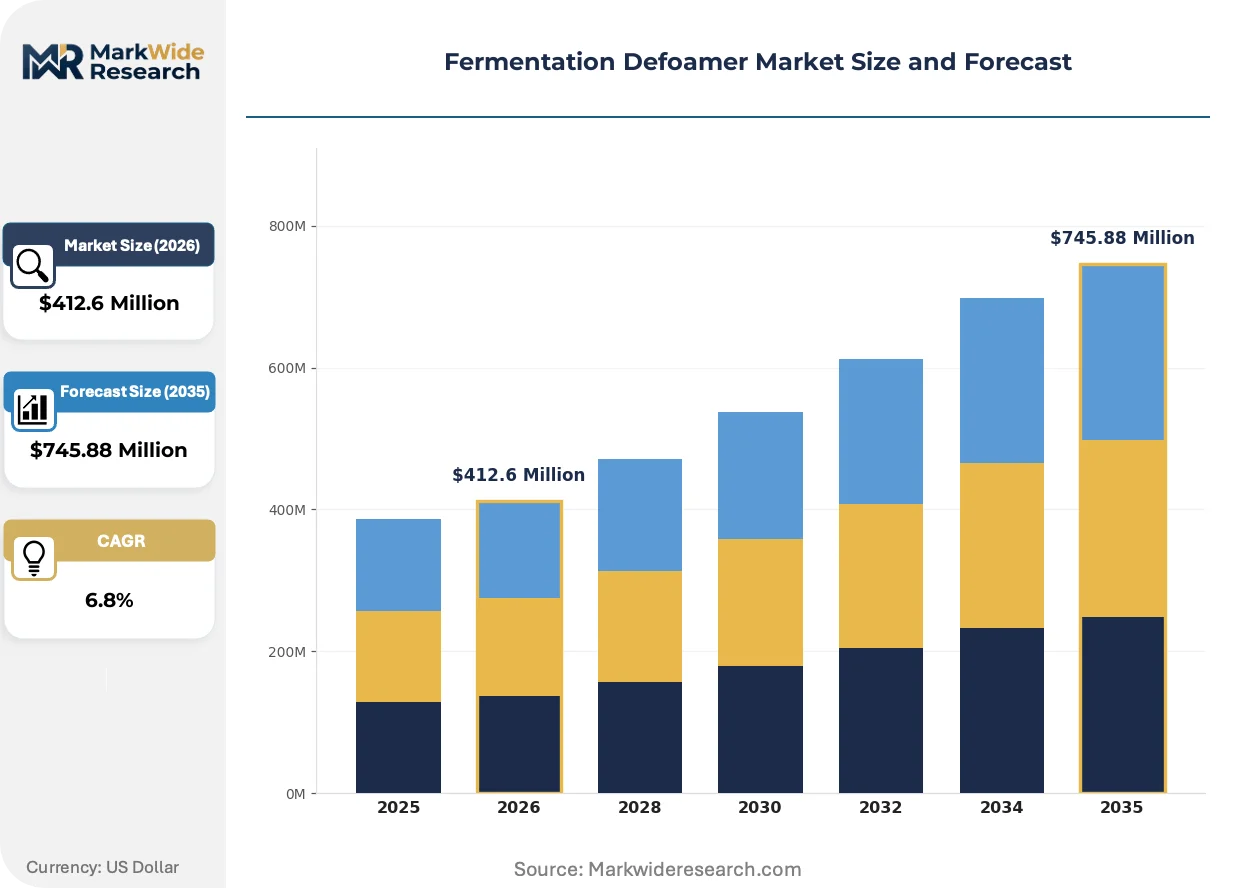
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-based, Organic, Polyether, Copolymer End User: Beverage Industry, Biofuel Production, Pharmaceutical, Agriculture Formulation: Liquid, Powder, Emulsion, Concentrate Application: Wastewater Treatment, Fermentation Processes, Food Processing, Brewing |
| Companies Covered | Shin-Etsu Chemical, Dow Inc., DuPont, Emerald Performance Materials, BASF SE, Momentive Performance Materials, Evonik Industries, Elkem Silicones, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermentation Defoamer Market Emerging Trajectories
Formulation chemistry is pivoting toward regulatory-compliant alternatives as silicone discharge limits tighten and biodegradable performance standards advance across major fermentation economies.
Organo-modified siloxanes with engineered biodegradation profiles are displacing conventional polydimethylsiloxane fluids in European pharmaceutical and biofuel applications. BASF and Wacker Chemie are scaling emulsion concentrates for automated dosing systems. This displacement is compressing market share for unmodified silicone oils while elevating R&D spend on siloxane backbone modification.
REACH Annex XVII restrictions on persistent organic pollutants are compelling reformulation of polyether amine surfactants used in organic defoamer variants. ECHA's 2023 updated guidance on biodegradation testing protocols is forcing suppliers to resubmit dossiers. Biofuel producers in Germany and the Netherlands are accelerating qualification of compliant alternatives to avoid supply interruption.
Buyers are consolidating annual defoamer volumes into multi-year framework agreements with technical service attachments, displacing spot purchasing through regional distributors. Large-scale fermentation operators in China and the United States are embedding supplier engineers on-site for dosing optimization. This concentration is visible most acutely in biofuel hubs around Rotterdam and the US Midwest corn belt.
Fermentation Defoamer Market Segmentation
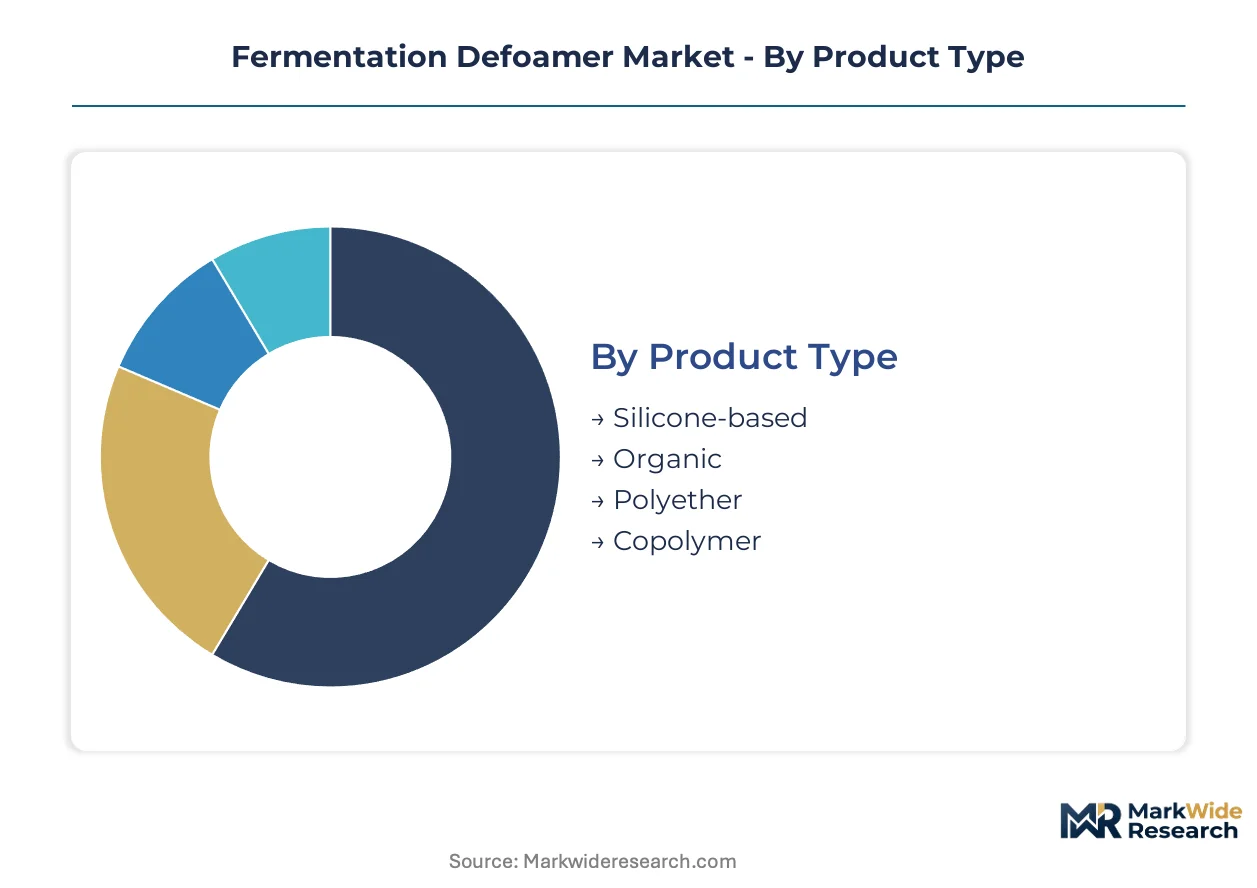
Fermentation defoamer segmentation reflects divergent regulatory pressures across major jurisdictions. Formulation chemistry, end-use requirements, and dosing infrastructure compatibility determine procurement decisions at scale.
Product Type:
REACH registration thresholds and EPA effluent limits are segmenting supplier qualification across silicone and organic chemistries.
- Silicone-based:Polydimethylsiloxane fluids dominate pharmaceutical and large-scale biofuel applications due to thermal stability above 120°C and rapid foam knockdown. Demand concentrates in Germany and the United States where stainless steel reactor installations exceed 10,000 liters, though EPA Clean Water Act discharge constraints are elevating treatment costs for US facilities.
- Polyether:Biodegradable copolymer structures are displacing conventional silicones in European biofuel plants subject to REACH Annex XVII persistent pollutant restrictions. ECHA's 2023 updated biodegradation testing protocols are forcing dossier resubmissions, compressing supplier margins while opening share for compliant formulators.
- Organic:Vegetable oil and fatty acid derivatives serve brewing and beverage applications with moderate temperature requirements.
- Copolymer:Silicone-polyether hybrids balance thermal performance with environmental degradability for precision fermentation operators.
Established volume favors silicone-based formulations; emerging adoption favors polyether alternatives.
End User:
Customer scale and dosing automation intensity are reshaping procurement relationships across fermentation verticals.
- Biofuel Production:Ethanol and biogas facilities in the US Midwest and Rotterdam corridor are embedding supplier engineers on-site for continuous dosing optimization. Renewable fuel mandates across EU member states are pulling volume into multi-year framework agreements with technical service attachments.
- Pharmaceutical:Biologics manufacturers demand high-purity grades with full toxicological dossiers for EMA and FDA submissions. CDSCO's streamlined biologics pathways in India are attracting contract manufacturing investment, creating virgin territory for pharmaceutical-grade penetration.
- Beverage Industry:Brewing and spirits producers favor aqueous emulsion technologies compatible with water-for-injection standards.
- Agriculture:Fermentation-based feed additive producers prioritize cost efficiency over thermal performance in smaller batch reactors.
Pharmaceutical and biofuel production concentrate procurement volume; beverage industry applications are climbing fastest on emulsion technology adoption.
Formulation:
Physical state determines shipping economics, handling safety, and dosing system compatibility across automated fermentation infrastructure.
- Liquid:Pump-ready fluids dominate automated injection systems at commercial-scale facilities. China's MEE volatile organic compound limits are favoring aqueous carriers over solvent-based legacy formulations in domestic production.
- Emulsion:Water-based concentrates reduce shipping costs and handling hazards where dilution occurs at point of use. BASF and Wacker Chemie are scaling emulsion technologies for European brewing and beverage clients.
- Concentrate:High-active formulations serve remote biofuel facilities with limited on-site storage capacity.
- Powder:Solid carriers persist in small-batch agricultural fermentation where dosing precision matters less than shelf stability.
Liquid formulations anchor installed dosing infrastructure; emulsion systems are gaining share fastest on water-based regulatory compliance.
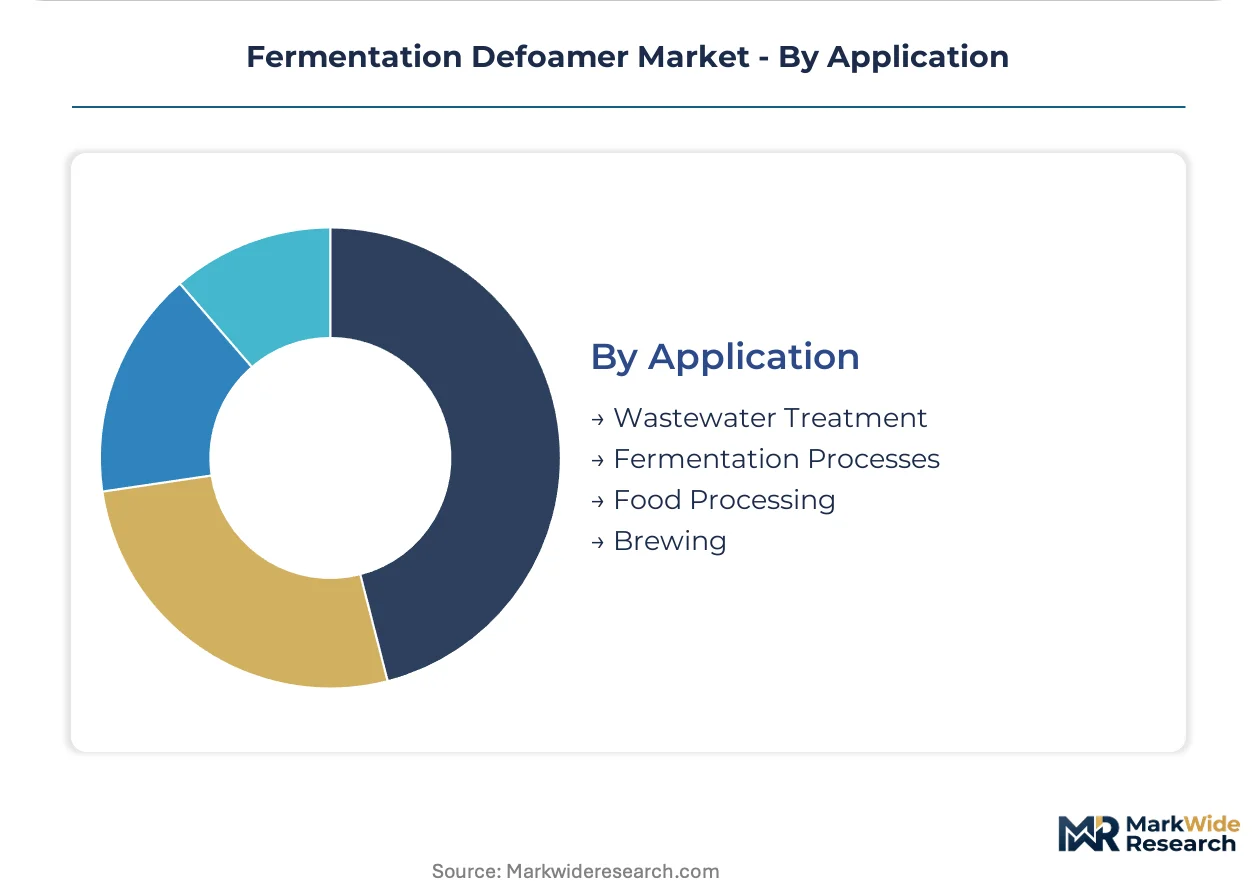
Application:
Oxygen transfer requirements and foam generation intensity vary sharply across downstream processing contexts.
- Fermentation Processes:Aerobic bioprocesses in stirred-tank reactors generate the highest foam loads and most demanding oxygen transfer maintenance. Stainless steel reactor proliferation in China and the United States is automating defoamer dosing at commercial scale.
- Brewing:Wort boiling and fermentation stages require food-grade formulations with flavor-neutral profiles. European craft brewery expansion is sustaining demand for silicone-free organic alternatives.
- Wastewater Treatment:Anaerobic digester foam control in municipal facilities employs lower-cost polyether variants with reduced thermal specifications.
- Food Processing:Fermented ingredient production for flavors and enzymes operates under FSSAI, FDA, and EFSA food contact regulations.
Fermentation processes command the dominant volume share; brewing applications are expanding most quickly on craft sector growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports silicone-based defoamer formulations to biofuel producers across the European Union, while China supplies polyether variants to fermentation facilities in Southeast Asia and the Middle East.
United States
Biofuel producers in the US Midwest corn belt drive concentrated demand for automated dosing-compatible liquid formulations. EPA effluent guidelines under the Clean Water Act constrain silicone discharge limits from fermentation facilities, elevating treatment capital burdens. Stainless steel reactor installations exceeding 10,000 liters in Iowa and Illinois are embedding supplier engineers on-site for continuous optimization.
Germany
REACH registration thresholds for polyether amines filter out low-volume importers and consolidate supplier bases among qualified European formulators. ECHA's 2023 updated biodegradation testing protocols force dossier resubmissions, compressing margins for non-compliant suppliers. The Rhineland chlorosilane precursor cluster anchors silicone supply chain concentration, creating geographic vulnerability for Western formulators lacking captive silicon metal sourcing.
China
Large-scale fermentation facilities in Jiangsu province and the Yangtze River Delta drive volume demand for aqueous emulsion technologies. MEE enforces stricter volatile organic compound limits on solvent-based defoamer carriers, favoring water-based formulations in domestic production. Stainless steel reactor proliferation automates defoamer dosing systems at commercial scale across Shandong and Guangdong provinces.
India
CDSCO's streamlined biologics approval pathways attract contract manufacturing investment, creating virgin territory for pharmaceutical-grade defoamer penetration. FSSAI food contact regulations govern fermented ingredient production for flavors and enzymes. Maharashtra and Karnataka host emerging biologics capacity clusters where high-purity grades with full toxicological dossiers command procurement priority.
Netherlands
Rotterdam corridor biofuel facilities embed supplier engineers on-site for continuous dosing optimization under EU renewable fuel mandates. REACH Annex XVII restrictions on persistent organic pollutants compel reformulation of polyether amine surfactants. The port cluster concentrates ethanol and biogas production volume, pulling silicone and biodegradable polyether defoamers into multi-year framework agreements.
Fermentation Defoamer Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with captive silicone supply chains. The supplier base concentrates among formulators with backward integration into chlorosilane precursors or polyether polyols. Three archetypes dominate: integrated silicone producers, polyether specialists with REACH dossier capabilities, and emulsion technology providers serving automated dosing systems. Competitive moves center on capacity expansion in aqueous emulsion technologies and strategic partnerships with large-scale fermentation operators for on-site technical service embedding.
Within the integrated silicone producer tier, Dow Inc. and Shin-Etsu Chemical occupy positions anchored by captive chlorosilane supply. BASF SE exemplifies the polyether specialist archetype with backward integration into polyether polyols for organic defoamer variants. Wacker Chemie AG sits within the emulsion technology provider category, representing European brewing and beverage client service capabilities. These three companies illustrate how formulation chemistry expertise and regulatory dossier capabilities determine competitive positioning across pharmaceutical and biofuel end-use segments.
| Leading Market Players |
|---|
| Shin-Etsu Chemical |
| Dow Inc. |
| DuPont |
| Emerald Performance Materials |
| BASF SE |
| Momentive Performance Materials |
| Evonik Industries |
| Elkem Silicones |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Multi-year framework agreements with embedded technical service attachments lock in supply access for biofuel producers while anchoring price visibility across volatile silicone feedstock cycles. These structures concentrate procurement power among large-scale fermentation operators in Germany, China, and the United States who can commit to annual volume thresholds above one tonne.
Pricing Analysis
Next-generation organo-modified siloxanes command 15-25% premiums over conventional polydimethylsiloxane fluids due to REACH-compliant biodegradation profiles. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and economy-grade formulations reflects certification intensity and toxicological dossier completeness. Cost compression in standard silicone oils is intensifying as EPA effluent limits elevate treatment burdens for US facilities. Biofuel producers in the US Midwest exhibit highest price sensitivity due to margin pressure from renewable fuel credit volatility, while pharmaceutical manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Germany and China anchor chlorosilane precursor production, with the Rhineland and Jiangsu province hosting concentrated silicone feedstock capacity. Formulation chemistry draws from silicon metal, polyether polyols, and organo-modified surfactant intermediates. Single-source vulnerability runs through German chlorosilane clusters exposed to energy cost volatility and regulatory inspection backlogs. Distribution runs through qualified formulator networks with REACH dossier capabilities, bypassing spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH registration and EPA effluent compliance creates defensive moats for incumbent formulators with established toxicological dossiers. Switching costs for large-scale fermentation operators exceed 18-24 months given dosing system validation requirements.
For Market Incumbents: Shield market position by deepening backward integration into chlorosilane precursors or polyether polyol supply. Prioritize capacity addition in aqueous emulsion technologies compatible with China's MEE volatile organic compound limits. Emerging polyether specialists with streamlined REACH dossiers pose substitution threats in European biofuel applications. For New Entrants and Emerging Players: CDSCO fast-track certification for pharmaceutical-grade defoamers unlocks penetration into India's expanding biologics contract manufacturing clusters. White-space targets include precision fermentation operators seeking silicone-polyether hybrid formulations and craft brewing facilities demanding flavor-neutral organic alternatives. Go-to-market angle centers on on-site dosing optimization services bundled with emulsion concentrate supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated silicone producers with captive chlorosilane supply and long-term framework agreements with biofuel majors. Five-to-ten year viability favors formulators with REACH dossier capabilities across both silicone and polyether chemistries. Acquisition target archetype: mid-cap emulsion technology specialists serving automated dosing infrastructure. Signal to watch: ECHA enforcement actions against non-compliant polyether amine surfactants.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Expansion | ECHA registration thresholds filter out low-volume importers, consolidating qualified supplier bases. |
| Aqueous Emulsion Scale-Up | Water-based formulations align with China's MEE volatile organic compound enforcement priorities. |
| Backward Integration | Captive chlorosilane supply insulates margin pressure from German Rhineland feedstock concentration. |
| On-Site Technical Embedding | Supplier engineers at Rotterdam and US Midwest biofuel hubs lock in multi-year framework agreements. |
| India Market Entry | CDSCO streamlined pathways attract contract manufacturing investment in Maharashtra biologics clusters. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, procurement leads at biofuel and pharmaceutical manufacturers, technical R&D directors at formulator companies, and distribution channel partners; and secondary validation through ECHA registration databases, EPA effluent guideline filings, customs trade records, and SEC disclosures from integrated chemical conglomerates. Bottom-up volume estimates from individual facility capacities were triangulated against top-down market sizing from trade association reports.
Across the analysis window, the forecasting framework modeled segmentation dimensions including formulation chemistry type, end-use vertical, physical state, and regional regulatory cluster. CAGRs were derived from weighted capacity expansion pipelines and mandate-driven demand elasticity. Industry-specific inputs incorporated stainless steel reactor installation trajectories in China and the United States, plus renewable fuel obligation schedules across EU member states.
Underlying assumptions cover regulatory enforcement continuity, feedstock price stability, and dosing automation adoption curves, with deviation risk concentrated in ECHA dossier review timelines and EPA effluent limit revisions. Recalibration cycles align with material shifts in REACH Annex XVII restrictions and biologics capacity investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Food Texture Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Clean Label Pectin Market