
 Food Grade Antifoams Market | 2026-2036
Food Grade Antifoams Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Antifoams Market Foresight
Silicone emulsion technology is tilting formulation priorities toward lower-dose, higher-efficiency antifoam systems that reduce carryover risk in pasteurized dairy lines. Evonik Industries AG leverages its organosilicon R&D pipeline to sustain premium positioning in European beverage applications. Dow Consumer Solutions anchors North American supply through backward integration into polydimethylsiloxane feedstocks. BASF SE competes on mineral oil-based alternatives for cost-sensitive baking facilities in emerging markets.
Food grade antifoams comprise surface-active agents, predominantly silicone compounds, polyglycols, or refined vegetable oils, engineered to destabilize foam lamellae at concentrations typically below 100 ppm in process streams. Their primary commercial purpose centers on maintaining throughput rates in continuous dairy evaporation, beverage carbonation, and vegetable oil refining where entrained air degrades heat transfer efficiency. Silicone-based formulations occupy the dominant value share owing to thermal stability above 150°C and rapid knockdown kinetics in high-shear environments. Polyether-based variants represent the fastest-expanding category as clean-label pressures from European retailers disfavor silicone residues in organic product lines. Liquid emulsions concentrate margin pools due to ease of automated dosing integration versus powder or paste formats that require pre-dispersion equipment.
FDA 21 CFR 173.340 governs permissible defoaming agents in food-contact applications, while the EU F-Gas Regulation and REACH constrain silicone precursor chemistries through perfluorinated compound restrictions and substance registration mandates. BIS certification requirements in India and China's GB 2760 food additive standards create divergent compliance pathways that fragment formulation portfolios for multinational suppliers. Stakeholders must monitor evolving national positive lists for antifoam carryover limits as regional regulators tighten analytical detection thresholds for residual silicones in finished consumer products.
Market Dynamics
Silicone-to-polyether formulation migration is compressing incumbent technology margins while fragmenting supplier portfolios across organic-certified dairy chains. REACH substance restrictions and EU F-Gas precursor constraints are forcing simultaneous chemistry switches and supply base diversification.
Growth Catalysts
- EU organic label expansion:Retailer clean-label mandates in Germany and France are accelerating polyether antifoam qualification programs for pasteurized milk packaging lines.
- Continuous evaporation throughput pressure:Dairy processors in India and China are automating dosing systems to minimize foam-related heat transfer losses in whey concentration stages.
- GB 2760 additive standard updates:China's SAMR is expanding the positive list for food-grade emulsion carriers, enabling faster local registration for international suppliers.
Market Restraints
- Dimethyl silicone feedstock concentration:Polydimethylsiloxane precursor supply clusters in Germany and the US, exposing formulators to freight-driven cost volatility.
- Clean-label silicone residue thresholds:EFSA detection methodology improvements are tightening analytical limits for residual silicones in finished organic products.
- Polyether glycol ether supply fragility:Ethylene oxide derivative availability fluctuates with European petrochemical cracker operating rates.
Strategic Opportunities
- Indian dairy cooperative modernization:FSSAI-aligned state milk federations in Gujarat and Maharashtra are retrofitting evaporators with automated antifoam injection skids.
- Plant-based beverage foaming chemistry:Oat and pea protein extraction lines require customized antifoam formulations distinct from legacy dairy applications.
- Carbon accounting integration:EU Green Deal scope-3 disclosure rules are creating preference for regionally manufactured emulsions with verified transport emissions.
Industry Challenges
- Organic certification timeline compression:EU 2018/848 regulation implementation is extending antifoam requalification cycles from 12 to 24 months.
- Legacy dosing equipment incompatibility:High-viscosity silicone pastes require pre-dispersion systems that clash with automated emulsion injection infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Antifoams Market |
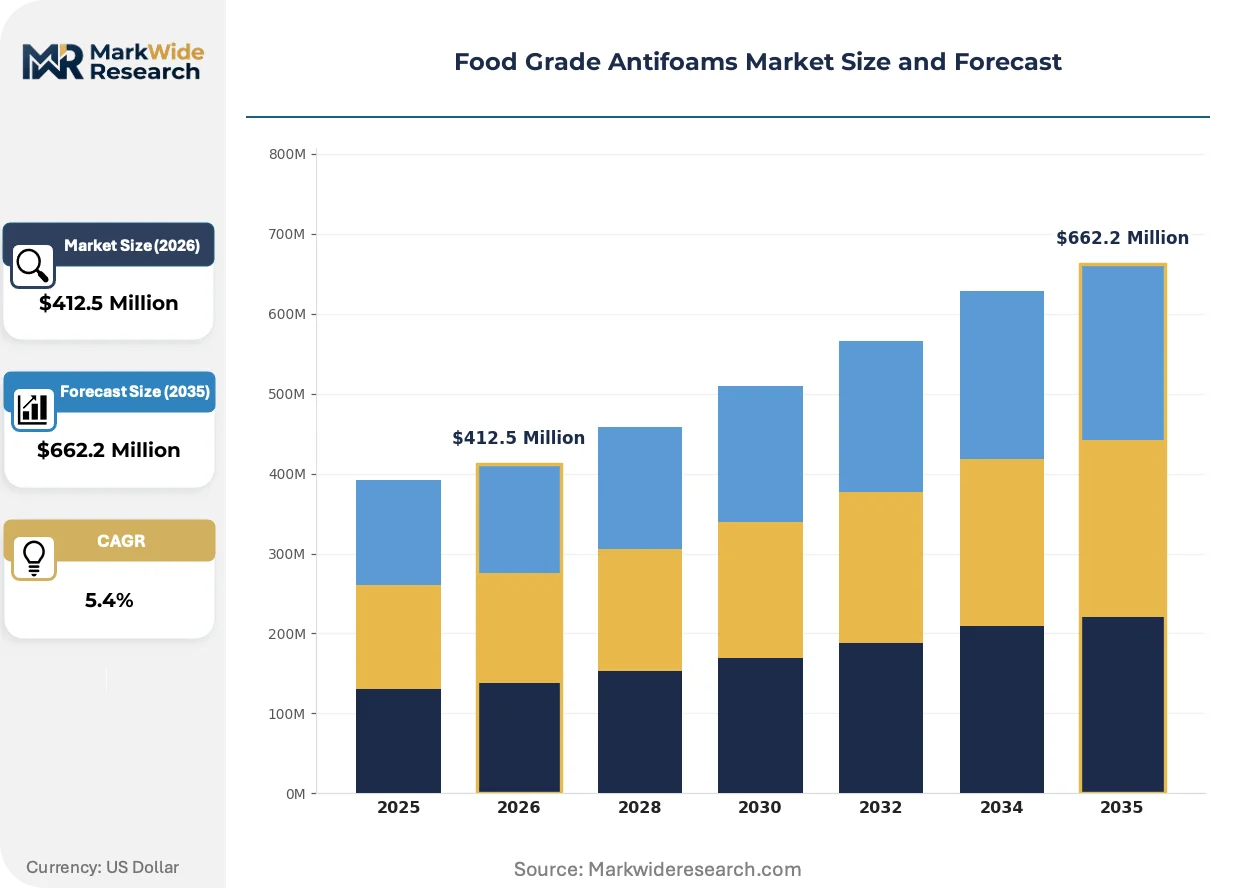
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Polyether-Based, Mineral Oil-Based, Vegetable Oil-Based, Ester-Based Form: Liquid, Emulsion, Powder, Paste Application: Dairy Processing, Beverage Production, Bakery Goods, Confectionery, Sauces & Dressings End User: Food Processing Plants, Beverage Manufacturers, Confectionery Units, Baking Facilities |
| Companies Covered | Evonik Industries AG, Penta Manufacturing Company, Dow Consumer Solutions, Ecolab Inc., Ashland LLC, BASF SE, Wacker Chemie AG, Elementis Plc, Lonza Consumer Product Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Antifoams Market Shifts & Advancements
Process analytical technology is embedding real-time foam detection into continuous dairy lines, shifting antifoam deployment from scheduled dosing to sensor-triggered response. This convergence of measurement and actuation is compressing formulation tolerance requirements.
Machine vision foam monitoring is digitizing antifoam consumption patterns in high-shear evaporators. European dairy cooperatives in the Netherlands and Denmark are piloting camera-based lamellae detection at 200 frames per second. The technology is digitizing supplier relationships by transmitting usage telemetry directly to chemical distributors for replenishment optimization.
REACH Annex XIV authorization requirements for siloxane D4/D5/D6 are forcing reformulation roadmaps for silicone-based products. German chemical distributors are stockpiling grandfathered inventories while accelerating polyether alternatives through ECHA notification. Organic dairy processors in Bavaria and Normandy are responding by disqualifying silicone-containing formulations from approved supplier lists.
Buyer consolidation among multinational dairy cooperatives is compressing supplier qualification cycles. Procurement teams at European beverage conglomerates are unbundling antifoam supply from broader chemical management contracts. This shift is most visible in Germany, where direct sourcing from specialty chemical manufacturers is displacing distributor intermediaries for volume accounts.
Food Grade Antifoams Market Segmentation
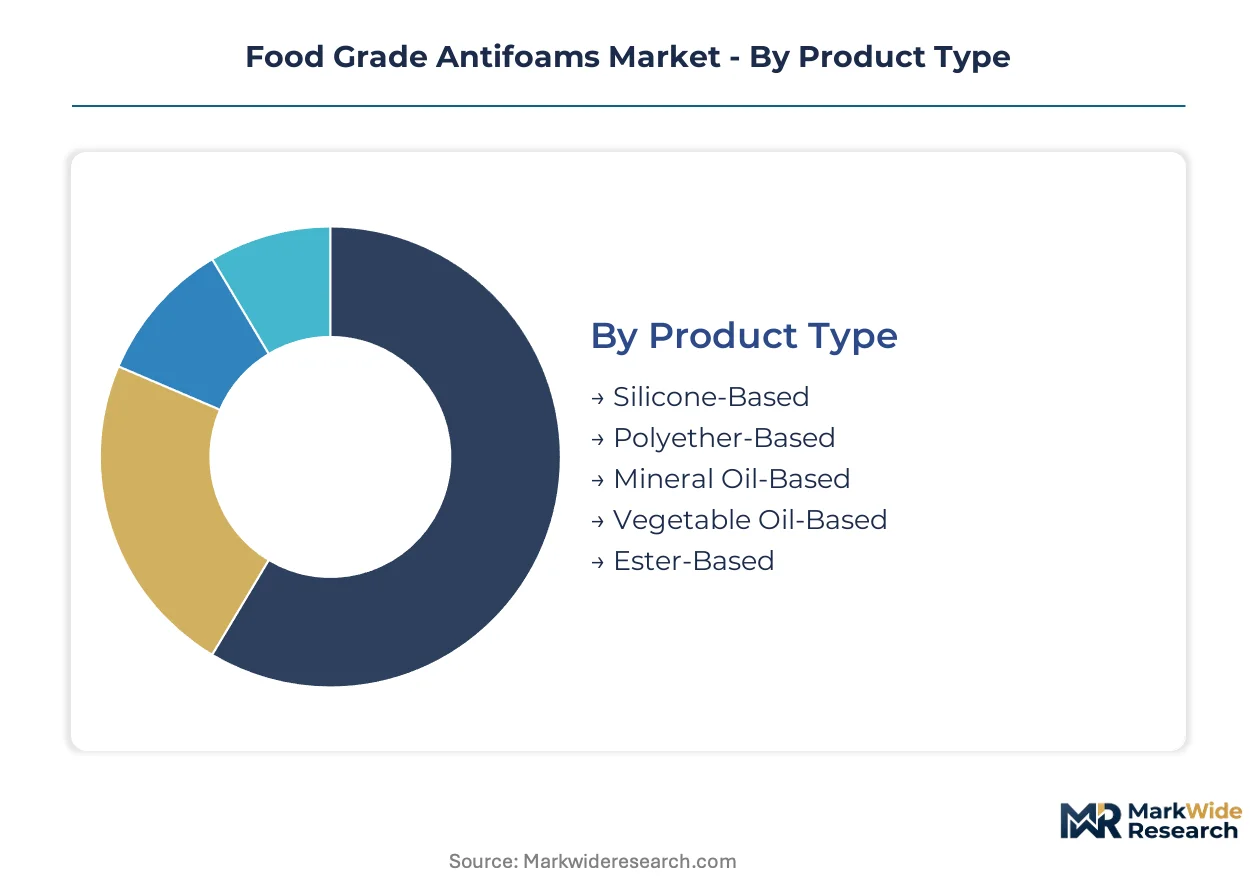
Food grade antifoams serve distinct process chemistries across thermal, shear, and pH environments. Segment boundaries reflect formulation compatibility with regulatory positive lists and dosing infrastructure constraints.
Product Type:
Silicone formulations dominate high-temperature evaporation, while polyether chemistry is displacing incumbents in clean-label supply chains.
- Silicone-Based:Polydimethylsiloxane emulsions deliver thermal stability above 150°C and rapid knockdown in whey concentration stages. German dairy cooperatives anchor procurement volumes despite REACH D4/D5/D6 authorization pressures tightening formulation roadmaps.
- Polyether-Based:Ethylene oxide-propylene oxide copolymers satisfy EU organic label requirements where silicone residues face EFSA detection threshold compression. French and German retailers are accelerating supplier qualification for pasteurized milk packaging lines.
- Mineral Oil-Based:Refined paraffinic fractions compete on cost in emerging market baking facilities with less stringent thermal performance demands.
- Vegetable Oil-Based:Triglyceride formulations serve kosher and halal-certified sauce production where petrochemical origins trigger compliance barriers.
- Ester-Based:Sorbitan ester chemistry targets confectionery aeration control with GRAS status under FDA 21 CFR 172.
The dominant share belongs to Silicone-Based formulations, while Polyether-Based chemistry is closing the gap fastest.
Form:
Physical state determines dosing automation compatibility and pre-dispersion capital requirements.
- Liquid:Neat silicone fluids integrate directly into continuous process streams without dilution equipment. Indian dairy cooperatives in Gujarat and Maharashtra are retrofitting evaporators with automated injection skids for this format.
- Emulsion:Aqueous dispersions concentrate margin pools through ease of metering pump integration versus high-viscosity alternatives. China's SAMR expanded GB 2760 positive list coverage for emulsion carriers, streamlining local registration.
- Powder:Spray-dried formulations serve remote baking facilities lacking liquid handling infrastructure.
- Paste:High-viscosity silicones require pre-dispersion systems that clash with modern automated infrastructure, compressing addressable share.
Liquid formats command the largest installed base, though Emulsion demand is climbing the fastest as continuous processing expands.
Application:
Process temperature and protein content dictate antifoam selection across food manufacturing verticals.
- Dairy Processing:Continuous evaporator and spray dryer operations generate the highest dosing volumes. Whey concentration stages in India and China are automating systems to minimize foam-related heat transfer losses.
- Beverage Production:Carbonation and fermentation control in beer and soft drink manufacturing. Oat and pea protein extraction lines require customized formulations distinct from legacy dairy chemistries.
- Bakery Goods:Dough mixing and yeast fermentation stages utilize lower-dose mineral oil or vegetable oil systems.
- Confectionery:Aerated candy and chocolate processing where ester-based chemistry controls bubble structure.
- Sauces & Dressings:High-shear mixing of emulsified products with vegetable oil formulations preferred for label-friendly positioning.
Dairy Processing holds the dominant position, while Beverage Production is gaining share fastest on plant-based protein expansion.
End User:
Facility scale and certification requirements stratify procurement sophistication across buyer types.
- Food Processing Plants:Integrated dairy and oil refining operations with centralized chemical management contracts. European beverage conglomerates are unbundling antifoam supply from broader agreements, favoring direct manufacturer relationships.
- Beverage Manufacturers:Carbonated soft drink and brewing operations with seasonal demand volatility. Dutch and Danish cooperatives are piloting machine vision foam monitoring at 200 frames per second, digitizing consumption telemetry.
- Confectionery Units:Batch-oriented facilities with lower annual volumes but higher formulation specificity requirements.
- Baking Facilities:Fragmented regional players in emerging markets where cost-sensitive mineral oil alternatives compete on price.
Food Processing Plants represent the largest procurement base, while Beverage Manufacturers are expanding fastest on automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German silicone precursor exports supply formulation houses across India and China, where dairy processor procurement is accelerating fastest. Trade corridors linking European chemical clusters to Asian manufacturing hubs define current supply chain topology.
United States
Dairy cooperatives in Wisconsin and California are retrofitting evaporator lines with automated antifoam injection systems. FDA 21 CFR 173.340 governs permissible defoaming agents, while EPA reporting requirements constrain silicone discharge limits. Chicago-area chemical distributors anchor procurement volumes for Midwestern cheese processing facilities.
Germany
Bavarian dairy processors are expanding polyether antifoam qualification to meet EU organic label requirements under Regulation 2018/848. ECHA REACH Annex XIV authorization pressures for siloxane D4/D5/D6 are compressing formulation timelines. The Leverkusen chemical cluster houses backward-integrated polydimethylsiloxane production serving European beverage applications.
China
Whey concentration facilities in Shandong and Hebei provinces are automating dosing infrastructure to minimize foam-related heat transfer losses. SAMR's GB 2760 standard updates are expanding the positive list for food-grade emulsion carriers. Yangtze River Delta formulation plants concentrate domestic emulsion manufacturing capacity.
India
FSSAI-aligned state milk federations in Gujarat and Maharashtra are retrofitting evaporators with automated antifoam injection skids. BIS certification requirements create divergent compliance pathways for international suppliers. Anand and Nagpur dairy clusters drive procurement volumes for continuous processing equipment.
France
Normandy organic dairy processors are disqualifying silicone-containing formulations from approved supplier lists ahead of EFSA detection threshold compression. EU F-Gas Regulation constraints on silicone precursors are accelerating polyether alternatives through ECHA notification. Rennes-area cooperatives pilot machine vision foam monitoring systems.
Food Grade Antifoams Market Competitive Landscape
On the supply side, the industry is consolidating around backward-integrated silicone precursor manufacturers and specialty formulation houses. Three archetypes dominate: integrated chemical conglomerates with captive siloxane supply, independent emulsion specialists serving regional dairy clusters, and mineral oil-based cost competitors targeting emerging market baking facilities. Dominant competitive moves include direct sourcing relationships displacing distributor intermediaries, and portfolio diversification into polyether chemistry ahead of REACH authorization deadlines.
Among German chemical conglomerates, Evonik Industries AG and Wacker Chemie AG exemplify the integrated archetype with upstream control over organosilicon feedstocks. BASF SE occupies a position across both silicone and mineral oil-based alternatives, serving cost-sensitive emerging market segments. These three anchors represent distinct strategic postures: premium European positioning, captive supply security, and emerging market price competition.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Penta Manufacturing Company |
| Dow Consumer Solutions |
| Ecolab Inc. |
| Ashland LLC |
| BASF SE |
| Wacker Chemie AG |
| Elementis Plc |
| Lonza Consumer Product Ingredients |
| Others |
Supply & Pricing Matrix
The Leverkusen chemical cluster's polydimethylsiloxane capacity dynamics directly shape pricing power for European beverage formulators. Downstream dairy processors in Bavaria and Normandy face compressed negotiation leverage when precursor supply tightens under REACH authorization pressures.
Pricing Analysis
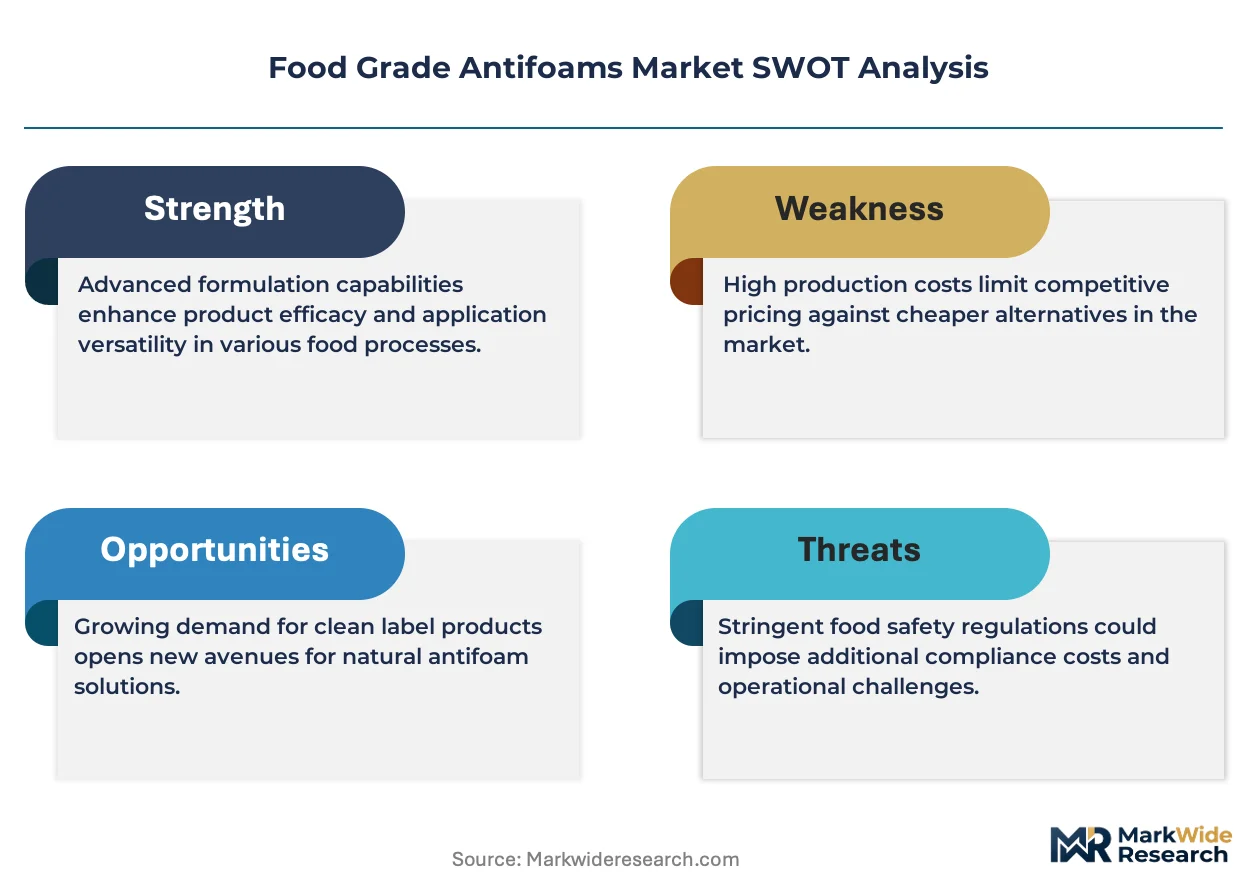
Current-generation silicone emulsions command substantial premiums over mineral oil-based alternatives, while next-generation polyether formulations occupy an emerging price tier. Three-tier pricing structure across premium silicone, standard polyether, and economy mineral oil levels stratifies the market. Pricing pressure stems from EFSA detection threshold compression on silicone residues in organic dairy lines. Small-scale baking facilities in emerging markets exhibit highest price sensitivity, whereas automated dairy cooperatives in Germany prioritize dosing precision over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus for polydimethylsiloxane precursor flows. Concentrated manufacturing in Germany, the United States, and China feeds global formulation capacity. Raw material dependencies center on dimethyl silicone feedstocks, ethylene oxide derivatives, and refined vegetable oil bases. Single-source vulnerability concentrates around German silicone precursor exports to Asian dairy processor markets. Distribution runs through specialty chemical distributors, though direct manufacturer relationships are displacing intermediaries for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers face a substitution defense against accelerating polyether migration as EU organic label expansion disqualifies silicone-containing formulations from approved supplier lists.
For Market Incumbents: Pre-empt polyether qualification timelines by accelerating ECHA notification for clean-label alternatives ahead of REACH Annex XIV authorization deadlines. Deepen backward integration into organosilicon feedstocks to secure margin pools amid dimethyl silicone concentration in Germany and the United States. Capture stranded premium positioning by serving legacy high-temperature dairy evaporator lines that resist polyether thermal performance limits. For New Entrants and Emerging Players: Establish a beachhead in Indian dairy cooperative modernization, where FSSAI-aligned state milk federations in Gujarat and Maharashtra are retrofitting evaporators with automated injection infrastructure. Target plant-based beverage foaming chemistry as a white-space segment, where oat and pea protein extraction lines require customized formulations distinct from legacy dairy applications. Lead with carbon-accounting transparency to exploit EU Green Deal scope-3 disclosure preferences for regionally manufactured emulsions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent emulsion specialists serving regional dairy clusters with automated dosing integration contracts. Long-term viability across the projection horizon favors acquisition targets with polyether R&D pipelines and ECHA pre-registration assets. Watch for inflection signals in SAMR GB 2760 positive list expansions that streamline local registration for international suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | Captive polydimethylsiloxane supply secures margin pools against German feedstock concentration. |
| Polyether Formulation Diversification | ECHA notification ahead of REACH Annex XIV deadlines defends organic dairy certification access. |
| Automated Dosing System Partnerships | Machine vision integration at Dutch and Danish cooperatives locks in consumption telemetry relationships. |
| Regional Emulsion Manufacturing Expansion | Yangtze River Delta capacity addresses SAMR GB 2760 registration acceleration for China dairy processors. |
| Carbon Accounting Certification Program | Verified transport emissions documentation satisfies EU Green Deal scope-3 disclosure requirements. |
Research Methodology
Operator-level perspectives from dairy plant managers, chemical procurement leads at beverage conglomerates, formulation R&D directors, and specialty chemical distribution partners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings, ECHA substance registration databases, and FSSAI compliance circulars. Bottom-up volume modeling across product type, application, and regional production hub segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed the analytical approach across the analysis window, with optimistic, baseline, and constrained cases reflecting divergent regulatory enforcement timelines and organic label adoption rates. Segmentation dimensions modeled include formulation chemistry, physical form, process application, and end-user facility scale. CAGRs derived from historical trajectory analysis adjusted for REACH authorization phase-out schedules and SAMR positive list expansion cadence. Forecast inputs incorporated whey concentration automation rates and machine vision foam monitoring pilot conversion ratios.
Sensitivities concentrate around EFSA detection methodology improvements, EU F-Gas Regulation precursor constraints, and BIS certification timeline variability in India. Forecasts reflect assumptions on antifoam carryover limit harmonization across regional positive lists. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Modified Starch Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
North America Native Starch Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market