
 Spain Car Rental Market | 2026-2036
Spain Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Car Rental Market Analytics
Premium SUV specification tiers is rotating fleet composition across Spanish rental operators. Europcar Mobility Group leverages its airport concession network to sustain volume leadership at Madrid-Barajas and Barcelona-El Prat. Sixt SE anchors its position through luxury vehicle specialization, while OK Mobility competes aggressively on price-positioned electric vehicle offerings in urban cores.
Spain car rental denotes short-to-medium term vehicle provisioning through contracted daily, weekly, or monthly rates, with fleets governed by manufacturer maintenance schedules and kilometer thresholds that ensure roadworthiness and insurance compliance. The primary commercial purpose centers on mobility substitution for tourists, business travelers, and temporary residents lacking local vehicle ownership. Leisure bookings within the service type dimension dominate revenue generation during summer months, while long-term rental duration contracts yield superior per-unit margins through corporate fleet outsourcing agreements. Tourist customer type segments drive peak-season pricing power, whereas corporate accounts stabilize off-peak utilization rates.
Spain's Directorate-General for Traffic enforces periodic vehicle inspection mandates that compress fleet replacement cycles, while EU Green Deal emissions benchmarks pressure operators toward electrified portfolios. Municipal Low Emission Zones in Barcelona, Madrid, and Valencia restrict internal combustion vehicle access, directly shaping fleet procurement decisions. Stakeholders must monitor regulatory tightening on diesel phase-out timelines and charging infrastructure adequacy across secondary tourism corridors to preserve competitive positioning.
Market Dynamics
Fleet electrification mandates under Spain's EU Green Deal compliance are compressing diesel procurement windows while charging infrastructure gaps in secondary tourism corridors create operational bottlenecks for rental operators.
Growth Catalysts
- EU Green Deal emissions benchmarks:Binding 2030 reduction targets are accelerating fleet turnover toward electrified portfolios across Spanish rental operators.
- Coastal tourism corridors:International arrivals along Andalusia's Costa del Sol sustain peak-season utilization rates that justify premium fleet investments.
- Telematics integration:Real-time vehicle tracking and predictive maintenance systems are reducing downtime and insurance compliance costs.
Market Restraints
- Charging infrastructure asymmetry:Secondary tourism destinations in Extremadura and Castilla-La Mancha lack adequate fast-charging networks, constraining electric fleet deployment.
- Residual value volatility:Accelerated diesel phase-out timelines are compressing secondary market prices for internal combustion vehicles.
- Input cost concentration:Battery supply chains concentrate in East Asian manufacturing hubs, exposing Spanish operators to currency and logistics volatility.
Strategic Opportunities
- Corporate long-term rental outsourcing:Enterprise fleet management contracts in Madrid and Barcelona offer superior per-unit margins through multi-year agreements.
- Mobility-as-a-service convergence:Integration with urban multimodal platforms creates subscription-based revenue streams beyond traditional daily rentals.
- Low Emission Zone expansion:Valencia's pending ZBE implementation will generate captive demand for electric vehicle offerings in Spain's third-largest metropolitan area.
Industry Challenges
- Technician certification gaps:High-voltage electric vehicle maintenance requires specialized training that outpaces Spain's vocational education pipeline.
- Legacy reservation system integration:Proprietary fleet management platforms resist interoperability with emerging mobility aggregator APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Car Rental Market |
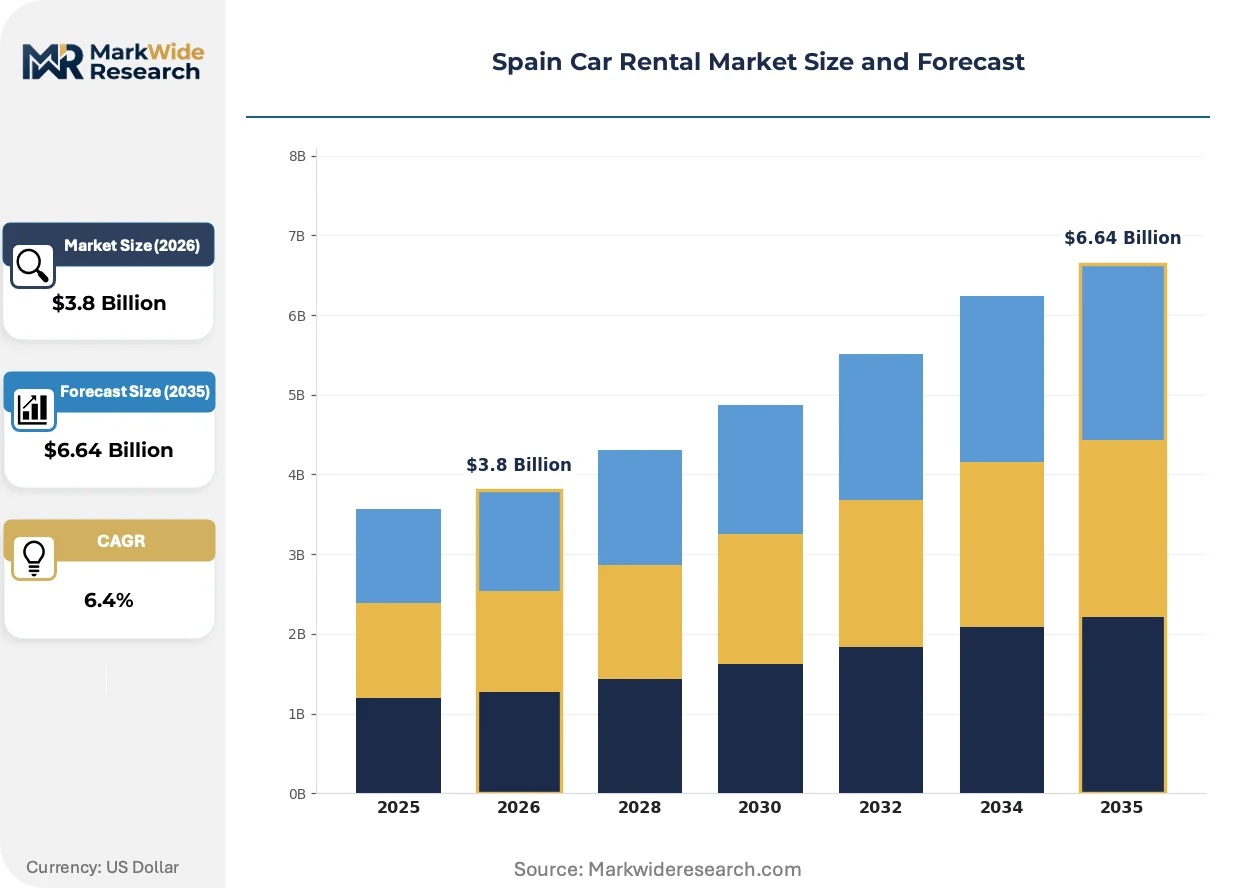
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Leisure, Business, Luxury, SUV Rental Duration: Daily, Weekly, Monthly, Long-Term Customer Type: Tourists, Corporates, Locals, Government Vehicle Type: Compact, Sedan, Van, Convertible |
| Companies Covered | Europcar Mobility Group, Sixt SE, Hertz Corporation, Avis Budget Group, Enterprise Holdings, Goldcar, Centauro Rent a Car, OK Mobility, Record Go, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Car Rental Market Evolving Landscape
Digital-native booking behaviors and connected vehicle architectures are dissolving traditional rental counter models while regulatory pressure on emissions intensifies capital allocation toward electrification.
Connected vehicle telematics is fragmenting fleet management paradigms across Spanish rental operators. Real-time diagnostics and geofencing capabilities enable dynamic pricing and automated damage assessment. Major airport concession holders are retrofitting existing fleets with OEM-agnostic IoT hardware to capture operational data without full vehicle replacement cycles.
Spain's Low Emission Zones in Barcelona, Madrid, and Valencia are mandating Euro 6 diesel or full electric access credentials for urban center entry. Municipal enforcement cameras automatically flag non-compliant rental vehicles, transferring penalty liability to operators. Fleet procurement teams are prioritizing plug-in hybrid and battery electric models for urban depot allocations regardless of upfront cost premiums.
Subscription-based mobility models are displacing traditional daily-rate structures among younger demographic segments in Spanish metropolitan markets. Flexible monthly plans with bundled insurance and maintenance appeal to temporary residents and digital nomads. This shift concentrates most visibly in Barcelona's Gràcia and Eixample districts where international remote workers cluster.
Spain Car Rental Market Segmentation
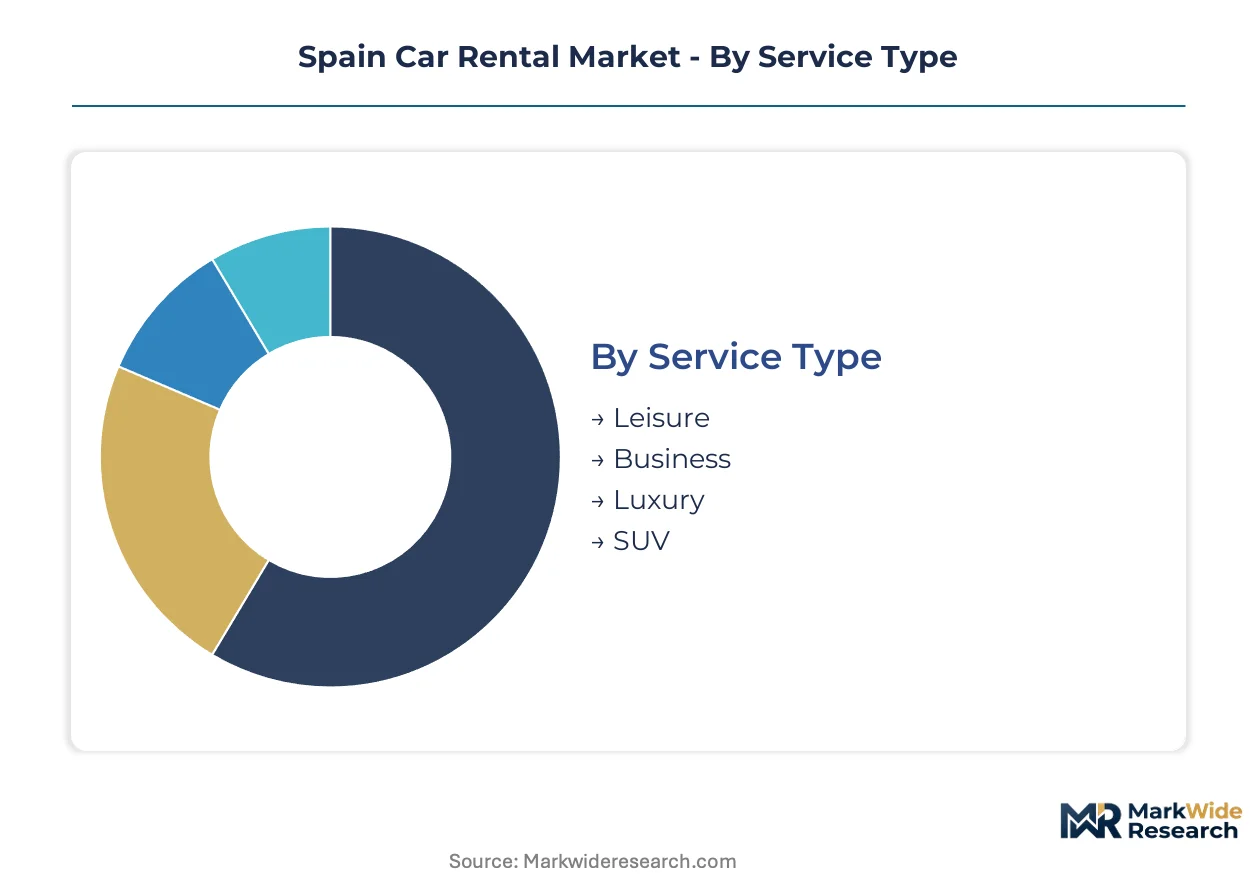
Segmentation in Spain's car rental market reveals how distinct customer behaviors and vehicle specifications create divergent margin profiles across service tiers. Understanding these divisions enables operators to allocate fleet capital toward the highest-yielding combinations of duration, customer type, and vehicle class.
Service Type:
Leisure bookings face intensifying substitution pressure from ride-hailing platforms and peer-to-peer car sharing, particularly among younger travelers in Barcelona and Madrid metropolitan zones.
- Leisure:Summer tourism drives volume concentration along Andalusia's Costa del Sol and Balearic Islands corridors, with peak-season utilization rates justifying premium fleet investments despite narrow off-peak windows.
- Business:Corporate travel budgets prioritize airport-to-city-center convenience and predictable billing structures, concentrating demand at Madrid-Barajas and Barcelona-El Prat terminals where concession rights determine competitive access.
- Luxury:High-net-worth tourists and corporate executives seeking prestige vehicles generate per-day yields substantially above mass-market tiers, though inventory risk concentrates in depreciation-sensitive premium segments.
- SUV:Family leisure travelers and outdoor tourism participants favor elevated seating capacity and luggage flexibility, with demand spiking during ski season in Pyrenean corridors and summer coastal migrations.
Leisure anchors the volume base while SUV gains share at the steepest rate.
Rental Duration:
Cost tier differentiation separates transactional daily rentals from relationship-driven long-term contracts with divergent customer acquisition economics.
- Daily:Airport concession holders capture impulse demand from international arrivals with premium pricing power, though customer lifetime value remains constrained by single-transaction relationships.
- Weekly:Domestic tourism and extended business assignments sustain mid-duration utilization, with pricing structures designed to reduce per-day rates progressively and extend vehicle occupancy.
- Monthly:Temporary residents and project-based corporate assignments generate predictable revenue streams with reduced fleet turnover costs compared to short-term rentals.
- Long-Term:Multi-year corporate fleet outsourcing agreements in Madrid and Barcelona deliver superior per-unit margins through bundled maintenance and insurance services.
Daily rentals generate the highest transaction velocity while long-term contracts deliver the most stable margin contribution.
Customer Type:
Volume concentration varies dramatically across customer types, with tourist segments driving peak-season pricing power and corporate accounts stabilizing off-peak utilization.
- Tourists:International arrivals sustain peak-season utilization rates across coastal provinces, with booking patterns concentrated in advance reservation windows that enable yield optimization.
- Corporates:Enterprise fleet management contracts and business travel accounts provide volume commitments that justify dedicated inventory allocation and preferred rate structures.
- Locals:Vehicle substitution during repair periods or special occasions generates sporadic demand with high price sensitivity and minimal loyalty attachment.
- Government:Public sector procurement frameworks prioritize cost efficiency and compliance documentation over service flexibility, with tender-based allocation constraining margin expansion.
Tourists dominate absolute transaction volume while corporates expand most quickly through outsourcing adoption.
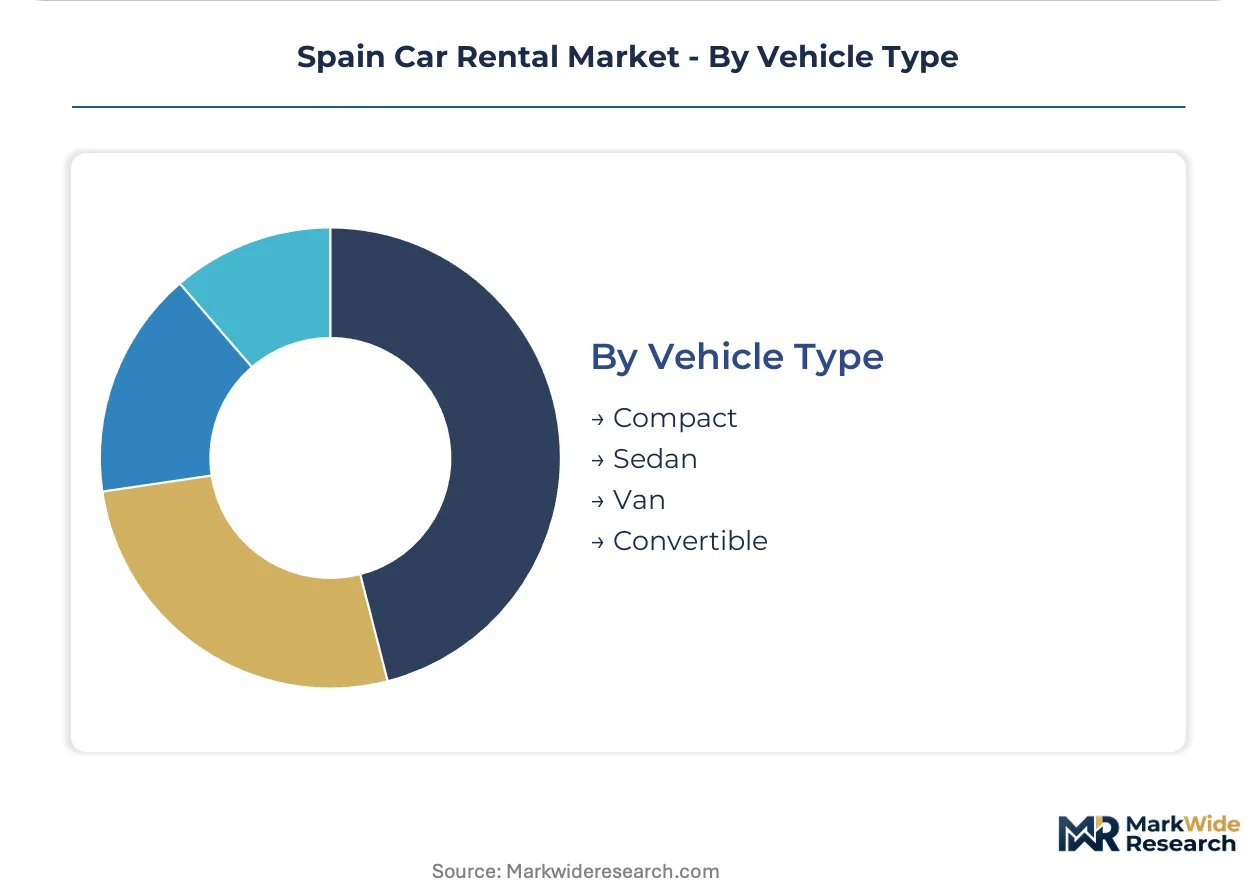
Vehicle Type:
Procurement patterns across vehicle classes reflect divergent residual value risks and regulatory compliance requirements under Spain's Low Emission Zone mandates.
- Compact:Urban tourists and cost-conscious leisure travelers favor fuel-efficient small vehicles for narrow historic center streets in Seville, Granada, and Valencia old quarters.
- Sedan:Business travelers and mid-tier leisure segments prioritize trunk capacity and rear-seat comfort for intercity highway journeys between Madrid, Barcelona, and coastal destinations.
- Van:Family groups and equipment-intensive tourism activities drive demand for multi-passenger configurations, with peak demand coinciding with summer vacation migration patterns.
- Convertible:Premium leisure positioning along Mediterranean coastal routes generates seasonal yield spikes, though limited annual utilization creates inventory management complexity.
Compact vehicles retain the largest fleet allocation while van configurations climb the fastest on multi-generational tourism trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's car rental market exhibits pronounced regional asymmetry, with coastal tourism corridors generating surplus vehicle demand that inland logistics networks struggle to redistribute efficiently during seasonal peaks.
Madrid
Madrid-Barajas Airport processes the highest volume of business travel demand across Spanish rental networks, with corporate fleet contracts concentrated in the capital's financial district. The city's Low Emission Zone restricts diesel vehicle access through automated camera enforcement, compelling operators to prioritize electric and plug-in hybrid allocations for urban depots. Fleet procurement decisions in Madrid increasingly factor in residual value risk from accelerated ICE phase-out timelines.
Catalonia
Barcelona-El Prat anchors Mediterranean cruise passenger conversions into rental bookings, with demand spiking during spring and autumn shoulder seasons. Catalonia's autonomous government maintains stricter emissions standards than national baselines, compressing compliant vehicle procurement windows for operators serving the metropolitan area. The Costa Brava corridor north of Barcelona sustains premium leisure pricing through concentrated international villa tourism.
Andalusia
Costa del Sol tourism generates the highest peak-season utilization rates across Spanish rental operations, with Malaga Airport serving as the primary gateway. Andalusian provincial authorities coordinate with operators to manage fleet overflow during summer months through temporary depot licensing. The region's interior cities of Seville and Granada maintain distinct compact-vehicle demand patterns for historic center navigation.
Valencia
Valencia's pending Low Emission Zone implementation is generating preemptive electric fleet investments by rental operators seeking first-mover positioning. The city's port cruise terminal and proximity to Costa Blanca beaches sustain dual leisure demand streams with complementary seasonal patterns. Metropolitan Valencia exhibits the fastest-growing subscription-based mobility adoption among Spanish secondary cities.
Basque Country
Bilbao and San Sebastian generate concentrated business travel demand from industrial corporate headquarters, with rental patterns skewing toward premium sedan configurations. Basque Country environmental regulations predate national Low Emission Zone mandates, creating earlier compliance deadlines for regional operators. The Pyrenean ski corridor drives winter-specific SUV and van demand distinct from coastal leisure patterns.
Spain Car Rental Market Competitive Landscape
Listed leaders compete with private specialists across airport concession networks and urban mobility corridors, creating a tiered structure where scale advantages in fleet procurement confront agility in electric vehicle deployment. Publicly traded operators leverage capital market access for fleet financing, while private competitors exploit regulatory arbitrage in secondary tourism markets. Three archetypes dominate: airport concession holders with volume-driven positioning, luxury specialists commanding premium yields, and price-focused electric vehicle entrants in metropolitan zones. Consolidation pressure intensifies through concession renewal cycles and manufacturer direct partnerships that reshape fleet access economics.
Within the airport concession tier, Europcar Mobility Group and Sixt SE exemplify divergent strategic positioning, with the former representing volume-optimized network coverage and the latter anchoring premium-midmarket specialization. OK Mobility occupies a position among price-positioned electric vehicle specialists targeting urban core demand. These three entities collectively illustrate how competitive advantage in Spanish car rental increasingly derives from fleet composition timing relative to regulatory phase-out deadlines rather than traditional scale economies alone.
| Leading Market Players |
|---|
| Europcar Mobility Group |
| Sixt SE |
| Hertz Corporation |
| Avis Budget Group |
| Enterprise Holdings |
| Goldcar |
| Centauro Rent a Car |
| OK Mobility |
| Record Go |
| Others |
Value Network & Pricing Analysis
Fleet scale economies at Madrid-Barajas and Barcelona-El Prat compress per-unit fixed costs while concentrating procurement leverage among airport concession holders, simultaneously elevating price floors for secondary operators and narrowing margin recovery windows during off-peak months.
Pricing Analysis
Tourist customer segments anchor a three-tier pricing structure across premium, standard, and economy levels, with airport impulse bookings commanding substantial premiums over advance reservations. Price differentiation rests on vehicle electrification credentials and Low Emission Zone compliance status, as Barcelona and Madrid enforcement cameras automatically penalize non-compliant rentals. Cost compression in the economy tier is intensifying because OK Mobility and price-positioned electric specialists compress daily-rate benchmarks. Corporate long-term contracts exhibit lowest price sensitivity due to bundled maintenance and insurance services, while leisure tourists demonstrate highest elasticity to per-day rate fluctuations.
Supply Chain Analysis
Inventory lead times for battery electric vehicles from Germany, South Korea, and China extend fleet procurement cycles beyond traditional internal combustion replacement windows. Spanish rental operators draw from concentrated lithium-ion cell supply anchored in East Asian manufacturing hubs, with semiconductor content for connected vehicle telematics resting on Taiwanese and South Korean foundry capacity. Single-source vulnerability in battery supply chains exposes operators to currency and logistics volatility. Distribution runs through manufacturer direct fleet sales programs and multi-brand leasing partnerships rather than retail dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's car rental market is recovering through international tourism volume restoration to Costa del Sol and Balearic corridors, with peak-season utilization rates justifying fleet expansion commitments despite residual value risks from accelerated diesel phase-out timelines.
For Market Incumbents: Consolidate airport concession positions at Madrid-Barajas and Barcelona-El Prat through renewal cycle investments, while accelerating electric fleet procurement to preempt Low Emission Zone compliance deadlines in Valencia. Threat substitution from peer-to-peer car sharing platforms in metropolitan cores demands proprietary telematics integration as a defensive lever. Vertical integration into charging infrastructure partnerships reduces operational bottlenecks in secondary tourism corridors.
For New Entrants and Emerging Players: Euro 6 diesel fast-track certification enables immediate urban core access before full electric mandates crystallize, creating a narrow positioning window. White-space targets concentrate in Extremadura and Castilla-La Mancha leisure corridors where charging infrastructure gaps deter incumbent electric deployment. Subscription-based mobility models for digital nomads in Barcelona's Gràcia district offer the most penetrable entry vector, with flexible monthly plans as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among corporate long-term fleet outsourcing providers in Madrid and Barcelona financial districts, offering superior cash-flow predictability versus transactional daily rental operators. Long-term viability across the projection horizon favors operators with manufacturer direct partnerships securing preferential electric vehicle allocation. The acquisition target archetype combines urban depot networks with established corporate account relationships. Monitor EU Green Deal diesel phase-out timeline acceleration as the critical inflection signal for residual value risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement Acceleration | EU Green Deal compliance deadlines in Barcelona, Madrid, and Valencia mandate Euro 6 diesel or full electric credentials. |
| Airport Concession Renewal Investment | Madrid-Barajas and Barcelona-El Prat volume concentration determines competitive access to highest-yield business travel segments. |
| Telematics Platform Integration | Real-time diagnostics and geofencing capabilities enable dynamic pricing and automated damage assessment for connected fleets. |
| Corporate Long-Term Contract Expansion | Multi-year enterprise fleet management agreements in Madrid and Barcelona deliver superior per-unit margins through bundled services. |
| Charging Infrastructure Partnership | Secondary tourism corridors in Extremadura and Castilla-La Mancha lack adequate fast-charging networks, creating operational bottlenecks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, airport concession managers, corporate travel buyers, and telematics platform engineers; and secondary validation through Spain's Directorate-General for Traffic inspection records, EU Green Deal implementation timelines, SEC filings of listed rental operators, and IHS Markit vehicle registration databases. Bottom-up fleet deployment estimates triangulated against top-down tourism arrival projections.
Across the analysis window, the forecasting framework modeled segmentation dimensions including service type, rental duration, customer archetype, and vehicle electrification status alongside regional regulatory cluster variations. CAGRs were derived from elasticity-adjusted utilization rate assumptions and fleet turnover cycle compression under emissions mandates. Industry-specific inputs incorporated Low Emission Zone expansion schedules and battery supply chain lead time volatility.
Decision-makers should treat outputs as directional under base assumptions of sustained international tourism recovery and stable EU regulatory timelines; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
China Vehicle Rental Market
Transportation Services
Scooter Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
United States Car Rental Market
Transportation Services
Cross Docking Services Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Australia Taxi Market