
 ASEAN Taxi Market | 2026-2036
ASEAN Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Taxi Market Outlook
Corporate fleet procurement across Indonesian mining and logistics sectors is restructuring buyer concentration toward enterprise contract pools. Grab Holdings Inc. leverages its super-app infrastructure to bundle ride-hailing with financial services across multiple ASEAN jurisdictions. Gojek anchors two-wheel and four-wheel mobility within Indonesia's archipelago logistics chain. ComfortDelGro Corporation Limited dominates regulated street-hail operations in Singapore and extends into adjacent Australian markets.
An ASEAN taxi constitutes a licensed commercial passenger vehicle operating under metered or digitally dispatched fare structures, typically governed by national transport authority regulations covering vehicle age limits, insurance minimums, and driver background verification. Ride-hailing platforms now control the largest volume channel, while executive taxi services capture disproportionate margin pools from airport and business district corridors. Shared ride formats struggle with unit economics outside Jakarta and Bangkok density cores, whereas sedan vehicle types retain preference among business travelers seeking predictable service tiers.
Malaysia's Land Public Transport Agency and Indonesia's Ministry of Transportation enforce divergent driver screening and vehicle inspection protocols that fragment compliance architectures for cross-border operators. Singapore's Land Transport Authority imposes strict quota controls on taxi licenses, constraining fleet elasticity during demand surges. Thailand's Department of Land Transport mandates GPS and emergency button installations, elevating technology costs for traditional operators. Stakeholders must weigh regulatory arbitrage opportunities against the capital requirements of multi-jurisdiction certification systems as electric vehicle mandates emerge across member states.
Market Dynamics
Electric vehicle mandates across Southeast Asian capitals are compressing fleet replacement timelines while app-based dispatch platforms consolidate booking volume away from street-hail incumbents. This dual pressure is restructuring capital allocation toward charging infrastructure and driver retraining programs.
Growth Catalysts
- Jakarta's Odd-Even Traffic Policy:Restrictions on private vehicle access during peak hours redirect commuters toward commercial ride services. Fleet operators capture displaced passenger volume during restricted windows.
- Contactless Payment Rails:QR-code and e-wallet integration across Vietnam and Thailand removes fare friction. Digital settlement accelerates trip throughput in high-frequency corridors.
- Ho Chi Minh City Density:Urban concentration exceeding 4,000 inhabitants per square kilometer sustains shared-ride unit economics. Short trip distances preserve driver hourly yield.
Market Restraints
- Cross-Border Compliance Fragmentation:Malaysia's Land Public Transport Agency and Indonesia's Ministry of Transportation enforce divergent driver screening protocols. Multi-jurisdiction operators face duplicated certification costs.
- Battery Supply Concentration:Lithium-ion cell production clusters in China and South Korea. ASEAN fleet electrification depends on import exposure and currency volatility.
- License Quota Rigidity:Singapore's Land Transport Authority maintains strict taxi permit caps. Fleet elasticity remains constrained during demand surges.
Strategic Opportunities
- Philippines Provincial Expansion:Secondary cities like Cebu and Davao lack app-based penetration. First-mover platforms can establish density before competitor entry.
- Thailand's EV Conversion Subsidies:Board of Investment incentives for electric commercial vehicle adoption reduce fleet acquisition premiums. Operators can front-load replacement cycles.
- Corporate Mobility Bundling:Enterprise travel managers seek consolidated ground transport contracts. Platforms integrating taxi, rental, and shuttle services capture procurement consolidation.
Industry Challenges
- Driver Retention and Platform Hopping:Multi-homing behavior fragments loyalty. Incentives drain margin without securing exclusive supply.
- Legacy Dispatch System Integration:Traditional taxi cooperatives operate proprietary radio networks. App platforms face technical friction merging analog and digital dispatch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Taxi Market |
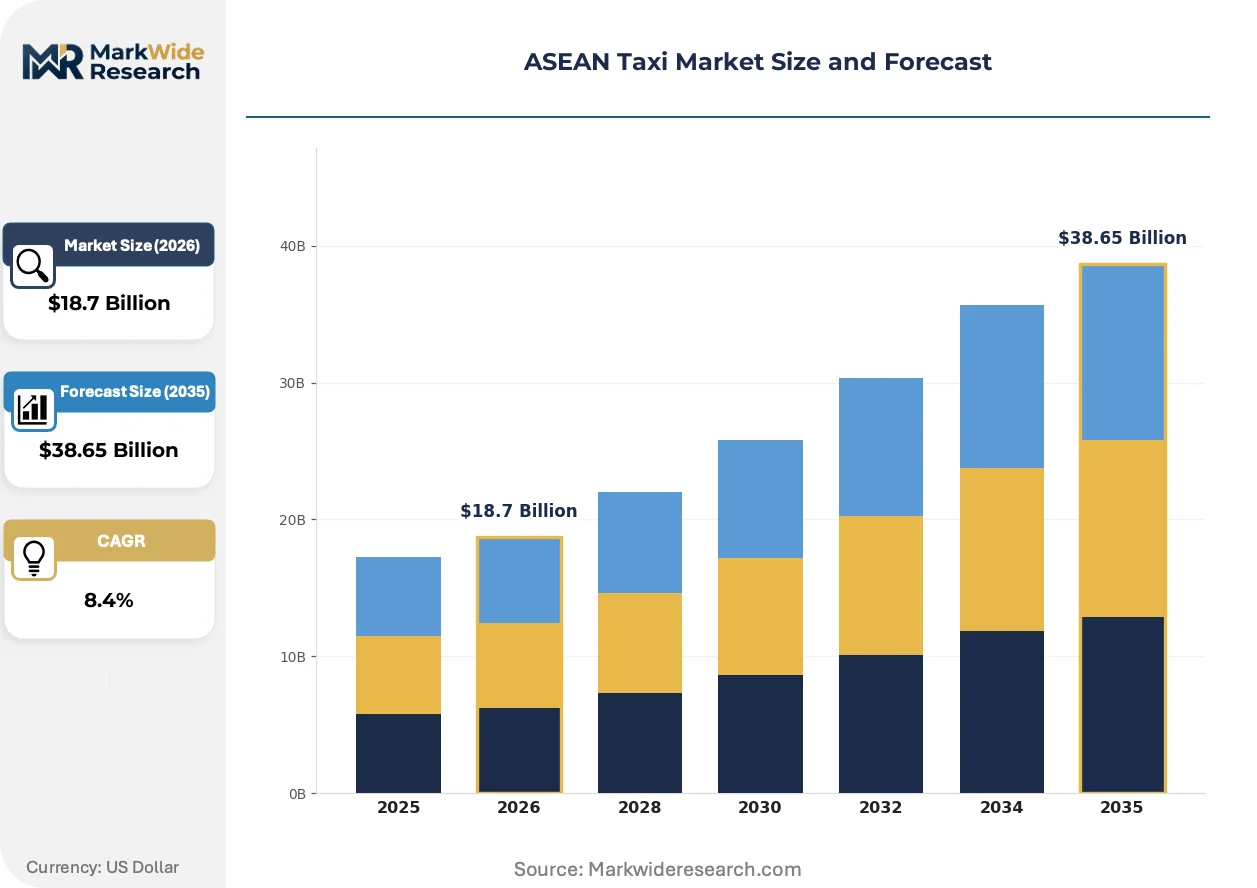
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Traditional Taxi, Ride-Hailing, Executive Taxi, Shared Ride Vehicle Type: Compact Car, SUV, Sedan, Minivan Payment Method: Cash, Credit Card, Mobile Payment, Digital Wallet Customer Type: Business Traveler, Tourist, Local Resident, Student |
| Companies Covered | Grab Holdings Inc., Gojek, ComfortDelGro Corporation Limited, Blue Bird Group, TADA Mobility, Ryde Group Ltd., Xanh SM, Vinasun Corporation, Public Cab Sdn. Bhd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Taxi Market Strategic Shifts
Fleet electrification and algorithmic demand prediction are converging to reshape vehicle procurement patterns and driver deployment strategies across Southeast Asian urban centers.
Telematics-enabled battery management systems are absorbing route optimization functions previously handled by standalone navigation platforms. Fleet operators in Bangkok and Kuala Lumpur deploy these integrated stacks to preserve charge range and minimize downtime. The technology is absorbing capital previously allocated to separate hardware procurement.
Thailand's Department of Land Transport mandates GPS tracking and emergency button installations in all commercial passenger vehicles. Compliance elevates hardware costs for traditional operators while creating data streams that insurers use to refine risk-based premium structures. Street-hail incumbents face steeper cost curves than digitally native competitors already possessing installed telemetry bases.
Corporate travel managers are consolidating ground transport procurement under enterprise software platforms. This procurement consolidation displaces fragmented expense reimbursement models with pre-negotiated rate cards and centralized billing. The shift is most visible in Singapore's central business district, where multinational headquarters demand unified service level agreements across mobility modes.
ASEAN Taxi Market Segmentation
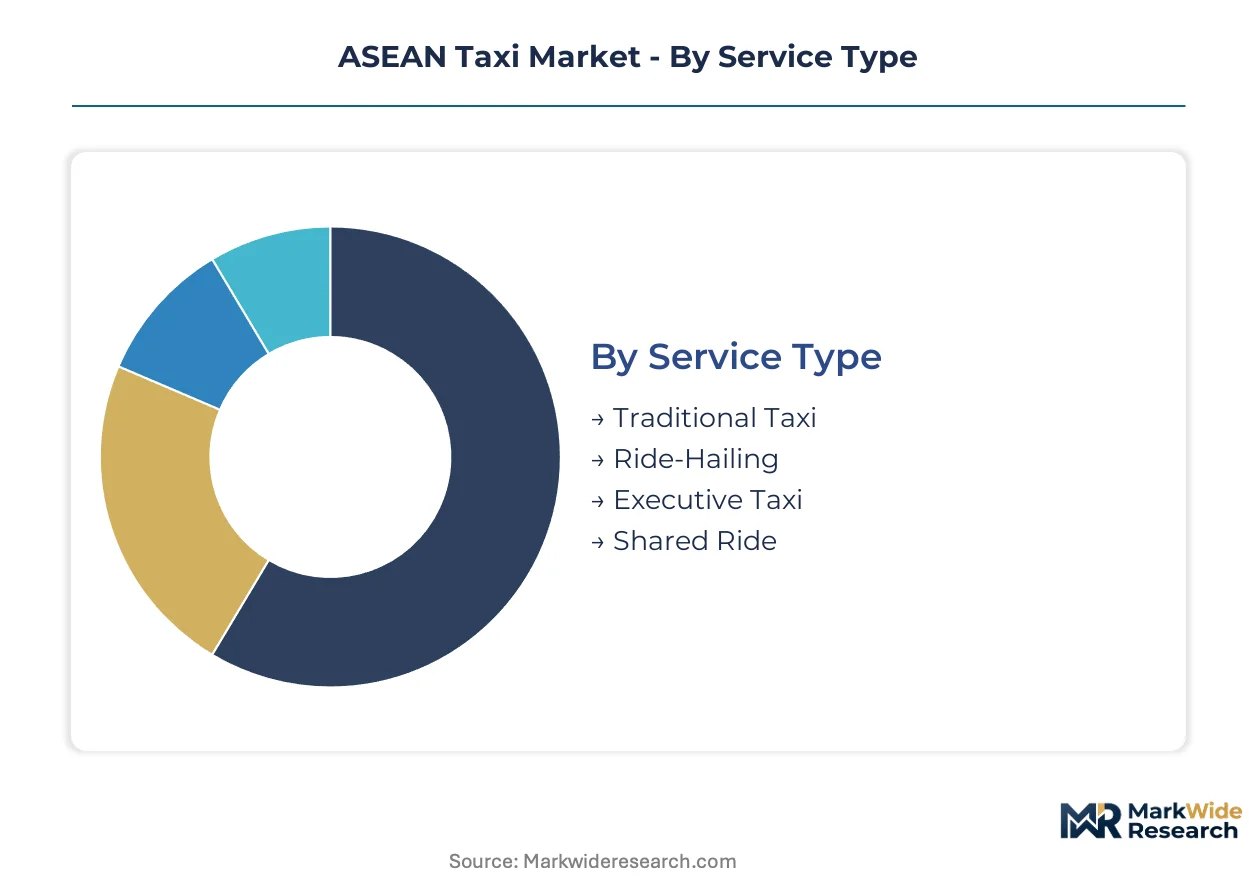
Service tier differentiation determines capital allocation and fleet procurement cycles across Southeast Asian taxi operators. Vehicle specification, payment infrastructure, and customer profile each create distinct margin pools and compliance burdens.
Service Type:
Fleet replacement cycles accelerate where digital dispatch platforms displace street-hail incumbents, compressing vehicle age limits and driver certification timelines.
- Ride-Hailing:App-based dispatch platforms control booking volume through algorithmic matching and dynamic pricing. Demand concentrates in Jakarta and Bangkok density cores where driver supply pools enable sub-five-minute pickup windows.
- Traditional Taxi:Metered street-hail operations retain regulatory preference in Singapore through license quotas. Fleet operators face stranded asset risk as digital platforms capture younger demographics.
- Executive Taxi:Premium service tier serving airport corridors and central business districts. Flat-rate airport transfers command margin premiums over metered alternatives.
- Shared Ride:Multi-passenger pooling format struggles outside Ho Chi Minh City and Manila hyper-density zones. Unit economics degrade rapidly beyond four-kilometer trip distances.
Volume placements concentrate in Ride-Hailing; the faster expansion belongs to Executive Taxi.
Vehicle Type:
Cost tier stratification shapes procurement patterns as electric vehicle mandates rewrite depreciation schedules across ASEAN capitals.
- Sedan:Four-door passenger configuration dominates business traveler preference for predictable service tiers. Procurement concentrates among Singapore and Kuala Lumpur fleet operators seeking airport contract eligibility.
- Compact Car:Sub-1,500cc displacement vehicles optimize fuel economy for high-frequency urban corridors. Indonesian operators deploy these units across Jakarta's odd-even restricted zones.
- SUV:Elevated seating and luggage capacity serve provincial expansion routes with degraded road infrastructure. Thai operators favor this configuration for Phuket and Chiang Mai tourist circuits.
- Minivan:Six-to-eight passenger capacity supports group travel and hotel shuttle contracts. Demand clusters in Bangkok's Suvarnabhumi Airport corridor.
Procurement volume tilts toward Sedan; Compact Car is climbing the fastest as electrification mandates favor smaller battery footprints.
Payment Method:
Customer type determines settlement infrastructure requirements, with corporate accounts demanding centralized billing distinct from retail fare collection.
- Mobile Payment:QR-code settlement through GrabPay, Gojek, and regional e-wallets removes fare friction. Vietnam and Thailand lead penetration rates among retail passengers.
- Digital Wallet:Pre-funded stored value systems enable subscription and loyalty program integration. Singapore's corporate travel managers mandate this format for expense reconciliation.
- Cash:Paper settlement persists in Philippine provincial markets and among unbanked driver populations. Reconciliation costs erode operator margins.
- Credit Card:Card-present and tokenized transactions dominate airport and hotel rank pickups. Interchange fees compress margins versus direct wallet settlement.
Transaction volume aggregates in Mobile Payment; Digital Wallet is gaining share fastest among enterprise contract pools.
Customer Type:
Application context dictates service level requirements, with business travelers demanding reliability guarantees unavailable to price-sensitive leisure segments.
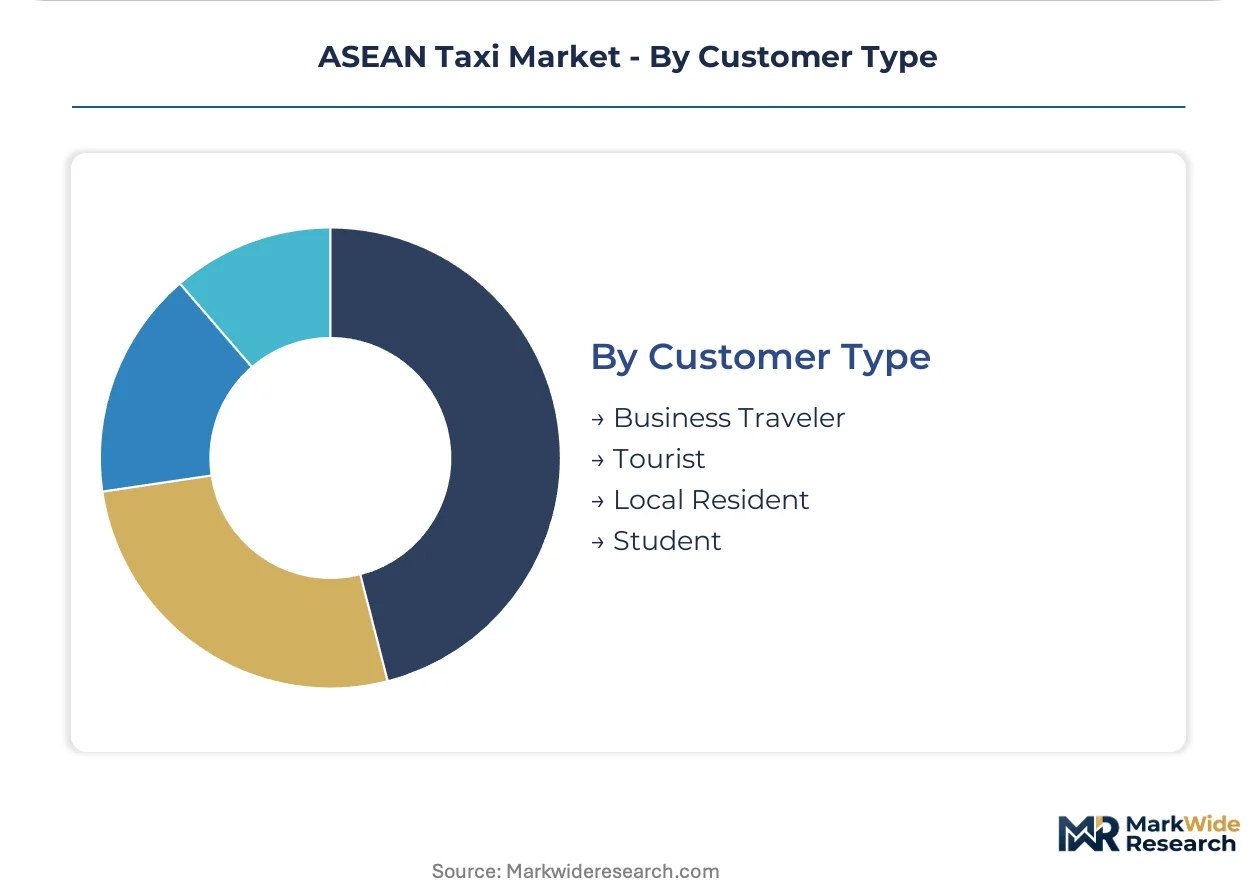
- Business Traveler:Corporate account holders require pre-negotiated rate cards and centralized billing. Singapore's central business district anchors this segment through multinational headquarters concentration.
- Tourist:Foreign visitors favor app-based platforms with English-language interfaces and fixed airport pricing. Phuket and Bali resort corridors concentrate seasonal demand volatility.
- Local Resident:Daily commute and errand trips sustain baseline fleet utilization across metropolitan areas. Price sensitivity drives platform hopping behavior.
- Student:Discounted fare tiers and off-peak usage patterns characterize this segment. University corridor density in Manila and Kuala Lumpur supports dedicated service tiers.
Revenue concentration rests with Business Traveler; Tourist shows the steepest expansion trajectory as ASEAN aviation capacity recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum refining corridors in Singapore and Johor anchor fuel supply networks that feed diesel and gasoline taxi fleets across the Malay Peninsula. These feedstock localities shape operational cost structures from Penang to Batam.
Singapore
Business traveler density in the central business district sustains executive taxi premiums. The Land Transport Authority enforces strict taxi license quotas that constrain fleet expansion during demand surges. Marina Bay and Changi Airport corridors concentrate flat-rate airport transfer contracts.
Indonesia
Jakarta's odd-even traffic restrictions redirect private vehicle commuters toward commercial ride services during peak windows. The Ministry of Transportation mandates divergent driver screening protocols from neighboring Malaysia. The Jabodetabek metropolitan area anchors Gojek's two-wheel and four-wheel mobility integration.
Thailand
Tourist corridor density in Phuket and Bangkok sustains seasonal demand volatility for metered and app-based services. The Department of Land Transport mandates GPS tracking and emergency button installations in all commercial passenger vehicles. Suvarnabhumi Airport ranks concentrate hotel shuttle and minivan contracts.
Vietnam
Ho Chi Minh City's urban density exceeding 4,000 inhabitants per square kilometer preserves shared-ride unit economics. National regulators are accelerating electric vehicle conversion timelines for commercial fleets. Xanh SM's battery-electric taxi fleet is scaling rapidly across the southern economic corridor.
Malaysia
Kuala Lumpur's airport contract eligibility requirements concentrate sedan procurement among fleet operators. The Land Public Transport Agency enforces driver certification standards that reshape compliance cost structures. The Klang Valley corridor anchors Grab Holdings Inc.'s super-app bundling of ride-hailing with financial services.
ASEAN Taxi Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electric vehicle fleet differentiation and provincial market penetration. The vendor base clusters around three archetypes: super-app platforms bundling mobility with financial services, regulated street-hail incumbents holding license-protected positions, and electric-first challengers exploiting subsidy windows. Competitive positioning depends on multi-jurisdiction certification capabilities and charging infrastructure partnerships. Dominant moves include fleet electrification acceleration and enterprise contract consolidation.
Among super-app operators, Grab Holdings Inc. and Gojek represent the platform consolidation archetype, leveraging user base density to cross-sell financial products. ComfortDelGro Corporation Limited anchors the regulated incumbent position, operating within license-quota frameworks. Xanh SM exemplifies the electric-first challenger model, capturing subsidy-supported replacement cycles in Vietnamese urban centers.
| Leading Market Players |
|---|
| Grab Holdings Inc. |
| Gojek |
| ComfortDelGro Corporation Limited |
| Blue Bird Group |
| TADA Mobility |
| Ryde Group Ltd. |
| Xanh SM |
| Vinasun Corporation |
| Public Cab Sdn. Bhd. |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion battery cell costs cascade through ASEAN taxi fleet procurement decisions, with Chinese and South Korean cathode production determining electric vehicle conversion premiums that operators in Bangkok and Jakarta must recover through fare tiering or subsidy capture.
Pricing Analysis
Warranty bundling separates premium fleet operators from asset-light platform intermediaries, with vehicle maintenance and driver retraining packages commanding margin premiums over bare-metal lease rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and charging infrastructure access. Pricing pressure stems from subsidy-dependent electric vehicle conversion timelines that compress replacement cycles. Corporate travel managers exhibit lowest price sensitivity due to centralized procurement contracts, while student and local resident segments drive platform-hopping behavior.
Supply Chain Analysis
Vehicle assembly rests on Thai and Indonesian manufacturing clusters for internal combustion units, while battery-electric fleets draw cells from Chinese and South Korean production hubs. Lithium carbonate, nickel sulfate, and semiconductor-grade silicon constitute critical input dependencies. Single-source vulnerability in battery cell supply creates fleet procurement risk during currency volatility episodes. Distribution runs through Grab and Gojek super-app platforms that consolidate driver supply and passenger demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet license quotas in Singapore and divergent driver certification protocols across Malaysia and Indonesia constrain capacity expansion, propping pricing power for compliant operators.
For Market Incumbents: Lock in charging infrastructure partnerships before subsidy windows close, securing captive energy supply for electric fleet conversion. Deepen backward integration into driver training academies to reduce certification cost exposure across multi-jurisdiction operations. Prioritize enterprise contract consolidation to defend margin pools against platform intermediaries.
For New Entrants and Emerging Players: Begin with provincial Philippine markets where app-based penetration remains thin, establishing density before super-app competitors deploy capital. Target Cebu and Davao corridors with two-wheel and four-wheel hybrid fleets that match local road infrastructure. Pursue white-label corporate mobility contracts as the primary go-to-market angle.
For Investors and Strategic Acquirers: Thailand's Board of Investment EV conversion subsidy exhaustion is the leading indicator that fleet replacement economics will tighten, favoring operators with secured battery supply agreements. Long-term viability centers on multi-jurisdiction certification capabilities and super-app bundling infrastructure. Acquisition targets should display vertical integration into charging networks or driver supply pools. Watch for Singapore license quota relaxation signals as the primary demand elasticity trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | Thai BOI subsidies reduce acquisition premiums for battery-electric vehicle deployment. |
| Enterprise Contract Consolidation | Singapore multinational headquarters demand unified service level agreements across mobility modes. |
| Provincial Market Penetration | Cebu and Davao corridors lack app-based density, enabling first-mover establishment. |
| Charging Infrastructure Partnership | State Grid and private utility alliances secure captive energy supply for fleet operators. |
| Driver Certification Investment | Malaysia's Land Public Transport Agency standards reshape compliance cost structures. |
Study Parameters
Regulatory filings from ASEAN transport authorities, customs import records for electric vehicle components, and platform disclosure documents formed the secondary backbone of this analysis. Primary fieldwork encompassed fleet operations directors, super-app platform strategists, charging infrastructure developers, and corporate travel procurement managers across Singapore, Indonesia, Thailand, Vietnam, and Malaysia. Bottom-up triangulation against top-down economic indicators validated volume and value estimates.
Bottom-up modeling anchored the analytical lens, with driver supply pools and trip frequency data informing fleet utilization assumptions across the projection horizon. Segmentation dimensions encompassed service tier, vehicle propulsion architecture, payment settlement mode, and customer travel purpose. CAGRs derived from regression analysis of historical fleet expansion rates against urban density and regulatory constraint variables. Electric vehicle mandate timelines and subsidy exhaustion schedules served as critical forecast inputs.
Underlying measurement precision varies by segment; ride-hailing volume estimates carry tighter precision than shared-ride unit economics due to platform disclosure availability. Forecasts reflect documented assumptions regarding subsidy continuity and battery cost trajectories. Regulatory arbitrage opportunities, currency volatility in cell import markets, and driver retention rates constitute specific risk factors that could revise projections. A small set of named triggers—Singapore license quota adjustments, Thai BOI subsidy renewals, and Vietnamese EV mandate acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Europe Van Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
India Taxi Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
North America International Express Service Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Waste Collection Vehicle Market