
 Vietnam Car Rental Market | 2026-2036
Vietnam Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Car Rental Market Outlook
Hanoi-based fleet operators are shifting toward hybrid vehicle procurement to align with Vietnam's emission reduction commitments. Mai Linh Group leverages its nationwide taxi infrastructure to sustain long-term rental contracts with corporate clients. Grab Holdings Inc. competes through app-based booking integration that anchors urban mobility demand. Vietnam Sun Corporation differentiates via airport-centric service density in Ho Chi Minh City.
Vietnam car rental encompasses short-term and long-term vehicle provisioning for commercial and personal transport, typically governed by per-day or per-kilometer pricing structures with mandatory commercial insurance coverage and periodic safety certification. The sector serves tourism, business travel, and temporary mobility substitution where vehicle ownership carries high capital commitment or regulatory burden. Chauffeur-driven services dominate revenue contribution among service types due to foreign visitor preference and local driving license restrictions. SUV and MPV categories within vehicle type segmentation capture expanding family tourism and group corporate transport demand. Mobile apps as a booking channel are displacing traditional travel agency intermediation, concentrating margin capture with platform operators.
Vietnam's Ministry of Transport mandates commercial vehicle inspection protocols that shape fleet renewal cycles and insurance underwriting standards. The country's central bank oversees digital payment licensing that affects app-based rental platform transaction architecture. Stakeholders must monitor regulatory alignment between local transport authorities and emerging electric vehicle import policies that will redefine fleet composition requirements.
Market Dynamics
Vietnam's Ministry of Transport commercial vehicle inspection protocols are compressing fleet renewal cycles and elevating insurance underwriting standards, forcing operators to accelerate capital deployment toward newer vehicle stock.
Growth Catalysts
- Inbound Tourism Recovery:International visitor arrivals to Da Nang and Ho Chi Minh City are regenerating short-term rental demand, particularly for chauffeur-driven services where foreign license restrictions apply.
- Digital Payment Infrastructure:The State Bank of Vietnam's licensing framework for e-wallet providers enables seamless app-based transactions, reducing friction in corporate account settlement and tourist bookings.
- Corporate Mobility Outsourcing:Foreign-invested enterprises in Hanoi and southern industrial zones are converting fixed vehicle assets to long-term rental contracts to optimize balance sheet efficiency.
Market Restraints
- Import Tariff Volatility:Fluctuating duties on completely built-up vehicles from Thailand and Indonesia distort fleet acquisition cost planning for rental operators.
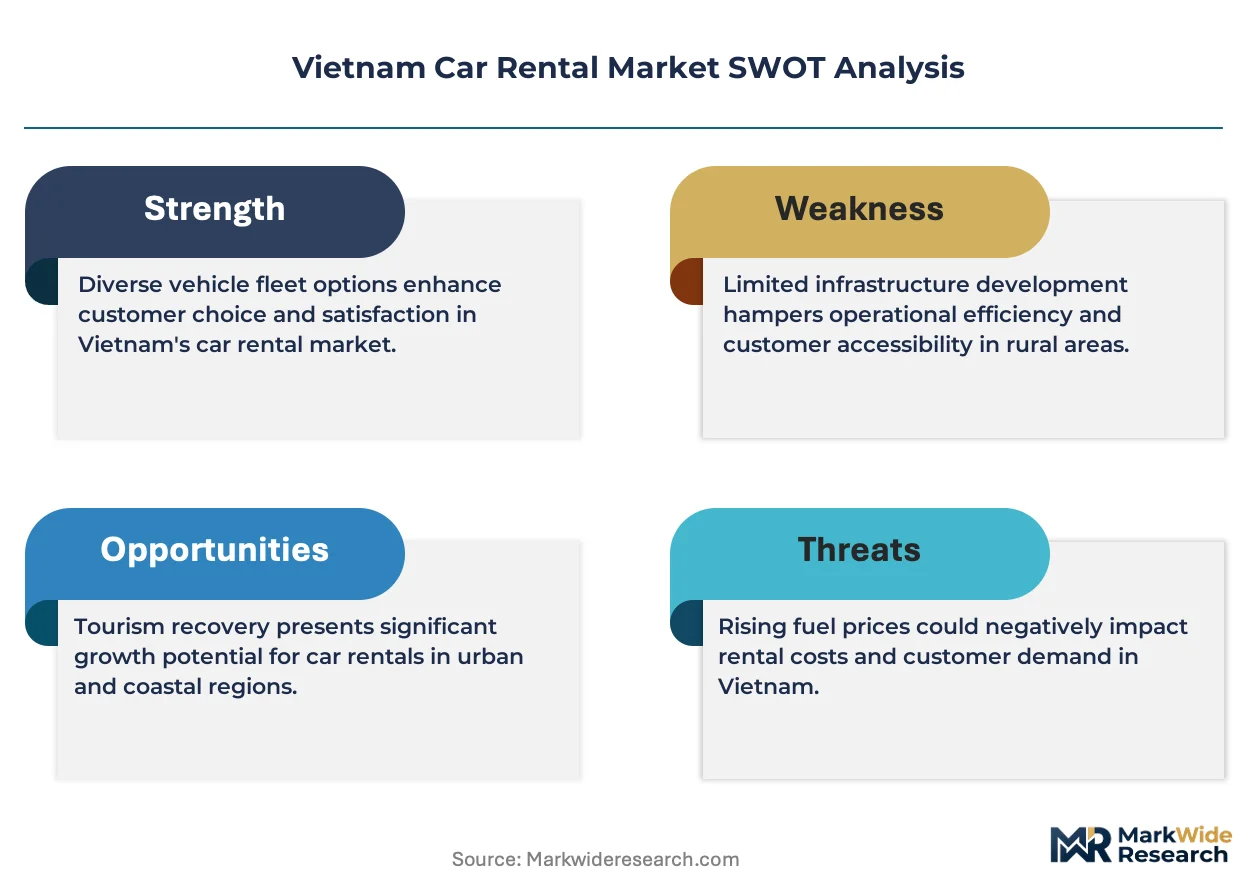
- Concentrated Refueling Infrastructure:Compressed natural gas and electric charging networks remain clustered around Hanoi and Ho Chi Minh City, limiting fleet deployment flexibility in central provinces.
- Commercial Driver Certification Bottlenecks:Vietnam's Ministry of Transport processing timelines for professional driving permits constrain chauffeur service scaling during peak tourism windows.
Strategic Opportunities
- Central Coast Tourism Corridors:Underdeveloped rental density in Hue and Quy Nhon creates first-mover positioning as infrastructure investment flows into these heritage and beach destinations.
- Electric Vehicle Fleet Transition:Vietnam's emission reduction commitments and anticipated import duty adjustments for battery electric vehicles will reward early fleet electrification.
- Intercity Corporate Shuttle Contracts:Manufacturing clusters in Binh Duong and Bac Ninh provinces generate demand for scheduled employee transport services beyond traditional taxi coverage.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems require substantial reconfiguration to interface with ride-hailing platform APIs and real-time booking engines.
- Skilled Maintenance Technician Scarcity:Hybrid and electric vehicle servicing expertise concentrates in dealership networks, creating operational dependency for independent rental operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Car Rental Market |
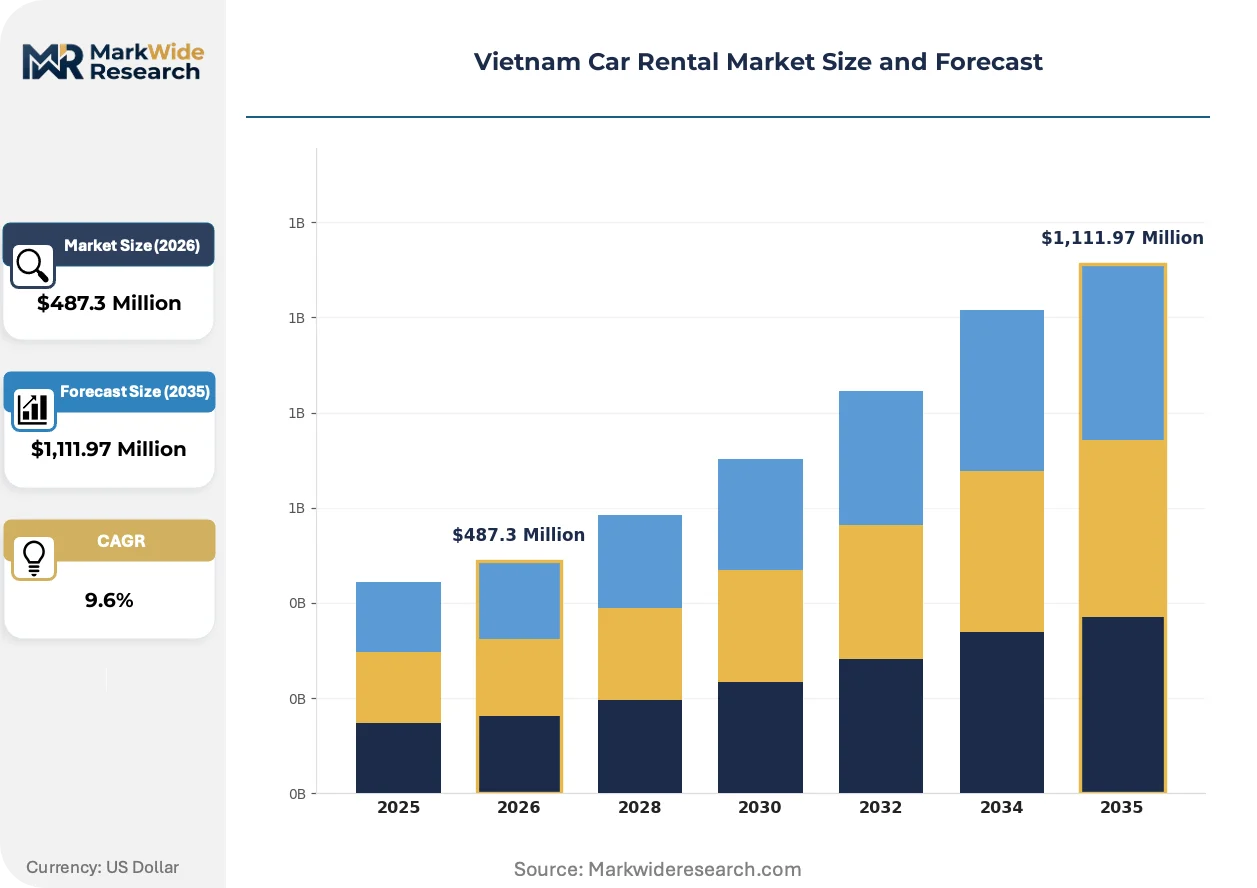
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,111.97 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Drive, Chauffeur-Driven, Long-Term Rental, Short-Term Rental Vehicle Type: Sedan, SUV, MPV, Luxury Customer Type: Corporate Clients, Tourists, Local Residents, Event Planners Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Mobile Apps |
| Companies Covered | Mai Linh Group, Enterprise Holdings, Grab Holdings Inc., Thue Xe Viet, Hertz Corporation, Green & Smart Mobility JSC, Avis Budget Group, Sixt SE, Vietnam Sun Corporation (Vinasun), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Car Rental Market Strategic Shifts
Mobile-first booking architectures are restructuring how vehicle inventory connects with demand, compressing traditional travel agency intermediation while elevating platform control over pricing and customer data.
Integrated fleet telematics is consolidating operational visibility across dispersed vehicle assets. Rental operators in Hanoi and Ho Chi Minh City are deploying GPS-enabled diagnostics and fuel monitoring systems to optimize utilization rates and reduce unauthorized usage. This technology compression is enabling outcome-based pricing models where corporate clients pay per kilometer rather than per day.
Vietnam's Ministry of Transport tightened commercial vehicle safety inspection protocols in alignment with ASEAN harmonized standards. These mandates accelerate fleet obsolescence for older vehicles while elevating insurance premium differentials between compliant and non-compliant operators. Chauffeur-driven service providers face the steepest compliance cost adjustments due to higher passenger liability exposure.
Corporate procurement teams are unbundling long-term rental contracts from bundled maintenance packages. Large manufacturing and technology employers in southern industrial zones now negotiate direct service agreements with third-party maintenance networks, pressuring rental operators to compete on transparent vehicle-only rates. This pattern is most pronounced among foreign-invested enterprises with established regional fleet management protocols.
Vietnam Car Rental Market Segmentation
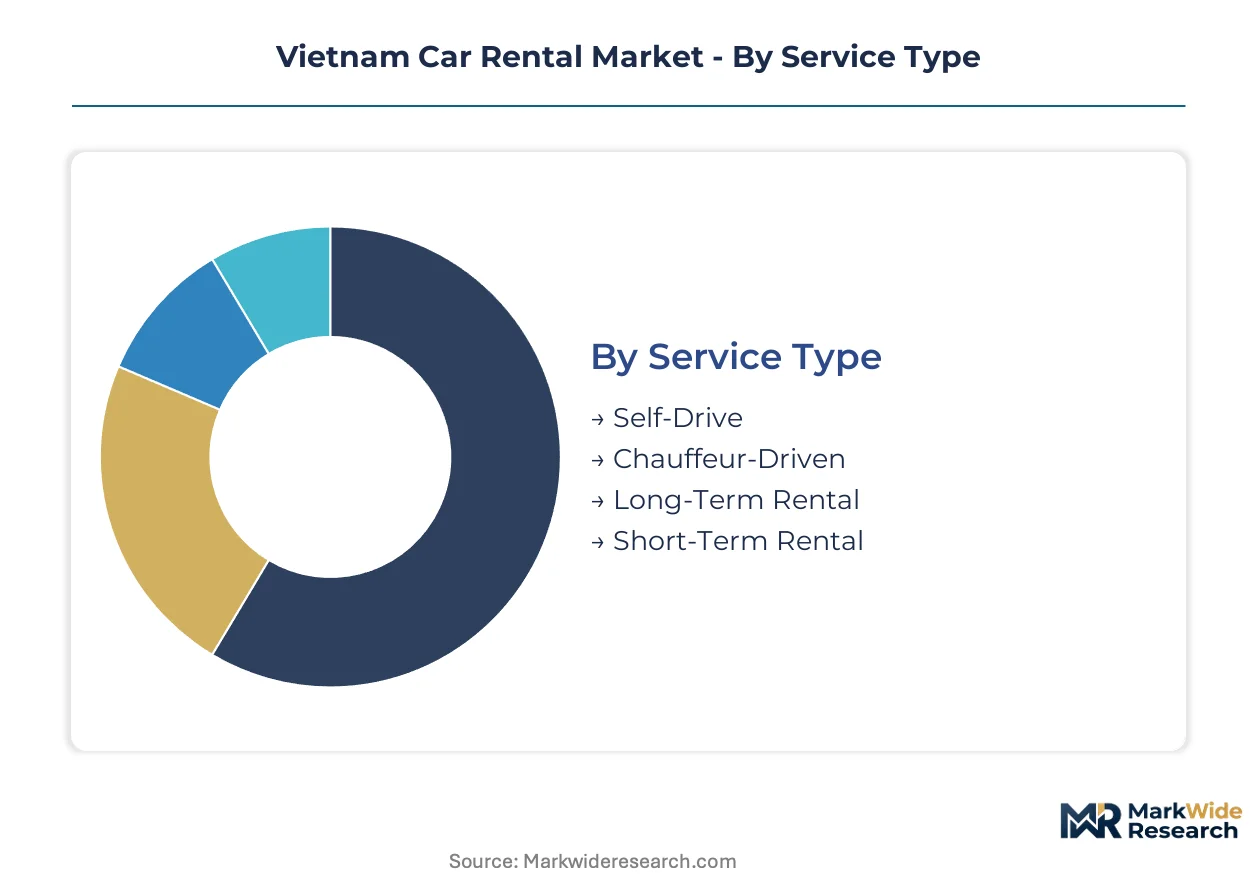
Vietnam's car rental market fragments across service delivery models, vehicle specifications, and customer procurement patterns. Each segmentation axis carries distinct capital requirements and margin profiles that shape operator strategy.
Service Type:
Capital intensity varies sharply across service models, with fleet ownership obligations and driver certification costs creating tiered entry barriers.
- Chauffeur-Driven:Operators shoulder vehicle assets plus commercial driver wages, insurance, and Vietnam Ministry of Transport permit compliance. Demand concentrates in Da Nang and Ho Chi Minh City where foreign visitor license restrictions eliminate self-drive alternatives.
- Self-Drive:Requires lower labor overhead but elevated theft prevention systems and damage deposit infrastructure. Hanoi operators report higher utilization from domestic business travelers seeking flexible urban mobility.
- Long-Term Rental:Contracts spanning 12+ months lock capital into depreciating assets with predictable revenue streams. Foreign-invested manufacturers in Bac Ninh and Binh Duong provinces favor this structure for employee transport.
- Short-Term Rental:Daily and weekly bookings demand rapid fleet turnover management and dynamic pricing algorithms. Tourism corridor operators in Hue and Quy Nhon are building density here.
Most installed capacity flows through Chauffeur-Driven services. Expansion is steepest in Long-Term Rental as corporate procurement teams outsource mobility assets.
Vehicle Type:
Acquisition cost spreads and utilization economics separate vehicle categories, with import tariff exposure distorting fleet planning across segments.
- SUV:Higher per-unit capital commitment but premium daily rates and family tourism demand in coastal provinces justify the investment. Operators in Da Nang prioritize SUV procurement for airport-hotel transfer contracts.
- MPV:Seven-to-nine seat configurations capture group corporate transport and multi-generational family travel. Ho Chi Minh City operators deploy MPVs heavily for intercity shuttle services to manufacturing zones.
- Sedan:Lowest acquisition threshold with compressed margins. Standard fleet workhorse for urban taxi-replacement and budget tourism segments.
- Luxury:Limited volume but highest per-kilometer yield. Concentrated in diplomatic and executive transport where image considerations override cost sensitivity.
Revenue concentration tilts toward SUV and MPV categories. Sedan deployment dominates unit volume despite thinner margins.
Customer Type:
Contract duration and price sensitivity diverge sharply across customer profiles, forcing operators to segment sales teams and fleet allocation.
- Corporate Clients:Multi-year contracts with standardized service level agreements and centralized billing. Foreign-invested enterprises in Hanoi and southern industrial zones drive demand for chauffeur-driven and long-term rental structures.
- Tourists:Seasonal demand spikes around Tet and summer holidays with high price elasticity. Short-term and self-drive bookings prevail among international visitors in Da Nang and Ho Chi Minh City.
- Local Residents:Occasional rental for vehicle substitution during repair periods or special occasions. Mobile app penetration is reshaping how this segment discovers and books services.
- Event Planners:Concentrated demand around conferences, weddings, and corporate gatherings requiring coordinated multi-vehicle logistics. Premium vehicle categories see disproportionate share here.
Corporate Clients anchor revenue stability. Tourists generate the steepest seasonal utilization swings.
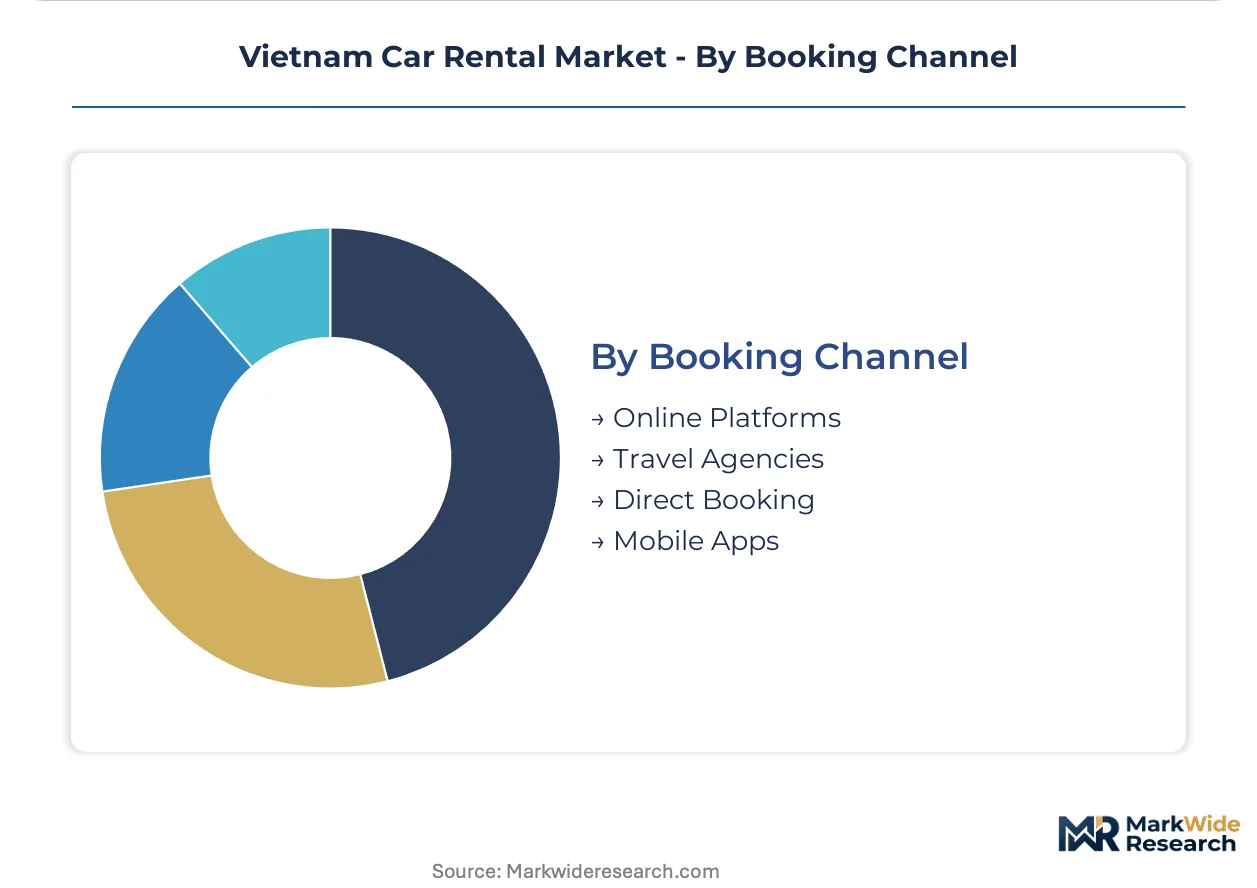
Booking Channel:
Technology infrastructure investment separates channel strategies, with platform economics favoring scale operators over fragmented agency networks.
- Mobile Apps:Requires substantial upfront development and Vietnam State Bank digital payment licensing. Grab Holdings and domestic platforms are consolidating urban demand through real-time inventory and dynamic pricing.
- Online Platforms:Web-based aggregators with lower development burden than native apps but thinning commission margins. International tourists frequently book through these channels before arrival.
- Travel Agencies:Traditional intermediation persists for package tourism and corporate travel management. Commission structures compress operator margins but deliver volume commitments.
- Direct Booking:Phone and walk-in reservations with zero platform commission but limited reach. Established operators like Mai Linh Group leverage brand recognition to sustain this channel.
Transaction volume is concentrating fastest in Mobile Apps. Direct Booking retains margin advantage for incumbents with established brand equity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Indonesia dominate fleet sourcing for Vietnamese operators, while domestic rental demand concentrates in three distinct economic corridors shaped by manufacturing investment and tourism infrastructure.
Red River Delta
Hanoi anchors northern rental demand through foreign-invested manufacturing and diplomatic transport contracts. Vietnam's Ministry of Transport mandates commercial vehicle inspection protocols that accelerate fleet turnover in this corridor. Bac Ninh province generates concentrated long-term corporate shuttle demand from electronics manufacturing clusters.
Southeast Region
Ho Chi Minh City drives premium chauffeur-driven volume through business travel and airport-hotel transfer contracts. The State Bank of Vietnam's digital payment licensing framework enables app-based platform penetration here. Binh Duong province's manufacturing zones sustain scheduled employee transport contracts beyond traditional taxi coverage.
South Central Coast
Da Nang captures international tourism arrivals regenerating short-term rental demand, particularly SUV categories for coastal resort transfers. Vietnam's emission reduction commitments are pushing operators toward hybrid procurement in this heritage destination. Quy Nhon presents underdeveloped rental density as infrastructure investment flows into beach tourism.
North Central Coast
Hue's heritage tourism generates seasonal demand spikes around festival periods with high price elasticity. Commercial driver certification bottlenecks from Vietnam's Ministry of Transport constrain service scaling during peak windows. The corridor remains underserved relative to southern tourism infrastructure.
Vietnam Car Rental Market Competitive Environment
Hanoi-based fleet operators anchor one tier; Ho Chi Minh City platform specialists hold differentiated positions through app-based booking integration. The market structures around three tiers: legacy taxi infrastructure players, international franchise operators, and technology-integrated mobility platforms. Strategic archetypes include fleet-heavy incumbents leveraging fixed asset bases, asset-light platforms capturing margin through intermediation, and airport-centric service density specialists. Competitive moves concentrate on fleet electrification commitments and corporate contract consolidation.
Within the legacy infrastructure tier, Mai Linh Group and Vietnam Sun Corporation exemplify fleet-heavy positioning built on nationwide taxi networks. Grab Holdings Inc. occupies the platform-integrated archetype, competing through real-time inventory and dynamic pricing architecture. Enterprise Holdings represents international franchise penetration targeting inbound corporate travel and diplomatic segments.
| Leading Market Players |
|---|
| Mai Linh Group |
| Enterprise Holdings |
| Grab Holdings Inc. |
| Thue Xe Viet |
| Hertz Corporation |
| Green & Smart Mobility JSC |
| Avis Budget Group |
| Sixt SE |
| Vietnam Sun Corporation (Vinasun) |
| Others |
Value Chain & Pricing Dynamics
Chauffeur-driven service premiums diverge sharply from self-drive economy tiers, compressing margins differently across fleet configurations while import tariff exposure on Thai and Indonesian vehicle sourcing reshapes procurement economics for each tier.
Pricing Analysis
Platform commission layers capture margin from operator revenue, with Grab Holdings and domestic app providers extracting transaction fees that compress fleet owner profitability. Price differentiation rests on vehicle age certification and Vietnam Ministry of Transport compliance tier, with newer hybrid fleets commanding daily rate premiums. Pricing pressure intensifies as corporate procurement teams unbundle maintenance from long-term contracts, forcing transparent vehicle-only rate competition. Tourist segments in Da Nang and Ho Chi Minh City exhibit highest price elasticity, while diplomatic and executive transport in Hanoi shows lowest sensitivity.
Supply Chain Analysis
Workforce scarcity for hybrid and electric vehicle technicians concentrates in Thailand and Indonesia dealership networks, limiting independent operator servicing flexibility. Fleet acquisition draws from completely built-up vehicle imports from Thailand, Indonesia, and Japan, with transmission and brake system components tethered to ASEAN manufacturing clusters. Supply chain risk centers on fluctuating import duties that distort capital deployment timing. Distribution runs through Ho Chi Minh City and Hanoi port corridors, with secondary logistics extending to Da Nang and Quy Nhon tourism corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's car rental market represents a late-cycle quality pivot, with inbound tourism recovery and corporate mobility outsourcing driving demand toward chauffeur-driven and hybrid fleet specifications that reward compliance investment.
For Market Incumbents: Extend fleet electrification timelines to capture anticipated import duty adjustments for battery electric vehicles, while deepening captive maintenance capabilities to offset third-party service network dependency. Vietnam Ministry of Transport inspection protocol tightening threatens older fleet obsolescence, making certification-aligned renewal the critical defensive lever. For New Entrants and Emerging Players: Mobile app channel penetration offers lowest customer acquisition friction, enabling rapid scale without legacy travel agency commission burdens. Target Quy Nhon and Hue central coast corridors where rental density remains underdeveloped relative to infrastructure investment flows, positioning for first-mover capture as beach and heritage tourism expands. For Investors and Strategic Acquirers: Consolidation pressure builds where telematics integration complexity strands legacy operators without platform API connectivity. Long-term viability favors asset-light mobility platforms and fleet-heavy incumbents with established corporate contract books over fragmented single-city operators. Watch electric vehicle import policy announcements as inflection signal for fleet valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fleet Procurement Commitment | Aligns operator positioning with Vietnam emission reduction commitments and anticipated duty advantages. |
| Telematics Platform Integration | Enables real-time utilization optimization and outcome-based corporate pricing models in Hanoi and Ho Chi Minh City. |
| Central Coast Geographic Expansion | Captures underpenetrated demand in Quy Nhon and Hue as tourism infrastructure investment accelerates. |
| Corporate Contract Consolidation | Locks predictable revenue streams from foreign-invested manufacturers in Bac Ninh and Binh Duong provinces. |
| Digital Payment Infrastructure Licensing | Secures State Bank of Vietnam e-wallet authorization for seamless app-based transaction architecture. |
Study Parameters
Direct dialogue with fleet operations directors, commercial vehicle procurement managers, tourism board officials, and digital payment platform executives grounded qualitative findings, validated against Vietnam Ministry of Transport regulatory filings, State Bank of Vietnam licensing records, customs import data, and ASEAN automotive trade statistics. Bottom-up fleet inventory analysis and top-down tourism arrival modeling were triangulated to cross-verify demand estimates.
Bottom-up segment modeling tracked vehicle deployment by service type, vehicle category, and customer archetype across the projection horizon, while top-down macroeconomic drivers anchored aggregate market sizing. CAGRs were derived from regression analysis against inbound tourism recovery trajectories and corporate outsourcing penetration rates. Segmentation incorporated propulsion technology mix, booking channel evolution, and regional corridor development patterns.
The model assumes a particular technology adoption path; alternative pathways for battery electric vehicle fleet conversion would alter the outlook if import duty schedules diverge from anticipated trajectories. Forecasts reflect assumptions regarding tourism recovery velocity, regulatory inspection enforcement intensity, and digital payment adoption curves. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Europe Van Rental Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
Poland Car Rental Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Russia Car Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Vietnam Taxi Market
Transportation Services
North America International Express Service Market
Transportation Services
Europe Refrigerated Truck Rental Market