
 China Vehicle Rental Market | 2026-2036
China Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
China Vehicle Rental Market Outlook
Aftermarket fleet management revenue is tilting toward subscription-based telematics and predictive maintenance contracts. CAR Inc. leverages its nationwide service center network to sustain high vehicle utilization rates across tier-one cities. eHi Car Service anchors its position through proprietary mobile booking infrastructure that dominates corporate account channels. Gofun Travel differentiates with dedicated EV-only operations spanning Beijing, Shanghai and Chengdu.
Vehicle rental denotes the short-term commercial provision of motorized transport assets against fixed-period contracts, encompassing daily, weekly or monthly tenure structures with mileage thresholds and insurance bundling. Operators maintain centralized fleet pools with standardized maintenance protocols to ensure asset turnover and residual value recovery. Short-term rental and car sharing capture the fastest expansion as urban consumers abandon private vehicle ownership in congested megacities. Corporate client segments generate the most stable margin pools through negotiated annual contracts with guaranteed utilization floors. Online platforms now command the dominant booking channel, displacing traditional travel agency intermediaries through direct-to-consumer pricing and real-time inventory visibility.
MIIT enforces NEV penetration quotas that mandate rising shares of electric vehicles in commercial fleets, while SAMR oversees consumer protection standards governing contract transparency and deposit handling. GB standards specify safety inspection intervals and emissions testing protocols that rental operators must document per vehicle. Dual carbon goals at the national level impose decarbonization timelines that reshape procurement decisions toward battery-electric and hybrid powertrains. Stakeholders must monitor charging infrastructure density and battery residual value curves as determinants of fleet economics and contract pricing models.
Market Dynamics
Fleet electrification mandates from MIIT are compressing procurement timelines for rental operators, forcing simultaneous capital redeployment toward charging infrastructure and battery-electric vehicle acquisition while residual value curves for internal combustion assets deteriorate.
Growth Catalysts
- Dual carbon goals:National decarbonization timelines accelerate operator procurement of battery-electric fleets, creating procurement certainty for OEMs and charging network developers.
- Corporate travel managers:Multinational firms headquartered in Shanghai and Shenzhen now mandate EV-only ground transport for employee business travel, locking in annual contract volumes.
- Airport corridor density:Pudong International and Shenzhen Bao'an have installed dedicated EV pickup zones, reducing friction for app-based sedan bookings versus counter rentals.
Market Restraints
- Battery residual value uncertainty:Rapid cell chemistry evolution and warranty transfer restrictions compress secondary market liquidity for ex-fleet electric vehicles.
- Charging infrastructure asymmetry:Tier-two and tier-three cities lack sufficient fast-charging density to support profitable EV fleet operations outside coastal corridors.
- Deposit handling regulations:SAMR consumer protection standards impose capital lockup requirements on rental deposits, constraining operator working capital flexibility.
Strategic Opportunities
- Greater Bay Area integration:Cross-border license plate liberalization between Shenzhen, Guangzhou and Hong Kong enables single-fleet coverage of three distinct regulatory jurisdictions.
- Predictive maintenance contracts:Telematics-enabled subscription revenue streams from corporate fleet clients diversify operator income beyond per-day rental yields.
- GB standards harmonization:Unified national safety inspection and emissions testing protocols reduce compliance fragmentation across provincial operating licenses.
Industry Challenges
- EV technician scarcity:High-voltage battery diagnostics and repair certification lags fleet electrification timelines, extending vehicle downtime during maintenance events.
- Legacy reservation system integration:Proprietary mobile booking platforms must interface with corporate travel management systems that still rely on EDIFACT messaging standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Vehicle Rental Market |
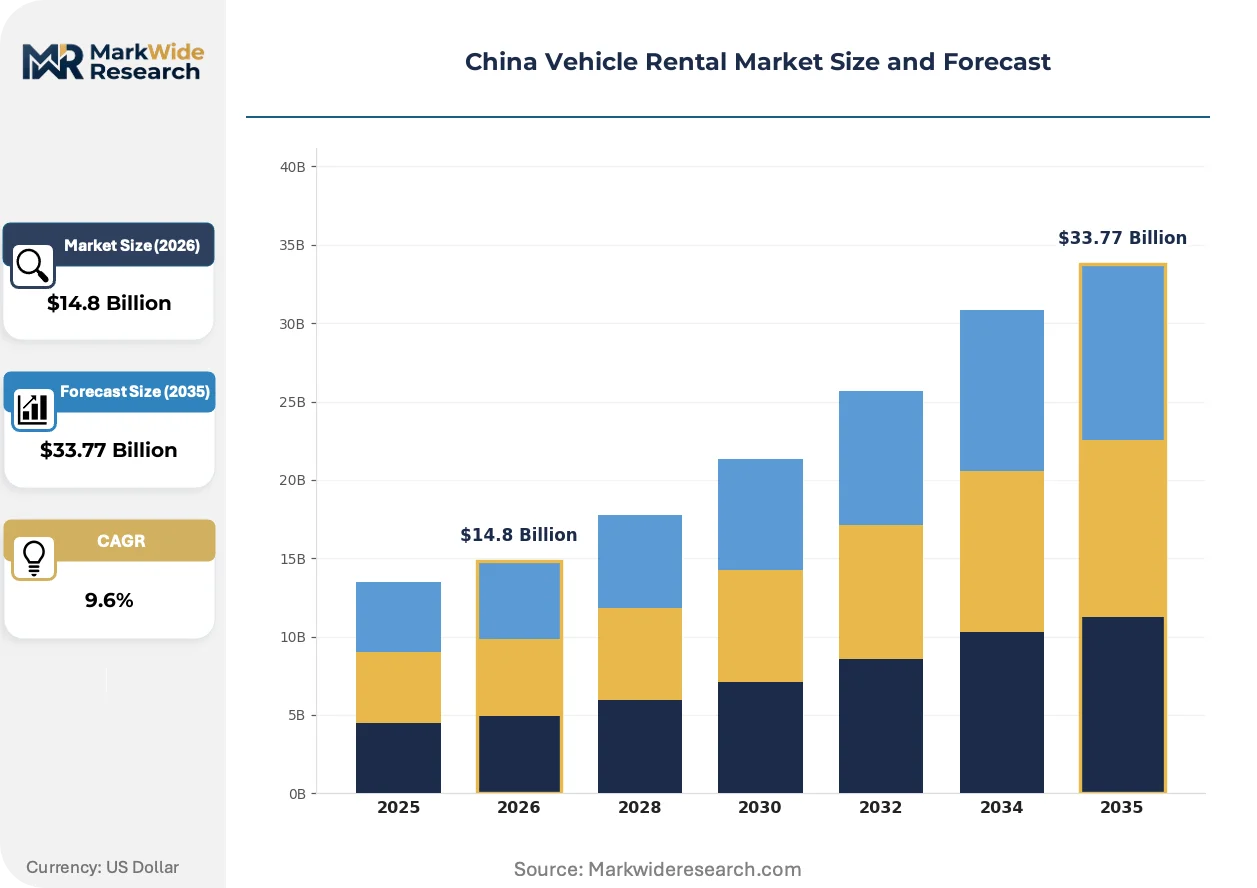
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rental, Long-Term Lease, Chauffeur Services, Car Sharing Vehicle Type: Sedan, SUV, Van, Luxury Car Customer Type: Corporate Clients, Tourists, Local Users, Government Agencies Distribution Channel: Online Platforms, Travel Agencies, Direct Booking, Affiliate Programs |
| Companies Covered | Beijing China Auto Rental (CAR Inc.), eHi Car Service, Shouqi Car Rental, Shenzhen Topone Car Rental, Didi Car Rental, EVCard, Gofun Travel, Caocao Mobility, Shenzhou Joy Travel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Vehicle Rental Market Strategic Shifts
Telematics-enabled fleet management is migrating from hardware-centric installations toward software-defined vehicle access, compressing the distinction between rental operators and mobility service platforms while reshaping how corporate procurement teams evaluate vendor capability.
Cellular vehicle-to-everything modules are migrating from aftermarket add-ons to factory-integrated standard equipment on new fleet acquisitions. Rental operators in Beijing and Shanghai now specify embedded connectivity as a procurement requirement for corporate contract eligibility. This capability migration from retrofitted dongles to OEM-native architecture is compressing the addressable market for third-party telematics hardware suppliers while elevating data sovereignty concerns among multinational lessees.
MIIT's NEV penetration quotas impose rising electric vehicle share requirements on commercial fleet operators each calendar year. GB standards for battery safety testing and fire suppression documentation have tightened inspection intervals for high-mileage rental assets. Operators in the Yangtze River Delta are responding by consolidating fleet procurement around single OEM partnerships to simplify compliance documentation and warranty claim processing.
Corporate travel procurement teams now book ground transport through integrated expense management platforms rather than standalone rental websites or travel agency intermediaries. This channel consolidation compresses commission structures and elevates real-time inventory visibility to a competitive threshold capability. The shift is most visible among technology and financial services firms with headquarters in Shanghai's Lujiazui district and Shenzhen's Nanshan corridor.
China Vehicle Rental Market Segmentation
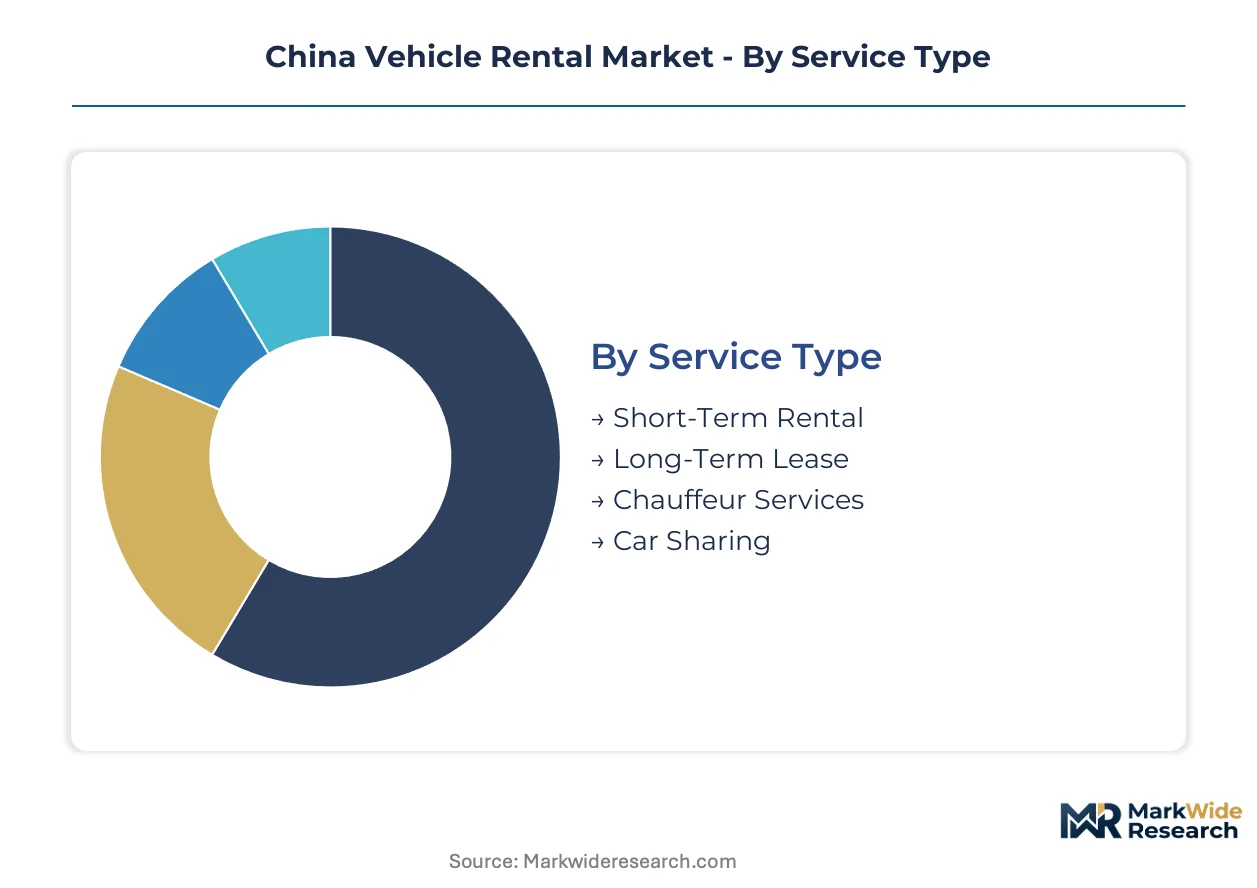
Segmentation in the China vehicle rental market reveals how fleet operators allocate capital across tenure structures and customer profiles. Each dimension carries distinct after-sales-service intensity, from predictive maintenance contracts for corporate fleets to minimal touch requirements for short-term tourist rentals.
Service Type:
After-sales-service intensity varies sharply across tenure structures, with long-term corporate leases demanding embedded telematics monitoring and scheduled maintenance protocols while short-term rentals prioritize rapid vehicle turnaround over deep service relationships.
- Short-Term Rental:Daily to weekly contracts with mileage caps and bundled insurance dominate airport corridors and downtown pickup zones. Shanghai Pudong and Shenzhen Bao'an have installed dedicated EV pickup infrastructure, compressing counter transaction times for business travelers booking through mobile apps.
- Long-Term Lease:Multi-month to annual contracts with guaranteed utilization floors generate the most stable margin pools. Corporate procurement teams at multinational firms in Shanghai's Lujiazui district and Shenzhen's Nanshan corridor now mandate EV-only ground transport, locking in predictable revenue streams for operators with electrified fleets.
- Chauffeur Services:Driver-provided transport for executive travel and special events commands premium pricing with high labor coordination overhead.
- Car Sharing:Minute-based urban access models target consumers abandoning private ownership in congested megacities.
By volume, Short-Term Rental leads. By growth pace, Car Sharing is ahead.
Vehicle Type:
Procurement cost tiers separate fleet composition strategies, with luxury electrified sedans capturing corporate contract premiums while utilitarian vans serve price-sensitive local demand in tier-two cities.
- Sedan:Battery-electric and hybrid powertrains dominate new fleet acquisitions as MIIT penetration quotas tighten. GB standards for battery safety testing and fire suppression documentation have compressed inspection intervals, pushing Yangtze River Delta operators toward single-OEM partnerships to simplify compliance.
- SUV:Higher acquisition costs and fuel consumption are offset by family and outbound tourist demand for intercity travel. Corporate travel managers in Beijing and Shanghai specify embedded connectivity as a procurement requirement, elevating factory-integrated telematics over aftermarket retrofits.
- Van:Commercial cargo and group transport applications prioritize durability and load capacity over electrification timelines.
- Luxury Car:Premium branding and concierge service bundling target high-net-worth individual and executive segments.
Sedan deployments dominate fleet counts. Luxury Car contracts deliver the steepest expansion trajectory in revenue per unit.
Customer Type:
Margin profiles diverge across customer categories, with corporate accounts yielding predictable annual volumes and government tenders imposing strict compliance documentation requirements that favor established operators with nationwide service networks.
- Corporate Clients:Negotiated annual contracts with guaranteed utilization floors and integrated expense management platform connectivity. Multinational technology and financial services firms headquartered in Shanghai and Shenzhen now book ground transport through consolidated procurement channels rather than standalone rental websites.
- Tourists:Seasonal demand concentration around national holidays and international gateway cities. Airport corridor density at Pudong International and Shenzhen Bao'an reduces friction for app-based bookings versus traditional counter rentals.
- Local Users:Urban residents supplementing public transit or replacing private vehicle ownership.
- Government Agencies:Public procurement tenders with mandatory NEV share requirements and centralized fleet management protocols.
Corporate Clients anchor revenue stability. Local Users are gaining share fastest as urban congestion charges and parking scarcity deepen.
Distribution Channel:
Channel economics reshape operator investment priorities, with proprietary mobile infrastructure commanding corporate eligibility while affiliate partnerships extend geographic reach without capital-heavy fleet duplication.
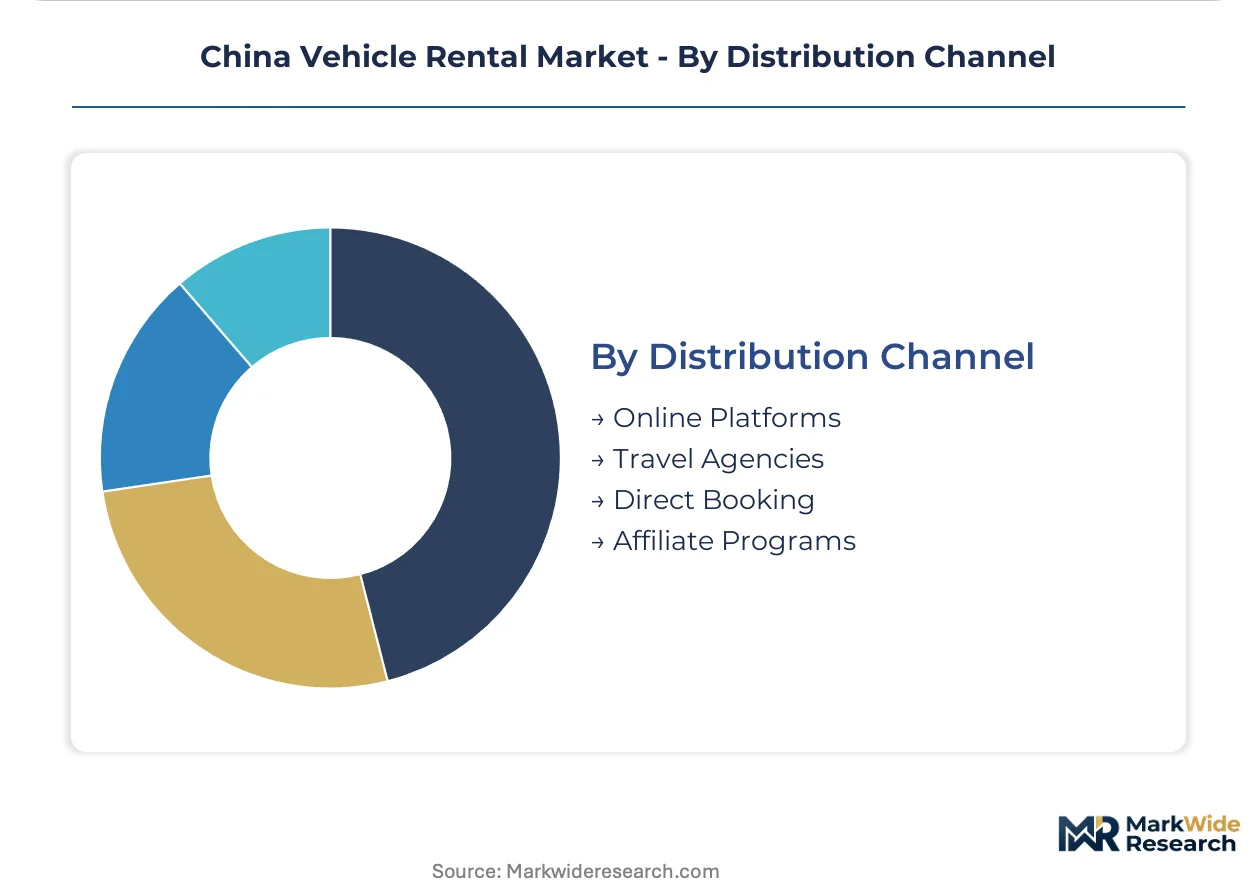
- Online Platforms:Direct-to-consumer pricing and real-time inventory visibility have displaced traditional travel agency intermediaries. Corporate travel procurement teams now require platform integration with expense management systems, compressing commission structures and elevating API connectivity to competitive threshold capability.
- Travel Agencies:Legacy intermediaries retain niche positioning for inbound international tourists and package tour bundling.
- Direct Booking:Operator-owned websites and call centers serving repeat customers and negotiated corporate accounts.
- Affiliate Programs:Third-party partnerships extending fleet availability without asset ownership, common in tier-three city penetration strategies.
Online Platforms handle the majority of transaction volume. Direct Booking is climbing the fastest as operators invest in proprietary mobile infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators concentrate procurement and charging infrastructure deployment along three coastal corridors where MIIT electrification mandates intersect with corporate demand density. Provincial operating licenses and GB standards compliance create sub-regional fragmentation that favors established networks with nationwide service center coverage.
Yangtze River Delta
Shanghai Pudong International Airport and the Lujiazui financial district generate concentrated business travel demand for battery-electric sedans. MIIT NEV penetration quotas enforce rising annual electric vehicle share requirements on commercial fleets operating across Jiangsu and Zhejiang provinces. CAR Inc. leverages its nationwide service center network to sustain high utilization rates across Shanghai, Hangzhou and Nanjing.
Pearl River Delta
Shenzhen Bao'an International Airport and the Nanshan technology corridor anchor corporate ground transport procurement for multinational firms. Dual carbon goals impose decarbonization timelines that reshape fleet procurement toward battery-electric powertrains in Guangdong province. Cross-border license plate liberalization between Shenzhen, Guangzhou and Hong Kong enables single-fleet coverage of three distinct regulatory jurisdictions.
Beijing-Tianjin-Hebei
Government agency tenders and state-owned enterprise travel budgets sustain demand for chauffeur services and long-term leased vehicles. GB standards for battery safety testing and fire suppression documentation tighten inspection intervals for high-mileage rental assets. Gofun Travel differentiates with dedicated EV-only operations spanning Beijing, Shanghai and Chengdu.
Sichuan-Chongqing
Chengdu's expanding airport infrastructure and inland technology park development attract corporate relocation from coastal cost centers. SAMR consumer protection standards impose capital lockup requirements on rental deposits, constraining operator working capital flexibility across western provinces. eHi Car Service anchors its position through proprietary mobile booking infrastructure that dominates corporate account channels.
China Vehicle Rental Market Competitive Environment
Nationwide fleet operators and regional specialists split the market along infrastructure intensity and technology platform differentiation. Consolidation pressure favors players with proprietary charging networks and integrated telematics systems. Strategic archetypes include asset-heavy fleet owners with service center density and asset-light mobility platforms with software-defined vehicle access. Dominant competitive moves encompass single-OEM procurement partnerships to simplify compliance documentation and API integration with corporate expense management systems.
Within the asset-heavy tier, Beijing China Auto Rental and Shouqi Car Rental exemplify nationwide network operators with service center infrastructure spanning tier-one and tier-two cities. Among platform-centric specialists, Gofun Travel occupies a position as an EV-native operator with concentrated presence in Beijing, Shanghai and Chengdu. Didi Car Rental sits within the mobility ecosystem tier, leveraging ride-hailing user bases to cross-sell rental services through integrated app interfaces.
| Leading Market Players |
|---|
| Beijing China Auto Rental (CAR Inc.) |
| eHi Car Service |
| Shouqi Car Rental |
| Shenzhen Topone Car Rental |
| Didi Car Rental |
| EVCard |
| Gofun Travel |
| Caocao Mobility |
| Shenzhou Joy Travel |
| Others |
Value Chain & Pricing Dynamics
Fleet utilization rates above 75% across Shanghai and Shenzhen signal tight capacity conditions that embolden operators to push through rate increases while compressing supplier payment terms for charging infrastructure vendors. This utilization dynamic simultaneously elevates working capital demands and strengthens pricing power at the counter.
Pricing Analysis
Predictive maintenance contracts and telematics subscriptions now generate the majority of lifetime value per corporate fleet account. Three-tier pricing structure across premium, standard, and economy levels segments the market by service bundling intensity and vehicle electrification status. Pricing pressure stems from battery residual value uncertainty as rapid cell chemistry evolution compresses secondary market liquidity for ex-fleet electric vehicles. Local users booking through minute-based car sharing platforms exhibit the highest price sensitivity, while multinational corporate travel managers prioritize guaranteed utilization floors over per-day rate negotiations.
Supply Chain Analysis
Export-control restrictions on advanced battery management systems and high-voltage power electronics constrain technology flows from US and European suppliers into Chinese fleet procurement channels. Battery cell manufacturing concentrates in China, South Korea, and Japan, with lithium carbonate sourcing anchored in Australia and Chile. Lithium iron phosphate cathodes, nickel-manganese-cobalt cells, and silicon-anode materials constitute critical input dependencies. Single-source vulnerability around proprietary battery chemistries from CATL and BYD elevates fleet operator procurement risk. Distribution runs through OEM-direct fleet sales agreements rather than traditional dealer networks, compressing intermediary margins and accelerating direct manufacturer-operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from integrated mobility platforms that bundle ride-hailing, public transit, and micro-mobility into unified subscription offerings, eroding standalone rental demand among urban consumers.
For Market Incumbents: Pre-empt platform consolidation by acquiring proprietary charging infrastructure in the Yangtze River Delta and Pearl River Delta corridors before real estate scarcity elevates site costs. Lock in multi-year battery supply agreements with CATL or BYD to hedge against cell chemistry transition risks that threaten fleet standardization. Channel control through integrated expense management API connectivity defends corporate account retention against Didi's mobility ecosystem cross-selling.
For New Entrants and Emerging Players: Establish a beachhead in tier-two city EV fleet operations where charging infrastructure asymmetry has deterred incumbent expansion and local regulatory enforcement remains fragmented. Target Sichuan-Chongqing corridor corporate relocations from coastal cost centers, where SAMR deposit handling regulations constrain established operator working capital flexibility. Go-to-market leverage rests on white-label telematics partnerships with corporate travel management platforms rather than proprietary app development.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric fleet transitions as charging infrastructure deployment and high-voltage technician certification demands outpace depreciation schedules. Long-term viability favors asset-heavy operators with nationwide service center density capable of sustaining utilization rates through maintenance integration. Acquisition target archetype: regional specialists with established OEM partnerships and GB standards compliance documentation. Watch MIIT NEV penetration quota acceleration as the inflection signal forcing consolidation among undercapitalized operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures site exclusivity in Pudong and Nanshan corridors before real estate scarcity elevates deployment costs. |
| Battery Supply Agreement | Locks in cell chemistry standardization with CATL or BYD to simplify GB standards compliance documentation. |
| Telematics Platform Integration | Embeds operator inventory into corporate expense management systems through API connectivity, displacing travel agency intermediaries. |
| Single-OEM Procurement Consolidation | Reduces warranty claim processing complexity and inspection interval documentation burden under MIIT mandates. |
| Predictive Maintenance Contract Launch | Diversifies revenue streams beyond per-day rental yields through subscription-based fleet monitoring services. |
Study Parameters
Operator-level perspectives from fleet procurement directors, charging infrastructure developers, corporate travel managers, and MIIT compliance officers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from vehicle production databases, customs records on battery imports, and SAMR regulatory filings established demand and supply parameters. Bottom-up fleet size estimates by operator and top-down macroeconomic indicators were triangulated to cross-check magnitude and direction.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning service type, vehicle propulsion architecture, customer category, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for electric vehicle penetration and corporate contract renewal rates. Forecast inputs incorporated MIIT NEV quota trajectories and charging infrastructure deployment schedules by provincial jurisdiction.
Stress conditions across battery residual value curves, charging network density thresholds, and SAMR deposit regulation enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet electrification timelines and corporate procurement platform adoption. Material shifts in dual carbon goal acceleration or cross-border license plate liberalization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Thailand Car Rental Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Poland Car Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Bike and Scooter Rental Market
Transportation Services
Global Taxi Market
Transportation Services
Europe Van Rental Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Bird Carriers Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Ship Management Software Market
Transportation Services
Europe Refrigerated Truck Rental Market