
 Cross Docking Services Market | 2026-2036
Cross Docking Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cross Docking Services Market Analysis
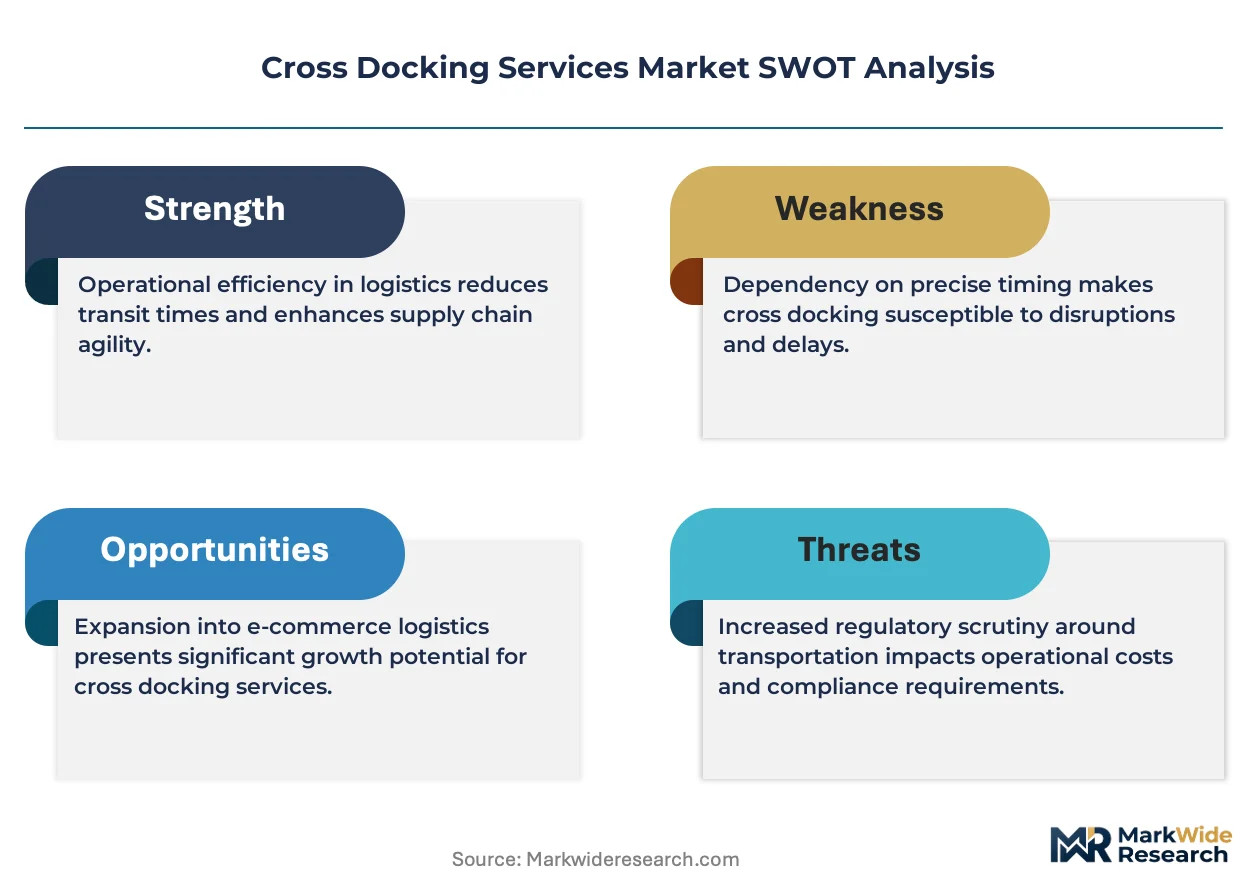
Third-party logistics providers are collapsing lead times for mid-market retailers that previously relied on dedicated warehousing. DB Schenker leverages its European rail-terminal network to sustain high-velocity consolidation across multiple industry verticals. C.H. Robinson Worldwide anchors North American freight matching through proprietary digital brokerage platforms that compete on lane density rather than asset ownership.
Cross docking services entail the direct transfer of goods from inbound to outbound transportation with minimal or zero storage dwell time, typically requiring dock-to-dock completion within 24 hours and real-time shipment visibility systems. The operational purpose centers on eliminating inventory carrying costs while synchronizing supply with demand signals from downstream buyers. Inventory management and consolidation services dominate margin pools as shippers prioritize freight density over pure transportation speed. Road transport leads delivery mode selection for regional distribution, though rail intermodal is gaining share on corridors exceeding 500 miles. Small enterprises and wholesale distributors represent the fastest-growing customer type as distributed inventory strategies fragment order sizes.
The US Federal Motor Carrier Safety Administration enforces hours-of-service limits that compress allowable driving windows, forcing consolidation at cross-dock nodes to maintain delivery velocity. The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles raise compliance costs for long-haul trucking, redirecting investment toward hub-based freight optimization. Stakeholders must monitor how California's Advanced Clean Trucks regulation propagates zero-emission mandates into terminal equipment procurement decisions.
Market Dynamics
E-commerce fulfillment networks are compressing inventory cycles, forcing cross-dock operators to synchronize inbound freight with outbound last-mile dispatch within shrinking time windows. The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles are redirecting capital toward hub-based freight optimization rather than long-haul fleet expansion.
Growth Catalysts
- Hours-of-service compression:The US Federal Motor Carrier Safety Administration's driving window limits force freight consolidation at cross-dock nodes to maintain delivery velocity without extending driver schedules.
- Just-in-time inventory models:Retailers and wholesale distributors are adopting distributed inventory strategies that fragment order sizes and increase demand for rapid consolidation services.
- Rail intermodal corridors:Corridors exceeding 500 miles are shifting volume from road transport to rail intermodal, expanding addressable market for terminal-based cross-dock operations.
Market Restraints
- Zero-emission equipment mandates:California's Advanced Clean Trucks regulation propagates into terminal equipment procurement, raising compliance costs for yard tractors and material handling equipment.
- Real-time visibility infrastructure:Dock-to-dock completion within 24 hours requires shipment visibility systems that demand significant IT integration spend.
- Driver availability constraints:Hours-of-service regulations reduce effective driver supply, creating bottlenecks at consolidation nodes during peak freight windows.
Strategic Opportunities
- Mid-market retail penetration:Third-party logistics providers can collapse lead times for mid-market retailers that previously relied on dedicated warehousing, capturing share from captive distribution networks.
- Rail-terminal network leverage:European rail-terminal infrastructure supports high-velocity consolidation across multiple industry verticals, creating template for North American replication.
- Digital brokerage integration:Proprietary freight matching platforms compete on lane density rather than asset ownership, opening margin expansion through technology rather than capital deployment.
Industry Challenges
- Warehouse management system integration:Legacy enterprise resource planning platforms require costly retrofit to achieve real-time inventory synchronization with cross-dock operations.
- Specialized terminal labor:High-velocity freight handling demands skilled dock coordinators capable of managing simultaneous inbound and outbound flows with minimal dwell time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross Docking Services Market |
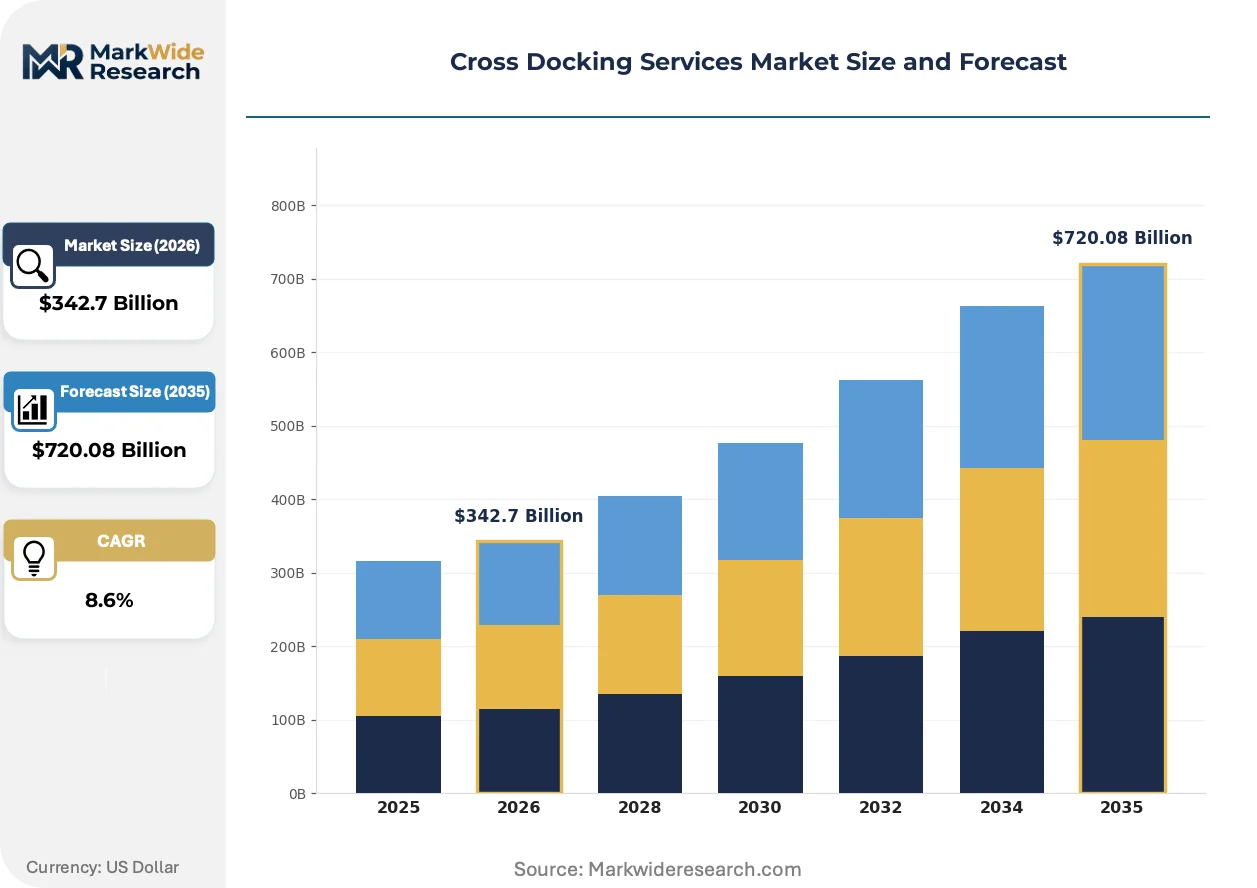
| Market Size in 2026 | $342.7 Billion |
| Market Size in 2035 | $720.08 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Direct Delivery, Inventory Management, Consolidation, Deconsolidation Industry Vertical: Retail, E-Commerce, Manufacturing, Food & Beverage Delivery Mode: Road Transport, Rail Transport, Air Freight, Sea Freight Customer Type: Small Enterprises, Large Corporations, Third-Party Logistics, Wholesale Distributors |
| Companies Covered | DB Schenker, CEVA Logistics, XPO Logistics, C.H. Robinson Worldwide, GEODIS, DHL Supply Chain, Kuehne + Nagel, DSV, UPS Supply Chain Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross Docking Services Market Emerging Trajectories
Operational technology investments are redefining competitive differentiation in cross-dock services, with automation and data integration displacing pure location advantages. Three developments are restructuring how freight consolidators capture value.
Automated yard management systems are fragmenting traditional dispatch scheduling. These platforms coordinate tractor-trailer movements between gates, doors, and staging areas using real-time location tracking. Mid-market 3PL providers are adopting these systems fastest to compensate for smaller door counts. The technology is fragmenting scale advantages previously held by large asset-based carriers with dedicated yard crews.
The EPA's Phase 3 greenhouse gas standards are accelerating terminal electrification investments. Compliance costs for long-haul diesel tractors are pushing shippers toward shorter haul segments connected by electrified hub operations. California's Advanced Clean Trucks regulation is forcing the earliest equipment turnover, with terminal operators there piloting battery-electric yard tractors ahead of federal mandates.
Shippers are unbundling transportation from inventory carrying, contracting cross-dock providers for pure consolidation rather than warehousing. Wholesale distributors and small enterprises are driving this shift, fragmenting order sizes across multiple fulfillment nodes. Texas and California distribution clusters show the highest concentration of this procurement pattern, with retailers demanding dock-to-dock velocity over storage flexibility.
Cross Docking Services Market Segmentation
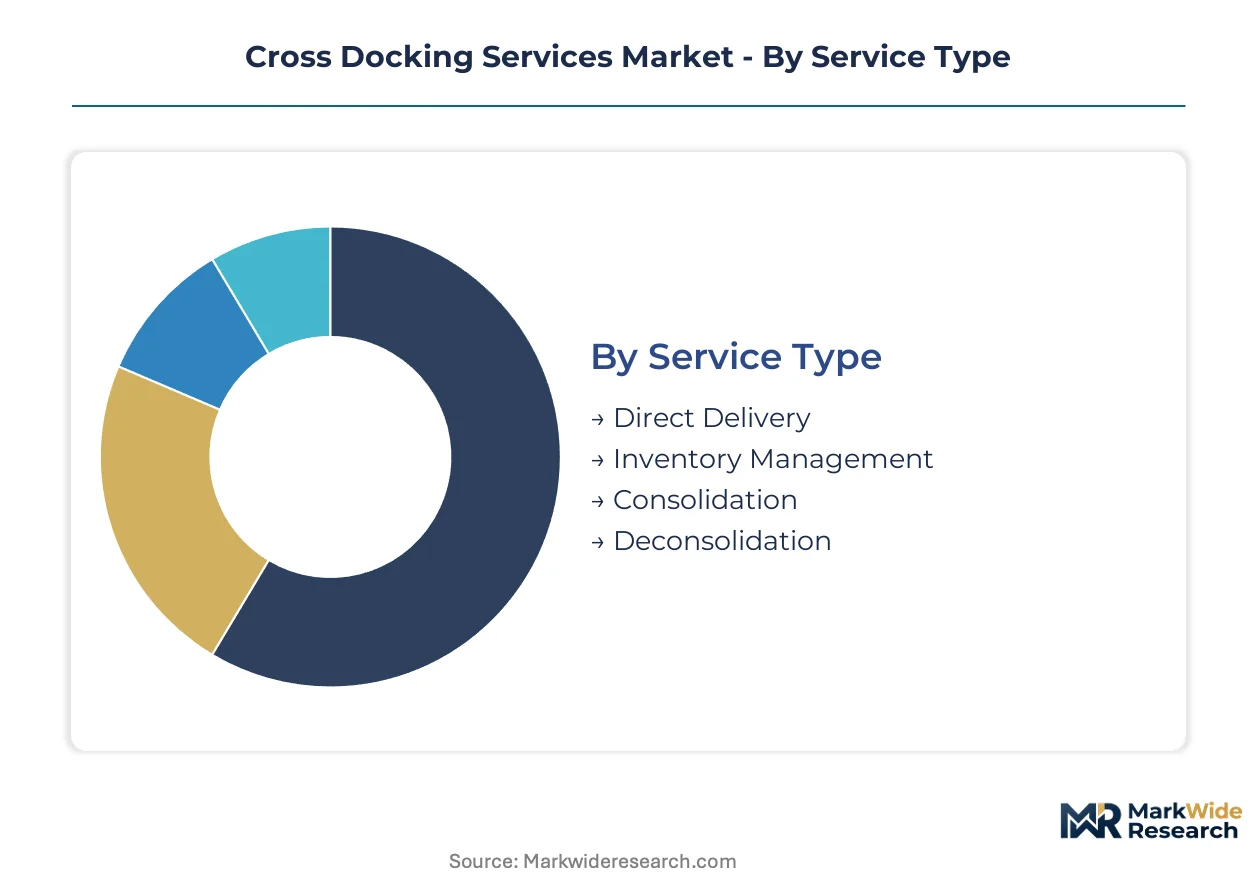
Service differentiation in cross docking determines capital intensity and margin structure. Shippers select providers based on dwell-time guarantees, modal flexibility, and synchronization with downstream distribution networks.
Service Type:
Regulatory pressure on driver hours and emissions standards fragments service demand across velocity tiers. The EPA's Phase 3 greenhouse gas standards and California's Advanced Clean Trucks regulation push shippers toward hub-based consolidation over long-haul point-to-point delivery.
- Inventory Management:Synchronizes inbound freight with outbound dispatch through real-time visibility systems. Demand concentrates among mid-market retailers adopting distributed inventory strategies in Texas and California distribution clusters, driven by just-in-time fulfillment requirements from e-commerce channels.
- Consolidation:Combines multiple less-than-truckload shipments into full truckload configurations at terminal nodes. Food & beverage distributors in the United States dominate adoption, pressured by FMCSA hours-of-service limits that compress allowable driving windows and force freight density optimization.
- Direct Delivery:Transfers goods from inbound to outbound transport with zero storage dwell time.
- Deconsolidation:Breaks bulk shipments into smaller configurations for last-mile distribution.
Inventory Management handles the majority of throughput; Consolidation is expanding most quickly on share.
Industry Vertical:
Cost tier differentiation separates asset-heavy from technology-enabled providers. High-velocity verticals command premium pricing for dock-to-dock completion within 24 hours.
- E-Commerce:Demands synchronized inbound and outbound flows to support same-day and next-day delivery promises. Amazon, Walmart, and Target fulfillment networks in the United States drive specification standards, with procurement favoring providers capable of sub-4-hour dock-to-dock cycles during peak windows.
- Retail:Balances seasonal volume spikes with year-round consolidation efficiency. Mid-market apparel and general merchandise retailers in California and Texas are migrating from dedicated warehousing to third-party cross-dock arrangements to reduce fixed cost exposure.
- Food & Beverage:Requires temperature-controlled handling and rapid turnover to maintain shelf life.
- Manufacturing:Synchronizes component inbound with production schedules to minimize work-in-process inventory.
E-Commerce captures the highest revenue concentration; Retail is climbing the fastest on share.
Delivery Mode:
Volume concentration follows corridor distance thresholds. Modal selection hinges on fuel cost differentials and terminal access rather than pure transit time.
- Road Transport:Dominates regional distribution under 500 miles with flexible routing and direct store delivery capabilities. Wholesale distributors and small enterprises in the United States rely on road-based cross-dock networks for fragmented order sizes across multiple fulfillment nodes.
- Rail Transport:Gains share on corridors exceeding 500 miles where intermodal cost advantages outweigh longer transit times. The BNSF and Union Pacific terminal networks in Texas and California support high-velocity consolidation for retail and manufacturing shippers.
- Air Freight:Serves time-critical shipments with premium pricing and limited terminal infrastructure.
- Sea Freight:Connects port-centric distribution with inland cross-dock facilities for import containerized cargo.
Road Transport handles the majority of throughput; Rail Transport is gaining share fastest.
Customer Type:
Customer maturity determines contract structure and technology integration requirements. Small enterprises demand rapid deployment without legacy system retrofit.
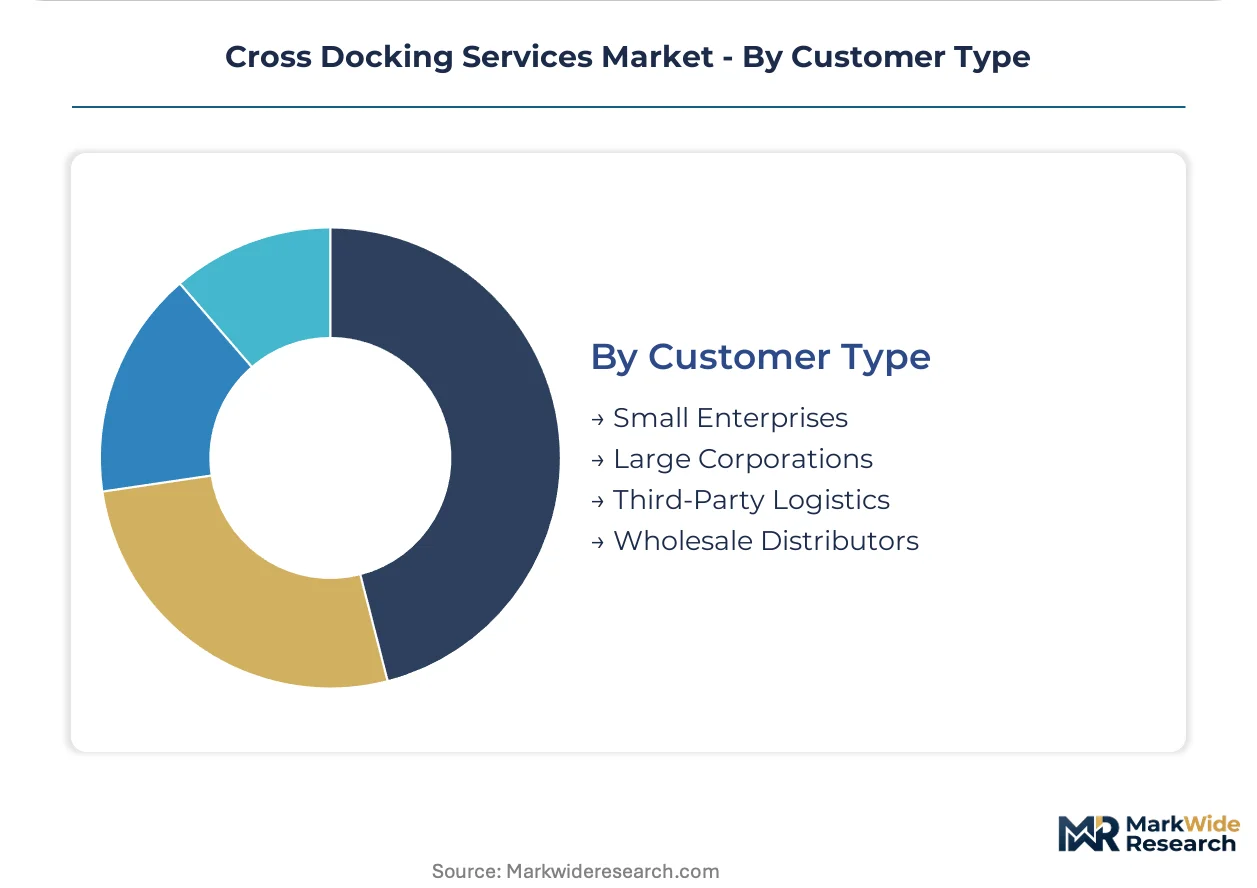
- Small Enterprises:Fragment order sizes across distributed inventory nodes without captive distribution infrastructure. These customers in the United States are driving fastest adoption of third-party cross-dock services as they abandon dedicated warehousing for variable-cost consolidation.
- Wholesale Distributors:Unbundle transportation from inventory carrying to focus on sourcing and customer relationships. Food & beverage and industrial supply distributors in Texas and California distribution clusters show highest concentration of this procurement pattern.
- Third-Party Logistics:Leverage cross-dock capabilities as a service layer within broader supply chain contracts.
- Large Corporations:Maintain hybrid models combining captive terminals with outsourced peak capacity.
Wholesale Distributors handle the majority of throughput; Small Enterprises show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border freight corridors from China and Germany into North American consumer markets are reshaping terminal infrastructure requirements. Distribution clusters concentrate around major port gateways and inland rail hubs where consolidation velocity determines competitive positioning.
United States
E-commerce fulfillment networks and FMCSA hours-of-service regulations drive terminal densification in Texas and California. The EPA's Phase 3 greenhouse gas standards redirect capital toward hub-based freight optimization. Dallas-Fort Worth and Los Angeles Basin distribution clusters show highest concentration of automated yard management deployments.
Germany
European rail-terminal networks support high-velocity consolidation for automotive and industrial verticals. The EU Green Deal and national emissions standards accelerate terminal electrification investments. Rhine-Ruhr and Bavarian logistics corridors anchor continental cross-dock throughput.
China
Manufacturing export flows and domestic consumption expansion multiply demand for port-centric consolidation. Dual carbon goals and MEE emissions standards pressure terminal operators toward electrified equipment. Yangtze River Delta and Pearl River Delta megaclusters dominate intermodal freight handling volume.
Netherlands
Rotterdam port throughput and European distribution gateway functions concentrate value-added logistics services. REACH compliance and CSRD reporting requirements shape terminal operator investment priorities. Randstad logistics corridor integrates sea-rail-road modes for continental freight distribution.
India
Distributed inventory strategies and e-commerce penetration fragment order sizes across multiple fulfillment nodes. PLI scheme incentives and BIS standards influence terminal infrastructure specifications. Maharashtra and Gujarat industrial corridors show fastest adoption of third-party cross-dock arrangements.
Cross Docking Services Market Vendor Landscape
Listed leaders compete with private specialists across asset ownership and technology-enabled service models. The vendor base fragments between asset-heavy terminal operators and digital freight brokers competing on lane density. Three archetypes dominate: integrated 3PL networks, specialized rail-terminal operators, and proprietary digital brokerage platforms. Capacity expansion and strategic technology partnerships represent the dominant competitive moves as players seek synchronization capabilities without fixed asset burdens.
Within the integrated 3PL tier, DB Schenker and DHL Supply Chain exemplify rail-terminal network leverage across multiple geographies. C.H. Robinson Worldwide occupies a position representing digital brokerage specialization, competing through proprietary platforms rather than captive infrastructure. These three anchors illustrate the strategic divergence between asset ownership and technology-enabled service delivery in high-velocity freight consolidation.
| Leading Market Players |
|---|
| DB Schenker |
| CEVA Logistics |
| XPO Logistics |
| C.H. Robinson Worldwide |
| GEODIS |
| DHL Supply Chain |
| Kuehne + Nagel |
| DSV |
| UPS Supply Chain Solutions |
| Others |
Supply Flow & Price Mechanics
Dock-to-dock completion windows under 24 hours compress pricing power toward terminal operators with automated yard management systems, while fragmented shipper demand across Texas and California distribution clusters erodes rate premiums for pure transportation speed. Inventory carrying cost elimination anchors buyer willingness-to-pay, synchronizing supply chain investments with velocity-tier pricing structures.
Pricing Analysis
Technology-generation pricing gaps separate automated yard management deployments from legacy dispatch scheduling platforms, with mid-market 3PL providers capturing rate premiums through real-time location tracking capabilities. Three-tier pricing structure across premium velocity, standard consolidation, and economy deferred-handling levels stratifies across dwell-time guarantees and modal flexibility. Pricing pressure stems from EPA Phase 3 compliance costs redirecting shipper procurement toward hub-based optimization over long-haul point-to-point contracts. Small enterprises exhibit highest price sensitivity due to variable-cost procurement models, while e-commerce fulfillment networks prioritize synchronization capabilities over rate minimization.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port gateways fluctuate with container availability and chassis positioning, compressing margin buffers for cross-dock operators dependent on maritime import flows. Terminal infrastructure concentrates in the United States, Germany, and China, with equipment procurement drawing from battery-electric yard tractor manufacturers and automated material handling system providers. Supply chain risk centers on California Advanced Clean Trucks regulation compliance timelines, which accelerate equipment turnover obligations ahead of federal mandates. Distribution runs through rail-terminal networks on corridors exceeding 500 miles and road-based regional nodes under that threshold.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-market retailers and wholesale distributors abandoning captive distribution networks, fragmenting procurement across multiple third-party providers and eroding volume-based rate premiums previously available to large corporations.
For Market Incumbents: Secure automated yard management deployments in Dallas-Fort Worth and Los Angeles Basin clusters to defend against digital freight brokers competing on lane density without asset ownership. Reinforce rail-terminal network leverage through European template replication, as DB Schenker's multi-vertical consolidation model demonstrates defensible positioning against pure technology entrants. For New Entrants and Emerging Players: Lead with sub-4-hour dock-to-dock cycle guarantees for e-commerce fulfillment networks during peak windows, targeting mid-market apparel retailers in California migrating from dedicated warehousing. Penetrate food and beverage distributor segments pressured by FMCSA hours-of-service compression, offering consolidation services that maintain delivery velocity without extending driver schedules. For Investors and Strategic Acquirers: Long-term, this sits as a hub-infrastructure consolidation play because terminal electrification investments and zero-emission equipment mandates raise capital barriers for fragmented regional operators. Acquisition targets should demonstrate proprietary freight matching platform integration or captive rail-terminal access in Texas and California distribution clusters. The signal to watch is California Advanced Clean Trucks regulation propagation into federal terminal equipment standards.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Yard Management Deployment | Mid-market 3PL providers compensate for smaller door counts through real-time tractor-trailer coordination. |
| Rail-Terminal Network Expansion | BNSF and Union Pacific corridors exceeding 500 miles shift volume from road transport to intermodal consolidation. |
| Digital Brokerage Platform Integration | Proprietary freight matching competes on lane density rather than captive asset ownership. |
| Terminal Electrification Investment | EPA Phase 3 standards redirect capital toward hub-based optimization over long-haul fleet expansion. |
| Mid-Market Retail Penetration | Third-party logistics providers collapse lead times for retailers abandoning dedicated warehousing. |
Methodological Framework
A standing panel of terminal operations directors, freight brokerage executives, shipper procurement managers, and FMCSA compliance officers provided ongoing calibration across primary interview rounds. Secondary validation drew from FMCSA hours-of-service regulatory filings, EPA Phase 3 greenhouse gas standard disclosures, BNSF and Union Pacific intermodal volume reports, and California Air Resources Board Advanced Clean Trucks implementation data. Bottom-up service provider capacity assessments and top-down freight flow modeling were triangulated against corridor-specific volume estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled service type, industry vertical, delivery mode, and customer maturity segments alongside regulatory compliance tier differentiation. CAGRs were derived from terminal throughput trajectories, equipment electrification investment cycles, and modal shift elasticity on corridors exceeding 500 miles. Forecast inputs incorporated e-commerce fulfillment network expansion rates and hours-of-service regulation enforcement intensity.
The analysis sits within stated boundaries; outcomes outside current FMCSA regulatory enforcement levels, California zero-emission mandate timelines, or e-commerce penetration trajectories would require recalibration. Forecasts reflect documented assumptions regarding rail intermodal capacity expansion and automated yard management adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Europe Vehicle Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Global Taxi Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Spain Car Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Vehicle Management System Market
Transportation Services
Truck Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Truck Sharing Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market
Transportation Services
Latin America Tourism Vehicle Rental Market