
 Scooter Rental Market | 2026-2036
Scooter Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Scooter Rental Market Analysis
ISO 15118 vehicle-to-grid communication certification is rotating as a baseline qualification for fleet operators seeking utility partnerships. Bird Global Inc. leverages its proprietary operating system to sustain deployment density across North American and European cities. TIER Mobility AG anchors its position through in-house battery recycling and circular manufacturing partnerships. Voi Technology AB differentiates via multimodal integration with public transit APIs in Scandinavian municipalities.
Scooter rental denotes the short-term commercial provision of motorized two-wheelers, typically electric units with 250-500W brushless hub motors and 36-48V lithium-ion battery packs, enabling point-to-point urban mobility without ownership obligations. Free-floating service models capture the dominant share of trip volume due to minimal friction in user pickup and drop-off, though subscription structures are gaining traction among daily commuters seeking predictable cost structures. Electric scooters command the primary vehicle category, while manual scooter deployments remain confined to tourist-dense historic districts with speed-restricted zones.
FAA regulations govern low-altitude geofencing protocols for aerial fleet monitoring systems, while EU Green Deal emission benchmarks and GDPR data handling requirements shape operational compliance across European deployments. NHTSA guidelines influence crash-testing standards and rider safety equipment mandates in the United States. Stakeholders must monitor evolving battery transportation classifications and municipal permitting caps that directly constrain fleet scaling economics.
Market Dynamics
Battery-swapping infrastructure mandates are compressing fleet economics across European metropolitan corridors. Operators must absorb retrofit costs while maintaining deployment density.
Growth Catalysts
- EU Green Deal emission benchmarks:Municipal procurement policies in Germany and France now prioritize zero-emission last-mile fleets. Fleet operators secure preferential street-access permits by demonstrating compliance.
- Urban last-mile delivery expansion:E-commerce fulfillment networks in Barcelona and Milan are integrating electric scooter pools for parcel handoff. Courier platforms negotiate bulk rental agreements with infrastructure guarantees.
- Lithium iron phosphate chemistry:Swappable battery packs using LFP cells reduce thermal runaway risk and extend cycle life. Operators cut insurance premiums and replacement frequency.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings directly compress battery pack margins. Operators face working capital strain during procurement cycles.
- Municipal permitting caps:Paris and Madrid enforce strict fleet-size limits per operator license. Scaling economics hit hard ceilings regardless of demand signals.
- Station-based dockless substitution:Bike-sharing networks with fixed docking infrastructure capture price-sensitive commuters. Free-floating scooter operators lose ridership to subsidized alternatives.
Strategic Opportunities
- Scandinavian multimodal integration:Swedish and Norwegian transit authorities open API access for real-time route coordination. Operators embed scooter availability into journey-planning apps.
- GDPR-compliant data monetization:Anonymized mobility patterns attract urban planning consultancies. Revenue streams diversify beyond trip fees.
- Solid-state battery convergence:Higher energy density enables lighter vehicle platforms and extended range. Early adopters differentiate through reduced charging downtime.
Industry Challenges
- ISO 15118 certification timelines:Vehicle-to-grid communication standards require extensive testing protocols. Fleet operators delay utility partnerships pending qualification.
- Field technician scarcity:Battery-swapping station maintenance demands electromechanical expertise. Recruitment lags behind infrastructure rollout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scooter Rental Market |
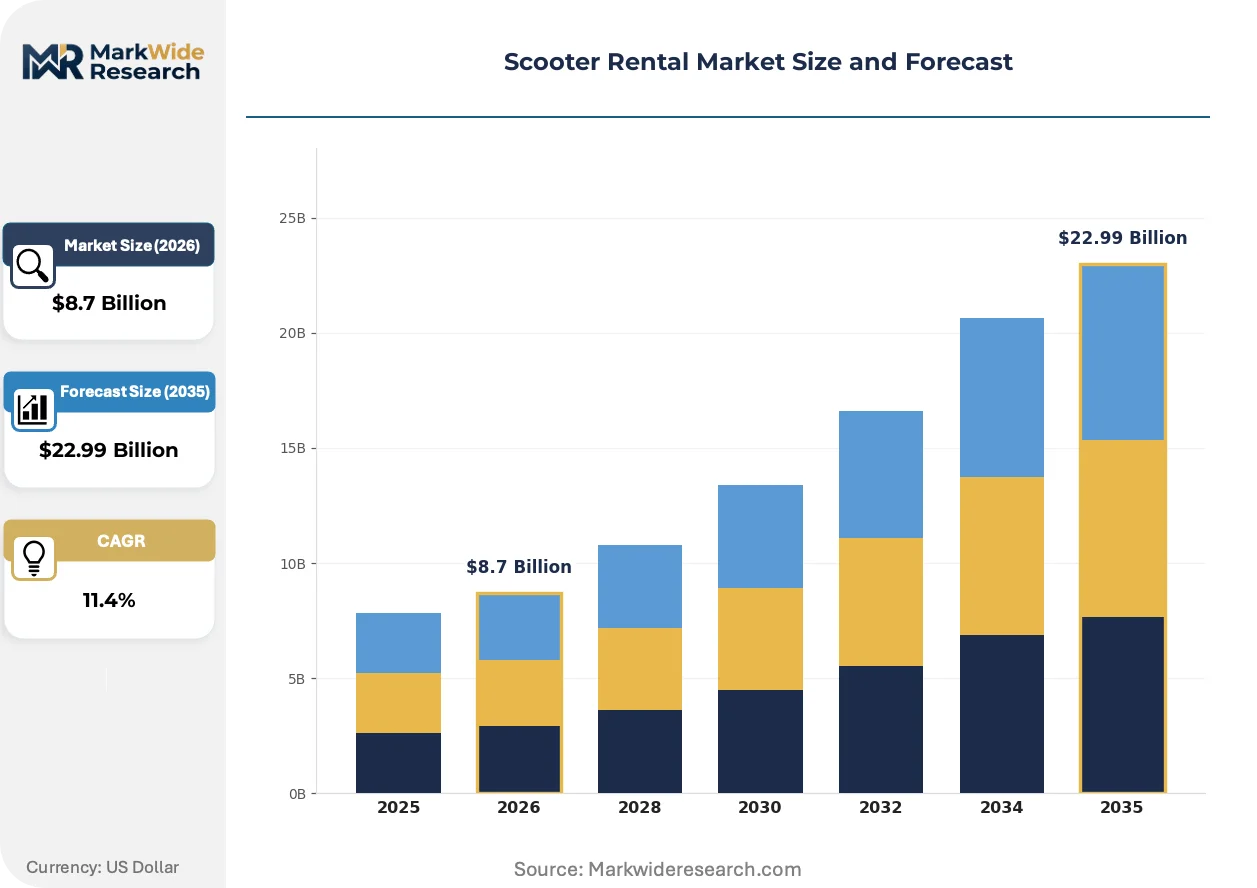
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Station-Based, Free-Floating, Subscription Deployment Model: On-Demand, Mobile App-Based, Stationary Kiosks, Integrated Solutions Customer Type: Tourists, Commuters, Students, Corporate Users Vehicle Type: Electric Scooters, Gas Scooters, Manual Scooters, Hybrid Scooters |
| Companies Covered | Neutron Holdings, Inc., Bird Global Inc., TIER Mobility AG, Voi Technology AB, Cityscoot, Uber Technologies, Inc., Lyft, Inc., Wind Mobility, Beam Mobility Holdings Pte. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scooter Rental Market Emerging Trajectories
Modular hardware architectures are enabling rapid fleet reconfiguration without full vehicle replacement. Operators respond to regulatory shifts through software-defined range and performance tuning.
Silicon carbide power electronics are decomposing traditional motor controller designs. Tier 1 suppliers in Stuttgart and Munich ship integrated inverter-motor units to scooter OEMs. The technology is decomposing discrete component supply chains and compressing assembly labor.
GDPR Article 32 security requirements now mandate encrypted telematics transmission for all fleet vehicles. Operators in Amsterdam and Copenhagen must audit data handling protocols quarterly. GDPR compliance costs are redirecting R&D budgets toward cybersecurity tooling.
Subscription pricing models are displacing per-minute billing among daily commuters in Berlin and Vienna. Corporate mobility budgets negotiate flat-rate employee access. Procurement teams favor predictable cost structures over variable trip expenses.
Scooter Rental Market Segmentation
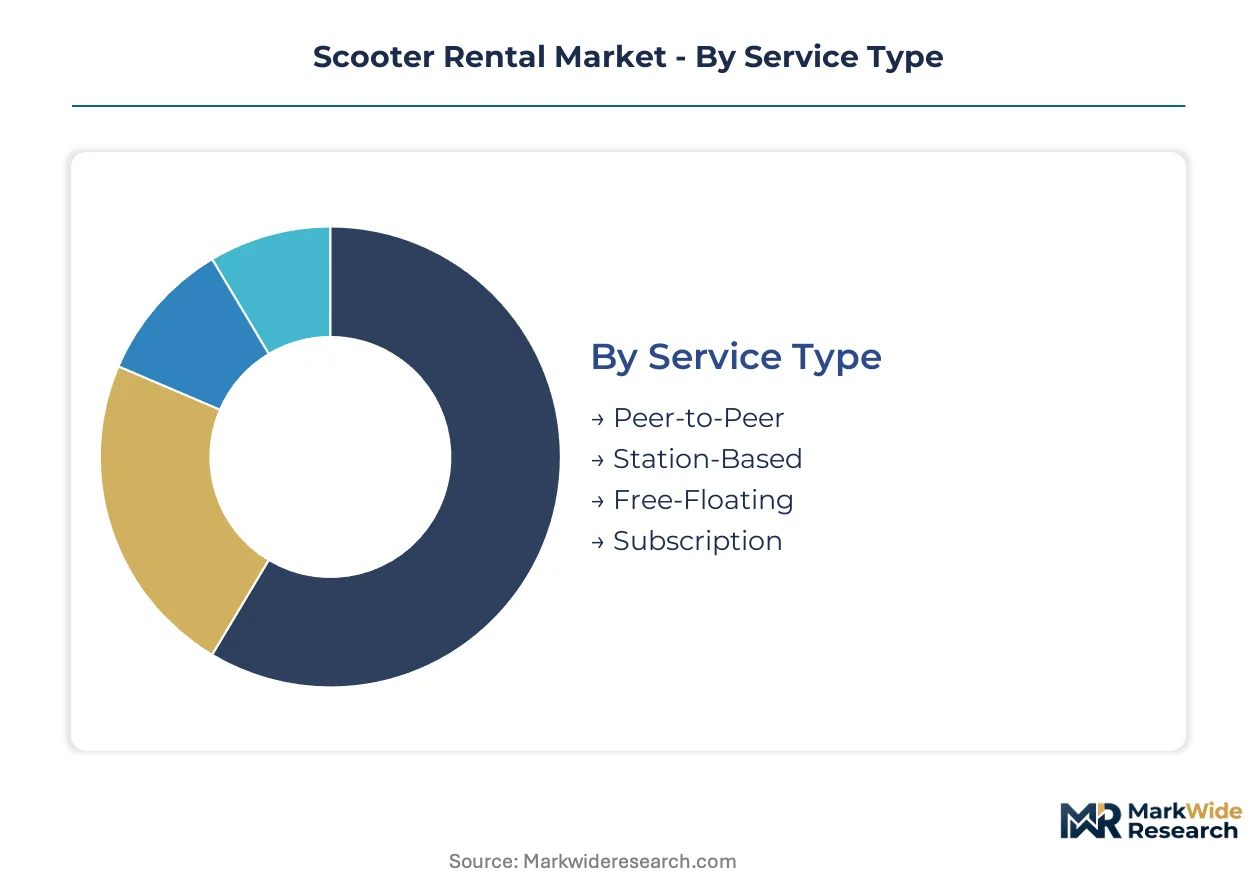
Scooter rental operators configure service architectures around distinct usage patterns and infrastructure constraints. Segmentation choices directly determine capital deployment intensity, regulatory exposure, and customer acquisition economics across metropolitan markets.
Service Type:
German and French operators dominate free-floating deployments, while station-based networks concentrate in Spanish municipal partnerships. Peer-to-peer models remain export-led through Nordic tourist corridors.
- Free-Floating:Unrestricted pickup and drop-off across geofenced urban zones. Demand clusters in Berlin and Paris where commuters prioritize spontaneity over predictability; GDPR-compliant telematics enable real-time fleet repositioning.
- Subscription:Flat-rate monthly access with unlimited trips under duration caps. Corporate mobility budgets in Vienna and Munich drive adoption as procurement teams seek fixed cost structures; operators lock in recurring revenue against seasonal ridership swings.
- Station-Based:Fixed docking infrastructure with guaranteed vehicle availability. Barcelona and Madrid deploy these through municipal concession agreements.
- Peer-to-Peer:Asset-light model matching private scooter owners with short-term renters. Copenhagen and Oslo pilot these for tourist-dense historic districts.
Free-floating commands the established base. The steepest expansion runs through subscription.
Deployment Model:
Mobile app-based systems capture volume leadership through frictionless onboarding. Stationary kiosk deployments concentrate where smartphone penetration lags among older demographics.
- Mobile App-Based:Smartphone-native reservation, unlock, and payment workflows. Commuters in Milan and Rome demand seamless integration with transit planning apps; operators invest in NFC tap-to-ride to reduce activation friction.
- On-Demand:Real-time vehicle dispatch through predictive algorithms. Last-mile delivery fleets in Amsterdam optimize courier handoff timing through demand-forecasting models.
- Stationary Kiosks:Physical rental terminals with card payment options. Tourist zones in Lisbon and Prague maintain these for cash-preferred visitors.
- Integrated Solutions:Multimodal platform bundling scooters with transit, bike-share, and car rental. Swedish transit authorities mandate API interoperability for public contract eligibility.
Mobile app-based systems anchor current deployment density. Integrated solutions are climbing the fastest as procurement specifications harden.
Customer Type:
Tourist demand peaks seasonally across Mediterranean coastal cities. Corporate user segments deliver year-round utilization with negotiated rate structures.
- Commuters:Daily work-trip users seeking reliable last-mile connectivity. Subscription pricing in German metropolitan corridors locks in ridership against weather-driven variability.
- Tourists:Short-stay visitors prioritizing sightseeing mobility. Barcelona and Venice impose fleet caps in historic centers to manage congestion.
- Students:Price-sensitive users with flexible timing. University partnerships in Copenhagen and Stockholm offer semester-long access at discounted rates.
- Corporate Users:Employer-sponsored mobility benefits with consolidated billing. Vienna and Munich see procurement teams negotiate enterprise agreements with sustainability reporting requirements.
Commuters provide the revenue foundation. Corporate users are gaining share fastest through ESG-linked procurement mandates.
Vehicle Type:
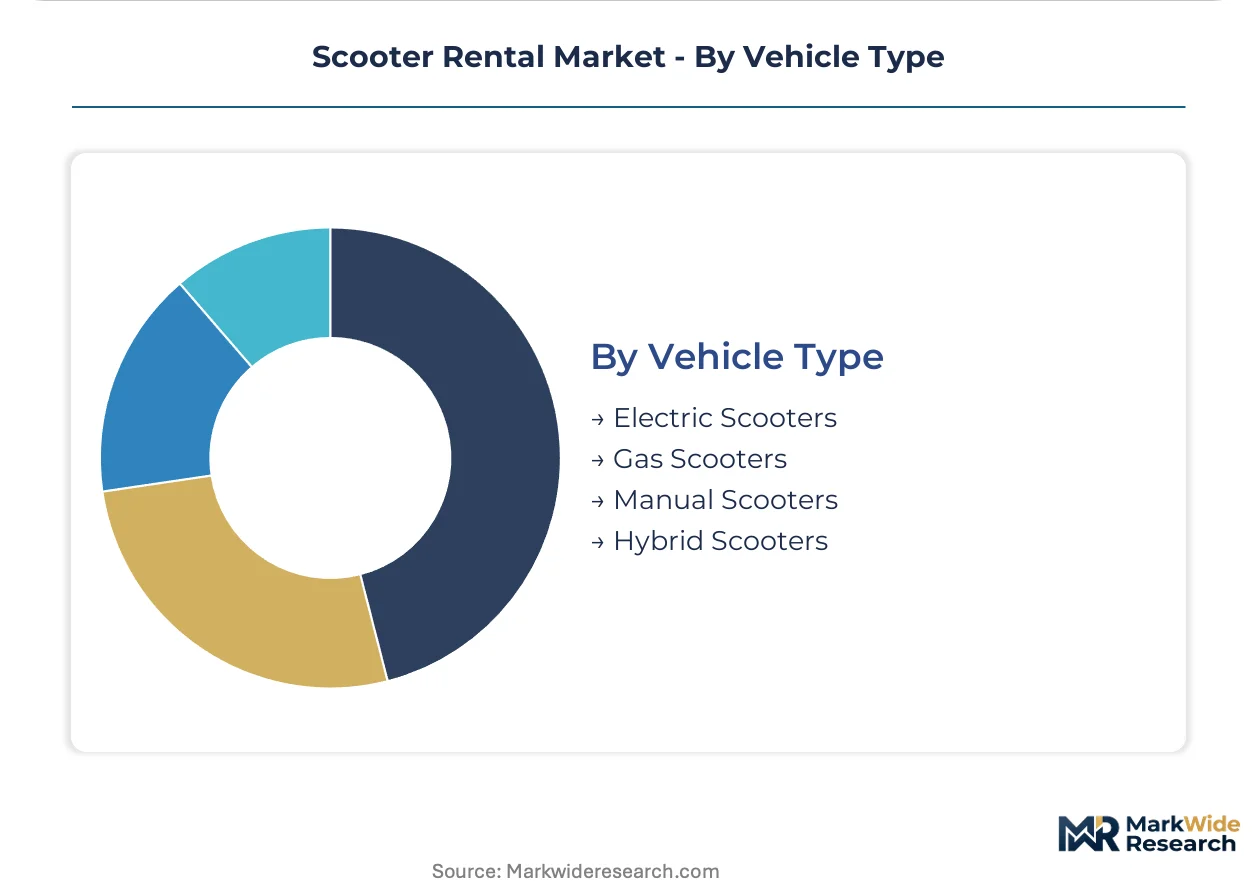
Electric scooters dominate fleet composition where EU Green Deal benchmarks influence municipal licensing. Manual scooters persist in speed-restricted heritage zones with pedestrian density.
- Electric Scooters:Lithium-ion powered units with 250-500W brushless hub motors. Battery-swapping infrastructure in Paris and Berlin enables continuous deployment; LFP chemistry reduces thermal risk and insurance premiums.
- Manual Scooters:Human-powered units for low-speed tourist corridors. Florence and Siena restrict motorized vehicles in UNESCO core zones, preserving niche demand.
- Hybrid Scooters:Dual-mode units switching between electric assist and manual operation. Pilot programs in Oslo test these for hilly terrain coverage.
- Gas Scooters:Combustion-engine units with declining deployment. Limited to rural Spanish markets where charging infrastructure remains sparse.
Electric scooters command the established base. Hybrid configurations show the steepest experimental traction in topographically challenging Nordic municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement teams in German metropolitan corridors anchor the largest buyer concentration. Subscription pricing models lock in recurring revenue against seasonal variability. Municipal concession frameworks in France and Spain shape operator entry economics.
Germany
Corporate mobility budgets in Munich and Berlin drive subscription adoption with ESG-linked reporting requirements. KBA vehicle-type approval mandates ISO 15118 certification for utility partnership eligibility. The Rhine-Ruhr corridor concentrates battery-swapping infrastructure deployment as operators absorb retrofit costs.
France
Tourist demand peaks seasonally across Mediterranean coastal cities while Paris enforces strict fleet-size licensing caps. EU Green Deal emission benchmarks prioritize zero-emission last-mile fleets in municipal procurement. The Île-de-France region anchors free-floating deployment density with GDPR-compliant telematics repositioning.
Spain
E-commerce fulfillment networks in Barcelona integrate electric scooter pools for parcel handoff with infrastructure guarantees. Municipal permitting caps in Madrid constrain scaling economics regardless of demand signals. Andalusian historic districts preserve niche manual scooter demand in UNESCO speed-restricted zones.
Sweden
Transit authorities open API access for real-time route coordination embedding scooter availability into journey-planning apps. GDPR Article 32 mandates encrypted telematics transmission with quarterly audit protocols. Stockholm and Copenhagen pilot peer-to-peer models for tourist-dense historic districts.
Italy
University partnerships in Milan and Rome offer semester-long access at discounted rates for price-sensitive student segments. ANSM data handling requirements shape operational compliance alongside EU Green Deal benchmarks. Florence and Siena restrict motorized vehicles in UNESCO core zones, preserving manual scooter niches.
Scooter Rental Market Vendor Landscape
Player mix skews toward venture-backed mobility platforms with proprietary operating systems. The vendor base concentrates among integrated fleet operators and asset-light technology licensors. Three archetypes dominate: full-stack operators controlling hardware and software, partnership-dependent platforms leveraging third-party vehicle supply, and multimodal integrators embedding scooters into transit APIs. Competitive moves center on municipal concession bidding and battery-swapping infrastructure pre-positioning.
Among venture-backed mobility platforms, Bird Global Inc., TIER Mobility AG, and Voi Technology AB occupy distinct positioning vectors. Bird Global Inc. represents the full-stack operator archetype with proprietary operating system deployment. TIER Mobility AG exemplifies circular manufacturing integration through in-house battery recycling partnerships. Voi Technology AB anchors the multimodal integration tier with public transit API coordination in Scandinavian municipalities.
| Leading Market Players |
|---|
| Neutron Holdings, Inc. |
| Bird Global Inc. |
| TIER Mobility AG |
| Voi Technology AB |
| Cityscoot |
| Uber Technologies, Inc. |
| Lyft, Inc. |
| Wind Mobility |
| Beam Mobility Holdings Pte. Ltd. |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with battery cell manufacturers lock in lithium iron phosphate supply for German and French fleet operators while anchoring unit economics against raw material indexation clauses. These arrangements bind capital for 36-48 month horizons but insulate procurement teams from lithium carbonate spot volatility that otherwise erodes fleet margins.
Pricing Analysis
Cost-plus contracts indexed to Shanghai Metals Market lithium carbonate benchmarks dominate battery pack procurement across Paris and Berlin deployments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15118-certified vehicles from baseline utility-partnership units and entry-level municipal permit tiers. Pricing pressure stems from municipal fleet caps that constrain revenue density per vehicle regardless of demand. Corporate mobility budgets in Vienna and Munich exhibit lowest price sensitivity due to ESG reporting mandates, while student segments in Copenhagen and Stockholm demand semester-rate discounts.
Supply Chain Analysis
Shenzhen and Ningbo manufacturing corridors constitute the critical chokepoint for brushless hub motor and controller assembly, with Rotterdam port congestion rippling through European delivery schedules. Battery cell supply draws from China, South Korea, and Japan for LFP chemistry, while aluminum chassis extrusions source from German and Italian Tier 2 suppliers. Single-source vulnerability concentrates in silicon carbide inverter modules from Stuttgart and Munich Tier 1s. Distribution runs through regional assembly hubs in Poland and the Netherlands before last-mile fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scooter rental market is cycling through post-permit-cap adjustment as municipal procurement policies in Germany and France reallocate street access toward zero-emission compliance tiers.
For Market Incumbents: Shield deployment density in Rhine-Ruhr and Île-de-France corridors by securing battery-swapping station real estate ahead of infrastructure mandate deadlines. Absorb field technician scarcity through electromechanical apprenticeship partnerships with technical universities in Stuttgart and Munich. Vertical integration into in-house battery recycling, following TIER Mobility AG's circular manufacturing model, defends margin position against raw material volatility. For New Entrants and Emerging Players: Differentiate on GDPR-compliant data monetization services for urban planning consultancies in Amsterdam and Copenhagen, where quarterly audit protocols already operationalize mobility pattern analytics. Target peer-to-peer tourist corridor pilots in Oslo and Stockholm historic districts, where asset-light models bypass municipal fleet caps entirely. Negotiate API interoperability mandates with Swedish transit authorities as the go-to-market anchor for multimodal integration. For Investors and Strategic Acquirers: Full-stack operators with proprietary operating systems and captive battery supply agreements represent the priority acquisition archetype, given their insulation from component margin compression. Long-term viability hinges on utility partnership eligibility through ISO 15118 certification timelines. Watch municipal permitting cap adjustments in Paris and Madrid as the inflection signal for fleet scaling economics release.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Pre-Positioning | Secures compliance with EU Green Deal infrastructure mandates in German metropolitan corridors. |
| ISO 15118 Certification Investment | Unlocks vehicle-to-grid utility partnerships and preferential street-access permits under KBA guidelines. |
| Multimodal Transit API Integration | Meets Swedish procurement specifications for public contract eligibility in Scandinavian municipalities. |
| In-House Battery Recycling Partnership | Reduces insurance premiums and thermal risk exposure through LFP chemistry lifecycle control. |
| Corporate Mobility Subscription Expansion | Captures ESG-linked procurement budgets in Vienna and Munich with fixed cost structures. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet operations directors, municipal permitting officers, battery procurement managers, and transit authority API integration leads, then refined through secondary validation. Fleet operator financial disclosures, EU Green Deal implementation reports, KBA vehicle-type approval databases, and GDPR Article 32 audit protocols anchored quantitative triangulation. Bottom-up deployment density modeling across metropolitan corridors converged with top-down market sizing through cross-referencing.
Variance decomposition across service type, vehicle configuration, and customer segment dimensions shaped the analytical framework over the projection horizon. CAGRs derived from battery-swapping infrastructure rollout schedules, municipal concession renewal timelines, and corporate mobility budget expansion trajectories. Subscription pricing adoption curves and last-mile delivery fleet integration rates supplied industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate supply stability and municipal permitting cap stability would require recalibration. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and battery chemistry transition timelines. Practitioners should keep alternative scenarios live as GDPR audit protocol stringency and ISO 15118 certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Global Taxi Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Spain Car Rental Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Brazil Car Rentals Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Driving Vacation Market
Transportation Services
India Car Rental Market
Transportation Services
Bird Carriers Market
Transportation Services
Poland Car Rental Market
Transportation Services
Scandinavia Car Rental Market