
 United States Car Rental Market | 2026-2036
United States Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
United States Car Rental Market Insights
Fleet electrification is rewriting margin allocation across acquisition, maintenance, and remarketing cycles. Enterprise Holdings leverages vertical integration through its own collision repair and fleet management arms. Hertz Global Holdings anchors scale via exclusive electric vehicle procurement partnerships with OEMs. Avis Budget Group differentiates through technology leadership in dynamic pricing algorithms across its digital channels.
United States car rental denotes a temporary vehicle access service where operators acquire, insure, maintain, and dispose of automotive assets through daily, weekly, or monthly fee structures, with fleet turnover typically occurring within twelve to twenty-four months to optimize residual value recovery. The primary commercial purpose centers on providing mobility substitutes for travelers, corporate commuters, and vehicle owners during repair periods. Short-term rentals dominate transaction volume at airport and urban satellite locations, while long-term rentals capture stickier corporate accounts with predictable utilization patterns. Electric vehicles represent the fastest-growing vehicle type segment as charging infrastructure density improves along interstate corridors, though SUVs sustain the largest share of revenue per rental day due to premium rate structures.
NHTSA safety recall protocols and EPA emissions certification requirements shape fleet composition decisions, compelling operators to accelerate retirement schedules for non-compliant powertrains. The Federal Trade Commission's advertising and pricing transparency rules constrain ancillary revenue bundling practices at point of sale. State-level insurance minimums vary considerably, creating operational complexity for interstate rental networks. Stakeholders must monitor residual value volatility in electrified assets and charging infrastructure capex commitments as the primary determinants of portfolio profitability.
Market Dynamics
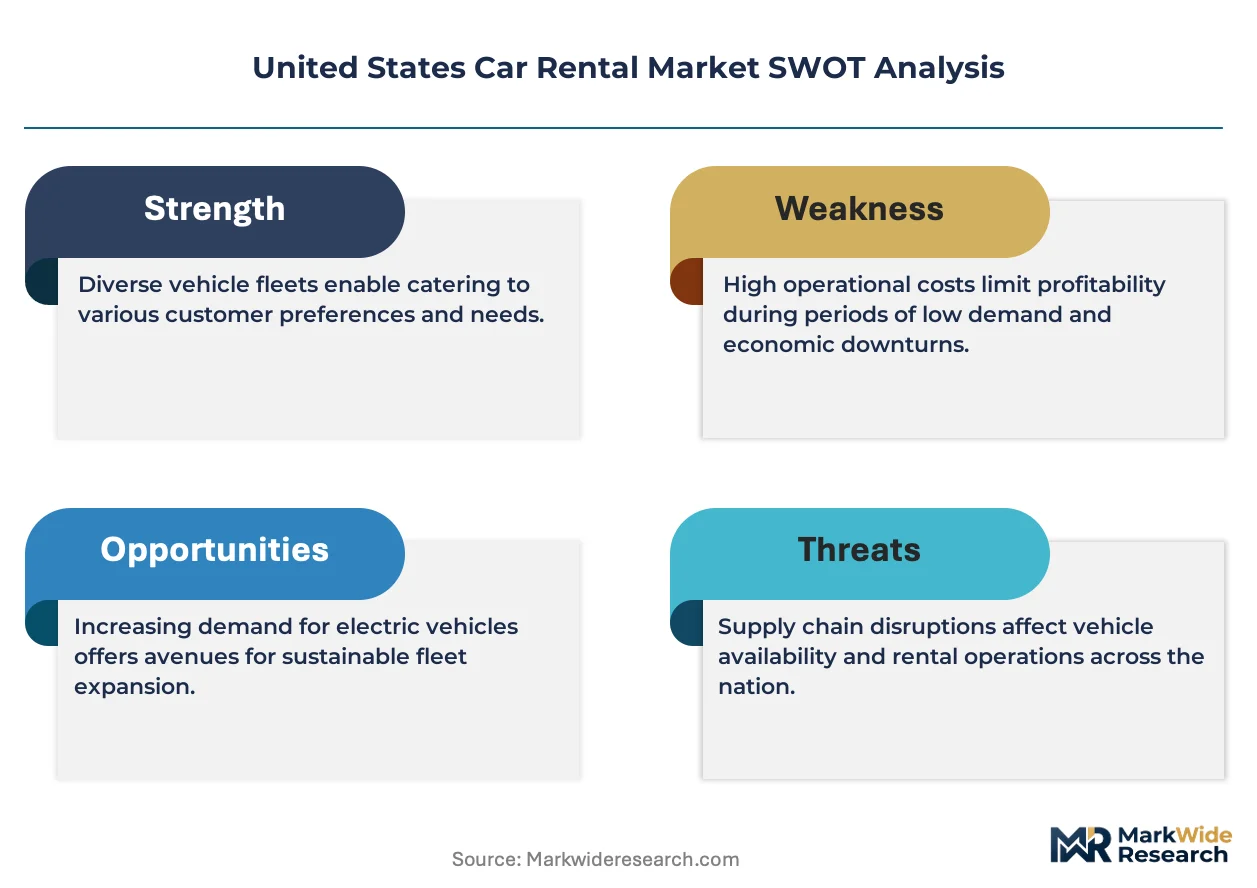
Fleet electrification is compressing asset turnover cycles while NHTSA safety mandates accelerate powertrain retirement schedules. Operators now face simultaneous pressure from EPA emissions thresholds and residual value volatility in battery-electric portfolios.
Growth Catalysts
- Extended-Stay Business Travel:Corporate accounts are lengthening rental durations across interstate corridors, improving fleet utilization rates and reducing per-vehicle repositioning costs.
- EPA Corporate Average Fuel Economy Standards:Regulatory pressure is compelling fleet operators to electrify portfolios, creating procurement volume for OEMs and charging infrastructure providers.
- Airport Hub Density:Texas, Florida, and California concentrate throughput at airport-adjacent locations, generating economies of scale in vehicle maintenance and customer acquisition.
Market Restraints
- Battery Residual Value Uncertainty:Electrified assets carry depreciation risk that outpaces internal combustion engines, constraining fleet financing structures.
- Charging Infrastructure Capex:Interstate corridor electrification requires capital commitments that strain operator balance sheets before utilization materializes.
- State Insurance Minimum Variation:Inconsistent coverage requirements across jurisdictions create operational complexity for interstate rental networks.
Strategic Opportunities
- Dynamic Pricing Algorithm Deployment:Real-time demand-responsive rate structures capture revenue premiums during peak travel windows at constrained airport locations.
- Collision Repair Vertical Integration:In-house damage assessment and repair facilities compress turnaround time and reduce third-party dependency.
- Long-Term Corporate Accounts:Predictable utilization patterns from extended-duration contracts stabilize revenue and improve fleet planning precision.
Industry Challenges
- Technician Training Gap:High-voltage battery diagnostics and repair certification lags fleet electrification timelines, extending vehicle downtime.
- Legacy Reservation System Integration:Real-time inventory synchronization across franchise and corporate locations requires middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Car Rental Market |
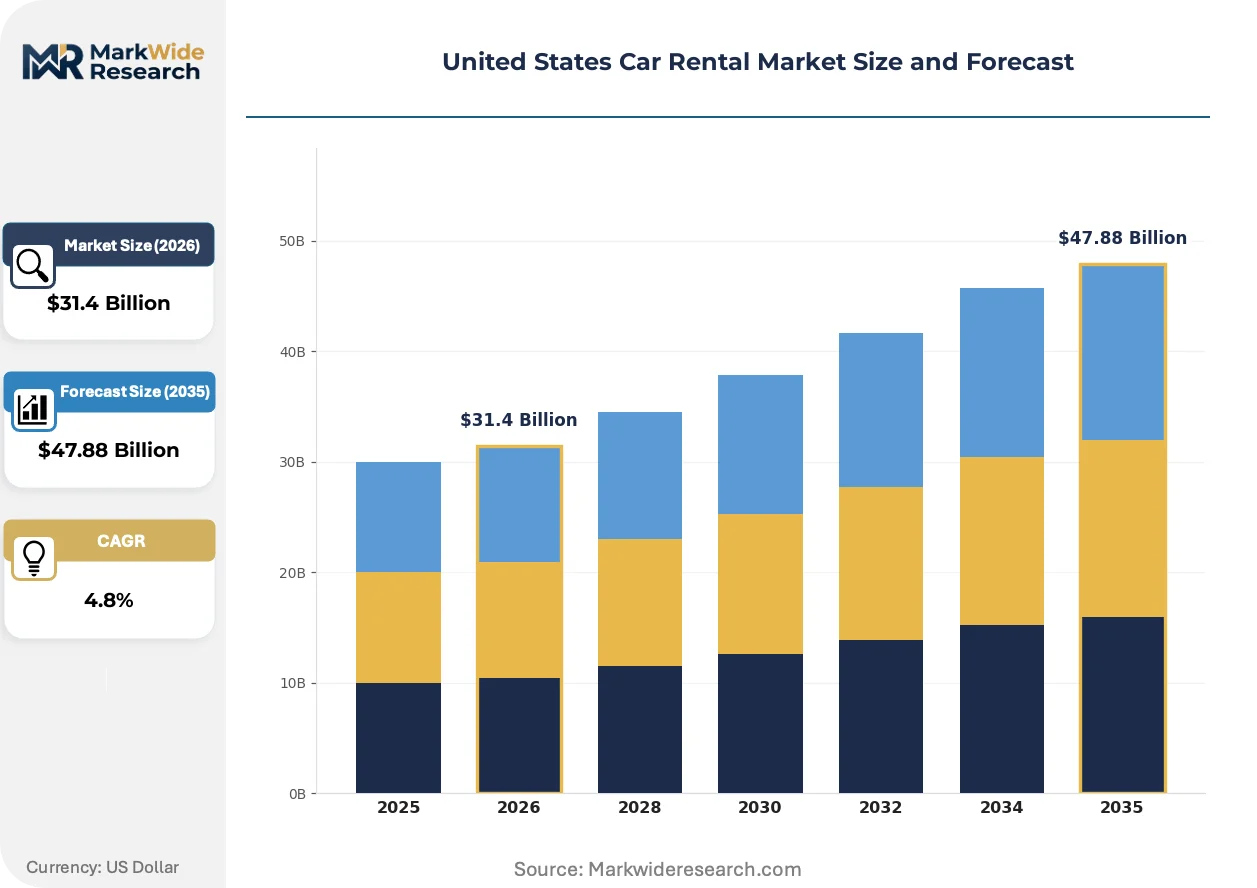
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $47.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rentals, Long-Term Rentals, Luxury Rentals, Peer-to-Peer Rentals Vehicle Type: SUVs, Sedans, Vans, Electric Vehicles Customer Type: Leisure Travelers, Business Travelers, Corporate Clients, Government Agencies Booking Channel: Online Platforms, Offline Agencies, Mobile Apps, Travel Aggregators |
| Companies Covered | National Car Rental, Sixt SE, Enterprise Holdings, Dollar Rent A Car, Budget Rent a Car, Hertz Global Holdings, Alamo Rent A Car, Thrifty Car Rental, Avis Budget Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Car Rental Market Trends and Innovations
Connected vehicle telemetry and automated pricing engines are restructuring how operators manage yield across distributed fleet networks. Three developments dominate competitive differentiation.
Telematics-enabled predictive maintenance is collapsing unscheduled downtime intervals for rental fleets. Operators deploy over-the-air diagnostics to flag component degradation before failure. Airport-based hubs now route vehicles to service bays during low-demand windows, compressing maintenance-related revenue loss.
NHTSA safety recall protocols are accelerating powertrain retirement schedules for non-compliant vehicles. Fleet managers must track VIN-level recall status across thousands of units. California and Texas operators face the tightest compliance windows due to state-level emissions enforcement layering atop federal requirements.
Subscription-style mobility access is displacing traditional daily-rate structures among urban corporate accounts. Fleet operators now bundle insurance, maintenance, and vehicle swaps into flat monthly fees. This model concentrates in California tech corridors where employers seek predictable commuter subsidies.
United States Car Rental Market Segmentation
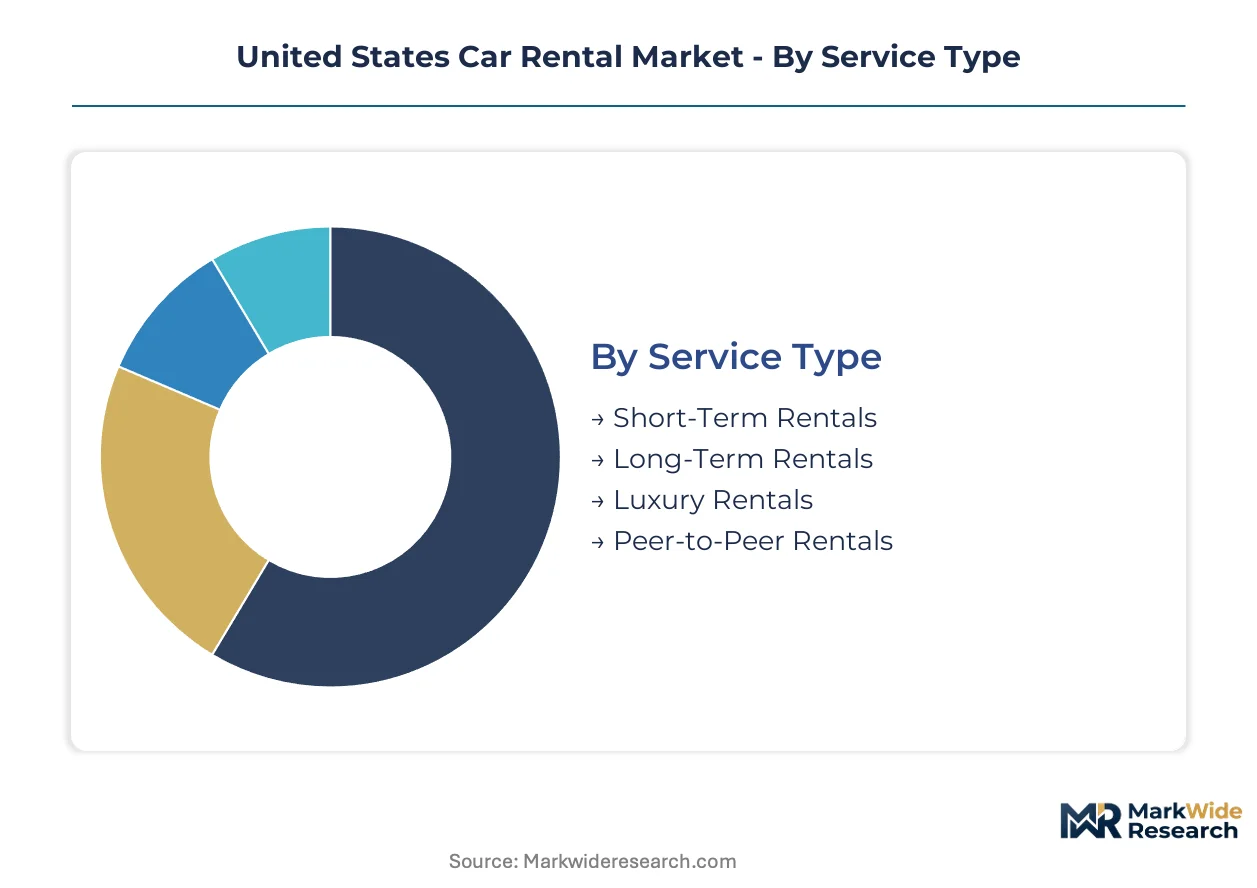
Segmentation in the United States car rental market reveals how distinct customer behaviors, asset configurations, and transaction modalities create divergent margin profiles. Each category demands specialized fleet composition, pricing architecture, and operational footprint strategies.
Service Type:
Mature daily-rate structures dominate transaction volume while emerging subscription models reshape contract economics across corporate accounts.
- Short-Term Rentals:Daily and weekly contracts at airport and urban satellite locations generate the highest transaction frequency. Demand concentrates in Texas, Florida, and California hubs where business travelers and leisure tourists overlap during peak seasons.
- Long-Term Rentals:Monthly and quarterly contracts reduce per-vehicle customer acquisition costs while stabilizing utilization rates. Corporate accounts in extended-stay corridors favor these arrangements for predictable commuter subsidies and reduced fleet repositioning overhead.
- Luxury Rentals:Premium vehicle tiers command rate multiples over standard fleets through specialized insurance bundling and concierge delivery services.
- Peer-to-Peer Rentals:Asset-light platforms aggregate privately-owned vehicle inventory, capturing price-sensitive demand outside traditional operator networks.
Short-term rentals retain volume leadership; peer-to-peer rentals hold the steepest expansion curve.
Vehicle Type:
Cost tier differentiation separates high-depreciation electric portfolios from established internal combustion assets with predictable residual value recovery.
- SUVs:Mid-size and full-size utility vehicles sustain the largest revenue per rental day through premium rate structures and family travel demand. Airport-adjacent hubs in California and Florida deploy SUVs at higher fleet percentages to capture leisure segment willingness-to-pay.
- Electric Vehicles:Battery-electric powertrains are expanding most quickly as EPA Corporate Average Fuel Economy standards pressure fleet composition. Charging infrastructure density along interstate corridors determines viable deployment geography.
- Sedans:Compact and mid-size cars serve price-sensitive segments with lower per-day rates but higher turnover velocity.
- Vans:Passenger and cargo configurations address group travel and commercial logistics demand with specialized insurance requirements.
SUVs retain volume leadership; electric vehicles hold the steepest expansion curve.
Customer Type:
Application-based segmentation separates predictable corporate utilization from stochastic leisure demand patterns.
- Business Travelers:Corporate road warriors generate weekday peak demand with lower price elasticity and consistent insurance coverage. Extended-stay corridors in Texas and California concentrate this segment through technology and energy sector travel budgets.
- Corporate Clients:Fleet outsourcing contracts deliver multi-year revenue visibility with negotiated rate schedules and dedicated account management. Government agencies add procurement complexity through Federal Acquisition Regulation compliance requirements.
- Leisure Travelers:Vacation and family trip demand exhibits high seasonality with price-sensitive booking behavior and ancillary revenue attachment opportunities.
- Government Agencies:Federal, state, and municipal contracts require specialized procurement protocols and security clearance procedures for certain vehicle classes.
Business travelers retain volume leadership; corporate clients hold the steepest expansion curve.
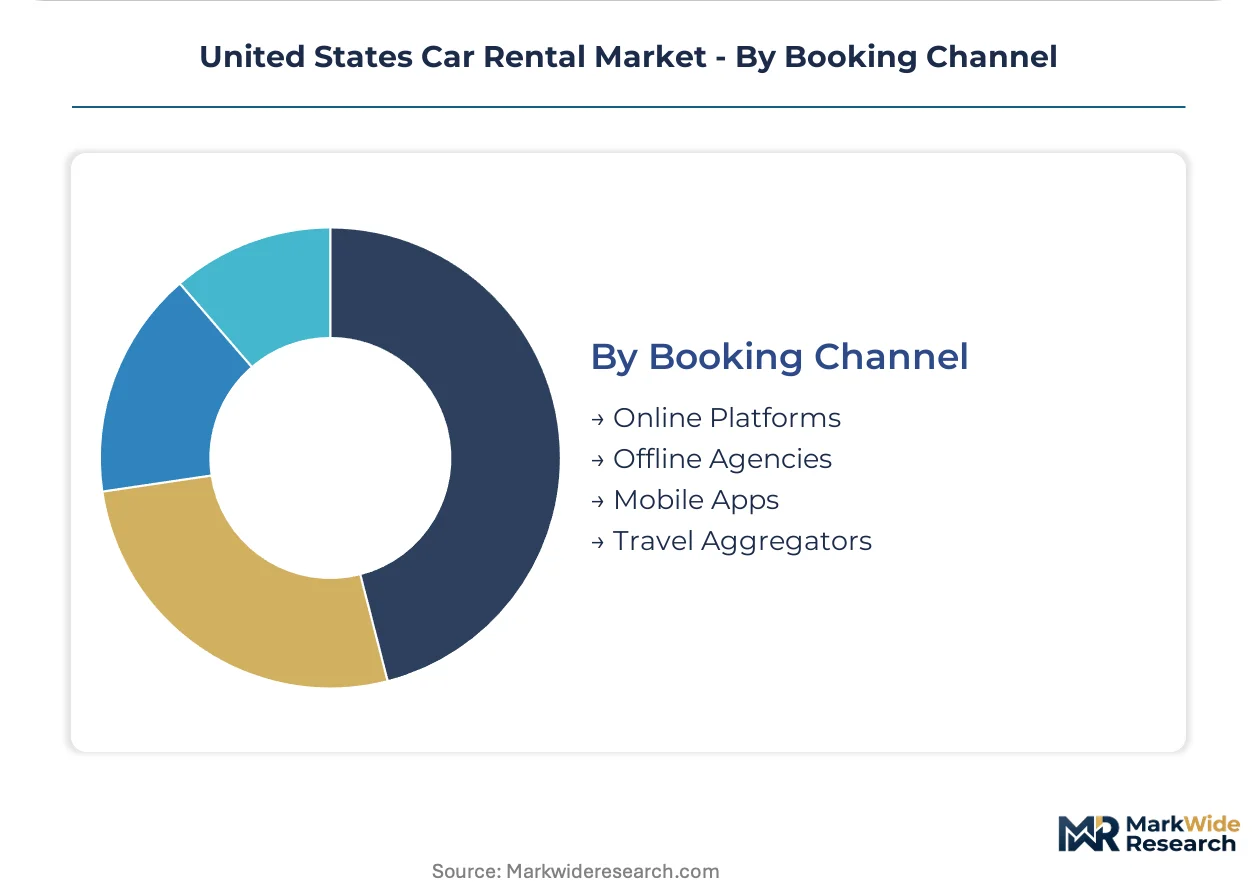
Booking Channel:
Volume concentration shifts toward digital intermediaries while direct operator relationships defend margin through loyalty program lock-in.
- Online Platforms:Direct-to-consumer websites and branded applications capture reservation volume with dynamic pricing algorithm deployment. Real-time inventory synchronization across distributed fleet networks determines conversion rates.
- Mobile Apps:Smartphone-native booking interfaces reduce friction for impulse reservations and last-minute fleet utilization optimization.
- Travel Aggregators:Third-party comparison engines drive price-transparent discovery with commission structures that compress operator net revenue per transaction.
- Offline Agencies:Brick-and-mortar travel advisors serve demographic segments with complex multi-leg itinerary requirements and insurance consultation needs.
Online platforms retain volume leadership; mobile apps hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leisure travelers in Florida and California exhibit the lowest price elasticity, absorbing premium rates during peak seasons, while corporate road warriors in Texas and Midwest manufacturing corridors negotiate volume discounts that compress per-day yields.
California
Tech sector commuter subsidies and extended-stay corporate housing drive monthly subscription growth in the San Francisco Bay Area and Los Angeles Basin. The California Air Resources Board enforces fleet electrification mandates that accelerate battery-electric vehicle procurement timelines. San Jose and San Diego operators deploy charging infrastructure at airport-adjacent hubs to capture business traveler demand.
Texas
Energy sector travel budgets and interstate corridor logistics sustain weekday fleet utilization across Dallas-Fort Worth and Houston. State insurance minimums fall below national averages, reducing operational complexity for cross-border rental networks. Austin and San Antonio concentrate subscription-model experimentation among technology employers seeking predictable commuter benefits.
Florida
Seasonal leisure surges from international tourism generate rate premiums at Miami and Orlando airport locations during winter months. The Florida Department of Highway Safety and Motor Vehicles maintains streamlined vehicle registration protocols that accelerate fleet turnover cycles. Tampa and Fort Lauderdale operators prioritize SUV deployment to capture family vacation willingness-to-pay.
New York Metro
Financial services road warriors and media sector production crews sustain weekday demand with lower ancillary attachment rates than leisure counterparts. Metropolitan Transportation Authority congestion pricing proposals threaten urban satellite location accessibility. Newark and LaGuardia airport hubs concentrate fleet investment due to higher per-vehicle revenue yields than Manhattan street locations.
Illinois/Michigan/Ohio Corridor
Automotive supplier travel and manufacturing plant rotations generate predictable midweek utilization across Chicago, Detroit, and Cleveland. Midwest state insurance minimums cluster near national medians, simplifying interstate fleet positioning. Detroit Metro and O'Hare airport locations serve as fleet rebalancing nodes for national operator networks.
United States Car Rental Market Competitive Landscape
Vertically integrated holding companies and technology-forward rate optimizers split the market between asset-heavy operational control and algorithmic yield management. Three archetypes dominate: legacy fleet aggregators with captive maintenance infrastructure, digital-native pricing specialists, and European premium-positioned entrants. Consolidation pressure intensifies through exclusive OEM procurement partnerships and collision repair backward integration.
Within the integrated holding company tier, Enterprise Holdings and Hertz Global Holdings exemplify divergent electrification strategies, while Avis Budget Group occupies a position emphasizing dynamic pricing deployment across digital channels. Sixt SE anchors the European-import archetype with premium fleet positioning in coastal metropolitan markets.
| Leading Market Players |
|---|
| National Car Rental |
| Sixt SE |
| Enterprise Holdings |
| Dollar Rent A Car |
| Budget Rent a Car |
| Hertz Global Holdings |
| Alamo Rent A Car |
| Thrifty Car Rental |
| Avis Budget Group |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in high-voltage battery diagnostics is compressing maintenance turnaround times and forcing operators to absorb premium labor rates for certified technicians. Fleet utilization rates above 75% at Texas and Florida airport hubs grant pricing power during peak travel windows, while California electrification mandates accelerate procurement cost pass-through.
Pricing Analysis
Ancillary revenue from insurance bundling and collision damage waivers drives lifetime customer value beyond base rental rates. Three-tier pricing structure across premium SUVs, standard sedans, and economy compacts segments demand by willingness-to-pay and trip purpose. Pricing pressure stems from travel aggregator commission structures that compress net revenue per transaction. Leisure travelers in Florida exhibit lowest price sensitivity during winter peak, while corporate accounts in Texas negotiate volume discounts that erode per-day yields.
Supply Chain Analysis
OEM production capacity in the United States, Mexico, and South Korea feeds fleet acquisition pipelines for domestic operators. Battery-electric powertrains, semiconductor components, and specialized fleet insurance products constitute critical input dependencies. Single-source vulnerability in lithium-ion cell supply creates exposure to commodity price volatility and tariff discontinuities. Distribution runs through airport-adjacent hub networks with satellite urban locations for incremental capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified high-voltage technicians is constraining fleet electrification timelines and inflating maintenance costs for early movers. The gap between electrification mandates and workforce readiness defines competitive positioning across the next replacement cycle.
For Market Incumbents: Pre-empt technician shortages by captive training partnerships with community colleges and OEM certification programs in Texas and California. Secure exclusive battery-electric procurement allocations from domestic OEMs before capacity constraints tighten. Vertical control over collision repair networks defends margin against third-party dependency as claim volumes rise with fleet age. For New Entrants and Emerging Players: Underserved secondary airports in the Midwest and Mountain West present white-space entry points with lower competitive density and negotiated ground transportation access. Subscription-model corporate accounts in Austin and Denver tech corridors offer stickier revenue with predictable utilization patterns. Target fleet outsourcing contracts for mid-sized energy and logistics employers seeking to eliminate owned-vehicle overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with embedded collision repair infrastructure and long-term corporate account penetration. Five-to-ten year viability hinges on charging infrastructure deployment density along interstate corridors. Monitor NHTSA recall velocity and EPA compliance deadlines as inflection indicators for accelerated fleet turnover demand.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Airport hub electrification in California and Texas captures EPA-compliant fleet positioning before mandate deadlines. |
| Collision Repair Backward Integration | In-house damage assessment facilities compress vehicle turnaround and reduce third-party claim processing dependency. |
| Dynamic Pricing Algorithm Deployment | Real-time demand-responsive rate structures maximize revenue per available vehicle day at constrained airport locations. |
| Long-Term Corporate Account Expansion | Extended-duration contracts in extended-stay corridors stabilize utilization and reduce per-vehicle customer acquisition costs. |
| Technician Certification Investment | High-voltage battery diagnostic capabilities address workforce scarcity and accelerate electrified fleet maintenance throughput. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, revenue management executives, airport concession managers, and collision repair facility operators; and secondary validation through SEC operator filings, DOT transportation statistics, EPA emissions certification databases, and state-level insurance regulatory filings. Bottom-up fleet size and utilization estimates triangulated against top-down market value reconstructions.
Forecast inputs incorporated vehicle replacement cycle modeling, regulatory compliance deadline sequencing, and charging infrastructure deployment trajectories across the projection horizon. Segmentation dimensions spanned service type, vehicle propulsion architecture, customer application, and booking channel. CAGRs derived from logistic adoption curves for electrified powertrains and elasticity-adjusted demand projections for business travel recovery patterns.
The forecast holds incumbent behavior within observed patterns; aggressive fleet electrification acceleration by Enterprise Holdings or Hertz Global Holdings would shift competitive dynamics and residual value recovery assumptions. Cross-checking against DOT airline passenger volume trends and corporate travel budget surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Middle East Car Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Global Taxi Market
Transportation Services
India Car Rental Market
Transportation Services
Truck Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Car Rental Service Market
Transportation Services
Poland Car Rental Market