
 India Aviation, Defense, and Space Market | 2026-2036
India Aviation, Defense, and Space Market Size, Share, and Industry Trends Forecast 2026-2036
India Aviation, Defense, and Space Market Insights
AS9100D certification is redrawing supplier eligibility across India's aerospace supply chain, forcing tier-2 and tier-3 vendors to upgrade quality management systems. Hindustan Aeronautics Limited anchors military aircraft production with deep integration into fighter jet final assembly. Bharat Electronics Limited specializes in radar and electronic warfare systems for domestic and export programs. Data Patterns (India) competes in satellite subsystems and avionics with a focus on indigenization.
The India Aviation, Defense, and Space sector encompasses design, manufacturing, and sustainment of atmospheric and exo-atmospheric platforms including composite airframes, propulsion systems, and guidance electronics operating across Mach regimes and orbital altitudes. Military Aircraft production absorbs the largest share of capital allocation given India's phased fighter squadron replenishment, while Satellites and Drones represent the fastest-expanding product categories driven by constellation programs and tactical unmanned requirements. Aerospace Materials and Avionics Systems command premium margins due to import substitution mandates under the Defence Acquisition Procedure.
The Ministry of Defence's Defence Acquisition Procedure and the Directorate General of Aeronautical Quality Assurance's certification protocols shape vendor qualification timelines and local content thresholds. BIS standards for aerospace materials and DGFT export control classifications further constrain supply base participation. Stakeholders must monitor indigenization list expansions and offset policy recalibrations to anticipate procurement priority shifts.
Market Dynamics
India's Defence Acquisition Procedure reforms are forcing tier-2 and tier-3 suppliers to absorb AS9100D certification costs or exit vendor lists, compressing the aerospace supply base while accelerating domestic manufacturing mandates.
Growth Catalysts
- Defence Acquisition Procedure indigenization mandates:Local content thresholds for fighter aircraft procurement are redirecting capital toward Karnataka and Telangana production clusters.
- Tactical unmanned systems:Border surveillance requirements and swarm warfare doctrine are expanding procurement of indigenous drone platforms across multiple altitude regimes.
- PLI scheme for specialty steel and composites:Production-linked incentives are reducing import dependency for aerospace-grade materials used in airframe manufacturing.
Market Restraints
- AS9100D certification barriers:Tier-2 machine shops face 18-24 month quality system upgrade cycles that freeze new vendor qualification.
- Import concentration for high-temperature alloys:Single-source supply of nickel-based superalloys for turbine blades creates price volatility exposure.
- Dual-use technology export controls:DGFT SCOMET classifications restrict access to precision machining equipment for satellite component fabrication.
Strategic Opportunities
- Telangana defense production corridor:Greenfield aerospace parks near Hyderabad offer integrated testing facilities absent in legacy Bengaluru infrastructure.
- Small satellite constellation demand:ISRO's commercial arm and private launch providers are creating captive markets for miniaturized avionics subsystems.
- Offset obligation restructuring:Revised multiplier credits for technology transfer are incentivizing foreign OEMs to establish engine MRO capabilities in-country.
Industry Challenges
- AS9100D auditor scarcity:Limited certification body capacity in India is extending vendor approval timelines beyond program milestones.
- Legacy platform sustainment integration:Russian-origin fighter fleets require parallel supply chains that fragment procurement scale and complicate inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Aviation, Defense, and Space Market |
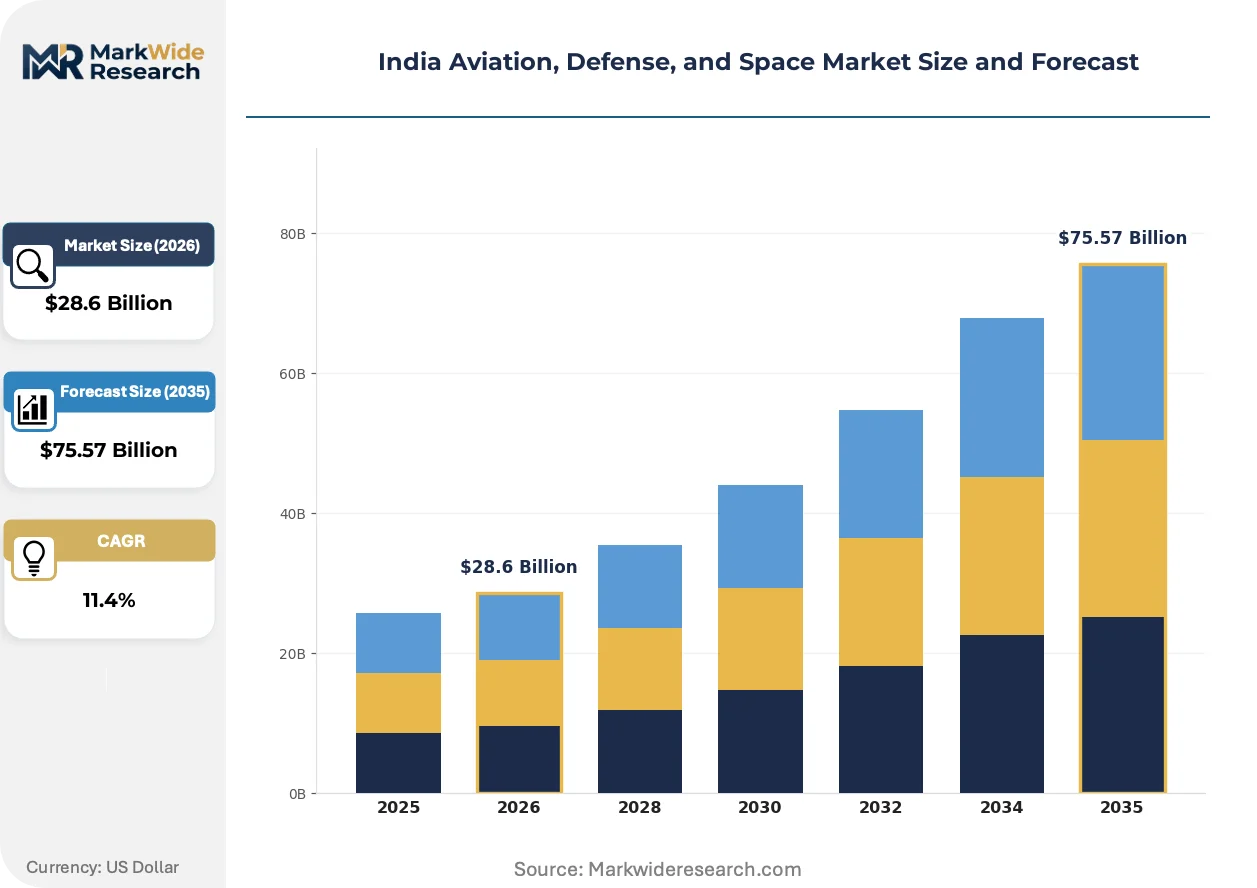
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Military Aircraft, Satellites, Drones Technology: Aerospace Materials, Avionics Systems, Navigation Systems, Missiles Application: Civil Aviation, Defense Operations, Space Exploration, Surveillance End User: Government Agencies, Private Operators, Defense Contractors, Aerospace Manufacturers |
| Companies Covered | Bharat Dynamics Limited, Garden Reach Shipbuilders & Engineers, Hindustan Aeronautics Limited, Data Patterns (India), Larsen & Toubro, Bharat Electronics Limited, Cochin Shipyard, Paras Defence and Space Technologies, Mazagon Dock Shipbuilders, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Aviation, Defense, and Space Market Trends and Innovations
Three forces are compressing development cycles and redrawing competitive boundaries: component miniaturization enabling new platform categories, regulatory recalibration of local content rules, and procurement model evolution toward performance-based sustainment contracts.
Gallium nitride (GaN) monolithic microwave integrated circuits are replacing legacy gallium arsenide components in radar and electronic warfare systems. The Indian Air Force's phased array upgrade programs are absorbing these devices at scale. This transition is miniaturizing antenna apertures while doubling power output per unit volume, enabling conformal radar integration on unmanned platforms previously constrained by payload budgets.
Revised Defence Acquisition Procedure offset guidelines now permit multiplier credits for technology transfer exceeding specified thresholds. Foreign OEMs must now embed design capabilities locally to claim full offset value against fighter and helicopter contracts. The military aircraft segment is responding by mandating joint development clauses in all contracts above defined capital thresholds.
Performance-based logistics contracts are displacing traditional spares procurement for indigenous fighter fleets. HAL and IAF maintenance commands now negotiate availability guarantees rather than component unit pricing. This shift is most visible in the Tejas light combat aircraft program, where contractor logistics support contracts cover 10-year operational availability commitments.
India Aviation, Defense, and Space Market Segmentation
Segmentation reveals how procurement authority and technical requirements split across India's aerospace value chain. Each dimension exposes different competitive dynamics, from HAL's dominance in military platforms to private sector capture of satellite subsystems.
Product Type:
Military Aircraft and Commercial Aircraft flow through Defence Acquisition Procedure channels with BIS certification requirements, while Satellites and Drones increasingly route through private launch service providers and tactical procurement frameworks.
- Military Aircraft:Fighter jet final assembly absorbs the largest capital allocation under India's phased squadron replenishment. Demand concentrates at Hindustan Aeronautics Limited facilities in Bengaluru with Tejas and AMCA programs driving indigenous content mandates.
- Satellites:Miniaturized bus platforms and propulsion subsystems serve ISRO's commercial arm and emerging private constellation operators. Telangana's emerging production corridor is capturing design-to-orbit contracts previously monopolized by legacy Bengaluru clusters.
- Drones:Tactical unmanned systems span surveillance, logistics, and swarm warfare applications across multiple altitude regimes.
- Commercial Aircraft:Narrow-body and regional jet components focus on MRO capabilities and subsystem tier-2 supply to foreign OEMs.
By volume, Military Aircraft leads. By growth pace, Satellites and Drones are expanding most quickly.
Technology:
Cost tiers separate import-dependent high-temperature alloys and precision avionics from domestically maturing navigation and materials segments.
- Aerospace Materials:Composite airframes and titanium structural components require AS9100D certification for supplier qualification. Karnataka's aerospace cluster dominates carbon fiber preform manufacturing while PLI schemes for specialty steel reduce nickel-based superalloy import dependency.
- Avionics Systems:Gallium nitride monolithic microwave integrated circuits are displacing legacy gallium arsenide in radar and electronic warfare applications. Conformal antenna integration on unmanned platforms drives miniaturization demand.
- Navigation Systems:GPS-NavIC hybrid receivers and inertial measurement units serve both civil and military platforms with indigenization mandates.
- Missiles:Guidance electronics and propulsion systems span tactical to strategic ranges with DGFT SCOMET classification constraints on precision machining equipment.
Aerospace Materials commands premium margins given import substitution urgency. Avionics Systems shows the steepest technology transition trajectory.
Application:
Customer procurement patterns distinguish long-cycle Defense Operations contracts from rapidly contracting Surveillance requirements and emerging Space Exploration commercialization.
- Defense Operations:Fighter fleet modernization and missile system procurement operate through multi-year Defence Acquisition Procedure frameworks with local content thresholds. Performance-based logistics contracts now displace traditional spares procurement for indigenous platforms.
- Surveillance:Border monitoring and maritime domain awareness drive tactical unmanned system deployment across multiple altitude regimes. Swarm warfare doctrine is accelerating procurement timelines beyond traditional platform development cycles.
- Civil Aviation:Narrow-body fleet expansion and regional connectivity schemes sustain component MRO demand.
- Space Exploration:Lunar and interplanetary mission support creates captive demand for specialized propulsion and thermal management subsystems.
Defense Operations dominates capital deployment. Surveillance applications are gaining share fastest as procurement accelerates.
End User:
Government Agencies and Defense Contractors operate under Defence Acquisition Procedure mandates, while Private Operators and Aerospace Manufacturers navigate BIS standards and emerging commercial launch regulations.
- Government Agencies:Indian Air Force fleet modernization and ISRO mission requirements anchor procurement volume with indigenization list compliance mandatory.
- Defense Contractors:Bharat Electronics Limited and Data Patterns supply radar, electronic warfare, and satellite subsystems with export program participation.
- Private Operators:Emerging launch providers and constellation operators create demand for miniaturized avionics outside traditional procurement frameworks.
- Aerospace Manufacturers:Tier-1 and tier-2 suppliers to HAL and foreign OEMs face AS9100D certification barriers with limited auditor capacity extending approval timelines.
Government Agencies anchor procurement scale. Private Operators represent the fastest-emerging demand category as commercial space activity liberalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and Defence Acquisition Procedure reforms are redistributing aerospace manufacturing capacity across Indian states. Karnataka and Telangana production corridors absorb the majority of fresh capital commitments.
Karnataka
Bengaluru's aerospace cluster anchors fighter aircraft final assembly through Hindustan Aeronautics Limited facilities. The state's BIS-certified composite preform manufacturing ecosystem supplies carbon fiber structural components to military programs. AS9100D auditor scarcity extends vendor qualification timelines beyond program milestones.
Telangana
Hyderabad's emerging defense production corridor captures design-to-orbit satellite contracts previously monopolized by legacy Bengaluru infrastructure. The Directorate General of Aeronautical Quality Assurance's certification protocols apply to greenfield aerospace parks with integrated testing facilities. Private launch providers and constellation operators create captive demand for miniaturized avionics subsystems.
Maharashtra
Mumbai-Pune industrial belt concentrates missile system integration and precision machining capabilities. DGFT SCOMET classifications restrict access to precision machining equipment for satellite component fabrication. Larsen & Toubro's engineering infrastructure supports submarine and surface vessel construction alongside aerospace component tier-2 supply.
Tamil Nadu
Chennai's manufacturing base sustains commercial aircraft MRO capabilities and narrow-body component supply to foreign OEMs. The Ministry of Defence's offset obligation restructuring incentivizes engine MRO establishment through revised multiplier credits. Tier-2 machine shops face 18-24 month quality system upgrade cycles.
Gujarat
Ahmedabad-Vadodara corridor specializes in aerospace-grade specialty steel production under PLI scheme coverage. Indigenization list expansions redirect procurement toward domestic nickel-based superalloy alternatives for turbine blade applications. Gujarat State Biotechnology Mission's materials science programs intersect with defense metallurgy requirements.
India Aviation, Defense, and Space Market Competitive Landscape
Player mix skews toward public sector undertakings with deep program integration and emerging private specialists in satellite subsystems. Consolidation pressures compress the vendor base as AS9100D certification barriers eliminate tier-3 participants. Two strategic archetypes dominate: state-owned platform integrators with captive supply chains, and private technology specialists capturing export-adjacent opportunities. Competitive moves center on backward integration into critical materials and joint development clauses mandating local design embedding.
Within the state-owned tier, Hindustan Aeronautics Limited and Bharat Electronics Limited occupy positions as platform and subsystem anchors respectively. Data Patterns (India) represents the private specialist archetype focused on satellite avionics and electronic warfare components. These three entities exemplify the bifurcation between scale-driven military production and technology-focused export competitiveness.
| Leading Market Players |
|---|
| Bharat Dynamics Limited |
| Garden Reach Shipbuilders & Engineers |
| Hindustan Aeronautics Limited |
| Data Patterns (India) |
| Larsen & Toubro |
| Bharat Electronics Limited |
| Cochin Shipyard |
| Paras Defence and Space Technologies |
| Mazagon Dock Shipbuilders |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month AS9100D certification cycles for tier-2 machine shops compress vendor eligibility while concentrating pricing power among incumbent suppliers with established quality credentials. This lead-time band forces procurement officers at Hindustan Aeronautics Limited and Bharat Electronics Limited to accept premium pricing for qualified aerospace materials and avionics subsystems, embedding cost premiums into fighter aircraft and satellite programs across Karnataka and Telangana production corridors.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified supplier tiers in India's aerospace value chain. Three-tier pricing structure across AS9100D-certified premium, BIS-compliant standard, and uncertified economy levels segments the vendor base. Price differentiation intensifies around nickel-based superalloy inputs where single-source import dependency concentrates leverage with foreign mills. Cost compression in tier-2 machining is intensifying because auditor scarcity extends qualification timelines beyond program milestones. Defense procurement officers exhibit lowest price sensitivity given indigenization mandates, while commercial MRO operators in Tamil Nadu negotiate hardest on unit component pricing.
Supply Chain Analysis
Strait of Hormuz transit underwrites titanium sponge and specialty steel flows to Gujarat's metallurgical facilities, exposing aerospace material pipelines to maritime chokepoint risk. Geographic supply concentration centers on Russia for nickel-based superalloys, Japan for carbon fiber preforms, and Germany for precision machining equipment. Raw material dependencies rest on aerospace-grade aluminum alloys, gallium nitride substrates for radar components, and high-temperature composites for engine applications. Single-source vulnerability for turbine blade alloys creates price volatility exposure during geopolitical disruptions. Distribution runs through HAL's captive supply network for military platforms and private tier-1 integrators for satellite subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indian Air Force procurement commands and ISRO's commercial arm as vendor qualification barriers compress the supply base to AS9100D-certified incumbents. This consolidation among platform integrators shifts negotiation leverage toward long-term availability contracts and away from spot component purchasing.
For Market Incumbents: Fortify backward integration into carbon fiber preform manufacturing and gallium nitride wafer processing to capture margin pools currently flowing to Japanese and German suppliers. The emergence of Telangana's greenfield aerospace parks threatens Bengaluru's legacy cluster dominance, demanding capacity expansion with integrated testing facilities. Priority investment in captive nickel-based superalloy production through Gujarat's PLI-covered specialty steel corridor reduces import dependency exposure. For New Entrants and Emerging Players: Aftermarket sustainment services for Russian-origin fighter fleets represent the most penetrable white-space target, as HAL maintenance commands struggle with parallel supply chain fragmentation. Miniaturized avionics for small satellite constellations offer second entry path, with private launch providers in Telangana creating demand outside traditional Defence Acquisition Procedure channels. Go-to-market execution should anchor on performance-based logistics contracts with availability guarantees rather than component unit sales. For Investors and Strategic Acquirers: Carve-out targets emerge from public sector undertaking non-core divisions with export-adjacent technology capabilities. Long-term viability hinges on positioning for indigenization list expansion and offset obligation restructuring that rewards technology transfer with multiplier credits. Signal to monitor: Defence Acquisition Procedure recalibrations that elevate local content thresholds for avionics and propulsion subsystems, triggering acquisition premiums for certified tier-2 suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Qualifies vendors for HAL fighter programs and ISRO satellite contracts under DGAQA protocols. |
| Backward Integration into Superalloys | Captures margin pools from Russian and German mills for turbine blade applications. |
| Joint Development Clause Embedding | Satisfies revised offset guidelines requiring local design capabilities for full credit claims. |
| Performance-Based Logistics Contracting | Aligns with IAF Tejas program availability guarantees displacing traditional spares procurement. |
| Telangana Greenfield Facility Establishment | Accesses integrated testing infrastructure absent in legacy Bengaluru aerospace clusters. |
Research Methodology
Operator-level perspectives from HAL program managers, Bharat Electronics procurement leads, DGAQA certification officers, and Telangana aerospace park developers anchored the qualitative base. Primary interviews with tier-1 and tier-2 supplier technical directors combined with secondary validation from BIS aerospace material standards, DGFT SCOMET classification schedules, Defence Acquisition Procedure amendment circulars, and PLI scheme implementation reports. Bottom-up vendor capacity assessments and top-down procurement budget analysis triangulated market sizing across the projection horizon.
Sensitivity analysis framing tested forecast robustness against indigenization list expansion scenarios and offset multiplier recalibration outcomes. Segmentation dimensions modeled include product type, technology tier, application category, and end-user procurement authority alongside state-level production cluster development patterns. CAGRs derived from expenditure trajectory analysis across Defence Acquisition Procedure capital acquisition heads and ISRO commercial mission allocations. Industry-specific inputs encompass fighter squadron replenishment phasing and small satellite constellation deployment schedules.
Forecasts assume regulatory continuity in Defence Acquisition Procedure local content thresholds and DGFT export control classifications; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
China Space Electronics Market
Space
Deep Space Exploration Market
Space
Canada Space Electronics Market
Space
US Space Launch Services Market
Space
Space-Based Solar Power Market
Space
Spacesuit Market
Space
Mexico Space Electronics Market
Space
Space Sensors Market
Space
Space Robotics Market
Space
Suborbital Space Tourism Market
Space
Space Semiconductor Market
Space
Asia-Pacific Space Electronics Market
Space
Space Robots Market
Space
Germany Space Electronics Market
Space
Africa Space Propulsion System Market
Space
Europe Space Electronics Market