
 Soybean Fungicide Seed Treatment Market | 2026-2036
Soybean Fungicide Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Soybean Fungicide Seed Treatment Market Analytics
Multi-source procurement of active ingredients is expanding as formulators seek supply resilience against azole and SDHI chemistry bottlenecks. BASF SE leverages its vertically integrated pyraclostrobin production to sustain cost advantages across Latin America. Syngenta Group anchors its position through proprietary seed treatment formulations that integrate fungicide, insecticide, and nematicide layers. Bayer CropScience competes by controlling distribution through its digital farming platform, which ties seed treatment recommendations to prescription agronomy services.
Soybean fungicide seed treatment denotes the application of protective chemical or biological agents to soybean seeds prior to planting, typically involving active ingredient loadings of 0.5–2.0 grams per kilogram of seed to suppress early-season diseases caused by Pythium, Rhizoctonia, and Phytophthora sojae. The primary commercial purpose is to reduce replant risk and protect yield potential during the critical germination-to-V4 growth stage when root systems remain vulnerable. Systemic fungicides dominate value capture due to their curative mobility through cotyledon tissue, while biological fungicides represent the fastest-expanding segment as Brazilian growers face tightening chlorothalonil restrictions. Coating technology leads treatment method adoption because it permits precise active ingredient placement with minimal dust-off, whereas seed soaking remains limited to niche organic operations where equipment constraints favor simpler processes.
EPA seed treatment labeling requirements and Brazil's national pesticide regulator ANVISA shape product registration timelines, with both agencies intensifying pollinator risk assessments that delay novel chemistry introductions. The EU's Farm to Fork strategy, though not directly binding in the Americas, influences multinational R&D allocation by signaling future restrictions on synthetic fungicide use. REACH compliance obligations for active ingredient exporters add documentation burdens that favor larger manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor how biological product efficacy data standards evolve, as inconsistent field trial protocols across jurisdictions threaten to fragment market access for microbial alternatives.
Market Dynamics
Biological fungicide registration acceleration in Brazil and tightening chlorothalonil restrictions are compressing synthetic chemistry timelines while elevating microbial formulation R&D priorities across formulators.
Growth Catalysts
- ANVISA accelerated pathways:Brazil's streamlined biological product registration reduces time-to-market for microbial seed treatments, incentivizing local field trial investment and domestic manufacturing partnerships.
- Intensive monoculture disease pressure:Continuous soybean cropping in Mato Grosso and Iowa elevates soilborne pathogen loads, forcing commercial growers toward prophylactic seed treatment adoption as a risk management standard.
- Coating technology precision:Advanced polymer film coatings enable sub-gram active ingredient loadings with dust-off below 0.5%, satisfying equipment compatibility requirements in precision planting systems.
Market Restraints
- Azole chemistry supply bottlenecks:Concentrated production of triazole intermediates in China creates vulnerability to export license disruptions and freight cost volatility for formulators lacking captive synthesis.
- Pollinator risk assessment delays:EPA's intensified neonicotinoid and fungicide interaction studies extend novel chemistry registration timelines by 18-36 months, freezing pipeline commercialization.
- Biological efficacy variability:Inconsistent microbial colonization rates across soil temperature gradients limit biological product reliability in early-planted northern geographies.
Strategic Opportunities
- Argentina underpenetration:Lower treatment penetration rates in Buenos Aires and Córdoba provinces present whitespace for biological-synthetic combination products tailored to local Rhizoctonia pressure.
- Digital agronomy integration:Seed treatment recommendations tied to prescription planting platforms create subscription revenue streams and lock-in effects with precision agriculture adopters.
- EU Farm to Fork signaling:Anticipated synthetic fungicide restrictions in European import markets incentivizes biological-active ingredient development for export-compliant Brazilian and US supply chains.
Industry Challenges
- Microbial formulation stability:Shelf-life limitations of live biological actives require cold chain infrastructure investments that strain distributor working capital and inventory management systems.
- Field trial protocol fragmentation:Inconsistent efficacy validation standards across ANVISA, EPA, and state-level extension services multiply registration costs and delay multi-territory product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soybean Fungicide Seed Treatment Market |
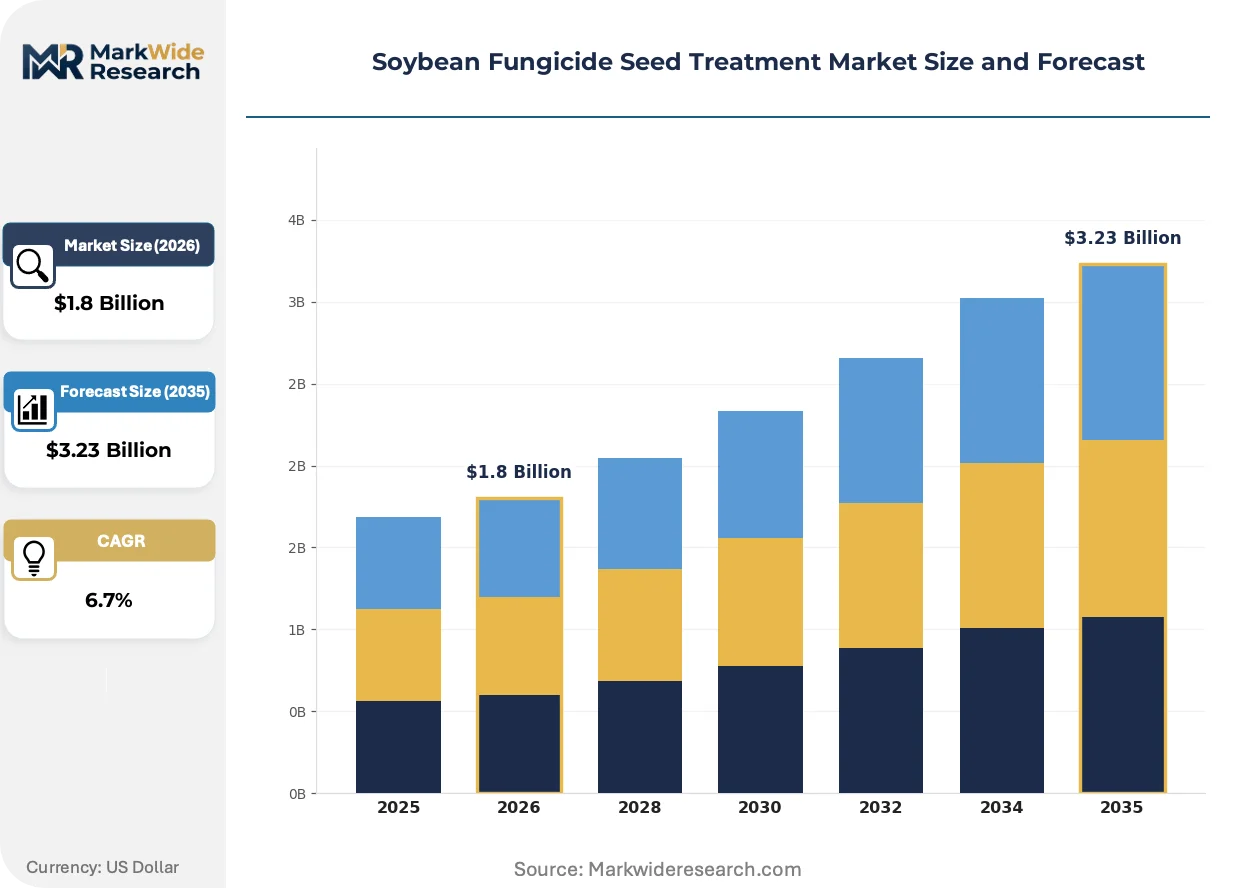
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systemic Fungicides, Contact Fungicides, Biological Fungicides, Combination Fungicides Application: Agronomic Crops, Horticultural Crops, Turf, Others Treatment Method: Coating, Drenching, Seed Soaking, Granulation Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | BASF SE, Syngenta Group, Bayer CropScience, Corteva Agriscience, FMC Corporation, UPL Limited, Nufarm Limited, Sumitomo Chemical, ADAMA Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soybean Fungicide Seed Treatment Market Evolving Landscape
Formulation chemistry is bifurcating toward high-efficacy synthetic stacks for disease hotspots and microbial-dominant systems for regulatory-sensitive zones, with coating hardware becoming the critical integration layer.
Polymer-encapsulated fungicide delivery is modularizing active ingredient release kinetics, permitting synchronized germination-phase protection. Large-scale Iowa and Illinois operators are retrofitting treater lines with precision metering systems that enable 0.1-gram dosing increments. Equipment standardization is compressing formulation differentiation toward application reliability rather than chemistry novelty.
EPA's revised seed treatment labeling requirements mandate pollinator exposure mitigation language and buffer zone specifications on all new registrations. The rule forces reformulation of dust-prone products and redirects R&D toward low-drift coating polymers. Brazilian growers face parallel pressure as ANVISA aligns pollinator risk assessments with OECD guidelines, favoring suppliers with established environmental fate data packages.
Commercial procurement patterns are consolidating around multi-year supply agreements with embedded price collars. Large Mato Grosso cooperatives are bypassing traditional distribution tiers to contract directly with formulators, extracting volume rebates and technical service commitments. Channel compression is most advanced in Brazil's Center-West, where consolidated landholding structures enable collective bargaining power unavailable in fragmented US tenant farming arrangements.
Soybean Fungicide Seed Treatment Market Segmentation
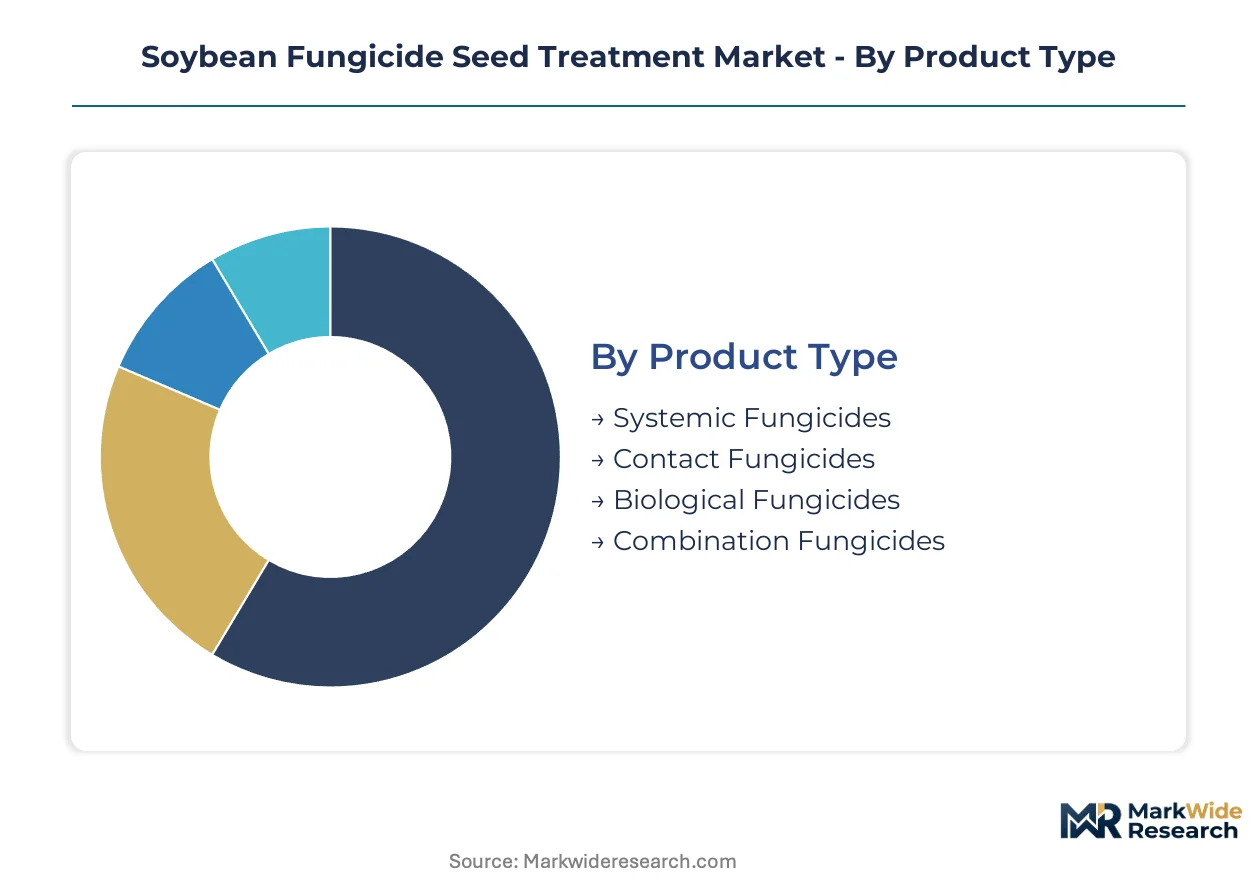
Segmentation in soybean fungicide seed treatment reveals how disease pressure, equipment compatibility, and regulatory exposure shape purchasing decisions across distinct grower profiles and operational scales.
Product Type:
Buyers differentiate by whether they prioritize curative mobility, residual surface protection, or regulatory-compliant biological alternatives.
- Systemic Fungicides:These chemistries translocate through cotyledon tissue to protect emerging root systems from soilborne Phytophthora and Pythium. Demand concentrates in Iowa and Illinois, where early planting into cool, wet soils elevates systemic uptake reliability as a risk management priority.
- Biological Fungicides:Microbial formulations employing Trichoderma and Bacillus species colonize the spermosphere to outcompete pathogens. Brazilian Mato Grosso growers drive fastest adoption as ANVISA accelerates registration timelines ahead of chlorothalonil phase-outs.
- Contact Fungicides:Surface-acting chemistries create protective barriers against Rhizoctonia solani on seed coats. These products suit cost-conscious operators in Argentina's Buenos Aires province seeking basic protection without systemic premium pricing.
- Combination Fungicides:Stacked formulations merge systemic and contact modes for broad-spectrum coverage. Large-scale commercial operations in Brazil's Center-West favor these for operational simplicity in high-volume treating facilities.
Systemic fungicides lead volumes today; biological fungicides are gaining share fastest.
Application:
End-use segmentation tracks how disease pressure intensity and revenue per acre dictate treatment investment thresholds.
- Agronomic Crops:Commercial soybean production dominates absolute demand, with continuous monoculture systems in Brazil and the US Corn Belt requiring prophylactic treatment as standard practice.
- Horticultural Crops:Specialty soybean varieties for edamame and tofu markets command premium seed costs that justify elevated treatment expenditure per unit.
- Turf:Golf course and sports field applications represent a narrow niche where aesthetic standards override agricultural economics.
- Others:Research seed lots and conservation plantings generate intermittent demand with highly variable specification requirements.
Agronomic crops anchor current revenue; horticultural crops show the steepest expansion trajectory.
Treatment Method:
Equipment infrastructure and precision requirements determine which application technology growers can operationalize.
- Coating:Polymer film application enables sub-gram active ingredient precision with dust-off below 0.5%. Precision planting system compatibility drives concentration among large-scale Iowa and Illinois operators retrofitting treater lines.
- Seed Soaking:Immersion-based treatment suits organic operations with simpler equipment constraints and lower throughput requirements.
- Drenching:Post-planting liquid application addresses replant scenarios where initial treatment failed or was skipped.
- Granulation:Dry formulation incorporation into seed coating matrices offers storage stability advantages for distributors managing inventory across multiple growing seasons.
Coating technology dominates installed base; granulation methods are climbing the fastest among biological product formulators.
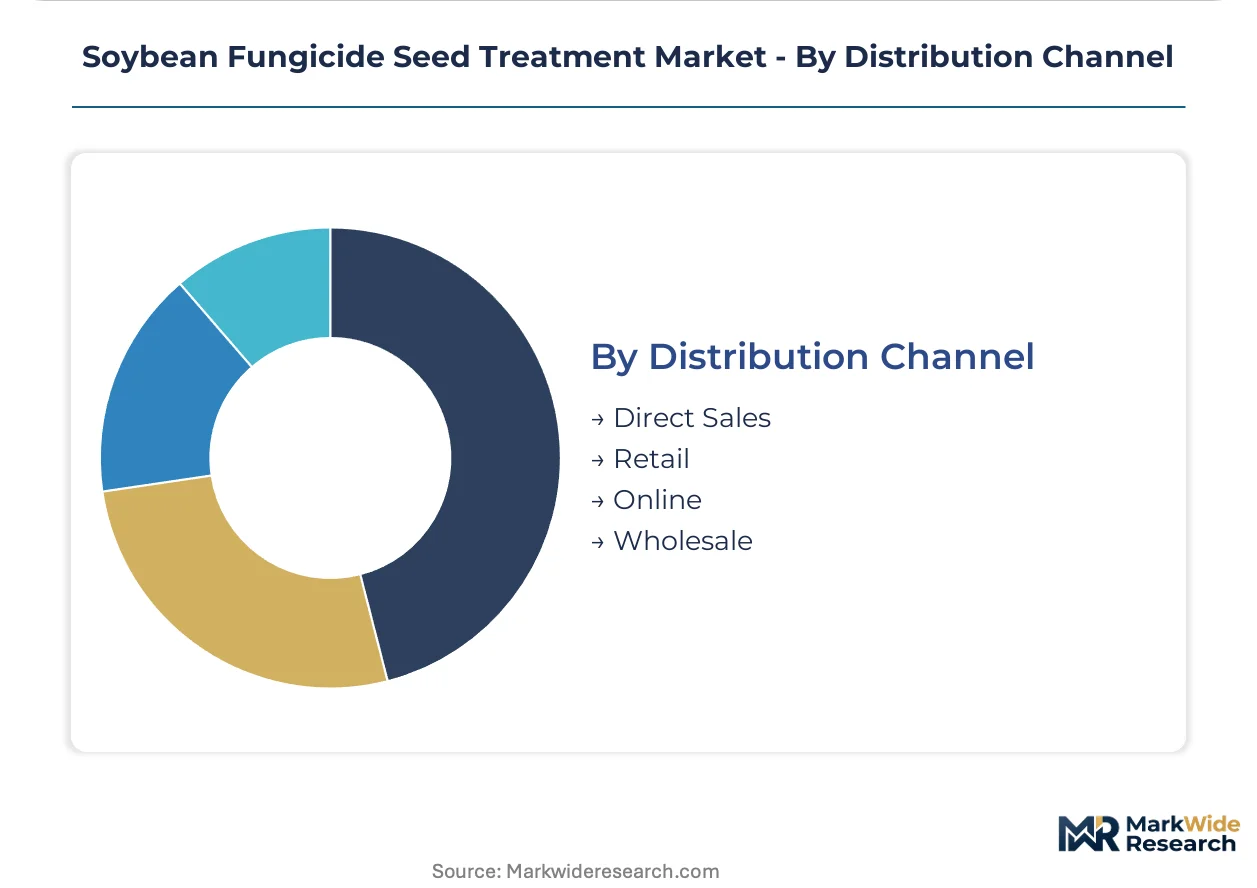
Distribution Channel:
Channel selection reflects farm scale, cooperative membership, and technical service requirements.
- Direct Sales:Formulator-to-grower contracting bypasses distribution tiers, extracting volume rebates and technical commitments. Consolidated Mato Grosso cooperatives pioneered this model.
- Retail:Local agricultural supply stores serve fragmented US tenant farming arrangements where individual growers lack collective bargaining power.
- Wholesale:Regional distributors aggregate demand across smaller treating facilities and independent seed conditioners.
- Online:Digital procurement platforms emerge for standardized biological products with established efficacy reputations and simpler handling requirements.
Retail channels capture the largest transaction volume today; direct sales are expanding most quickly among commercial-scale operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mato Grosso anchors soybean fungicide seed treatment demand through intensive monoculture systems that elevate soilborne pathogen pressure. Brazil's Center-West region generates the highest treatment intensity per hectare globally. The United States Corn Belt follows as the second-largest concentration, with Iowa and Illinois driving systemic fungicide volumes.
Brazil
ANVISA accelerated registration pathways for biological products compress synthetic chemistry timelines while elevating microbial R&D priorities. Chlorothalonil restrictions in Mato Grosso force commercial growers toward Trichoderma-based alternatives. São Paulo-based formulators are expanding domestic manufacturing partnerships to capture local field trial advantages.
United States
EPA pollinator risk assessment delays extend novel chemistry registration timelines by 18-36 months, freezing pipeline commercialization. Iowa and Illinois operators retrofit treater lines with precision metering systems enabling 0.1-gram dosing increments. The Corn Belt's early-planted northern geographies limit biological product reliability due to soil temperature variability.
Argentina
Buenos Aires and Córdoba provinces present whitespace for biological-synthetic combination products tailored to local Rhizoctonia pressure. The national agricultural regulator maintains conventional registration timelines that lag Brazil's accelerated pathways. Pampas region cooperatives negotiate volume rebates directly with multinational formulators, bypassing traditional distribution tiers.
Canada
Health Canada PMRA aligns pollinator risk assessments with OECD guidelines, favoring suppliers with established environmental fate data packages. Prairie Provinces adoption concentrates in Manitoba's Red River Valley, where cool, wet soils elevate Pythium pressure. Ontario's horticultural soybean segment for edamame markets commands premium treatment expenditure per unit.
China
Concentrated production of triazole intermediates creates vulnerability to export license disruptions and freight cost volatility for formulators lacking captive synthesis. The Ministry of Ecology and Environment intensifies environmental compliance obligations for active ingredient manufacturers. Shandong Province chemical clusters supply global azole and SDHI chemistry, with NMPA registration requirements adding documentation burdens for biological product exporters.
Soybean Fungicide Seed Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microbial formulation specialization. The market structures around three archetypes: integrated chemical manufacturers with captive synthesis, biological technology specialists, and regional formulators with distribution control. Consolidation pressure intensifies as multi-year supply agreements with embedded price collars compress margin flexibility. Strategic moves concentrate on backward integration into active ingredient production and digital agronomy platform integration.
Among integrated chemical manufacturers, BASF SE anchors the pyraclostrobin supply tier through in-house production capabilities. Syngenta Group occupies the multi-layer formulation position, exemplifying proprietary seed treatment stacks. Bayer CropScience represents the digital integration archetype, with its platform tying recommendations to prescription agronomy services. These three entities collectively demonstrate how chemistry control, formulation complexity, and data-driven distribution define competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Bayer CropScience |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Nufarm Limited |
| Sumitomo Chemical |
| ADAMA Ltd. |
| Others |
Value Network & Pricing Analysis
Azole intermediate spot prices in Shandong Province cascade through formulator cost structures into three-tier pricing stratification across premium systemic stacks, standard contact formulations, and economy biological alternatives. Brazilian Mato Grosso cooperatives leverage direct contracting to compress distributor margins, while Iowa precision planting operators absorb polymer-coating premiums for sub-gram dosing compatibility.
Pricing Analysis
Input-cost pass-through from concentrated triazole production in China drives pricing pressure across synthetic fungicide tiers, with formulators lacking captive synthesis exposure absorbing freight volatility and export license uncertainty. Price differentiation hinges on active ingredient loading precision and after-sales technical service bundling, separating premium systemic products with field agronomist support from economy contact chemistries sold through retail channels. Cost compression in standard-tier formulations is intensifying as ANVISA accelerations compress registration investment recovery windows. Tenant farming arrangements in the US Corn Belt exhibit highest price sensitivity, while consolidated Brazilian cooperatives prioritize performance guarantees over unit economics.
Supply Chain Analysis
ANVISA local-content incentives and Brazil's domestic manufacturing partnership requirements are reshaping sourcing patterns for microbial formulation components and coating polymer feedstocks. Active ingredient production concentrates in China's Shandong Province chemical clusters, India's specialty chemical corridors, and Germany's agrochemical manufacturing hubs. Raw material dependencies encompass triazole intermediates, SDHI chemistry precursors, and live microbial culture substrates. Single-source vulnerability in Chinese azole intermediate supply creates structural risk exposure for formulators without backward integration into synthesis. Distribution runs through direct formulator-to-cooperative contracting in Brazil's Center-West and retail agricultural supply networks in fragmented US tenant farming regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
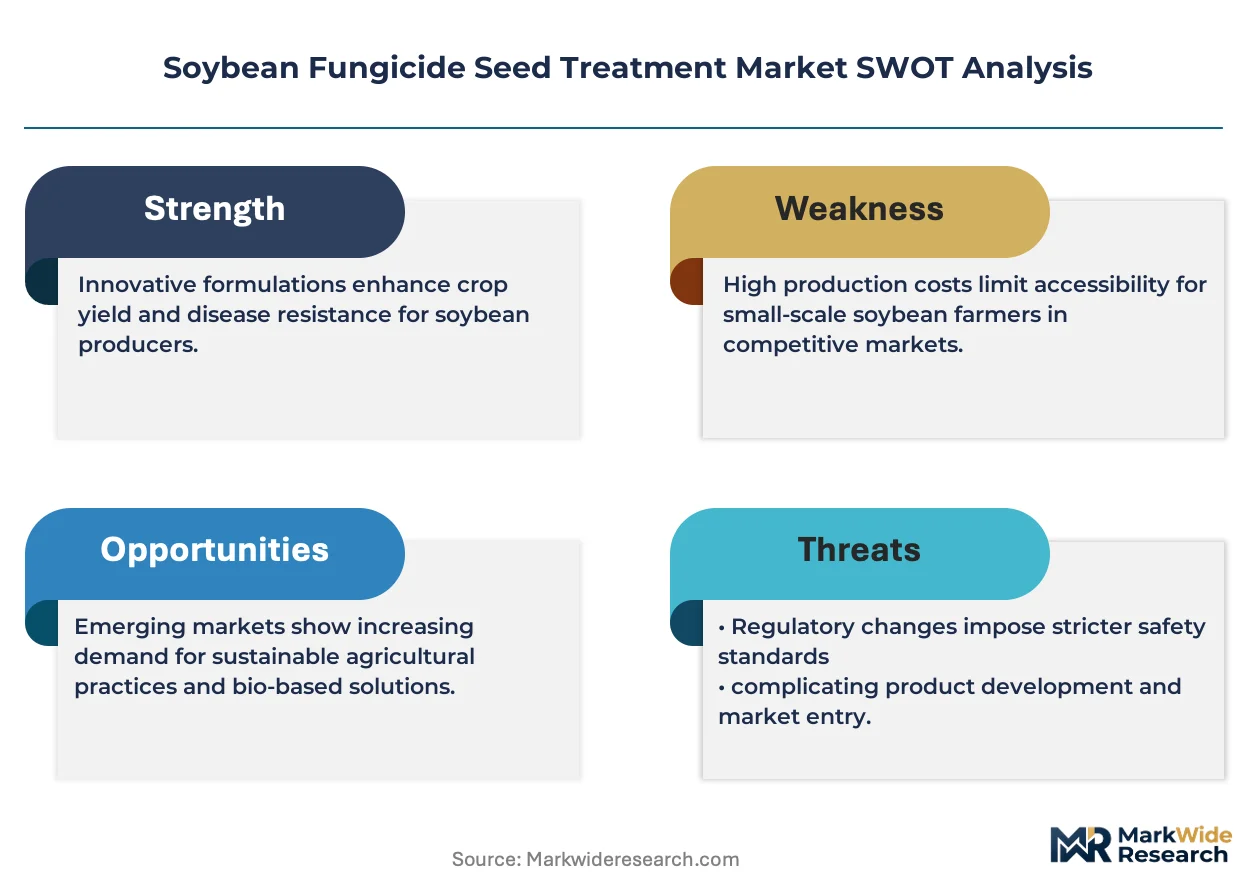
The soybean fungicide seed treatment market functions as a stable compounder anchored by irreversible monoculture disease pressure in Brazil and the US Corn Belt that makes prophylactic treatment a non-discretionary input.
For Market Incumbents: Extend formulation complexity advantages by integrating biological-synthetic combination stacks that preempt regulatory phase-outs of chlorothalonil and other restricted chemistries. Deepen backward integration into pyraclostrobin or other captive active ingredient production to defend margin position against azole supply bottlenecks. Lock in multi-year direct supply agreements with Mato Grosso cooperatives before channel compression accelerates further. For New Entrants and Emerging Players: Enter via Argentina's Buenos Aires and Córdoba provinces where treatment penetration lags Brazilian and US benchmarks and local Rhizoctonia pressure favors tailored biological-synthetic combinations. Target horticultural soybean segments for edamame and tofu markets where premium seed costs justify elevated treatment expenditure per unit and regulatory scrutiny remains lighter than field crop applications. Pursue digital agronomy platform partnerships to embed recommendations within prescription planting workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with biological technology specialists possessing validated Trichoderma and Bacillus strain libraries and established ANVISA registration track records that accelerate time-to-market against synthetic chemistry pipelines frozen by EPA pollinator risk assessment delays. Over a multi-decade agricultural input replacement cycle, microbial formulation capabilities will compound in scarcity value as synthetic restrictions tighten across import markets. Monitor EU Farm to Fork implementation timelines as the critical inflection signal for biological product demand acceleration in export-compliant Brazilian supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Biological-Synthetic Combination Development | Stacked formulations preempt chlorothalonil restrictions while preserving curative efficacy against Phytophthora sojae. |
| Precision Coating Equipment Integration | Sub-gram dosing capability locks in compatibility with Iowa and Illinois precision planting system retrofits. |
| Direct Cooperative Contracting | Bypassing distribution tiers captures Mato Grosso volume rebates and technical service commitment premiums. |
| Domestic Manufacturing Partnerships | ANVISA local-content rules favor São Paulo-based production with accelerated field trial advantages. |
| Digital Agronomy Platform Embedding | Prescription planting integration creates subscription revenue streams and grower lock-in effects. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seed treatment formulator R&D directors, Brazilian cooperative agronomy managers, US precision planting equipment dealers, and ANVISA regulatory affairs specialists with secondary validation through EPA registration databases, ANVISA biological product filings, customs trade data on azole intermediate flows, and SEC 10-K disclosures from listed agrochemical manufacturers. Bottom-up acreage treatment rates and top-down manufacturer revenue estimates were triangulated to anchor market sizing.
Segment-weighting approaches modeled systemic, biological, contact, and combination product categories alongside coating, soaking, drenching, and granulation treatment methods across agronomic and horticultural crop applications. CAGRs were derived from trend extrapolation of treatment penetration rates, active ingredient pricing trajectories, and regulatory timeline impacts across the projection horizon. Industry-specific forecast inputs incorporated ANVISA registration acceleration schedules and EPA pollinator risk assessment pipeline status.
Inputs from EPA and ANVISA filing databases were available through the study window; gaps in proprietary manufacturer field trial data introduce uncertainty bands around biological product efficacy assumptions. Forecasts reflect documented regulatory timelines and disease pressure intensity assumptions, with revision risk stemming from pollinator risk assessment outcome variability and chlorothalonil restriction implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Azoxystrobin Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
IPM Pheromones Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Grain Fumigants Market
Crop Protection
Specialty Pesticides Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
India Herbicide Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Metamitron Herbicides Market