
 Azoxystrobin Market | 2026-2036
Azoxystrobin Market Size, Share, and Industry Trends Forecast 2026-2036
Azoxystrobin Market Outlook
The EU Green Deal's Farm to Fork strategy is hardening residue limits and accelerating the phase-down of high-risk crop protection chemistry across member states. Syngenta anchors the originator segment with proprietary formulation expertise and deep stewardship infrastructure in European cereals. BASF competes through backward integration into active ingredient production and broad geographic registration coverage. ADAMA Agricultural Solutions differentiates via cost-optimized manufacturing scale in China and aggressive generic penetration across emerging markets.
Azoxystrobin is a broad-spectrum strobilurin fungicide synthesized from the natural antibiotic strobilurin A, functioning by inhibiting mitochondrial respiration at the Qo site of cytochrome bc1 complex to block fungal ATP production. The compound delivers preventive and curative control of Ascomycete, Basidiomycete, and Oomycete pathogens in field crops, orchards, and turf systems at application rates typically ranging from 100 to 250 grams active ingredient per hectare. Liquid formulation and SC categories dominate volume due to ease of tank-mixing and foliar adhesion, while WDG formats command premium positioning in high-value fruit and vegetable segments where dust-free handling and precise dosing reduce operator exposure. Turf grass applications sustain above-average margins through specialized channel access and golf course maintenance contracts, though cereals generate the absolute tonnage base.
EPA tolerance reassessments and REACH authorization requirements are reshaping product registration timelines and data package costs for azoxystrobin registrants across North America and Europe. China's MEE enforces stricter effluent standards on azoxystrobin intermediate manufacturers, tightening supply responsiveness during peak seasonal demand. Brazil's national agricultural regulator maintains residue monitoring programs that directly influence import acceptance criteria for grain shipments. Stakeholders must weigh regulatory lag against biological efficacy erosion as pathogen resistance to QoI chemistry accumulates in major cereal and soybean production belts.
Market Dynamics
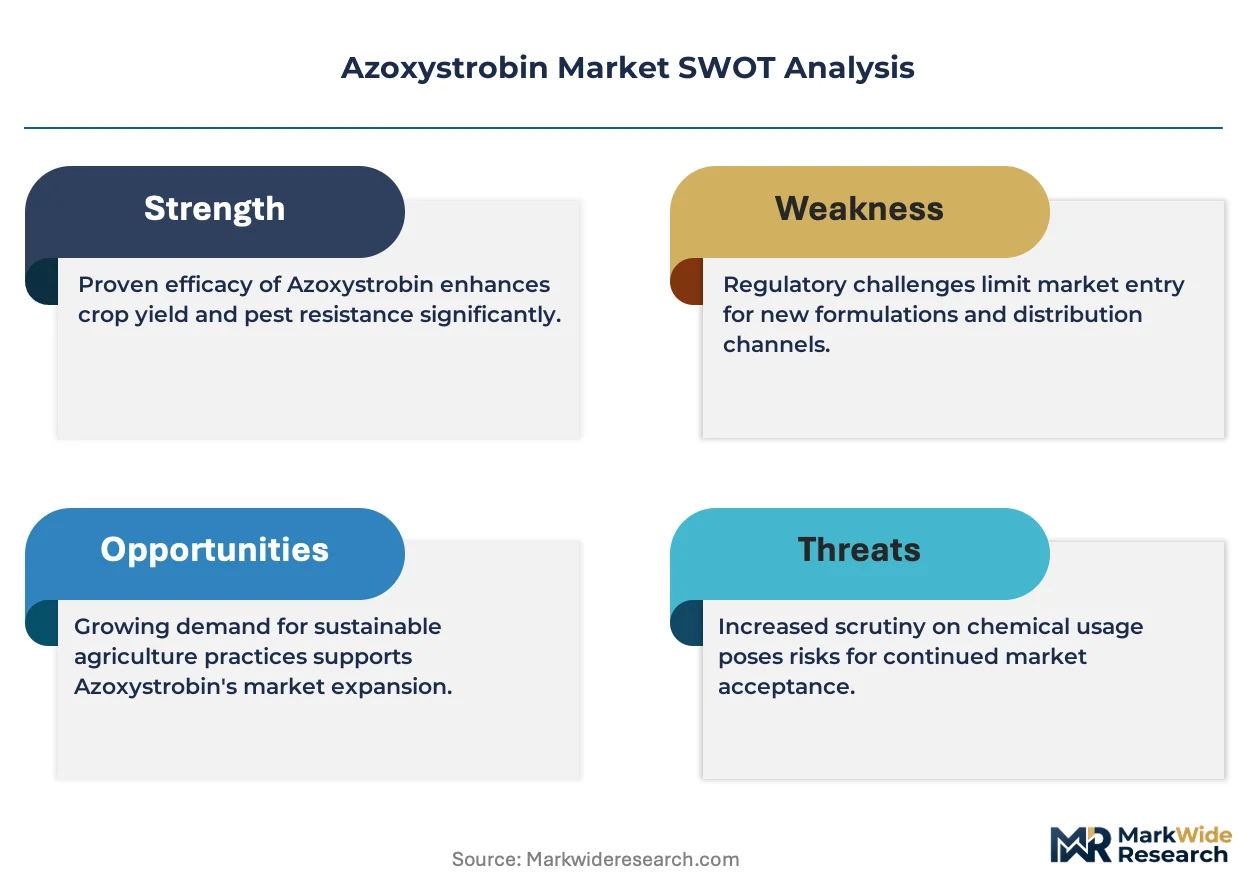
Resistance accumulation in QoI fungicide chemistry is forcing registrants to deploy mandatory mixture protocols and rotate modes of action across cereal and soybean belts. Stewardship obligations from the EPA and EU are tightening label restrictions and accelerating the phase-down of standalone azoxystrobin applications in high-residue crops.
Growth Catalysts
- Climate-intensified disease pressure:Wheat and rice growers in Brazil and India are expanding preventive fungicide programs as erratic rainfall patterns elevate foliar pathogen incidence in humid subtropical zones.
- REACH authorization timelines:ECHA's extended registration windows for strobilurin actives are consolidating compliant supplier bases and locking in committed offtake from European cereal cooperatives.
- Suspension concentrate formulations:SC technology improves tank-mix compatibility and foliar adhesion, concentrating demand among East Asian vegetable producers seeking operator-friendly application methods.
Market Restraints
- Intermediate supply concentration:China's MEE effluent enforcement on azoxystrobin precursor manufacturers creates seasonal bottlenecks during Q2 planting windows in the Northern Hemisphere.
- Biological substitution threat:Bacillus-based biofungicides are capturing share in organic-certified fruit segments where residue tolerance thresholds approach zero.
- Resistance management mandates:EPA-mandated resistance mitigation labels restrict single-active applications and force costly co-formulation development.
Strategic Opportunities
- Underpenetrated African cereals:Commercial wheat and maize operations in Ethiopia and Kenya lack systematic fungicide protocols, creating first-mover positioning for stewardship-anchored registrants.
- Seed treatment pivot:Migrating azoxystrobin from foliar to seed-applied delivery reduces resistance selection pressure and opens proprietary formulation premiums in hybrid corn markets.
- EU Green Deal residue compression:Farm to Fork's 50% pesticide reduction target is accelerating demand for precision-dosed WDG formats that minimize environmental loading while maintaining efficacy.
Industry Challenges
- Regulatory data package costs:EPA tolerance reassessments and OECD-compliant ecotoxicology studies require multi-year investment timelines that strain mid-tier generic portfolios.
- Pathogen monitoring infrastructure:Real-time resistance surveillance networks remain underdeveloped across South American soybean belts, delaying adaptive stewardship responses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azoxystrobin Market |
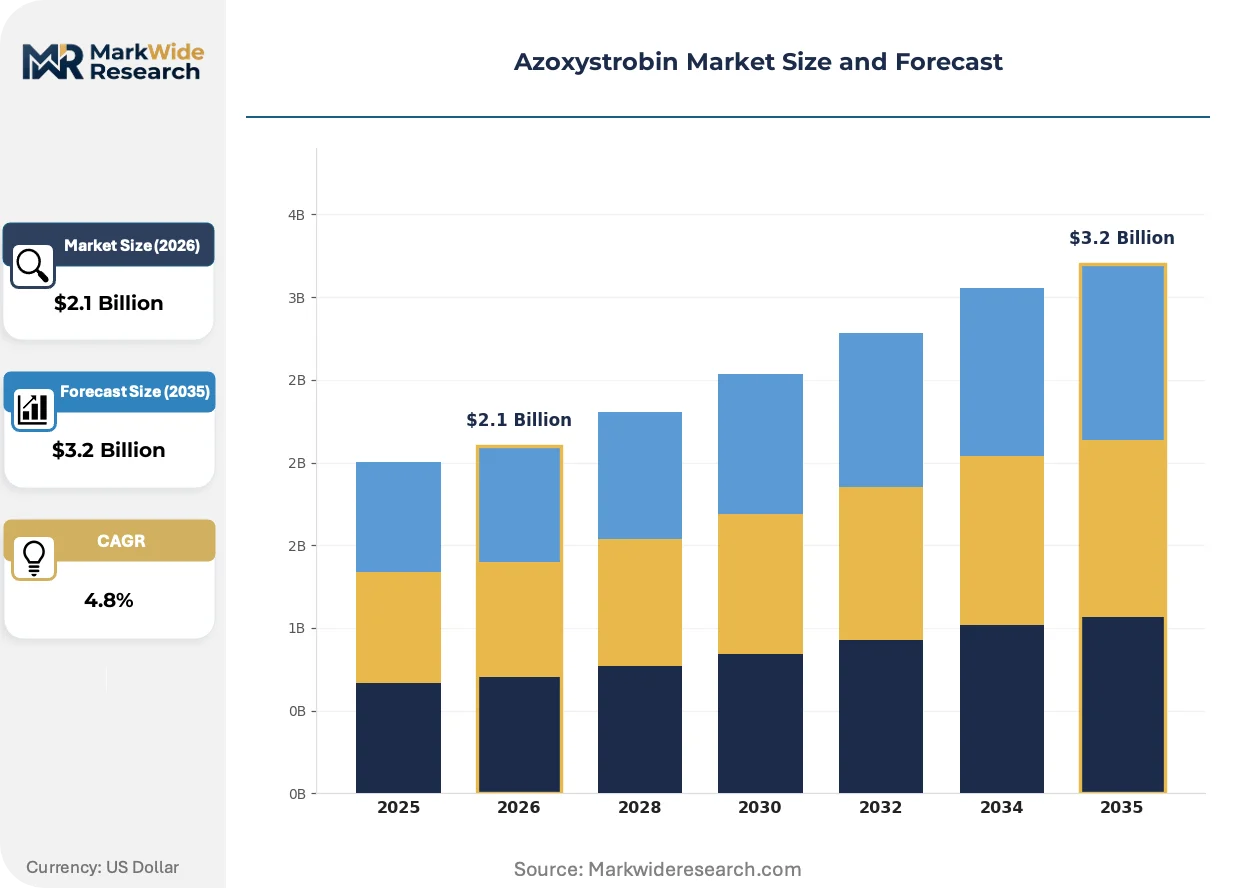
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Formulation, Granule Formulation, WDG, SC Application: Cereals, Fruits, Vegetables, Turf Grass End User: Agricultural Producers, Commercial Growers, Distributors, Retailers Distribution Channel: Online Sales, Wholesale, Direct Supply, Agrochemical Retail |
| Companies Covered | Nutrichem, Jiangsu Frey, Syngenta, BASF, Zhejiang Rayfull Chemicals, Suli Chemical, Limin Chemical, ADAMA Agricultural Solutions, Shanghai Heben, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azoxystrobin Market Strategic Shifts
Formulation chemistry and digital agriculture tools are compressing application windows and reshaping how growers integrate fungicide decisions into precision crop management systems.
Microencapsulation technology is converging with drone-based aerial application systems to enable controlled-release azoxystrobin delivery that reduces drift and extends residual protection. Brazilian soybean cooperatives are piloting these combinations across Mato Grosso and Paraná states. The convergence is compressing traditional ground-spray equipment replacement cycles and concentrating service revenue in agritech-enabled distribution channels.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate fluorinated propellants from pressurized azoxystrobin formulations and migrate toward water-based delivery systems. This industrial consequence is accelerating capital redeployment into aqueous suspension infrastructure. High-value vineyard and orchard segments in France and Italy are responding fastest, accepting modest price premiums for fluorine-free certified products.
Channel consolidation among agricultural retailers is compressing fungicide procurement from decentralized distributor networks toward direct manufacturer-contracted agronomy service bundles. Independent farm supply cooperatives in the US Corn Belt are being displaced by vertically integrated input platforms that bundle seed, chemistry, and digital monitoring. This behavioral shift is most visible across Iowa and Illinois, where three-channel purchasing has collapsed to single-source contracting within five growing seasons.
Azoxystrobin Market Segmentation
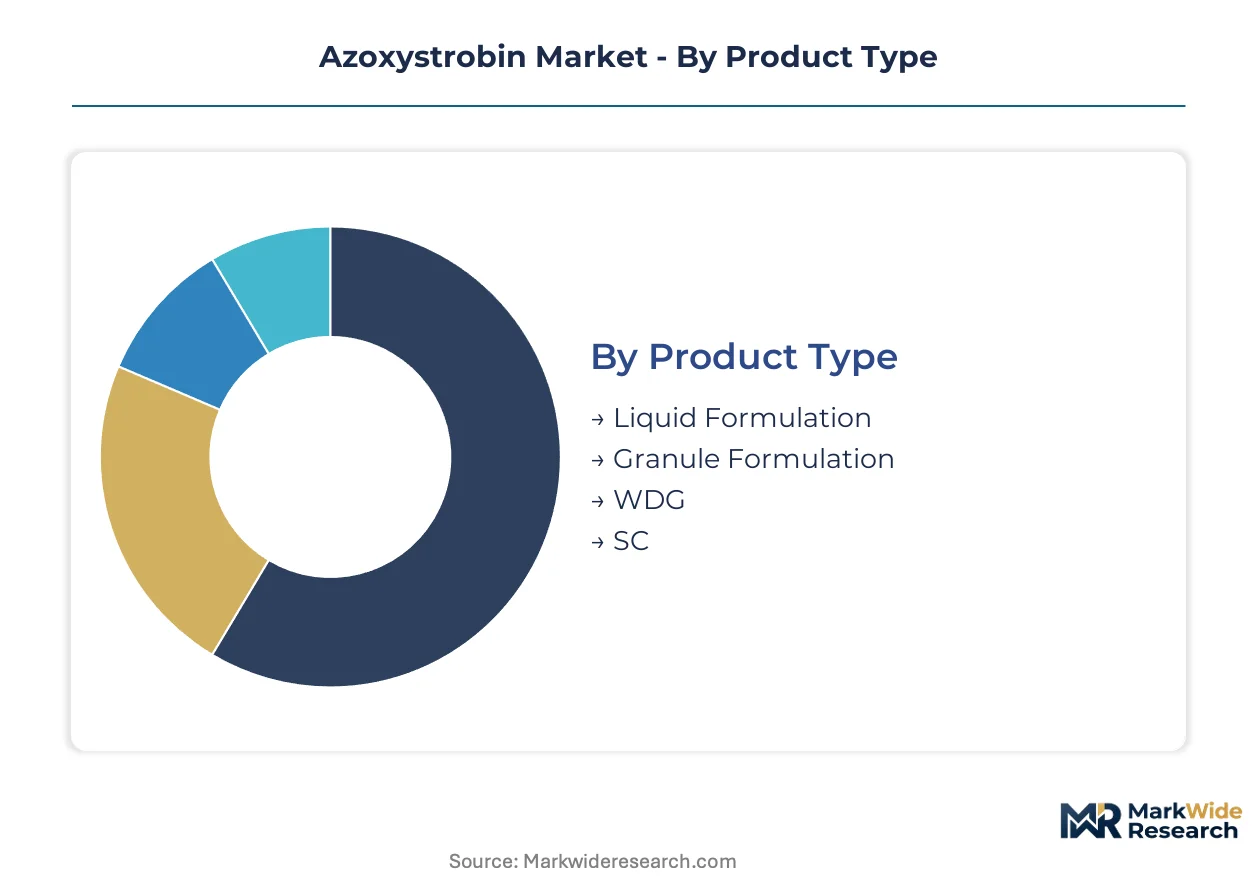
Formulation chemistry and application method determine margin structure and regulatory exposure across azoxystrobin value chains. Segmentation reveals where capital deployment concentrates and which channels capture premium pricing.
Product Type:
Liquid suspension systems and dry granule technologies demand differentiated manufacturing infrastructure, with aqueous processing lines requiring heavier upfront environmental compliance investment.
- Liquid Formulation:Oil-in-water emulsion systems enable rapid tank-mixing with co-formulants and foliar adhesion enhancers. Brazilian soybean cooperatives and Indian rice paddy operations favor this format for aerial application compatibility during compressed planting windows.
- SC:Suspension concentrate technology suspends solid active ingredient particles in aqueous phase with polymeric stabilizers. East Asian vegetable producers in China's Shandong and Japan's Hokkaido prefectures concentrate demand here for operator-friendly handling and reduced drift liability.
- WDG:Water-dispersible granules eliminate dust exposure and enable precise dosing calibration.
- Granule Formulation:Dry broadcast granules serve subsurface application in turf and certain cereal systems.
Liquid Formulation absorbs the bulk of installed capacity; SC is expanding most quickly.
Application:
Crop value per hectare and disease pressure intensity segment demand across radically different margin profiles and stewardship requirements.
- Cereals:Wheat and rice applications in Brazil's Rio Grande do Sul and India's Punjab generate absolute tonnage through repetitive seasonal programs. Volume concentration here forces price competition and co-formulation bundling to maintain registrant margins against generic substitution.
- Turf Grass:Golf course maintenance contracts and sports field management sustain above-average pricing through specialized channel access and technical service bundling. Florida, Arizona, and Spain's Costa del Sol represent concentrated demand clusters where superintendent relationships lock in recurring revenue.
- Fruits:Orchard applications in Italy's Emilia-Romagna and Chile's Central Valley face stringent residue limits that favor precision-dosed WDG formats.
- Vegetables:High-value protected cropping in China's Shouguang and Mexico's Sinaloa demands rapid disease suppression with minimal pre-harvest intervals.
Cereals command the volume base; Turf Grass captures the margin premium.
End User:
Scale and technical sophistication separate buyers who self-apply from those requiring full-service agronomy support.
- Agricultural Producers:Owner-operated farms across Iowa, Mato Grosso, and Ukraine's Black Belt purchase through cooperative buying groups. Equipment ownership and spray contractor relationships determine brand loyalty and formulation preferences.
- Commercial Growers:Corporate farming operations and managed investment funds standardize input procurement across multiple properties. Technical staff and in-house agronomists enable direct manufacturer relationships that bypass traditional distribution markups.
- Distributors:Regional agrochemical wholesalers maintain inventory positions and credit extension for seasonal demand surges.
- Retailers:Independent farm supply stores and input cooperatives serve smaller operators with technical advice and application timing recommendations.
Commercial Growers are consolidating procurement volume fastest; Agricultural Producers retain the broadest geographic footprint.
Distribution Channel:
Channel structure determines working capital intensity and who captures agronomic service revenue.
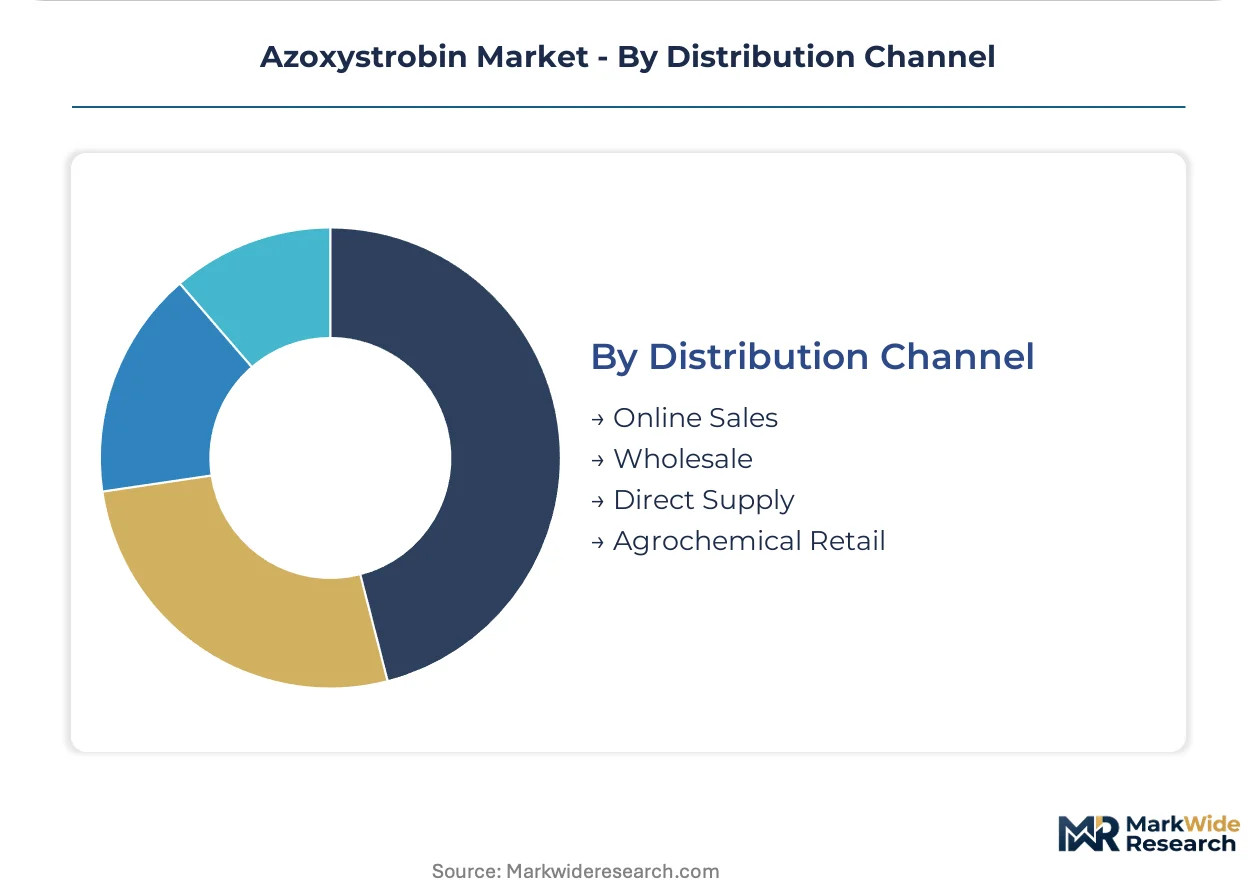
- Wholesale:Volume aggregation through national distributors dominates cereal belt procurement in the US Corn Belt and Argentina's Pampas. Inventory financing and seasonal credit terms lock in supplier relationships across multiple active ingredient categories.
- Direct Supply:Manufacturer-contracted agronomy bundles displace independent retailers across Iowa and Illinois. Seed-chemistry-digital monitoring integration captures full-farm input decisions and reduces price transparency.
- Online Sales:E-commerce platforms penetrate smaller horticultural operations and specialty crop segments with transparent pricing and rapid fulfillment.
- Agrochemical Retail:Branded retail networks with technical service staff maintain position in high-value fruit and vegetable districts.
Wholesale channels handle the volume foundation; Direct Supply is gaining share fastest among large-scale operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates azoxystrobin active ingredient production while Brazil and India drive consumption growth through expanding wheat and rice programs. Regulatory divergence between EPA-mandated resistance protocols and EU Green Deal residue compression is fragmenting regional product availability. Industrial clusters in Jiangsu province and São Paulo state illustrate this supply-demand asymmetry.
China
Jiangsu and Zhejiang provinces host concentrated intermediate manufacturing for azoxystrobin precursors. MEE effluent enforcement tightens seasonal supply responsiveness during Northern Hemisphere planting peaks. Shandong's vegetable production belt concentrates demand for suspension concentrate formulations among protected cropping operations.
Brazil
Wheat growers in Rio Grande do Sul and soybean cooperatives across Mato Grosso expand preventive fungicide applications amid intensifying Asian soybean rust pressure. ANVISA residue monitoring programs directly shape import acceptance criteria for grain shipments. Paraná state pilots microencapsulated drone delivery systems across commercial soybean operations.
United States
Corn Belt operators in Iowa and Illinois consolidate procurement through vertically integrated seed-chemistry bundles. EPA tolerance reassessments extend registration timelines and inflate data package costs for generic registrants. Florida's golf course maintenance sector sustains premium pricing through specialized superintendent relationships.
India
Rice paddy applications in Punjab and Haryana intensify as erratic monsoon patterns elevate sheath blight incidence. Central Insecticides Board registration requirements slow new formulation introductions while protecting incumbent positions. Maharashtra's horticultural districts demonstrate fastest adoption of water-dispersible granule formats among export-oriented grape producers.
Germany
Cereal cooperatives in Bavaria and Lower Saxony lock in committed offtake through REACH-compliant supplier consolidation. ECHA extended registration windows for strobilurin actives filter non-compliant competitors from European supply chains. Rhineland-Palatinate's vineyard operations drive demand for fluorine-free certified formulations under EU F-Gas Regulation phase-down schedules.
Azoxystrobin Market Competitive Environment
The competitive structure tilts toward originator-backed formulation specialists with deep stewardship infrastructure. Market concentration reflects significant barriers from multi-year registration timelines and resistance management data requirements. Two strategic archetypes dominate: integrated agrochemical majors with captive active ingredient supply, and cost-optimized Chinese manufacturers with generic penetration capabilities. Capacity expansion and co-formulation bundling represent the dominant competitive moves as standalone azoxystrobin applications face regulatory phase-down.
Among integrated agrochemical majors, Syngenta and BASF exemplify the originator tier through proprietary formulation expertise and backward integration into active ingredient production. ADAMA Agricultural Solutions occupies a distinct position representing the generic-specialist archetype with manufacturing scale advantages. Chinese manufacturers including Nutrichem, Jiangsu Frey, and Zhejiang Rayfull Chemicals sit within the cost-optimized supply tier serving emerging market demand. Limin Chemical and Suli Chemical represent mid-scale fabricators concentrated in Jiangsu province's chemical manufacturing corridor. The competitive dynamic pivots on stewardship infrastructure investment versus manufacturing cost minimization as regulatory divergence between jurisdictions intensifies.
| Leading Market Players |
|---|
| Nutrichem |
| Jiangsu Frey |
| Syngenta |
| BASF |
| Zhejiang Rayfull Chemicals |
| Suli Chemical |
| Limin Chemical |
| ADAMA Agricultural Solutions |
| Shanghai Heben |
| Others |
Value Chain & Pricing Dynamics
Family-owned chemical conglomerates in China's Jiangsu manufacturing corridor anchor active ingredient production, translating captive intermediate supply into pricing discipline that resists seasonal volatility during Northern Hemisphere planting peaks. Their ownership structure enables patient capital deployment against environmental compliance upgrades, insulating originator-tier pricing from generic cost-down pressure.
Pricing Analysis
Margin tightening in generic-grade azoxystrobin reflects MEE effluent enforcement costs passed through Jiangsu precursor manufacturers to downstream formulators. Three-tier pricing structure across originator, branded generic, and unbranded commodity levels segments buyers by stewardship service intensity and registration data access. Cost compression accelerates as Brazilian soybean cooperatives consolidate procurement through direct manufacturer contracts, bypassing distributor markups. Agricultural Producers in cooperative buying groups exhibit highest price sensitivity, while Turf Grass superintendents accept premiums for technical service bundling.
Supply Chain Analysis
Container freight rate volatility from Shanghai to Santos strains working capital for Brazilian distributors holding seasonal inventory positions. Active ingredient production concentrates in China, India, and Germany, with formulation finishing distributed across regional hubs. Precursor chemistry draws from aniline and phenylacetic acid feedstocks vulnerable to petrochemical price swings. Single-source vulnerability persists where Jiangsu intermediate fabricators lack qualified backup capacity. Distribution runs through vertically integrated agronomy service platforms displacing independent retailers in the US Corn Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Azoxystrobin fungicide chemistry confronts a formulation-transition phase as microencapsulation and drone-compatible suspension concentrates displace legacy emulsifiable concentrate and wettable powder formats.
For Market Incumbents: Deepen backward integration into azoxystrobin precursor manufacturing to secure supply continuity against MEE environmental enforcement tightening. Expand stewardship infrastructure in Brazilian soybean belts and Indian rice districts to lock in cooperative offtake before generic registration data packages mature. Resistance management mandates from EPA and ECHA threaten standalone product viability, making co-formulation bundling with SDHI or triazole chemistry essential for label retention. For New Entrants and Emerging Players: Drone application service providers represent the most accessible channel anchor for novel formulation technologies lacking ground-spray equipment relationships. White-space concentration exists in Ethiopian and Kenyan commercial cereal operations lacking systematic fungicide protocols. Precision-dosed WDG formats for EU vineyard and high-value vegetable segments offer penetrable entry points where residue compression accelerates demand for dust-free handling. Seed treatment pivot opportunities in hybrid corn markets reduce resistance selection pressure while opening proprietary premium positioning. For Investors and Strategic Acquirers: ECHA extended registration windows for strobilurin actives filtering non-compliant competitors is the leading indicator that European supply chain consolidation will accelerate. Mid-scale Chinese fabricators with captive environmental compliance infrastructure and REACH-ready data packages represent the most viable acquisition archetype. Long-term viability hinges on formulation innovation pipelines capable of migrating azoxystrobin from foliar to seed-applied and microencapsulated delivery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Secures supply continuity against MEE effluent enforcement tightening seasonal responsiveness. |
| Co-Formulation Development with SDHI Chemistry | Satisfies EPA resistance management mandates threatening standalone azoxystrobin label retention. |
| Microencapsulation Technology Deployment | Enables drone-compatible controlled-release delivery reducing drift liability in Brazilian soybean operations. |
| Seed Treatment Format Migration | Reduces resistance selection pressure while opening proprietary premiums in hybrid corn markets. |
| Stewardship Infrastructure Expansion in Africa | Captures first-mover positioning in Ethiopian and Kenyan commercial cereal operations. |
Study Parameters
Independent corroboration across regulatory filing databases, customs trade records, and agronomic extension publications underwrites the qualitative findings on resistance accumulation patterns and formulation adoption trends. Primary interviews with plant protection product managers, procurement leads at Brazilian soybean cooperatives, distribution channel partners in the US Corn Belt, and technical R&D directors at Jiangsu manufacturing facilities combined with secondary validation from EPA tolerance reassessment documents, ECHA registration dossiers, ANVISA residue monitoring reports, and OECD-compliant ecotoxicology study disclosures. Bottom-up volume modeling and top-down value reconciliation triangulated across these sources.
Comparable-period anchoring to historical application intensity data across cereals, turf, fruits, and vegetables calibrated the forecast window against climate-driven disease pressure trends. Segmentation modeling incorporated formulation type, crop application, end-user scale, and distribution channel structure throughout the projection horizon. CAGRs derived from regression analysis of planted area expansion, fungicide treatment frequency indices, and price trajectory assumptions for originator versus generic product tiers. Industry-specific inputs included Asian soybean rust incidence monitoring and EU Farm to Fork pesticide reduction target implementation pacing.
Caveats apply where pathogen resistance breakthroughs, regulatory revocation events, or biological fungicide substitution acceleration could materially shift the outlook. Forecasts reflect assumptions on stewardship compliance cost pass-through and generic registration timeline pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Organic Pesticides Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Iprodione Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market
Crop Protection
South America Acaricides Market
Crop Protection
Nematicides Market
Crop Protection
Global Termite Control Market
Crop Protection
Europe Insecticides Market
Crop Protection
China Insecticide Market
Crop Protection
IPM Pheromones Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
South America Insecticide Market
Crop Protection
Tebuconazole Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Latin America Crop Protection Chemicals Market