
 India Herbicide Market | 2026-2036
India Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
India Herbicide Market Insights
Horticulture and cash crop intensity is hardening herbicide demand across India's western and northern agricultural belts. UPL Limited anchors its position through backward integration into technical manufacturing and deep distribution into tier-three towns. Syngenta Group differentiates via biological-herbicide combination portfolios tailored to export-oriented fruit and vegetable growers. Corteva Agriscience competes on R&D intensity, particularly in sulfonylurea-tolerant hybrid rice systems.
Herbicides are phytochemical agents designed to disrupt specific enzymatic pathways in target weeds, formulated as emulsifiable concentrates or suspension concentrates with active ingredients such as glyphosate, atrazine, or 2,4-D amine salts, and applied to protect crop yield by suppressing competing vegetation. Selective herbicides dominate volume due to their compatibility with India's cereal-pulse rotation systems, while non-selective formulations capture expanding margin pools in zero-tillage wheat and direct-seeded rice protocols. Post-emergent applications are accelerating fastest as farmers shift from manual weeding to timed spray interventions during critical crop growth windows.
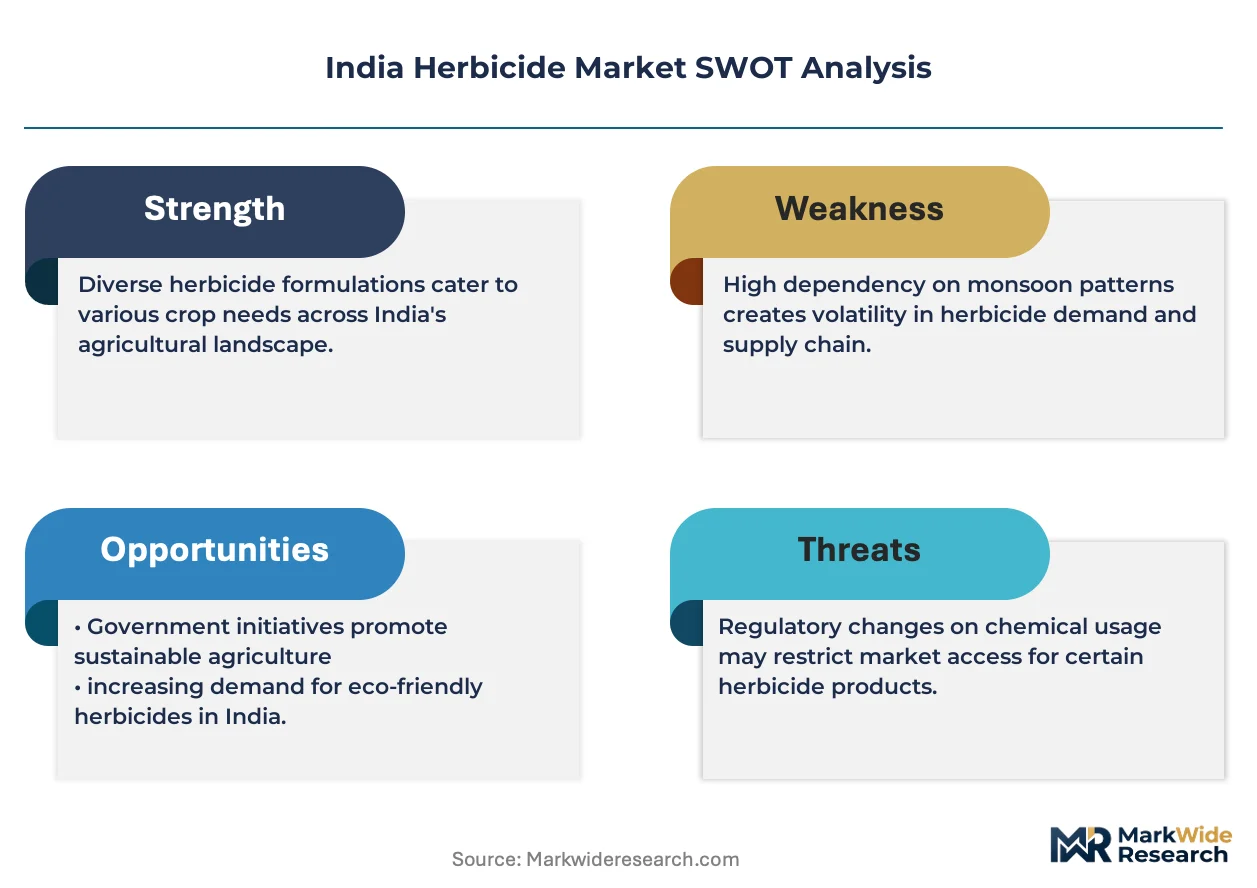
BIS mandates residue limits under the Food Safety and Standards Act, while CEA guidelines govern aerial and power sprayer application standards near water bodies. CDSCO regulates novel molecule registration timelines, and the PLI scheme for agrochemicals is reshaping where technical-grade manufacturing locates versus formulation-only facilities. Stakeholders must monitor how state-level groundwater extraction bans intersect with herbicide runoff containment rules in Punjab and Haryana.
Market Dynamics
The PLI scheme for agrochemicals is redirecting technical-grade manufacturing capacity toward domestic active ingredient production, compressing import dependence while reshaping competitive positioning between integrated and formulation-only players.
Growth Catalysts
- PLI scheme incentives:The production-linked incentive framework for agrochemicals subsidizes capital expenditure for technical-grade manufacturing, drawing formulation capacity toward backward integration into glyphosate and 2,4-D active ingredient production.
- Cotton belt expansion:Post-emergent selective herbicide volumes are hardening in Maharashtra and Gujarat as Bt cotton acreage intensifies and manual weeding labor costs escalate.
- Zero-tillage protocols:Direct-seeded rice and zero-tillage wheat systems in Punjab and Haryana are displacing traditional tillage practices, expanding non-selective herbicide application windows.
Market Restraints
- Import concentration:Technical-grade glyphosate and paraquat dependence on Chinese intermediate suppliers creates supply vulnerability during port congestion or diplomatic friction.
- FSSAI residue enforcement:The Food Safety and Standards Act maximum residue limits for atrazine and 2,4-D in food grains are tightening, forcing reformulation investments and label restriction compliance.
- Groundwater extraction bans:Punjab and Haryana state-level restrictions on tube well irrigation are compressing herbicide runoff dilution capacity, elevating environmental compliance costs near water bodies.
Strategic Opportunities
- Biological-herbicide combinations:Microbial bioherbicide adjuvants paired with reduced-dose synthetic chemistries are opening premium positioning among export-oriented grape and pomegranate growers in Nashik and Sangli.
- Tier-three distribution:Direct-to-retailer digital procurement platforms are penetrating Andhra Pradesh and Telangana, disintermediating traditional mandi-based supply chains.
- Drone application protocols:CEA guidelines for aerial spraying near water bodies are creating certified service provider niches for power sprayer fleet operators in canal-irrigated belts.
Industry Challenges
- Registration timeline compression:CDSCO novel molecule approval cycles averaging 36-48 months are delaying product pipeline commercialization and eroding patent-effective market exclusivity periods.
- Formulation chemist scarcity:Technical talent capable of suspension concentrate and oil dispersion formulation development is concentrating in Mumbai-Pune and Hyderabad clusters, creating recruitment bottlenecks for northern manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Herbicide Market |
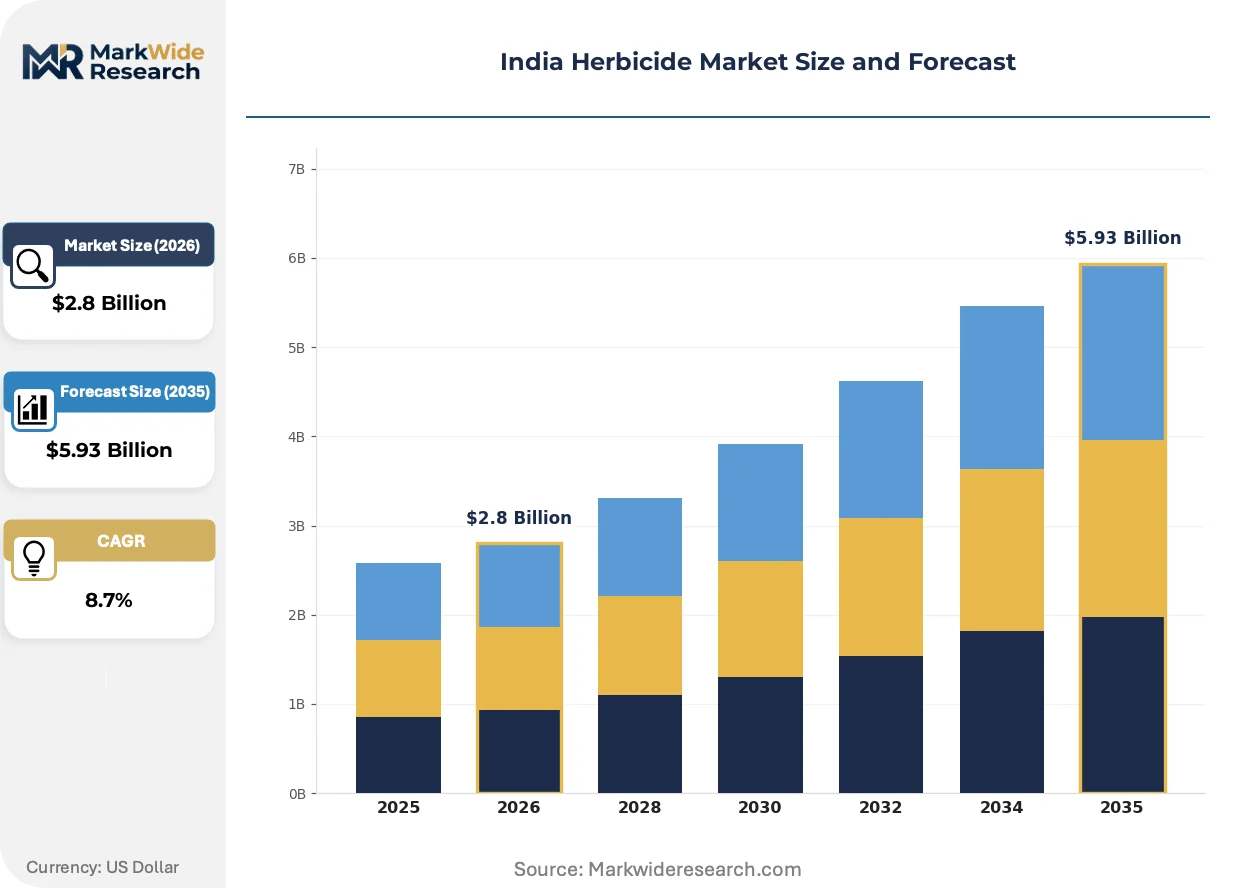
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective, Non-Selective, Pre-Emergent, Post-Emergent Crop Type: Cereals, Pulses, Vegetables, Fruits Formulation: Liquid, Granular, Emulsifiable Concentrate, Suspension Concentrate Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Corteva Agriscience, Syngenta Group, UPL Limited, Gharda Chemicals Ltd, BASF SE, Bayer AG, FMC Corporation, Rallis India Limited, PI Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Herbicide Market Trends and Innovations
Herbicide markets are pivoting toward precision application technologies and residue-compliant formulations as regulatory scrutiny intensifies and labor economics shift weeding decisions toward chemical intervention timing.
Drone-mounted electrostatic sprayers are overtaking conventional knapsack and tractor-mounted boom systems in large contiguous cotton and soybean holdings. Progressive farmers in Gujarat's Kheda and Bharuch districts are adopting swarm-drone fleets for night-time application during dew-heavy windows. This hardware shift is compressing labor requirements while enabling variable-rate herbicide deposition that reduces active ingredient loading per hectare.
FSSAI residue limit notifications under the Food Safety and Standards Act are forcing reformulation toward lower-dose sulfonylurea and aryloxyphenoxypropionate chemistries in wheat and rice systems. Molecule registrations now require exhaustive groundwater leaching studies before CDSCO approval, extending development timelines. Export-oriented basmati rice processors in Haryana's Karnal and Panipat belts are demanding certified residue-free sourcing, pushing herbicide selection toward pre-harvest interval-compliant products.
Farmer buying committees in Maharashtra's Vidarbha region are consolidating procurement through cooperative-level tendering, disintermediating traditional distributor networks. These aggregations negotiate volume-based pricing directly with technical manufacturers, compressing margin pools for regional formulation packagers. Digital soil testing and weed identification apps are accelerating product selection decisions, shifting influence from retail counter recommendations toward algorithm-driven prescription models in smartphone-penetrated districts.
India Herbicide Market Segmentation
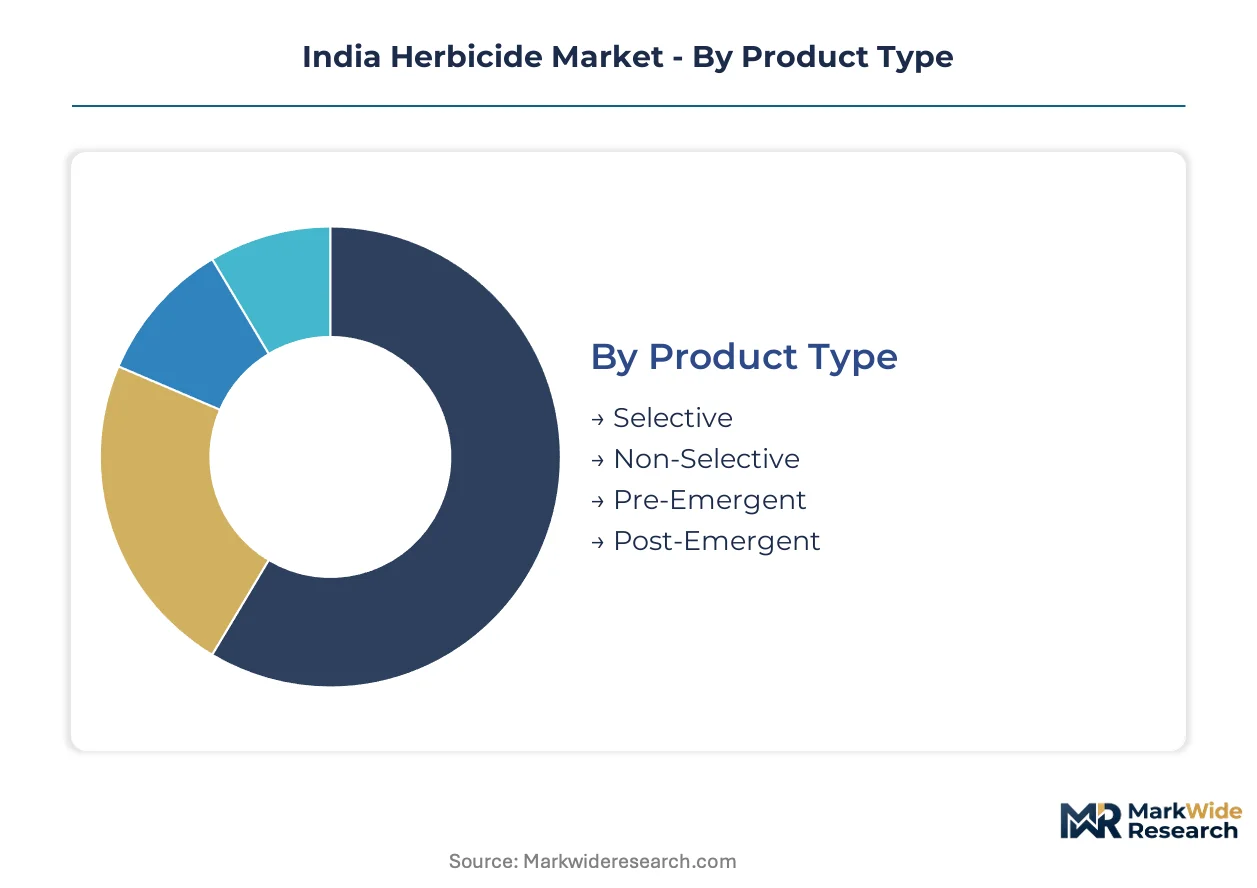
Herbicide procurement decisions in India pivot on crop rotation compatibility, labor cost economics, and residue compliance requirements. Segmentation reveals where formulation investments concentrate and which distribution pathways are disintermediating.
Product Type:
Farmers weigh selectivity against tillage economics when choosing chemistries for India's cereal-pulse rotations and zero-tillage systems.
- Selective:These chemistries target specific weed families while sparing crop plants through enzymatic pathway differences. Demand concentrates in Punjab and Haryana wheat-rice systems where farmers need grass control without injuring cereals. FSSAI residue limits are pushing reformulation toward lower-dose sulfonylurea variants.
- Non-Selective:Broad-spectrum agents destroy all vegetation through systemic action, requiring precise application timing. Zero-tillage wheat and direct-seeded rice protocols in Indo-Gangetic plains are expanding glyphosate and paraquat volumes before planting windows.
- Pre-Emergent:Applied before crop emergence to form soil-active barriers against germinating weeds. Usage persists in irrigated cotton belts where moisture activation can be timed reliably.
- Post-Emergent:Contact or systemic action on emerged weeds during critical crop growth stages. Maharashtra and Gujarat Bt cotton farmers are accelerating adoption as manual weeding labor costs escalate.
Volume sits with Selective chemistries compatible with India's dominant cereal systems; growth tilts toward Post-Emergent applications as labor economics shift weeding decisions to timed spray interventions.
Crop Type:
Herbicide intensity correlates with cash crop value and export orientation, driving premium formulation demand.
- Cereals:Wheat and rice rotations dominate absolute consumption volume across Indo-Gangetic plains. Sulfonylurea-tolerant hybrid rice systems are displacing traditional hand-weeding in eastern Uttar Pradesh and Bihar.
- Pulses:Lentil and chickpea cultivation requires careful selectivity to avoid crop injury from broadleaf herbicides. Adoption lags cereals due to lower farmgate prices and thinner input budgets.
- Vegetables:Tomato, onion, and potato growers in Nashik and Indore belts demand residue-compliant pre-harvest interval products for domestic and export market access. Biological-herbicide combinations are penetrating this segment fastest.
- Fruits:Grape and pomegranate orchards in Maharashtra's Sangli and Nashik districts command premium pricing for certified residue-free sourcing. Export processors mandate third-party validated herbicide protocols.
Cereals anchor absolute volume; Vegetables and Fruits are climbing the fastest as export-oriented basmati rice processors and horticulture exporters enforce residue compliance.
Formulation:
Application equipment compatibility and storage stability determine farmer preference across India's fragmented landholding structure.
- Liquid:Ready-to-use solutions eliminate mixing errors for smallholder farmers with limited technical training. Penetration concentrates in Andhra Pradesh and Telangana where knapsack sprayer ownership is highest.
- Granular:Slow-release formulations reduce application frequency in labor-constrained settings. Usage persists in tea and coffee plantations of Karnataka and Tamil Nadu where terrain limits spray access.
- Emulsifiable Concentrate:Oil-based systems requiring dilution before application, offering extended residual activity. Dominates in large contiguous cotton and soybean holdings where tractor-mounted boom sprayers operate.
- Suspension Concentrate:Water-based formulations with reduced phytotoxicity risk and improved stability. Technical talent for development concentrates in Mumbai-Pune and Hyderabad clusters, creating supply bottlenecks for northern manufacturers.
Emulsifiable Concentrate formulations retain volume leadership in mechanized belts; Suspension Concentrate is gaining share fastest as residue compliance and storage stability requirements intensify.
Distribution Channel:
Procurement pathway selection reflects farm size, credit access, and digital penetration variation across state boundaries.
- Wholesale:Mandi-based bulk purchasing through commission agents and cooperative societies. Maharashtra's Vidarbha farmer buying committees are consolidating procurement through tender-based aggregation, compressing margins for regional packagers.
- Retail:Counter sales through village-level agro-dealer networks with credit extension and technical advice. UPL Limited and domestic formulation players anchor presence through deep tier-three town penetration.
- Online:Direct-to-retailer digital procurement platforms disintermediating traditional supply chains. Penetration accelerates in smartphone-saturated districts of Andhra Pradesh and Telangana.
- Direct Sales:Manufacturer-to-farmer contracting for bulk volume with technical support bundling. Emerging in contract farming arrangements for export-oriented basmati rice and grape cultivation.
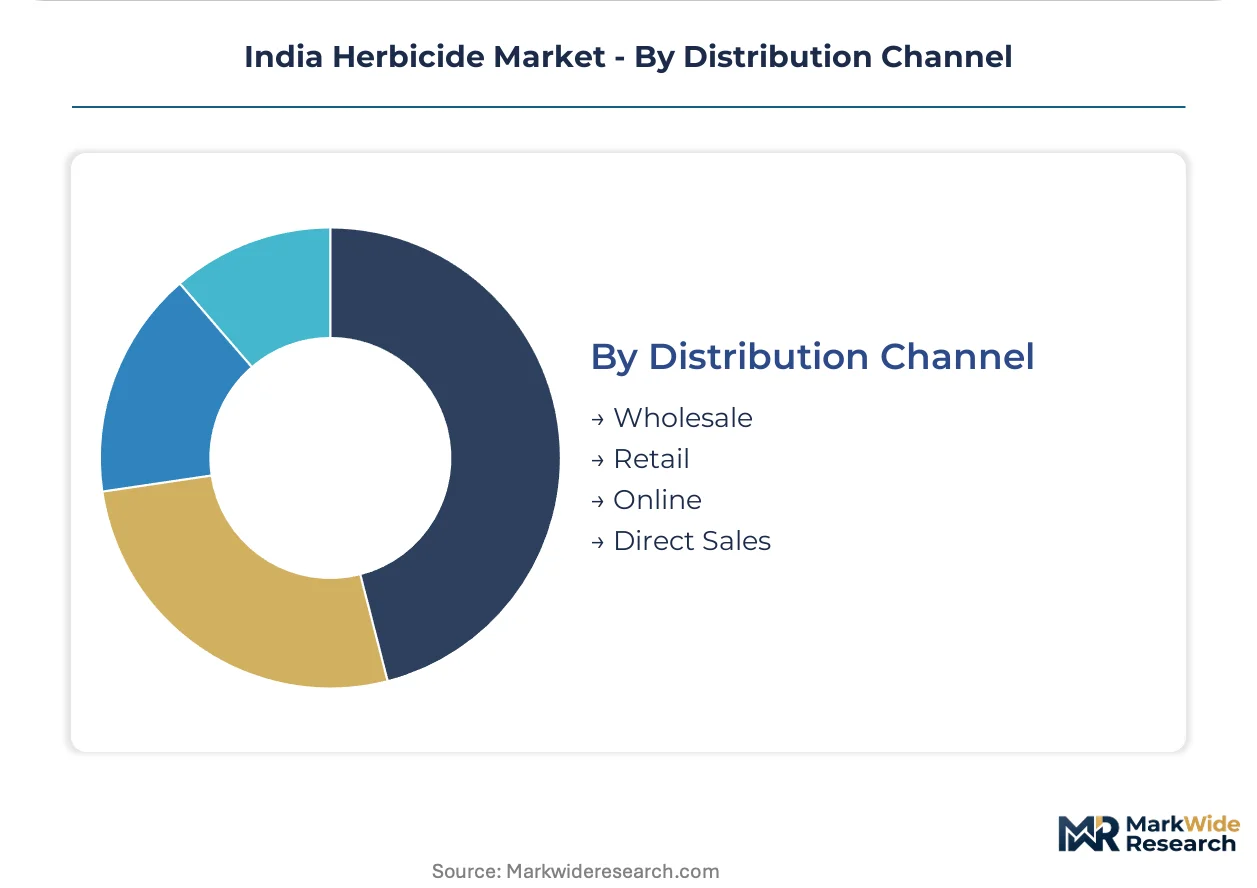
Retail maintains volume dominance through credit relationships; Online channels are expanding most quickly as digital soil testing and weed identification apps shift product selection influence from counter recommendations to algorithm-driven prescriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones under the PLI scheme for agrochemicals are concentrating technical-grade manufacturing capacity in designated clusters across India's western and northern agricultural belts.
Maharashtra
Bt cotton acreage intensification in Vidarbha and Marathwada is hardening post-emergent selective herbicide demand. FSSAI residue limit enforcement is forcing reformulation investments among Nashik-based grape processors. Mumbai-Pune formulation clusters are anchoring suspension concentrate development for export-oriented horticulture.
Gujarat
Zero-tillage wheat protocols in Kheda and Bharuch districts are expanding non-selective herbicide application windows. CEA guidelines for aerial spraying near water bodies are creating certified drone service provider niches. Ahmedabad-Vadodara industrial corridors are drawing PLI-subsidized glyphosate technical manufacturing capacity.
Punjab
Direct-seeded rice systems in Ludhiana and Amritsar belts are displacing traditional puddled transplanting, elevating pre-plant glyphosate volumes. State-level groundwater extraction bans are compressing herbicide runoff dilution capacity near canal networks. Sulfonylurea-tolerant hybrid rice adoption is accelerating in Ferozepur and Bathinda districts.
Haryana
Export-oriented basmati rice processors in Karnal and Panipat are mandating certified residue-free sourcing protocols. BIS maximum residue limits under the Food Safety and Standards Act are tightening atrazine and 2,4-D thresholds for grain shipments. Yamuna canal-irrigated belts are experiencing elevated environmental compliance costs for power sprayer operations.
Andhra Pradesh and Telangana
Knapsack sprayer ownership concentration in Guntur and Warangal districts is sustaining liquid formulation preference. Direct-to-retailer digital procurement platforms are disintermediating traditional mandi-based supply chains. Farmer buying committees are consolidating tender-based procurement directly with technical manufacturers.
India Herbicide Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated technical producers commanding margin pools that formulation-only packagers cannot access. The vendor base organizes around three archetypes: multinational agrochemical majors with captive R&D pipelines, domestic integrated players with backward technical manufacturing, and regional formulation specialists dependent on imported active ingredients. Consolidation pressure is intensifying as PLI scheme incentives reward capital-intensive technical-grade investments, while digital procurement platforms erode traditional distributor margins.
Among multinational agrochemical majors, Corteva Agriscience, Syngenta Group, and UPL Limited occupy positions exemplifying distinct competitive vectors. Corteva represents R&D-intensive patent-protected chemistry development, particularly in hybrid rice tolerance systems. Syngenta sits within the biological-synthetic combination tier, targeting export-oriented fruit and vegetable segments with integrated crop protection portfolios. UPL anchors the domestic backward integration archetype, leveraging technical manufacturing scale and deep tier-three distribution penetration to compress procurement costs for smallholder farmers.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Syngenta Group |
| UPL Limited |
| Gharda Chemicals Ltd |
| BASF SE |
| Bayer AG |
| FMC Corporation |
| Rallis India Limited |
| PI Industries |
| Others |
Pricing and Supply Chain Analysis
Export-oriented basmati rice processors in Haryana and Punjab anchor procurement power through certified residue-free sourcing mandates, compressing margin pools for formulation-only packagers while rewarding integrated technical manufacturers with premium positioning. This buyer concentration feeds into a contract-based long-term offtake model where volume commitments trade against price stability and compliance guarantees.
Pricing Analysis
Short lead-time premiums dominate spot procurement for glyphosate technical amid port congestion vulnerability, while annual contract discounts anchor strategic relationships between Maharashtra cotton cooperatives and integrated manufacturers. Price differentiation rests on FSSAI residue certification tiers and backward integration status, with formulation-only players facing cost compression from Chinese intermediate price volatility. Smallholder farmers in Vidarbha exhibit highest price sensitivity, whereas export grape processors in Nashik absorb premium positioning for third-party validated protocols.
Supply Chain Analysis
BIS technical-grade manufacturing certification gates entry for domestic active ingredient production, concentrating supply among PLI-subsidized facilities in Gujarat and Maharashtra industrial corridors. Raw material dependencies draw from Chinese paraquat intermediates, Indian 2,4-D acid production, and imported sulfonylurea technicals. Single-source vulnerability around Chinese glyphosate intermediates elevates supply risk during diplomatic friction. Distribution runs through mandi-based wholesale networks in northern belts, with digital platforms disintermediating traditional channels in Andhra Pradesh and Telangana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical-grade manufacturing capacity scarcity props pricing power for integrated producers, as PLI scheme absorption rates lag formulation demand expansion across India's cotton and rice belts.
For Market Incumbents: Anchor technical manufacturing scale in Ahmedabad-Vadodara and Mumbai-Pune clusters to defend against Chinese import price volatility. Deepen captive supply of glyphosate and 2,4-D active ingredients through PLI-subsidized capacity additions. Lock long-term offtake contracts with Maharashtra cotton cooperatives before digital procurement platforms erode distributor margins.
For New Entrants and Emerging Players: Export-oriented grape and pomegranate growers in Sangli and Nashik represent the most penetrable buyer archetype, with biological-herbicide combination demand outpacing incumbent supply. Target drone application service provision in Gujarat canal-irrigated belts where CEA certification creates qualified provider scarcity. Launch direct-to-retailer digital procurement in Warangal and Guntur districts, bypassing mandi intermediaries with algorithm-driven prescription bundling.
For Investors and Strategic Acquirers: The window for entry favors domestic integrated players with captive technical manufacturing and FSSAI pre-certified residue protocols. Acquisition targets should command formulation development talent in suspension concentrate and oil dispersion systems. Watch CDSCO registration timeline compression as the inflection signal for pipeline commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Manufacturing | PLI scheme subsidies compress cost position versus Chinese import-dependent competitors. |
| Biological-Herbicide Combination Development | FSSAI residue limits in Nashik grape belts reward reduced-dose synthetic positioning. |
| Drone Application Service Certification | CEA aerial spraying guidelines near water bodies create qualified provider scarcity in Gujarat. |
| Direct-to-Retailer Digital Platform Launch | Smartphone penetration in Andhra Pradesh enables algorithm-driven prescription disintermediation. |
| Suspension Concentrate Formulation Investment | Technical talent concentration in Mumbai-Pune clusters creates recruitment bottlenecks for northern competitors. |
Research Methodology
Multi-period observation of CDSCO registration timelines, PLI scheme absorption rates, and state-level groundwater extraction policy shifts anchored the trend analysis, supplemented by interviews with agrochemical plant managers, FSSAI compliance officers, cotton cooperative procurement leads, and mandi commission agents. Secondary validation drew from BIS residue limit notifications, DGFT import data, state agricultural department acreage reports, and CDSCO molecule approval databases. Bottom-up volume modeling across crop-type segments triangulated against top-down technical manufacturing capacity assessments.
Segment-weighting across product type, crop application, formulation chemistry, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories against cotton acreage expansion, labor cost escalation, and zero-tillage protocol adoption rates. Forecast inputs incorporated FSSAI enforcement intensity indices and PLI scheme disbursement velocity assumptions.
Revisions become necessary when Chinese intermediate supply disruptions, state-level groundwater extraction ban extensions, or CDSCO regulatory acceleration materialize beyond baseline assumptions. A model refresh is warranted upon material change in PLI scheme technical manufacturing absorption rates or FSSAI residue limit notification frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
South America Fungicide Market
Crop Protection
Iprodione Market
Crop Protection
IPM Pheromones Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Grain Fumigants Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Metamifop Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Europe Insecticides Market
Crop Protection
US Herbicide Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Phytogenic Poultry Feed Additives Market