
 Fruit and Vegetable Crop Protection Market | 2026-2036
Fruit and Vegetable Crop Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable Crop Protection Market Foresight
Agricultural cooperative procurement networks are reshaping how crop protection reaches fruit and vegetable growers across fragmented landholdings. BASF SE leverages its biologicals portfolio to anchor shelf space in European horticultural supply chains. Syngenta International AG competes through integrated seed-and-chemistry bundles that reduce per-acre decision complexity for apple and grape producers. FMC Corporation specializes in precision application technologies that extend its reach into greenhouse operations where labor costs pressure manual spraying economics.
Fruit and vegetable crop protection encompasses chemical, biological, and integrated pest management formulations designed to control arthropod pests, fungal pathogens, weeds, bacteria, and nematodes in high-value edible crops, with active ingredient concentrations typically calibrated to pre-harvest interval requirements and maximum residue limits set by importing jurisdictions. The primary commercial purpose centers on yield preservation and post-harvest quality maintenance in production systems where cosmetic standards determine marketability and export eligibility. Fungicides occupy the largest margin pool in orchards and vineyards where perennial cropping cycles amplify disease pressure across successive growing seasons. Biological insecticides represent the fastest-expanding product category as commercial growers face residue restrictions from European retail chains and Japanese import protocols. Greenhouse applications command premium formulation prices due to confined-space operator exposure limits and pollinator proximity concerns that restrict conventional chemistry options.
The EPA regulates pesticide registration and tolerance establishment under FIFRA and the Federal Food, Drug, and Cosmetic Act, while the EU Green Deal and Farm to Fork Strategy mandate 50% synthetic pesticide reduction targets that redirect R&D investment toward microbial and biochemical alternatives. REACH and residue monitoring protocols in Germany and the Netherlands create compliance thresholds that filter supplier participation in premium export channels. Stakeholders must monitor evolving MRL harmonization between Codex Alimentarius standards and unilateral national restrictions that threaten containerized shipment acceptance at destination ports.
Market Dynamics
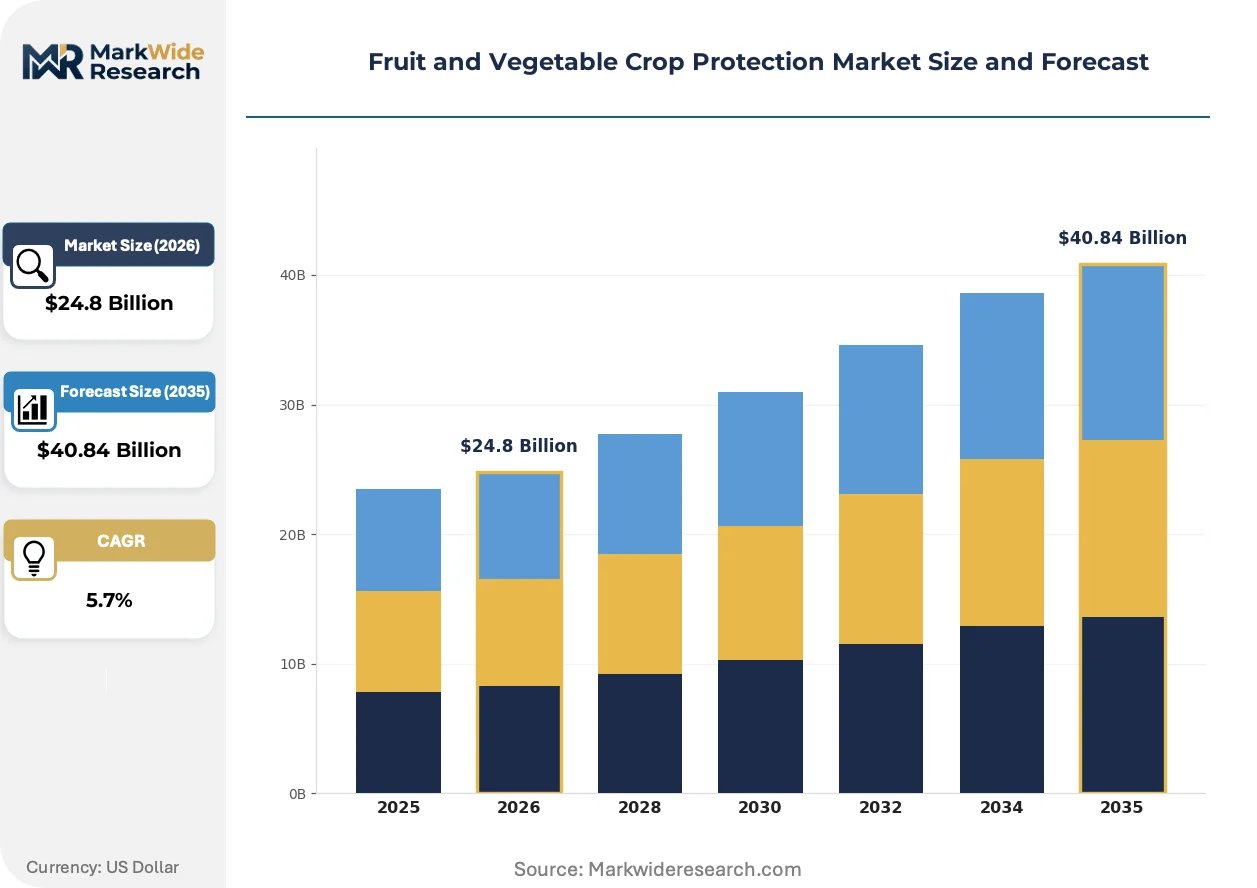
Biological pesticide registration acceleration under EPA and EU Green Deal mandates is restructuring competitive positioning, forcing incumbents to reallocate R&D budgets from synthetic chemistry portfolios toward microbial fermentation capacity and biochemical extraction infrastructure.
Growth Catalysts
- EU Farm to Fork pesticide reduction targets:The 50% synthetic pesticide reduction mandate redirects procurement toward microbial alternatives, expanding addressable market for biocontrol suppliers in German and Dutch export channels.
- Neonicotinoid restrictions in California:EPA cancellation orders on clothianidin and thiamethoxam for citrus and cotton eliminate conventional chemistry options, forcing Central Valley growers toward Bacillus thuringiensis and spinosad formulations.
- Greenhouse vegetable expansion:Protected cultivation acreage growth in Almeria and the Netherlands creates concentrated demand for low-residue, pollinator-compatible protection products with premium formulation economics.
Market Restraints
- Active ingredient supply concentration:Chinese manufacturers control 60-70% of technical-grade synthetic active ingredient production, exposing formulators to tariff volatility and shipping disruption risks.
- Biological product storage limitations:Microbial formulations require cold chain infrastructure and shortened shelf lives that constrain distribution radius and inventory holding periods.
- Registration timeline costs:EPA FIFRA registration processes extend 3-5 years for novel active ingredients, compressing effective patent protection windows and elevating capital recovery thresholds.
Strategic Opportunities
- Precision application technology convergence:Integration of drone-based variable-rate spraying with real-time pest monitoring sensors enables per-plant treatment protocols that reduce input volumes 30-40% versus broadcast methods.
- Brazilian citrus belt biological penetration:São Paulo state resistance management protocols and export MRL alignment with European retail chains create adoption pull for microbial fungicides and insecticides in orange and sugarcane systems.
- Direct-to-grower digital platforms:E-procurement channels bypass traditional agricultural cooperative markups, capturing margin compression value through subscription-based agronomic advisory bundles.
Industry Challenges
- Biological formulation technical talent scarcity:Fermentation scale-up expertise and microbial stability science capabilities concentrate in limited academic and industrial centers, constraining product pipeline velocity.
- MRL harmonization complexity:Unilateral national residue limits in Japan, South Korea, and Switzerland frequently diverge from Codex Alimentarius standards, forcing parallel registration strategies and label differentiation.
- Integrated pest management certification integration:GLOBALG.A.P. and Rainforest Alliance audit requirements demand documentation systems that smallholder cooperatives struggle to implement without third-party service support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable Crop Protection Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Herbicides, Bactericides, Nematicides Application: Orchards, Vineyards, Greenhouses, Open Fields End User: Commercial Growers, Small-scale Producers, Contract Farmers, Horticulturists Distribution Channel: Direct Sales, Agrochemical Retailers, Online Platforms, Cooperatives |
| Companies Covered | Adama Agricultural Solutions Ltd., BASF SE, Bayer Cropscience AG, Corteva Agriscience, Syngenta International AG, FMC Corporation, UPL Limited, Nufarm Limited, Sumitomo Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable Crop Protection Market Shifts & Advancements
RNA interference technology and precision biological delivery systems are compressing the efficacy gap between conventional chemistry and microbial alternatives, while regulatory data requirements and residue monitoring protocols intensify formulation complexity thresholds.
RNA interference crop protection is collapsing the historical performance differential between biological and synthetic insecticides. Greenhouse tomato and pepper operators in the Netherlands and Spain are piloting sprayable dsRNA formulations against whitefly and thrips at commercial scale. Bayer and Syngenta pipeline investments signal this technology is collapsing resistance management timelines from multi-year rotation cycles toward single-season trait deployment.
EU REACH authorization amendments and residue monitoring expansion in Germany are tightening metabolite assessment requirements for existing active ingredients. The industrial consequence elevates analytical chemistry and environmental fate study costs for registration maintenance. Ornamental and minor crop segments face disproportionate pressure as data cost recovery per hectare becomes economically unviable, consolidating supply toward major horticultural crops.
Retail chain residue specification enforcement is restructuring procurement authority toward centralized technical buyers. European supermarket groups and Japanese trading houses now mandate pre-shipment third-party residue testing, displacing traditional spot-check protocols at destination ports. This shift concentrates supplier qualification power in Rotterdam and Yokohama-based import inspection networks, filtering participant pools by analytical documentation capability rather than price alone.
Fruit and Vegetable Crop Protection Market Segmentation
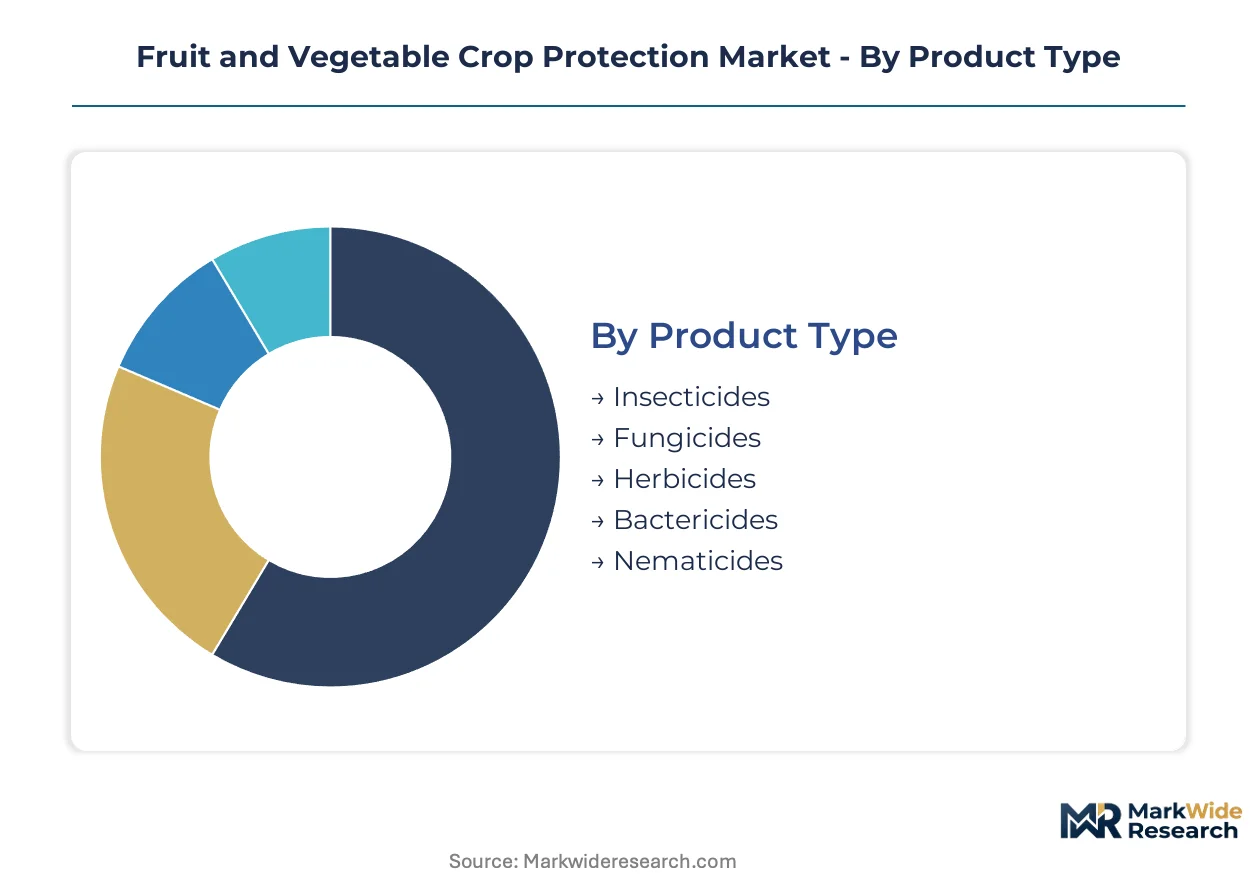
Fruit and vegetable crop protection segments diverge sharply by residue tolerance thresholds and application infrastructure requirements. Biological alternatives command premium positioning in greenhouse and export-oriented systems where MRL compliance determines market access.
Product Type:
Cost tier differentiation separates commodity synthetic chemistry from precision biological formulations with extended development timelines.
- Insecticides:Formulations targeting lepidopteran and hemipteran pests in high-value orchards face neonicotinoid substitution pressure. California citrus operators pivot toward Bacillus thuringiensis and spinosad as EPA cancellation orders eliminate clothianidin access.
- Fungicides:Perennial cropping systems in vineyards and tree fruit operations generate recurring disease pressure across multiple growing seasons. Botrytis and powdery mildew management in European grape production sustains margin concentration in strobilurin and SDHI chemistry segments.
- Herbicides:Row crop vegetable systems rely on pre-emergent and post-emergent weed control with narrow selectivity windows.
- Bactericides:Copper-based and antibiotic formulations address fire blight and bacterial spot in pome and stone fruit.
- Nematicides:Soil-applied fumigants and biological antagonists target root-knot nematode pressure in protected vegetable cultivation.
Fungicides hold installed capacity. Nematicides are rotating up the share rankings.
Application:
Application environment dictates formulation specifications for operator exposure limits and pollinator proximity constraints.
- Orchards:Aerial and ground-based spraying of tree fruit systems requires drift mitigation technologies and extended pre-harvest intervals. Washington apple and Italian pear producers anchor demand for mating disruption and reduced-risk insecticide rotations.
- Greenhouses:Confined-space cultivation in Almeria and the Netherlands mandates low-residue, pollinator-compatible products with premium unit economics. Biological insecticides and microbial fungicides dominate tomato, pepper, and cucumber protection protocols.
- Vineyards:Fungicide resistance management in French and Italian wine grape regions drives multi-site chemistry rotations.
- Open Fields:Scale vegetable operations in California and São Paulo state rely on broadcast application equipment with volume-based pricing.
Orchards hold installed capacity. Greenhouses are climbing the fastest.
End User:
Customer type determines procurement authority concentration and technical advisory requirements.
- Commercial Growers:Large-scale operations with centralized agronomic decision-making negotiate direct manufacturer relationships and volume-based pricing. Brazilian orange producers and California lettuce operators qualify for technical service bundling and early-access biological formulations.
- Contract Farmers:Supply chain integration with processor and exporter specifications mandates residue documentation systems and GLOBALG.A.P. certification compliance.
- Small-scale Producers:Fragmented landholdings depend on cooperative procurement networks and retailer credit programs for input access.
- Horticulturists:Specialty ornamental and nursery operations prioritize aesthetic quality standards over yield metrics.
Commercial growers hold installed capacity. Contract farmers are rotating up the share rankings.
Distribution Channel:
Supply concentration varies from direct manufacturer relationships to fragmented retail networks with regional coverage gaps.
- Agrochemical Retailers:Independent and branded retail networks dominate last-mile distribution in North American and European agricultural regions. Storefront locations in California's Central Valley and São Paulo's citrus belt maintain inventory depth for immediate grower demand.
- Direct Sales:Manufacturer field representatives serve large commercial accounts with customized agronomic programs and application equipment integration.
- Cooperatives:Member-owned purchasing organizations aggregate smallholder demand for price negotiation and technical training delivery.
- Online Platforms:E-procurement channels bypass traditional markups through subscription advisory bundles and digital scouting tools.
Agrochemical retailers hold installed capacity. Online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Brazilian citrus protection formulations runs 15-20% above equivalent products in Indian vegetable markets, reflecting export MRL compliance premiums and supply chain reliability differentials between the two production systems.
United States
California Central Valley specialty crop growers drive biological pesticide demand as EPA cancellation orders on clothianidin and thiamethoxam eliminate conventional chemistry options. The Federal Insecticide, Fungicide, and Rodenticide Act registration timelines extend 3-5 years for novel active ingredients. Fresno County and Kern County anchor adoption of Bacillus thuringiensis and spinosad formulations in citrus and lettuce operations.
Brazil
São Paulo state citrus belt generates concentrated demand for resistance management protocols and export-aligned MRL compliance in orange and sugarcane systems. ANVISA pesticide registration acceleration supports microbial fungicide penetration. The Ribeirão Preto and Araraquara regions concentrate formulation complexity requirements for European retail chain supply integration.
Germany
REACH authorization amendments and residue monitoring expansion tighten metabolite assessment requirements for existing active ingredients. The EU Green Deal 50% synthetic pesticide reduction mandate redirects procurement toward microbial alternatives. The Lower Rhine and Bavarian vegetable production clusters anchor demand for low-residue greenhouse protection products.
Netherlands
Protected cultivation acreage growth in Westland and Almeria creates concentrated demand for pollinator-compatible biological formulations with premium unit economics. EU Farm to Fork Strategy compliance requirements filter supplier participation through analytical documentation capability thresholds. Wageningen University research partnerships accelerate precision application technology convergence.
China
Technical-grade synthetic active ingredient production concentration exposes formulators to tariff volatility and shipping disruption risks. The Ministry of Ecology and Environment dual carbon goals redirect domestic R&D toward biochemical alternatives. Shandong and Jiangsu provinces anchor manufacturing capacity for export-oriented formulators serving Brazilian and Southeast Asian markets.
Fruit and Vegetable Crop Protection Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower formulation portfolios. The vendor base concentrates around integrated seed-and-chemistry bundlers, precision application technology providers, and microbial fermentation capacity builders. Three archetypes dominate: diversified agrochemical conglomerates with biologicals portfolios, mid-scale specialists in greenhouse and horticultural segments, and generic manufacturers with cost-positioned synthetic chemistry. Competitive moves center on microbial fermentation capacity expansion and direct-to-grower digital platform development.
Within the diversified conglomerate tier, BASF SE and Syngenta International AG occupy positions anchored by integrated supply chain control and seed-chemistry bundling capabilities. FMC Corporation exemplifies the precision application specialist archetype, sitting within the technology convergence segment where drone-based variable-rate spraying meets real-time pest monitoring. Bayer Cropscience AG represents the research-intensive platform model with RNA interference pipeline investments signaling technology transition.
| Leading Market Players |
|---|
| Adama Agricultural Solutions Ltd. |
| BASF SE |
| Bayer Cropscience AG |
| Corteva Agriscience |
| Syngenta International AG |
| FMC Corporation |
| UPL Limited |
| Nufarm Limited |
| Sumitomo Chemical Co. Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese technical-grade active ingredient manufacturing is compressing margins for downstream formulators while simultaneously creating procurement leverage for large-scale growers in Brazil and California. This utilization imbalance forces suppliers toward premium biological formulations to escape commodity pricing traps, reshaping how protection products reach fruit and vegetable operations across fragmented landholdings.
Pricing Analysis
The customization-premium spread separates standard synthetic chemistry from precision biological formulations with extended development timelines. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by MRL certification grade and after-sales agronomic advisory bundling. Cost compression in commodity insecticide tiers is intensifying because Chinese manufacturers flood export channels with generic technical-grade inputs. Small-scale producers remain most price-sensitive, while greenhouse operators in the Netherlands and Almeria absorb premium pricing for pollinator-compatible formulations.
Supply Chain Analysis
Upstream feedstock concentration in Shandong and Jiangsu provinces anchors global technical-grade synthetic active ingredient availability. The supply chain draws from Chinese fermentation capacity, Indian biochemical extraction infrastructure, and European microbial formulation expertise. Single-source vulnerability in Chinese technical-grade production exposes formulators to tariff volatility and shipping disruption risks. Distribution runs through agricultural cooperative networks in fragmented landholding regions and direct manufacturer relationships for large commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as agricultural cooperatives aggregate fragmented smallholder demand and retail chains impose residue documentation requirements that filter supplier pools. This consolidation shifts procurement authority toward centralized technical buyers capable of mandating pre-shipment testing protocols.
For Market Incumbents: Build biological formulation moats through microbial fermentation capacity expansion in São Paulo state and the Lower Rhine corridor. Anchor shelf space via integrated seed-and-chemistry bundles that reduce per-acre decision complexity for apple and grape producers. Defend against RNA interference technology disruption by accelerating precision application technology convergence with drone-based variable-rate spraying platforms. For New Entrants and Emerging Players: Southeast Asian greenhouse vegetable markets offer underpenetrated white-space for low-residue biological formulations with premium unit economics. Direct-to-grower digital platforms bypass traditional cooperative markups through subscription-based agronomic advisory bundles. Target contract farmer segments in India's fragmented vegetable belt with GLOBALG.A.P. certification support services bundled with input procurement. For Investors and Strategic Acquirers: Capital is best deployed toward precision application technology specialists with drone-based variable-rate spraying capabilities and real-time pest monitoring sensor integration. Long-term viability hinges on microbial fermentation scale-up expertise scarcity constraining product pipeline velocity. Watch EPA biological pesticide registration acceleration timelines as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Fermentation Capacity Expansion | Builds captive supply of Bacillus thuringiensis and spinosad alternatives for California citrus operators facing neonicotinoid cancellations. |
| Precision Application Technology Convergence | Integrates drone-based variable-rate spraying with real-time pest monitoring sensors for per-plant treatment protocols in Almeria greenhouses. |
| Direct-to-Grower Digital Platform Development | Bypasses agricultural cooperative markups through subscription-based agronomic advisory bundles with digital scouting tools. |
| EU MRL Compliance Certification Investment | Qualifies suppliers for European retail chain procurement networks in Rotterdam and Yokohama-based import inspection systems. |
| RNA Interference Pipeline Advancement | Collapses resistance management timelines from multi-year rotation cycles toward single-season trait deployment for Bayer and Syngenta. |
Research Methodology
A standing panel of crop protection R&D directors, agricultural cooperative procurement managers, greenhouse operations supervisors, and EPA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA FIFRA registration databases, EU EFSA residue monitoring protocols, ANVISA pesticide filings, and customs trade data for technical-grade active ingredient flows. Bottom-up acreage and application-rate modeling triangulated against top-down manufacturer revenue segmentation.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, application environment, end-user scale, and distribution channel concentration. CAGRs derived from fitted growth curves applied to acreage expansion rates, biological adoption penetration curves, and regulatory-driven substitution elasticities. Forecast inputs incorporated EU Farm to Fork synthetic pesticide reduction mandates and EPA cancellation order implementation timelines.
Practitioners should monitor EPA biological registration acceleration timelines, EU REACH metabolite assessment amendments, and Japanese unilateral MRL divergence from Codex Alimentarius standards for early signals of forecast revision. Cross-checking against Bayer and Syngenta pipeline disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
India Herbicide Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Global Algaecides Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Pest Control Products Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Nematicides Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Europe Seed Treatment Market