
 Asia-Pacific Nematicides Market | 2026-2036
Asia-Pacific Nematicides Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nematicides Market Outlook
Buyer concentration across Asia-Pacific vegetable farming cooperatives is rebalancing as mid-scale commercial growers fragment procurement previously dominated by large estate operations. Corteva Agriscience anchors its position through extensive distribution networks across India and Southeast Asia. Syngenta Group differentiates via integrated seed-treatment-to-soil-application portfolios that capture recurring grower commitments. BASF SE competes through biological nematicide pipelines aligned with tightening residue standards in export-oriented markets.
Nematicides comprise chemical, biological, and natural agents formulated to suppress plant-parasitic nematode populations in agricultural soils, typically applied through soil drenching, drip irrigation, or seed coating at rates calibrated to nematode pressure and crop sensitivity. Their primary commercial purpose centers on protecting root systems to maintain yield integrity in intensive horticulture and field crop systems. Chemical formulations still occupy the dominant revenue position, though biological nematicides represent the fastest-expanding margin pool as residue-conscious buyers in Japan and South Korea shift procurement criteria. Soil treatment applications lead volume deployment, while drip irrigation methods gain traction in water-stressed regions where precision delivery reduces active ingredient requirements.
India's Central Insecticides Board enforces registration requirements that delay new chemical nematicide entry while accelerating biological product approvals. China's Ministry of Agriculture and Rural Affairs applies GB standards that restrict organophosphate-based soil treatments in major vegetable-producing provinces. Australia's TGA and APVMA jointly influence import tolerance benchmarks that shape formulation decisions for export-oriented growers across the region. Stakeholders must monitor how divergent national residue protocols reshape product-portfolio viability across country boundaries.
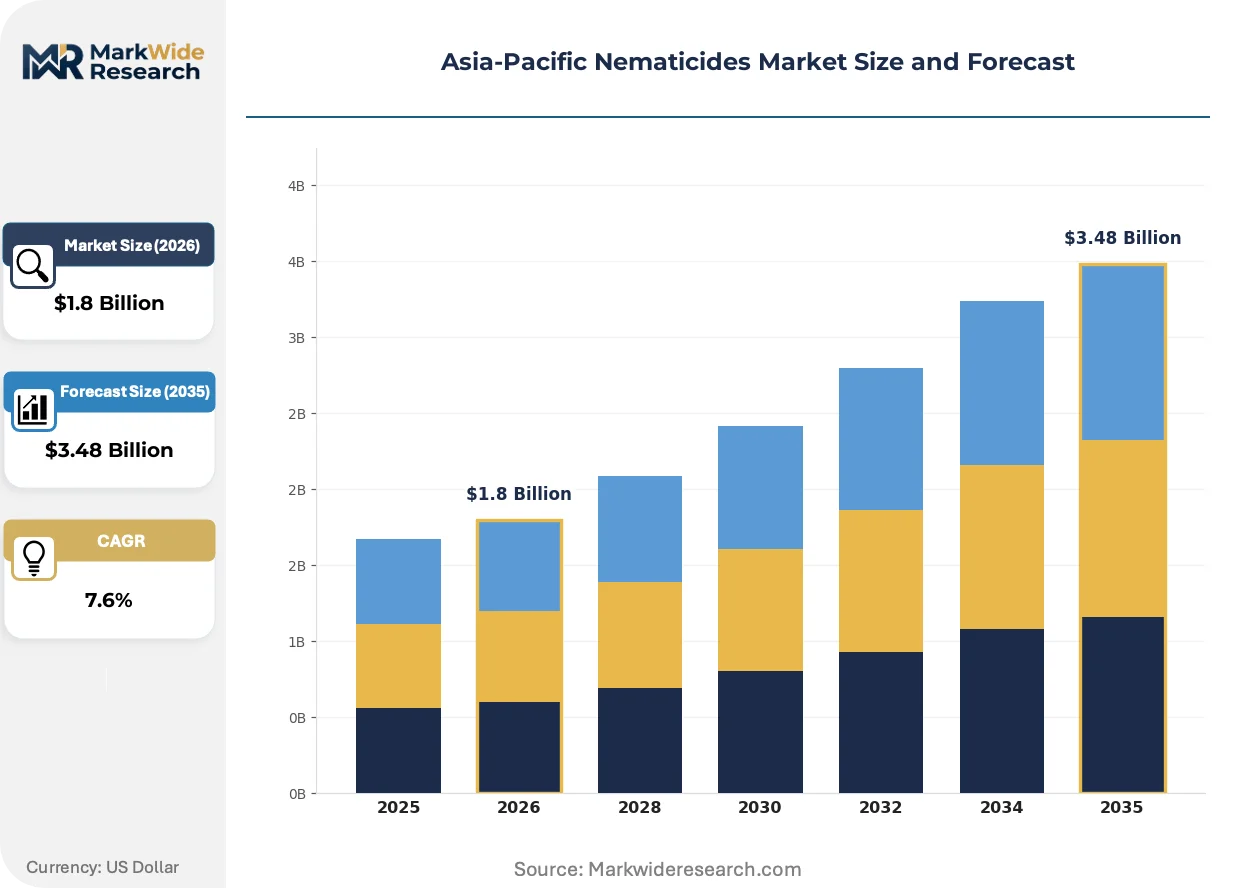
Market Dynamics
India's PLI scheme for agrochemical manufacturing and China's dual carbon goals are redirecting capital toward lower-toxicity biological formulations, fragmenting procurement patterns across vegetable farming cooperatives previously dominated by large estate operations.
Growth Catalysts
- Biological nematicide pipelines:Export-oriented growers in Japan and South Korea are prioritizing residue-compliant biological agents over chemical alternatives to maintain market access in premium destinations.
- India's PLI scheme:Domestic manufacturing incentives are accelerating local production capacity for nematicide active ingredients, reducing import dependency for Gujarat-Maharashtra vegetable belts.
- Precision drip irrigation:Water-stressed regions across Australia's Murray-Darling basin are deploying calibrated nematicide delivery through drip systems, cutting active ingredient volumes per hectare.
Market Restraints
- Registration friction:India's Central Insecticides Board enforces multi-year approval timelines for new chemical nematicides that delay product commercialization against accelerating biological alternatives.
- Input cost volatility:Petrochemical-derived active ingredient prices fluctuate with crude oil benchmarks, compressing margin predictability for formulation manufacturers serving price-sensitive Indian cooperatives.
- Supply concentration:Specialty surfactant and adjuvant production clusters in eastern China create single-source vulnerability for regional formulators dependent on just-in-time ingredient flows.
Strategic Opportunities
- Vietnam's Mekong Delta expansion:Intensive vegetable cultivation zones in this underpenetrated corridor present first-mover potential for integrated seed-treatment-to-soil-application service models.
- Australia's TGA-APVMA alignment:Harmonized residue tolerance benchmarks create formulation standardization opportunities for exporters serving multiple Asia-Pacific destination markets simultaneously.
- Biological-chemical hybrid platforms:Converging fermentation-derived biocontrol agents with reduced-rate chemical carriers addresses performance reliability concerns among risk-averse commercial growers.
Industry Challenges
- Nematology expertise scarcity:Field-level diagnostic capability for species-specific pressure assessment remains concentrated among senior agronomists, limiting precision application adoption among mid-scale cooperatives.
- Biological stability logistics:Temperature-sensitive live-organism formulations require cold-chain infrastructure that fragments distribution economics across Indonesia's archipelago geography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nematicides Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological, Chemical, Synthetic, Natural Crop Type: Fruits, Vegetables, Grains, Pulses Application Method: Soil Treatment, Foliar Spray, Seed Treatment, Drip Irrigation Distribution Channel: Online Retail, Wholesale, Direct Sales, Agricultural Stores |
| Companies Covered | Corteva Agriscience, ADAMA Agricultural Solutions Ltd, Syngenta Group, BASF SE, American Vanguard Corporation, Bayer AG, FMC Corporation, Nufarm, UPL Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nematicides Market Strategic Shifts
Formulation science and application technology are converging to reduce chemical load per hectare while maintaining nematode suppression efficacy, with biological agents capturing margin expansion in residue-sensitive segments.
Microencapsulation technology for abamectin and other high-potency actives is modularizing application flexibility across variable soil moisture conditions. Australian vegetable exporters are adopting these formulations to meet Japan's MRL protocols. The technology is modularizing service bundling opportunities that combine physical delivery hardware with calibrated dosing algorithms.
China's GB standards restricting organophosphate-based soil treatments in Shandong-Henan vegetable corridors are accelerating biological nematicide registration submissions. Formulators are reformulating legacy portfolios to exclude restricted actives ahead of enforcement phase-ins. Biological product pipelines are capturing accelerated approval pathways relative to chemical alternatives under this regulatory framework.
Vegetable farming cooperatives across India are consolidating procurement volumes through regional buying groups that displace individual estate negotiations. These aggregators demand performance guarantees and residue testing documentation that smaller formulators struggle to supply. The consolidation is most visible in Gujarat's potato and tomato belts where export certification requirements concentrate buyer power.
Asia-Pacific Nematicides Market Segmentation
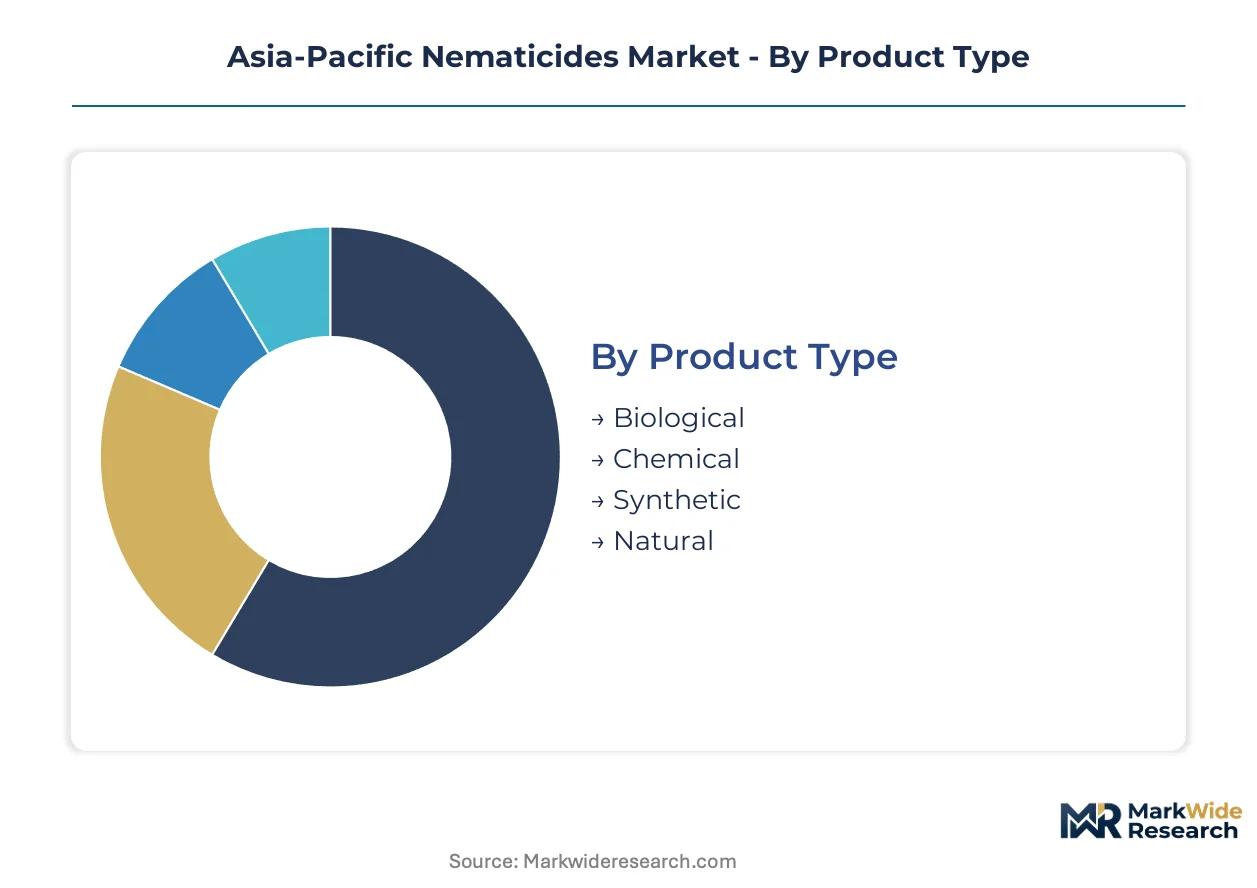
Segmentation across the Asia-Pacific nematicides market reveals distinct procurement patterns shaped by residue compliance requirements, irrigation infrastructure maturity, and cooperative buying power concentration in India's vegetable belts and China's Shandong-Henan corridor.
Product Type:
Biological formulations command premium positioning in export-oriented supply chains while chemical products retain volume dominance across price-sensitive domestic markets.
- Biological:Fermentation-derived biocontrol agents containing live organisms or metabolites suppress nematode populations without synthetic residues. Japan and South Korea's MRL-conscious buyers are consolidating procurement of these formulations to maintain access to premium export destinations. Temperature-sensitive supply chains and cold-chain distribution requirements constrain penetration across Indonesia's archipelago.
- Chemical:Synthetic organic compounds including organophosphates, carbamates, and fumigants deliver rapid nematode mortality through neurotoxic or metabolic disruption mechanisms. India's Gujarat-Maharashtra vegetable belts and China's intensive cultivation zones depend on these cost-effective solutions despite tightening GB standards and Central Insecticides Board registration friction.
- Synthetic:Laboratory-engineered actives with precise molecular targeting occupy mid-tier positioning between biological premiums and commodity chemical volumes. Formulators are reformulating legacy portfolios to exclude restricted actives ahead of enforcement phase-ins.
- Natural:Plant-extracted compounds and mineral-based formulations derived from neem, marigold, or other botanical sources serve organic certification requirements. Australia's export-oriented growers deploy these for TGA-APVMA aligned residue protocols.
Mature deployment sits with Chemical. Newer deployment is concentrated in Biological.
Crop Type:
Root system vulnerability and export certification intensity determine application rates and formulation selection across cropping systems.
- Vegetables:Tomato, potato, carrot, and leafy green cultivation in India's Gujarat-Maharashtra belt and China's Shandong-Henan corridor drives the highest nematicide application intensity per hectare. Intensive monoculture systems create recurring nematode pressure demanding scheduled treatment programs.
- Fruits:Banana, citrus, and pineapple plantations across the Philippines and Vietnam's Mekong Delta deploy soil treatments to protect perennial root systems from Meloidogyne and Radopholus species. Export certification requirements for Japanese and South Korean destinations favor residue-compliant biological formulations.
- Grains:Rice and maize systems apply nematicides selectively where nematode pressure exceeds economic thresholds, with lower per-hectare intensity than horticultural crops. Water management in flooded rice systems partially suppresses nematode populations.
- Pulses:Chickpea, lentil, and soybean cultivation in India's central states faces escalating cyst nematode pressure as pulse acreage expands under crop rotation programs. Biological seed treatments are gaining traction for their compatibility with nitrogen-fixing rhizobia inoculants.
Volume concentration centers on Vegetables. Steepest expansion trajectory is emerging in Pulses.
Application Method:
Precision delivery capabilities and water infrastructure availability fragment adoption patterns across the region's diverse agricultural landscapes.
- Soil Treatment:Pre-planting broadcast or banded application of granules, liquids, or fumigants remains the dominant volume deployment method. India's cooperative buying groups consolidate procurement for this established approach across Gujarat's potato belts.
- Drip Irrigation:Chemigation systems inject calibrated nematicide doses directly to root zones, cutting active ingredient volumes per hectare. Australia's Murray-Darling basin vegetable exporters deploy these systems to meet Japan's stringent MRL protocols while managing water scarcity.
- Seed Treatment:Coating seeds with nematicide-active formulations provides early-season protection with minimal environmental load. Integrated seed-treatment-to-soil-application service models are capturing recurring grower commitments in Vietnam's Mekong Delta expansion zones.
- Foliar Spray:Limited efficacy against soil-dwelling nematodes restricts this method to specific systemic actives with downward translocation properties. Application concentrates in specialty crop segments where alternative methods are impractical.
Established infrastructure supports Soil Treatment. Precision agriculture investment is accelerating Drip Irrigation.
Distribution Channel:
Buyer scale and technical support requirements determine channel selection across fragmented farm structures and consolidating cooperative networks.
- Agricultural Stores:Local input retailers with agronomist staff serve mid-scale commercial growers across India's fragmented landholding patterns. These outlets provide field-level diagnostic support and credit terms that anchor farmer loyalty.
- Wholesale:Regional distributors aggregate volumes for cooperative buying groups displacing individual estate negotiations. Gujarat's potato and tomato belt consolidators demand performance guarantees and residue testing documentation through this channel.
- Direct Sales:Large estate operations and integrated farming companies procure directly from formulators for customized service bundling. Australian vegetable exporters leverage direct relationships for TGA-APVMA aligned formulation standardization.
- Online Retail:E-commerce platforms penetrate remote areas and smallholder segments with standardized product offerings. Cold-chain requirements for biological formulations constrain category expansion through this channel.
Procurement consolidation favors Wholesale. Digital infrastructure investment is expanding Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vegetable cultivation belts across India and China concentrate procurement volumes for nematicide applications, with intensive farming operations in specific sub-regional corridors driving formulation demand and distribution infrastructure investment.
India
Gujarat and Maharashtra vegetable belts deploy the highest nematicide application intensity per hectare for tomato and potato cultivation. The Central Insecticides Board registration requirements favor biological product approvals over chemical alternatives. Cooperative buying groups in these states now consolidate procurement volumes that previously flowed through individual estate channels.
China
Shandong-Henan corridor dominates domestic nematicide consumption for protected vegetable cultivation systems. GB standards restrict organophosphate-based soil treatments, accelerating biological nematicide registration submissions. Formulators in this corridor actively reformulate legacy portfolios to exclude restricted actives ahead of enforcement timelines.
Japan
Export-oriented vegetable growers prioritize residue-compliant biological formulations to maintain access to premium destination markets. METI guidelines and MRL protocols shape procurement criteria for nematicide selection. Precision application adoption concentrates in Kyushu and Hokkaido vegetable production zones where diagnostic capabilities support species-specific treatment programs.
Australia
Murray-Darling basin vegetable exporters deploy drip irrigation chemigation systems to meet Japan's stringent MRL requirements. TGA and APVMA jointly influence residue tolerance benchmarks that determine formulation viability. Direct sales relationships between large estate operations and formulators dominate procurement in this export-focused market.
Vietnam
Mekong Delta intensive vegetable cultivation zones present expansion opportunities for integrated seed-treatment-to-soil-application service models. Biological nematicide penetration remains limited by cold-chain infrastructure gaps across the delta's distributed farming geography. Mid-scale commercial growers in this corridor are consolidating procurement through emerging cooperative structures.
Asia-Pacific Nematicides Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biological formulation specialization and precision delivery service bundling. The market structure reflects moderate consolidation with multinational agrochemical groups anchoring volume positions alongside regional formulators serving price-sensitive domestic channels. Three archetypes dominate: integrated seed-to-soil portfolio providers, biological pipeline specialists, and distribution-heavy incumbents with extensive agronomist networks. Competitive moves center on portfolio diversification toward lower-toxicity formulations and strategic partnerships for cold-chain biological distribution.
Among the integrated portfolio providers, Corteva Agriscience and Syngenta Group exemplify archetypes combining seed treatment capabilities with soil application expertise. BASF SE occupies a position within the biological pipeline specialist tier, with formulation development aligned to tightening residue standards. These three entities represent distinct strategic postures: distribution network depth, recurring grower commitment capture through integrated services, and regulatory-compliant biological innovation respectively.
| Leading Market Players |
|---|
| Corteva Agriscience |
| ADAMA Agricultural Solutions Ltd |
| Syngenta Group |
| BASF SE |
| American Vanguard Corporation |
| Bayer AG |
| FMC Corporation |
| Nufarm |
| UPL Limited |
| Others |
Value Chain & Pricing Dynamics
Cooperative buying group consolidation across India's Gujarat-Maharashtra vegetable belts is forcing formulators to absorb residue testing documentation costs while specialty surfactant dependencies in eastern China amplify input price volatility. This demand-side compression reshapes margin structures and sourcing strategies across the regional value chain.
Pricing Analysis
Volume-margin splits separate commodity chemical nematicides serving price-sensitive domestic markets from biological formulations commanding premium positioning in Japan and South Korea export channels. Three-tier pricing structure across residue-compliant biological, reduced-rate synthetic, and commodity chemical levels reflects certification grade and cold-chain service bundling. Pricing pressure stems from petrochemical feedstock volatility compressing formulation margins. Indian cooperative buyers exhibit highest price sensitivity while Australian estate operators prioritize residue compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialty surfactant and adjuvant production clusters concentrated in eastern China's chemical manufacturing corridors. Active ingredient manufacturing draws from China, India, and limited Japanese fermentation facilities for biological agents. Raw material dependencies include petrochemical-derived organophosphates, fermentation substrates, and cold-chain packaging materials. Tariff exposure on cross-border active ingredient flows compounds procurement risk. Distribution runs through regional wholesale aggregators serving cooperative buying groups, with direct sales channels penetrating Australian export-oriented estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where GB standards in China and Central Insecticides Board registration friction are systematically advantaging capitalized players with biological pipelines and cold-chain infrastructure.
For Market Incumbents: Acquire fermentation-derived biological production capacity to preempt regulatory displacement of legacy chemical portfolios. Corteva Agriscience and Syngenta Group should deepen backward integration into cold-chain distribution networks across Indonesia's archipelago to neutralize temperature-sensitive logistics gaps threatening biological formulation viability. BASF SE's existing biological pipeline positions it to capture margin expansion as residue standards tighten. For New Entrants and Emerging Players: India's PLI scheme for agrochemical manufacturing opens a window for domestic biological nematicide production targeting Gujarat-Maharashtra cooperative procurement consolidation. Vietnam's Mekong Delta vegetable expansion zones offer white-space penetration for integrated seed-treatment-to-soil-application service models. New entrants should anchor go-to-market strategies through agricultural store partnerships providing field-level nematology diagnostic support. For Investors and Strategic Acquirers: The window for entry favors biological pipeline specialists with regulatory approval momentum over chemical legacy assets facing enforcement phase-outs. Long-term viability centers on fermentation technology platforms and precision delivery hardware integration. Watch accelerated biological product approvals under China's GB standards and India's Central Insecticides Board as the inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captures margin pool in biological nematicides as GB standards restrict chemical actives in Shandong-Henan corridors. |
| Cold-Chain Distribution Partnership | Enables biological formulation penetration across Indonesia's archipelago geography where temperature sensitivity fragments economics. |
| Precision Drip Irrigation Service Bundling | Aligns with Australia's Murray-Darling basin water scarcity constraints and Japan's MRL protocol requirements. |
| Cooperative Buying Group Direct Contracting | Secures volume commitments from Gujarat-Maharashtra consolidators displacing individual estate negotiations. |
| Biological-Chemical Hybrid Platform Development | Addresses performance reliability concerns among risk-averse commercial growers in Vietnam's Mekong Delta expansion zones. |
Study Parameters
Document review covered regulatory filings with India's Central Insecticides Board, China's GB standards documentation, and APVMA residue protocols, complemented by interviews with formulation R&D directors, cooperative procurement managers, and cold-chain logistics operators. Secondary sources included customs trade data on active ingredient flows, agrochemical manufacturing capacity disclosures, and vegetable export certification databases. Bottom-up procurement volume estimates from regional buying groups were triangulated against top-down market sizing from production capacity analysis.
Market value and volume outputs across the projection horizon reflect segmented modeling by product type, crop application, and distribution channel with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation of biological approval velocity, cooperative consolidation rates, and precision irrigation adoption curves. Industry-specific inputs included nematode pressure indices from vegetable cultivation intensity metrics and residue tolerance benchmark harmonization progress between TGA and APVMA.
Caveats apply where enforcement timeline shifts for China's GB standards or India's PLI scheme modifications could materially shift the outlook for biological versus chemical formulation competitiveness. Forecasts reflect assumptions on cold-chain infrastructure buildout rates and cooperative buying group consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Global Insecticides Market
Crop Protection
Tebuconazole Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
India Insecticide Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Dicamba Market
Crop Protection
Global Algaecides Market