
 Global Insect Pest Control Market | 2026-2036
Global Insect Pest Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insect Pest Control Market Foresight
Biological control agents derived from Bacillus thuringiensis and entomopathogenic nematodes is realigning product economics away from synthetic pyrethroids and organophosphates. Rentokil Initial plc leverages its service-network density across urban corridors to anchor recurring revenue from commercial building contracts. BASF SE differentiates through microbial formulation R&D, while Syngenta AG competes by extending its seed-treatment expertise into adjacent foliar biological platforms.
Insect pest control encompasses the management, suppression, or elimination of arthropod species that threaten agricultural yield, public health, structural integrity, or food safety through chemical, biological, physical, or integrated intervention protocols; active ingredients typically require EPA or EMA registration with specified LD50 thresholds and environmental fate profiles. Chemical insecticides still dominate value capture in warehouse and residential applications where speed of knockdown commands premium positioning. Biological agents represent the fastest-expanding margin pool, particularly in agricultural fields where export-oriented growers face EU residue limits and North American retailer sustainability audits.
The EPA regulates product registration and label claims under FIFRA in the United States, while the EU Green Deal and REACH framework restrict neonicotinoid deployment and mandate substitution planning across member states. India's Central Insecticides Board enforces phased bans on monocrotophos and diazinon, redirecting formulation investment toward botanical extracts and pheromone traps. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and anticipate which active ingredients will retain multi-country access.
Market Dynamics
The EU F-Gas Regulation and parallel EPA restrictions on neonicotinoids are compressing the synthetic chemistry window while biological formulation R&D accelerates, forcing incumbents to rebuild active ingredient portfolios from microbial foundations.
Growth Catalysts
- Integrated Pest Management Mandates:Brazil's Ministry of Agriculture requires IPM protocols on soybean and corn operations exceeding 500 hectares, expanding biological agent procurement.
- Vector-Borne Disease Expansion:Climate shifts in India and the United States extend malaria and dengue zones, intensifying public health spraying contracts and residual insecticide demand.
- REACH Substitution Planning:The EU Green Deal mandates chemical hazard assessment and substitution roadmaps, redirecting formulation investment toward Bacillus thuringiensis and pheromone platforms.
Market Restraints
- Active Ingredient Concentration:Three Chinese manufacturers supply over 60% of global pyrethroid technical material, creating supply vulnerability during environmental compliance shutdowns.
- Registration Timeline Friction:EPA FIFRA registration for novel biologicals averages 36-48 months, delaying revenue capture from microbial discoveries.
- Neonicotinoid Substitution Cost:Farmers in wheat and canola face 15-40% cost increases when switching from banned seed treatments to biological alternatives.
Strategic Opportunities
- Underpenetrated African Markets:Nigeria and Kenya lack established distribution infrastructure for biological crop protection, creating first-mover channel advantages for microbial suppliers.
- Pheromone-Trap Convergence:Integration of IoT sensors with mating-disruption dispensers enables precision monitoring, opening subscription revenue models in California almond and Washington apple orchards.
- India's PLI Scheme for Agrochemicals:Production-linked incentives for domestic technical material manufacturing reduce import dependence and lower landed costs for export-oriented biological formulations.
Industry Challenges
- Microbial Formulation Expertise Gap:Shelf-stability engineering for entomopathogenic nematodes requires PhD-level biochemistry talent scarce outside BASF's Ludwigshafen and Syngenta's Basel R&D centers.
- Cross-Jurisdiction Label Harmonization:Divergent residue limits between EPA, EFSA, and India's Central Insecticides Board force product variants that fragment production runs and inflate inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insect Pest Control Market |
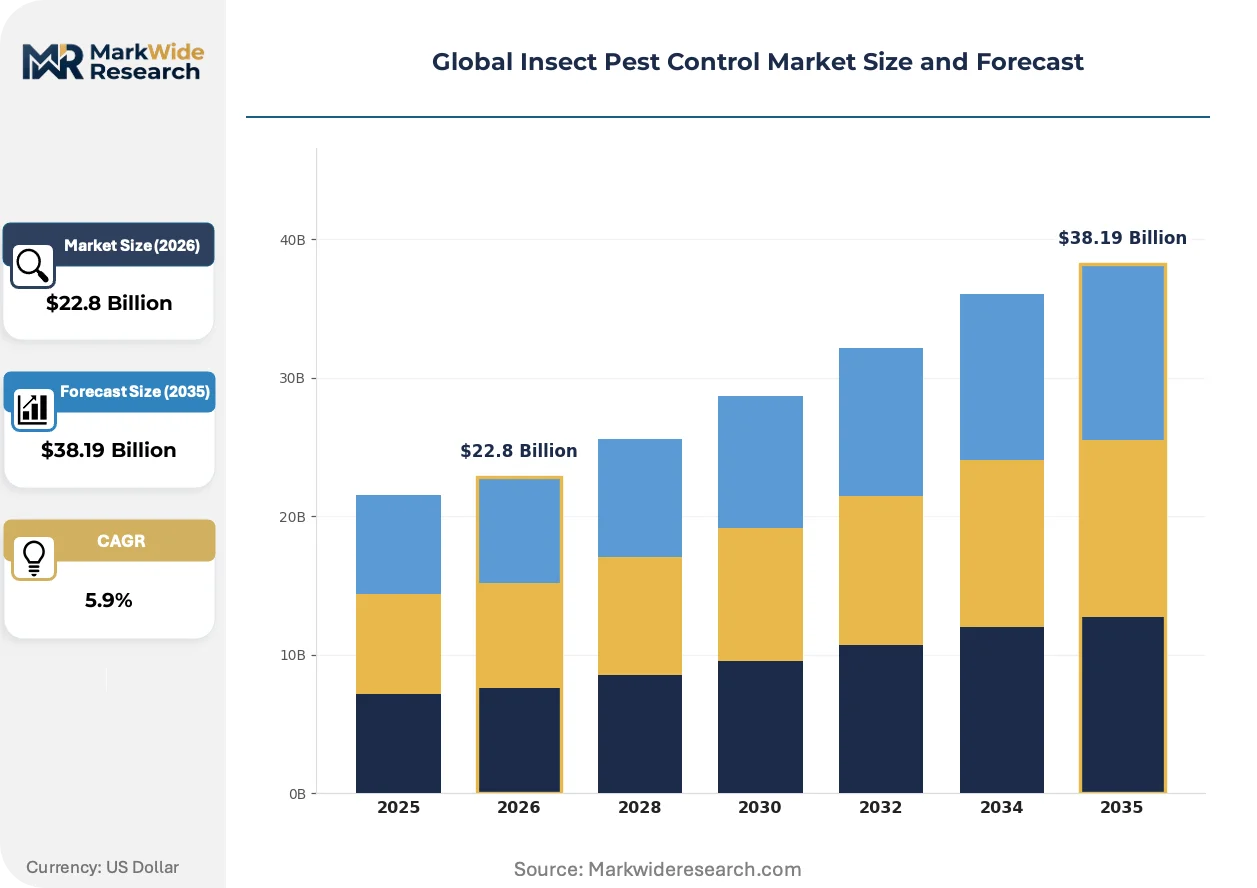
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $38.19 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Control Method: Chemical Insecticides, Biological Agents, Physical Barriers, Traps, Botanical Extracts Target Insect Type: Termites, Mosquitoes, Cockroaches, Flies, Ants, Bedbugs Application Area: Agricultural Fields, Commercial Buildings, Residential Properties, Public Health Zones, Warehouses End User: Farmers, Pest Management Professionals, Property Owners, Public Health Agencies, Hospitality Sector |
| Companies Covered | Rentokil Initial plc, Rollins Inc., Ecolab Inc., Bayer AG, BASF SE, Syngenta AG, FMC Corporation, Anticimex, Sumitomo Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insect Pest Control Market Shifts & Advancements
Biological active ingredients and precision application hardware are converging to displace calendar-based spraying, while regulatory chemistry restrictions accelerate microbial platform investment.
RNA interference technology targets specific pest genotypes without off-species toxicity. Specialty crop growers in California and Florida are piloting foliar sprays containing double-stranded RNA against lepidopteran larvae. This platform is automating pest identification-to-treatment workflows through drone-mounted biosensors that trigger variable-rate application.
The EU F-Gas Regulation phases down hydrofluorocarbon propellants in aerosol formulations, forcing reformulation of household insecticide products. Manufacturers are shifting to compressed gas and pump-spray delivery systems. Germany and France show fastest compliance adaptation, with retailers delisting non-compliant SKUs ahead of 2027 deadlines.
Large-scale farming cooperatives in Brazil and the United States now specify biological-only protocols for export-bound soy and specialty crops. Distributors respond by unbundling chemical and biological portfolios into separate sales teams with distinct incentive structures. This bifurcation is most advanced in Mato Grosso and Iowa, where co-op procurement committees audit field-level compliance.
Global Insect Pest Control Market Segmentation
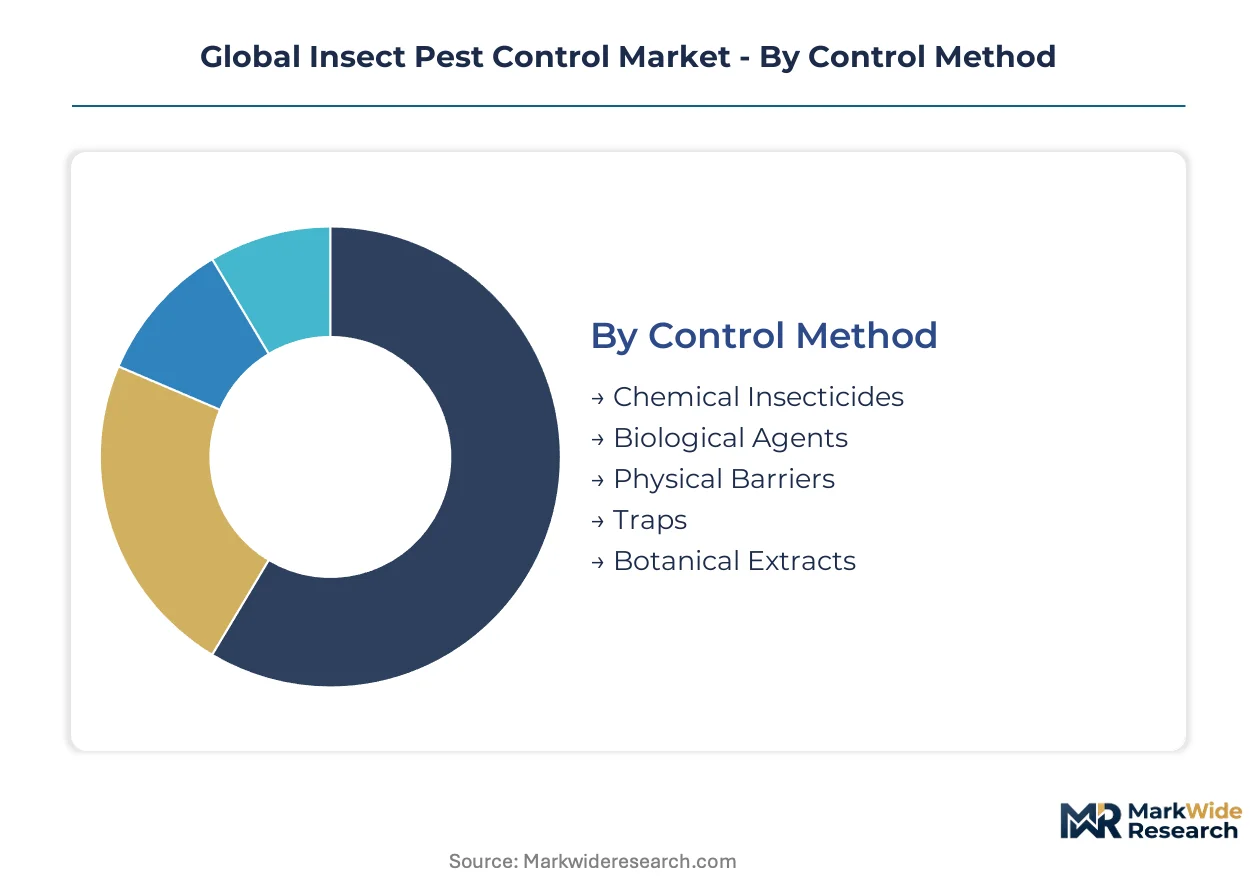
Segmentation in insect pest control reveals divergent margin structures and regulatory exposure profiles. Control method selection determines whether procurement flows through commodity chemical channels or specialized biological distributors.
Control Method:
Standalone chemical applications dominate warehouse and residential contracts where speed commands premium positioning, while biological agents increasingly embed within integrated pest management protocols across agricultural procurement.
- Chemical Insecticides:Synthetic pyrethroids and organophosphates deliver rapid knockdown for emergency infestation response. Demand concentrates in Brazilian soybean warehousing and US residential perimeter treatments where EPA FIFRA registration provides liability shielding.
- Biological Agents:Bacillus thuringiensis formulations and entomopathogenic nematodes require refrigerated supply chains and technical application support. Procurement from export-oriented growers in Mato Grosso and California specialty crop districts accelerates under EU residue limit pressure and retailer sustainability audits.
- Physical Barriers:Mesh screens and sealed storage infrastructure eliminate chemical residue concerns entirely for organic-certified operations.
- Traps:Pheromone-baited monitoring systems enable precision timing of intervention thresholds in Washington apple orchards.
- Botanical Extracts:Neem and pyrethrum derivatives serve bridge applications where synthetic chemistry faces regulatory sunset.
Volume placements concentrate in chemical insecticides; the faster expansion belongs to biological agents.
Target Insect Type:
Cost tier stratification separates commodity termite contracts from premium vector-borne disease programs where public health agencies fund aerial spraying campaigns.
- Termites:Subterranean species threaten structural integrity across warm-humid climate zones. Pre-construction soil treatments and bait-station monitoring generate recurring revenue for pest management professionals in Florida and Queensland.
- Mosquitoes:Anopheles and Aedes species transmit malaria, dengue, and Zika. India's National Vector Borne Disease Control Programme and Brazilian municipal health departments sustain residual insecticide demand through climate-intensified transmission seasons.
- Cockroaches:German and American species trigger food safety violations in commercial kitchens.
- Flies:House and fruit fly suppression concentrates in livestock operations and food processing facilities.
- Ants:Fire ant mound treatments and Argentine ant perimeter control dominate southern US residential markets.
- Bedbugs:Heat treatment and encasement protocols displace chemical reliance in hospitality sector remediation.
Procurement scale peaks with mosquito programs; margin compression is steepest in commoditized cockroach services.
Application Area:
Customer type determines whether contracts specify calendar-based spraying or sensor-triggered precision intervention, with agricultural buyers demanding biological compatibility for export certification.
- Agricultural Fields:Row crops and specialty produce face the strictest residue limits. Brazil's Ministry of Agriculture mandates IPM protocols on operations exceeding 500 hectares, redirecting procurement toward microbial formulations and pheromone mating disruption.
- Commercial Buildings:Office towers and retail chains prioritize invisible, odorless treatments that permit continuous occupancy. Rentokil Initial and Orkin anchor recurring service contracts through technician route density in London, New York, and Singapore corridors.
- Residential Properties:Quarterly perimeter barriers and interior crack-and-crevice applications dominate subscription models.
- Public Health Zones:Municipal spraying programs target vector breeding sites in Indian urban slums and US Gulf Coast counties.
- Warehouses:Fumigation and residual treatments protect stored grain from infestation in Argentine and Ukrainian export facilities.
Revenue concentration sits with commercial buildings; the steepest expansion trajectory runs through agricultural fields.
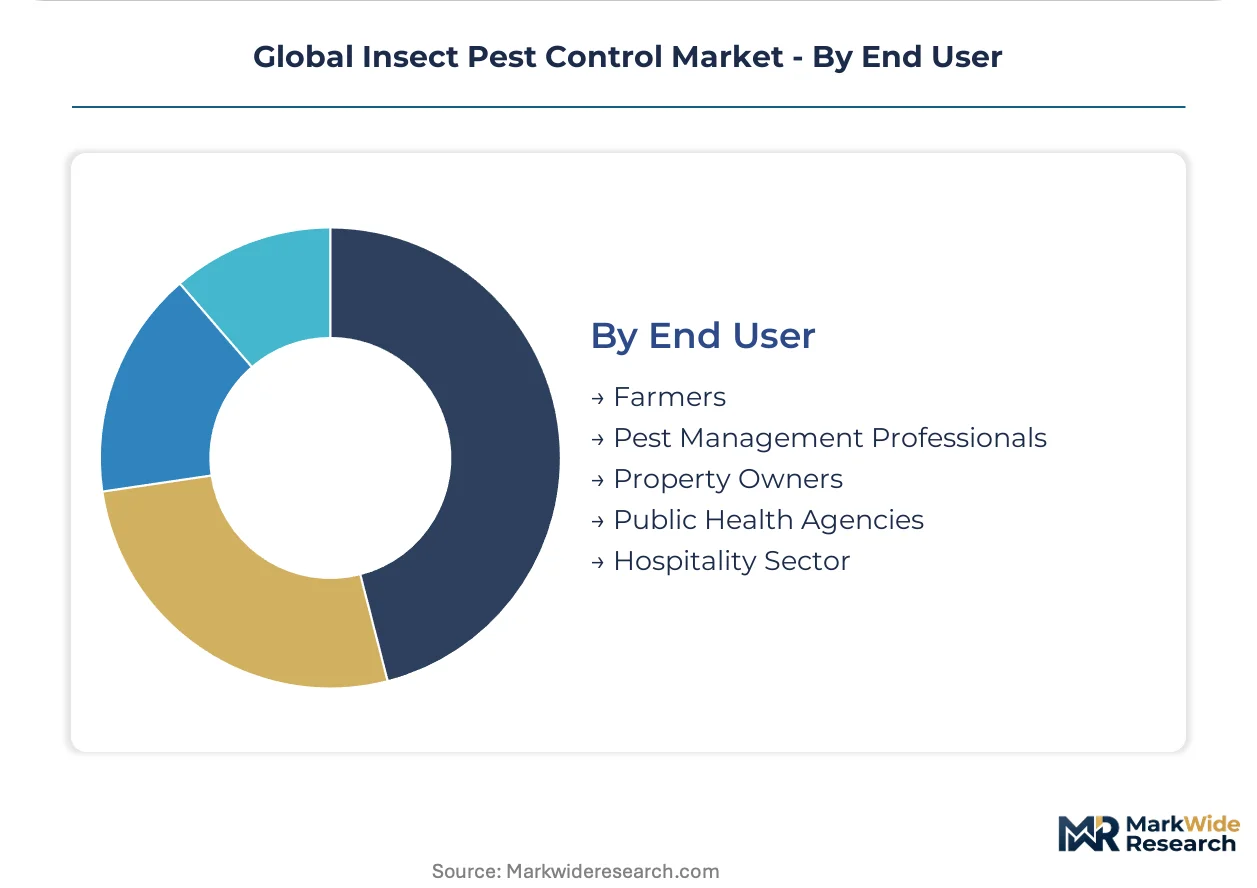
End User:
Supply concentration varies sharply across user categories, with farmers sourcing through cooperative procurement committees while property owners fragment across thousands of local service providers.
- Farmers:Large-scale cooperatives in Iowa and Mato Grosso now specify biological-only protocols for export-bound soy, unbundling procurement into dedicated biological sales teams with distinct incentive structures.
- Pest Management Professionals:Licensed technicians carry liability for proper application and regulatory compliance, concentrating brand loyalty around training support and technical hotlines.
- Property Owners:Homeowner association contracts and individual residential subscriptions generate recurring revenue through annual renewal cycles.
- Public Health Agencies:WHO-prequalified product lists constrain procurement for malaria control programs in Nigeria and Kenya.
- Hospitality Sector:Zero-tolerance bedbug policies drive emergency response contracts and preventive monitoring in Las Vegas and Dubai hotel clusters.
Contract value concentrates with farmers; the fastest share gains belong to pest management professionals consolidating through acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in São Paulo and Gujarat concentrate biological formulation manufacturing for export-oriented agriculture, drawing contract research organizations and cold-chain logistics providers into co-located industrial parks.
United States
Vector-borne disease expansion across Florida and Texas intensifies municipal spraying contracts for Aedes and Anopheles control. EPA FIFRA registration timelines constrain novel biological introduction, delaying revenue capture from microbial discoveries. California's Central Valley specialty crop districts anchor precision pheromone-trap deployment with IoT sensor integration.
Brazil
Soybean and corn operations exceeding 500 hectares face mandatory IPM protocols from the Ministry of Agriculture, expanding Bacillus thuringiensis procurement. ANVISA alignment with EU residue standards redirects formulation investment toward microbial platforms. Mato Grosso farming cooperatives now specify biological-only protocols for export-bound shipments.
India
Climate-intensified malaria and dengue transmission sustains residual insecticide demand through the National Vector Borne Disease Control Programme. The Central Insecticides Board enforces phased bans on monocrotophos and diazinon, redirecting technical material investment toward botanical extracts. Maharashtra and Gujarat production-linked incentive zones reduce import dependence for agrochemical manufacturing.
Germany
The EU F-Gas Regulation and REACH substitution mandates compress synthetic chemistry windows while accelerating microbial R&D. BASF's Ludwigshafen campus anchors entomopathogenic nematode shelf-stability engineering. Retailers in Frankfurt and Berlin corridors delist non-compliant aerosol SKUs ahead of 2027 hydrofluorocarbon phase-down deadlines.
China
Three manufacturers supply over 60% of global pyrethroid technical material, creating supply vulnerability during environmental compliance shutdowns under MEE enforcement. Yangtze River Delta formulation clusters serve as contract manufacturing hubs for biological exports. Zhejiang and Jiangsu provinces concentrate domestic agricultural insecticide production for rice and wheat protection.
Global Insect Pest Control Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with service-network density commanding premium positioning in commercial buildings while microbial formulation expertise concentrates among agricultural suppliers. The vendor base organizes into three tiers: multinational chemical conglomerates with seed-treatment extensions, dedicated pest management service providers with route-optimized technician networks, and emerging biological specialists with refrigerated supply chain capabilities. Competitive moves center on acquisition-driven route consolidation in urban corridors and backward integration into technical material manufacturing to reduce import exposure.
Within the multinational tier, Bayer AG and BASF SE occupy positions anchored by microbial R&D infrastructure and regulatory registration depth across multiple jurisdictions. Syngenta AG exemplifies the seed-treatment extension archetype, leveraging foliar biological platform adjacencies. Among service-network specialists, Rentokil Initial plc represents route-density optimization in commercial building corridors, while Rollins Inc. and Ecolab Inc. sit within the North American residential and food-safety contract segments respectively.
| Leading Market Players |
|---|
| Rentokil Initial plc |
| Rollins Inc. |
| Ecolab Inc. |
| Bayer AG |
| BASF SE |
| Syngenta AG |
| FMC Corporation |
| Anticimex |
| Sumitomo Chemical Co. Ltd. |
| Others |
Supply & Pricing Matrix
Microbial formulation R&D is compressing synthetic chemistry margins while concentrating production expertise in specialized biotech clusters, simultaneously elevating input costs for biological agents and fragmenting pricing power across legacy chemical channels. This bifurcation separates premium biological procurement from commoditized pyrethroid spot markets as regulatory substitution mandates accelerate.
Pricing Analysis
Volume placements concentrate in chemical insecticides; biological agents capture expanding margins. Three-tier pricing structure across premium microbial formulations, standard synthetic chemistry, and economy bulk pyrethroids reflects certification grade and cold-chain service bundling. Price differentiation stems from EU residue compliance tiers and refrigerated logistics support. Pricing pressure intensifies in chemical tiers as REACH substitution mandates erode demand. Smallholder farmers in India exhibit highest price sensitivity; export-oriented Brazilian cooperatives accept premium biological positioning.
Supply Chain Analysis
Refrigerated freight costs for entomopathogenic nematodes and Bacillus thuringiensis concentrates constrain biological distribution radius, favoring regional formulation hubs over centralized manufacturing. Supply concentrates in China for pyrethroid technical material, Germany for microbial R&D infrastructure, and India for botanical extract processing. Raw material dependencies include fermentation feedstocks, nematode propagation media, and neem biomass. Single-source vulnerability in Chinese pyrethroid intermediates creates disruption risk during MEE environmental compliance shutdowns. Distribution runs through cooperative procurement committees in agricultural segments and route-optimized technician networks in commercial buildings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and REACH substitution mandates construct a cost-of-compliance barrier that favors incumbents with existing microbial registration portfolios and multi-jurisdiction regulatory infrastructure. This moat disadvantages pure-chemical players facing active ingredient sunset.
For Market Incumbents: Acquire refrigerated logistics networks and nematode propagation facilities to anchor biological supply chain control. Prioritize backward integration into fermentation capacity in São Paulo and Gujarat industrial zones to reduce import exposure. Defend against biological specialists by embedding IoT-enabled pheromone monitoring into existing service contracts, converting transactional chemical sales into subscription-based precision intervention platforms. For New Entrants and Emerging Players: Launch via direct-to-cooperative distribution in Mato Grosso and Iowa, bypassing established chemical distributor relationships. Target underpenetrated African markets in Nigeria and Kenya where WHO-prequalified product lists constrain incumbent procurement flexibility. Position around RNA interference foliar sprays for California specialty crops, leveraging automatable drone application to displace labor-intensive microbial deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational agrochemical conglomerates seeking biological platform fill-in. Long-term viability favors targets with refrigerated supply chain capabilities and EPA FIFRA registration depth across multiple active ingredients. Acquisition target archetype: mid-scale biological formulators with established nematode shelf-stability engineering. Monitor ANVISA-EU residue alignment announcements as inflection signal for accelerated biological substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Material Manufacturing | Captive pyrethroid supply reduces exposure to Chinese environmental compliance shutdowns under MEE enforcement. |
| Cold-Chain Logistics Network Expansion | Refrigerated distribution infrastructure extends entomopathogenic nematode shelf life and enables premium biological positioning. |
| IoT-Enabled Pheromone Platform Launch | Sensor-integrated mating disruption converts chemical spraying contracts into recurring subscription revenue in California orchards. |
| Regulatory Registration Portfolio Buildout | Multi-jurisdiction EPA FIFRA and EU active substance approvals create moats against faster-follower biological competitors. |
| Cooperative Procurement Committee Partnership | Direct relationships with Mato Grosso and Iowa farming cooperatives bypass fragmented distributor channels for biological-only protocols. |
Research Methodology
Document review covered EPA FIFRA registration databases, EU REACH substitution roadmaps, and ANVISA residue limit filings, complemented by interviews with biological R&D directors at multinational agrochemical firms, procurement leads at Brazilian farming cooperatives, pest management professional franchise operators, and cold-chain logistics specialists. Secondary validation drew from customs trade data, SEC 10-K filings of listed service providers, and Ministry of Agriculture IPM protocol documentation. Bottom-up volume estimates from application-area procurement patterns were cross-referenced against top-down market sizing from active ingredient production capacity.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include control method chemistry, target insect vector type, application area intensity, and end-user procurement concentration. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory phase-down schedules and climate-driven vector expansion patterns. Industry-specific inputs include ANVISA-EU alignment timelines and India's Central Insecticides Board ban implementation schedules.
Regulatory acceleration beyond announced phase-down dates, unexpected resistance development in target pest populations, and Chinese environmental policy enforcement intensity are the dominant revision risks to modeled biological substitution trajectories. Stakeholders should weight assumptions against their own operating context and registration portfolio exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Tebufenozide Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Miticides Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Europe Nematicide Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Pest Control Products Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Global Acephate Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
United States Crop Protection Chemicals Market