
 Middle East and Africa Algaecides Market | 2026-2036
Middle East and Africa Algaecides Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Algaecides Market Foresight
Aftermarket service revenue for dosing system calibration and reservoir monitoring is reconfiguring profit pools across the Middle East and Africa algaecides value chain. BASF SE leverages its regional formulation networks to supply copper-based algaecides to Egyptian agricultural cooperatives. UPL Limited anchors its position through distributor partnerships in sub-Saharan African markets with limited direct sales infrastructure. Nufarm Limited competes on price-sensitive municipal tenders in South Africa through localized blending operations.
Algaecides are chemical or biological agents formulated to inhibit, kill, or prevent algae proliferation in aqueous environments, typically containing active ingredients such as copper sulfate, quaternary ammonium compounds, or peroxyacetic acid at concentrations between 0.1 and 5.0 ppm for industrial applications. These compounds serve essential functions in maintaining water quality, preventing biofouling, and protecting crop yields across warm-climate regions where thermal stratification accelerates algal blooms. Liquid formulations dominate volume sales due to ease of metered injection in continuous-flow water treatment systems, while granules command premium positioning in controlled-release aquaculture applications. The concentrate formulation segment captures the largest margin pool through dilution economics that reduce per-unit freight costs across the Middle East and Africa's dispersed customer base.
South Africa's Department of Water and Sanitation enforces national water quality standards that mandate algaecide intervention when microcystin levels exceed potable thresholds, directly shaping municipal procurement volumes. Egypt's Ministry of Agriculture and Land Reclamation regulates agricultural runoff containing algal biomass through irrigation district management protocols. Stakeholders must monitor evolving registration requirements for quaternary ammonium compounds under REACH-aligned chemical frameworks as Gulf Cooperation Council harmonization progresses.
Market Dynamics
Municipal water treatment utilities across South Africa are expanding algaecide procurement to combat cyanobacterial blooms in reservoir systems. Egypt's Nile Delta agricultural corridor drives recurring consumption through irrigation canal maintenance requirements. These dual demand anchors are compressing formulation margins while expanding service revenue pools for dosing system calibration.
Growth Catalysts
- South Africa's National Water Act:Tightened discharge standards for algae-laden effluent mandate intervention when microcystin levels exceed potable thresholds. Municipal procurement volumes scale directly with enforcement intensity.
- Copper sulfate demand:Egyptian agricultural cooperatives require continuous algaecide application to prevent biofouling in gravity-fed irrigation networks. Warm-climate thermal stratification accelerates treatment frequency.
- Aftermarket service expansion:Reservoir monitoring and dosing system calibration are reconfiguring profit pools across the value chain. Technical service contracts now outpace raw chemical margins in select municipal accounts.
Market Restraints
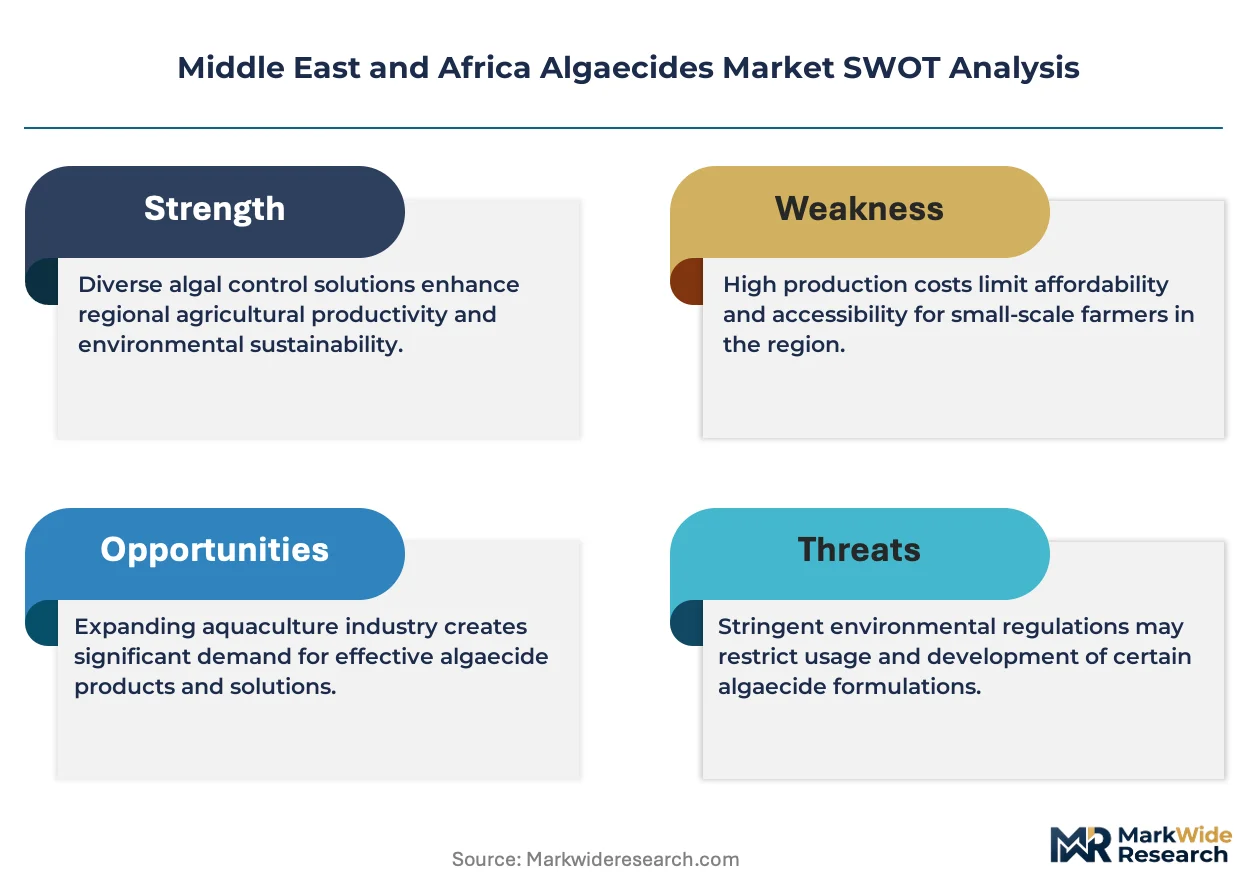
- Quaternary ammonium compound registration:REACH-aligned chemical frameworks under Gulf Cooperation Council harmonization are extending approval timelines. Formulators face regulatory friction in cross-border product mobility.
- Copper price volatility:Active ingredient cost fluctuations compress blending margins for copper-based formulations. Price-sensitive municipal tenders in South Africa resist pass-through mechanisms.
- Technical substitution limits:Biological algaecides struggle to match copper sulfate efficacy in high-turbidity reservoir conditions. Performance gaps restrict segment penetration in municipal applications.
Strategic Opportunities
- Sub-Saharan distributor partnerships:Markets with limited direct sales infrastructure offer first-mover positioning for technical support networks. UPL Limited's anchor model demonstrates viable pathway.
- Controlled-release aquaculture:Granule formulations command premium positioning in fish farming applications. Warm-water pond systems across Egypt and Nigeria present untapped demand pools.
- Concentrate formulation economics:Dilution protocols reduce per-unit freight costs across dispersed customer bases. Localized blending operations capture margin expansion in price-sensitive segments.
Industry Challenges
- Integrated water quality management frameworks:Multi-agency coordination between agriculture and sanitation departments complicates procurement standardization. Stakeholders navigate overlapping compliance requirements.
- Legacy dosing infrastructure:Manual injection systems in older Egyptian irrigation districts resist automated metered upgrade. Capital constraints delay precision application adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Algaecides Market |
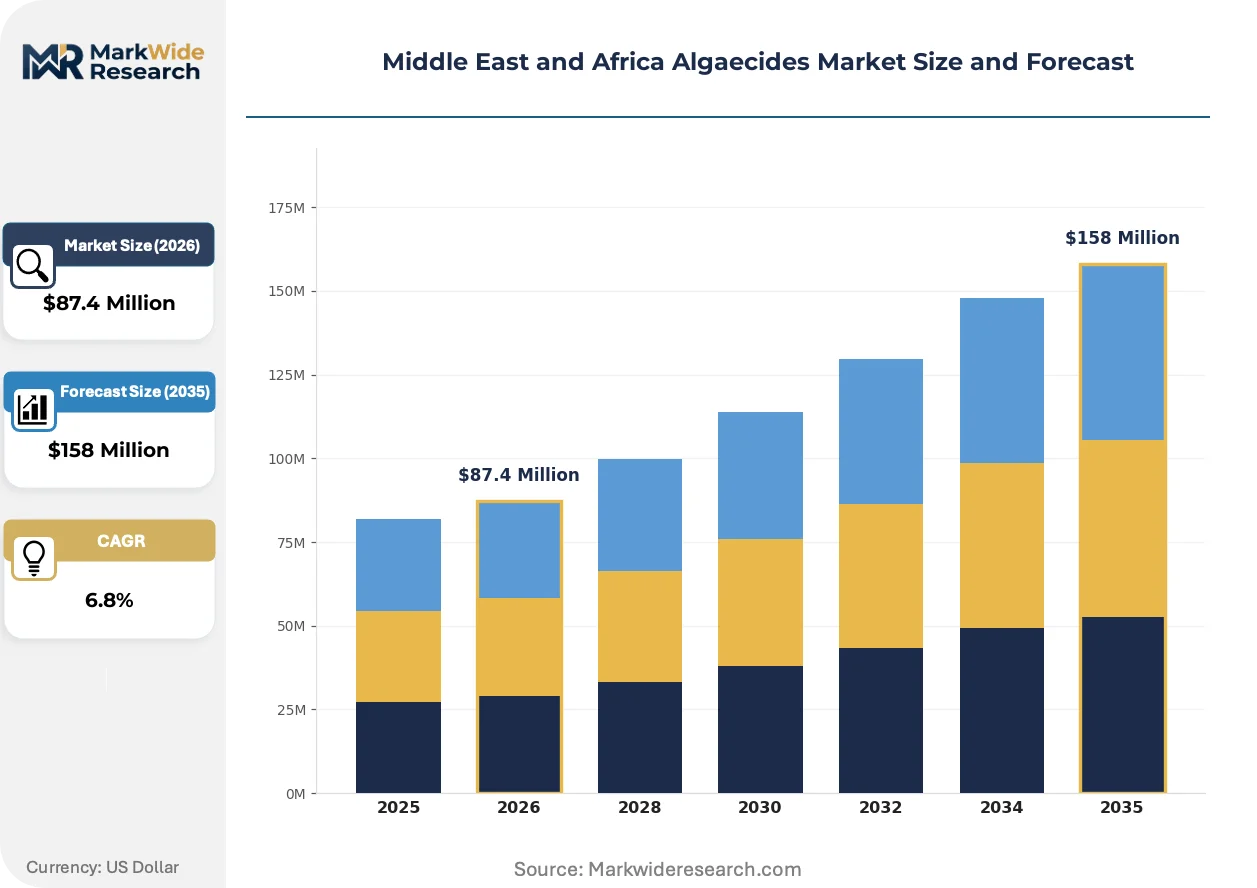
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid, Pellets, Emulsions Formulation: Concentrate, Ready-to-Use, Dry, Water-Soluble Application: Aquaculture, Agriculture, Industrial Water Treatment, Swimming Pools Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | BASF SE, FMC Corporation, UPL Limited, Nufarm Limited, Arxada AG, Dow, Lonza Group AG, SePRO Corporation, BioSafe Systems, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Algaecides Market Shifts & Advancements
Formulation chemistry and application precision are reshaping competitive positioning across the Middle East and Africa algaecides market. Technical service unbundling and regulatory alignment pressures are compressing traditional chemical-only revenue models.
Peroxyacetic acid formulations are migrating from niche aquaculture applications into municipal reservoir treatment protocols. South African water utilities are piloting these compounds in cyanobacterial bloom scenarios where copper resistance has emerged. The shift is enabling non-metal discharge compliance while compressing legacy copper sulfate volume share in sensitive catchments.
Egypt's Ministry of Agriculture and Land Reclamation is tightening irrigation district management protocols for agricultural runoff containing algal biomass. The regulatory consequence is mandatory treatment documentation across Nile Delta cooperatives. Copper-based algaecide suppliers are responding with integrated application logging systems to satisfy audit requirements.
Technical service contracts are displacing standalone chemical procurement in South African municipal accounts. Water treatment utilities now bundle reservoir monitoring with algaecide supply through multi-year agreements. This pattern is most visible in Gauteng and Western Cape provinces where integrated water quality management frameworks mandate continuous oversight.
Middle East and Africa Algaecides Market Segmentation
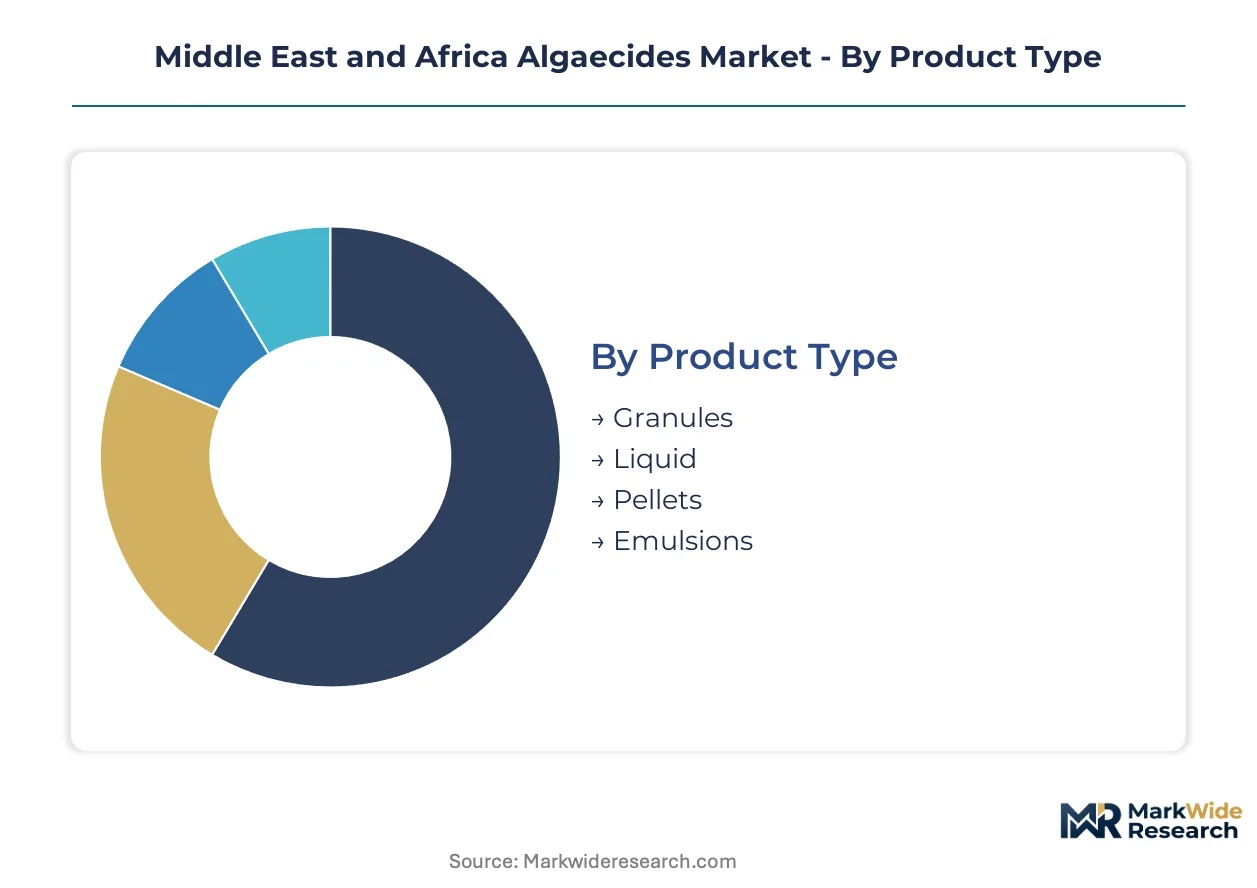
Algaecide procurement patterns across the Middle East and Africa diverge sharply by application environment and supply chain access. Segment boundaries reflect water chemistry requirements, labor availability for manual application, and the technical sophistication of dosing infrastructure.
Product Type:
Liquid formulations turn over fastest in continuous-flow municipal systems, while granules and pellets exhibit slower replacement cycles tied to seasonal aquaculture harvests.
- Liquid:Dominates volume sales through ease of metered injection in reservoir and canal systems. South African municipal utilities specify liquid copper sulfate for automated dosing stations where microcystin monitoring triggers continuous feed rates.
- Granules:Command premium positioning in controlled-release aquaculture applications. Egyptian fish farming cooperatives along the Nile Delta prefer granule formulations for warm-water pond systems where sustained release reduces labor costs.
- Pellets:Target niche applications in ornamental water features and small-scale irrigation reservoirs where localized treatment zones are required.
- Emulsions:Serve specialized industrial cooling tower applications where oil-phase carriers enhance penetration of biofilm matrices.
Liquid dominates installed base. Granules are where expansion concentrates.
Formulation:
Cost tier stratification separates freight-sensitive concentrate economics from convenience-positioned ready-to-use formats.
- Concentrate:Captures the largest margin pool through dilution protocols that reduce per-unit freight costs across dispersed customer bases. Egyptian agricultural cooperatives blend concentrate shipments locally to bypass import volume restrictions.
- Ready-to-Use:Premium positioning targets swimming pool maintenance contractors and small-scale aquaculture operators lacking technical mixing infrastructure. South African residential pool service companies absorb higher unit costs to eliminate field preparation errors.
- Dry:Bulk shipments serve industrial water treatment facilities with on-site dissolution and feed systems. Nigerian textile manufacturers utilize dry copper sulfate for cooling lagoon maintenance.
- Water-Soluble:Dissolvable packets address safety and handling concerns in manual application scenarios across legacy Egyptian irrigation districts.
Concentrate commands procurement volume. Ready-to-Use is climbing the fastest in service-contract segments.
Application:
Customer type differentiation separates institutional procurement with technical specifications from price-sensitive agricultural volume buyers.
- Agriculture:Recurring consumption driven by irrigation canal maintenance across Egypt's Nile Delta corridor. Gravity-fed networks require continuous algaecide application to prevent biofouling that reduces flow capacity.
- Industrial Water Treatment:High-specification formulations for cooling towers and process water systems. South African mining operations specify quaternary ammonium compounds for tailings pond management under discharge compliance protocols.
- Aquaculture:Premium granule demand concentrates in Egyptian and Nigerian warm-water fish farming. Controlled-release formulations reduce mortality events from oxygen depletion during algal bloom episodes.
- Swimming Pools:Seasonal demand spikes align with tourism cycles in UAE and Saudi Arabian hospitality sectors. Service contractors bundle algaecide with pH balancing chemicals.
Agriculture anchors volume demand. Aquaculture is gaining share fastest in value terms.
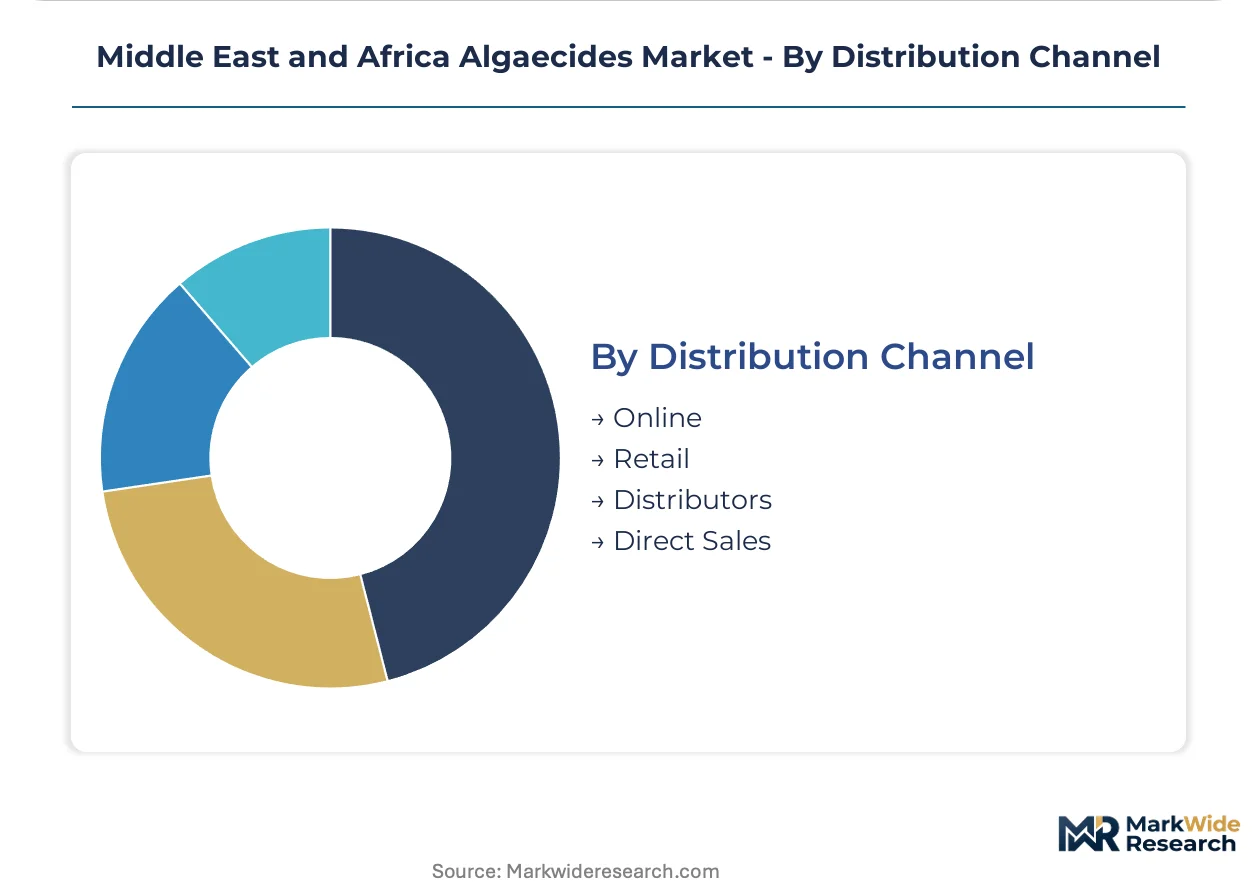
Distribution Channel:
Supply concentration patterns favor distributor networks where technical support requirements exceed direct sales infrastructure.
- Distributors:Anchor sub-Saharan markets with limited manufacturer presence. Kenyan and Tanzanian agricultural supply cooperatives rely on regional distributors for inventory stocking and application training.
- Direct Sales:Municipal tender processes in South Africa and Egypt favor direct manufacturer relationships for compliance documentation and multi-year service contracts.
- Retail:Swimming pool specialty stores serve residential maintenance segments in UAE and Saudi Arabian urban centers.
- Online:Emerging channel for standardized concentrate formulations where buyers possess technical competence for dilution protocols.
Distributors dominate installed base. Direct Sales is where expansion concentrates in municipal accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures sharply across the Middle East and Africa algaecides market. South African municipal utilities absorb premium pricing for compliance-grade formulations, while Egyptian agricultural cooperatives drive volume through concentrate blending that minimizes landed costs.
South Africa
The Department of Water and Sanitation enforces microcystin thresholds that trigger mandatory algaecide intervention in reservoir systems. Gauteng and Western Cape provinces bundle multi-year technical service contracts with chemical supply, shifting procurement toward integrated water quality management frameworks. Mining operations in the Northern Cape specify quaternary ammonium compounds for tailings pond compliance.
Egypt
The Ministry of Agriculture and Land Reclamation mandates treatment documentation across Nile Delta irrigation districts through tightened runoff protocols. Gravity-fed canal networks in the Delta corridor require continuous copper sulfate application to prevent biofouling that degrades flow capacity. Egyptian agricultural cooperatives blend concentrate shipments locally to circumvent import volume restrictions.
United Arab Emirates
MOHAP regulates recreational water quality standards that intensify algaecide consumption in hospitality sector swimming pools. Dubai and Abu Dhabi service contractors bundle algaecide with pH balancing chemicals during seasonal tourism peaks. The emirates' premium positioning supports ready-to-use formulation premiums that exceed regional averages.
Nigeria
Warm-water aquaculture expansion across Lagos and Ogun states generates demand for controlled-release granule formulations. Nigerian fish farming cooperatives prioritize sustained-release products that reduce mortality from oxygen depletion during bloom events. Textile manufacturers in Kano utilize dry copper sulfate for industrial cooling lagoon maintenance.
Saudi Arabia
SFDA alignment with Gulf Cooperation Council chemical harmonization extends registration timelines for quaternary ammonium compounds. The Kingdom's desalination infrastructure requires algaecide protocols to prevent biofouling in reverse osmosis pre-treatment stages. Eastern Province industrial cities concentrate procurement for high-specification cooling tower applications.
Middle East and Africa Algaecides Market Competitive Landscape
Capability concentration sits with formulation specialists possessing regional registration expertise; scale advantage sits with diversified chemical conglomerates leveraging freight optimization across dispersed markets. The vendor base stratifies into three functional tiers: multinational agrochemical majors with integrated supply chains, regional formulators capturing price-sensitive agricultural volume, and technical service providers bundling monitoring with chemical supply. Consolidation pressure operates through distributor acquisition in sub-Saharan markets and backward integration into concentrate blending operations.
Within the multinational tier, BASF SE anchors European-origin supply networks serving Egyptian agricultural cooperatives through localized formulation capabilities. UPL Limited exemplifies distributor-dependent models that penetrate sub-Saharan markets lacking direct sales infrastructure. Nufarm Limited occupies a position in price-sensitive municipal procurement through South African blending operations that compress delivered costs.
| Leading Market Players |
|---|
| BASF SE |
| FMC Corporation |
| UPL Limited |
| Nufarm Limited |
| Arxada AG |
| Dow |
| Lonza Group AG |
| SePRO Corporation |
| BioSafe Systems |
| Others |
Supply & Pricing Matrix
Overcapacity in Egyptian concentrate blending facilities is compressing formulation margins while simultaneously expanding aftermarket service pricing power for technical providers. Suppliers respond by unbundling reservoir monitoring from chemical supply, creating dual revenue streams that offset freight cost pressures across dispersed Nile Delta and sub-Saharan delivery routes.
Pricing Analysis
Aftermarket service revenue pools now drive lifetime value extraction across municipal accounts more than raw chemical margins. Three-tier pricing structure across premium compliance-grade, standard agricultural, and economy bulk-blend levels separates South African utilities from Egyptian cooperatives from Nigerian industrial buyers. Price differentiation hinges on certification documentation intensity and geographic delivery cost to remote reservoir systems. Pricing pressure stems from copper sulfate commodity volatility that resists pass-through in price-sensitive tenders. Egyptian agricultural cooperatives exhibit highest price sensitivity; South African mining operations show least.
Supply Chain Analysis
REACH-aligned chemical frameworks under Gulf Cooperation Council harmonization function as de facto export controls limiting cross-border product mobility for quaternary ammonium compounds. Manufacturing concentration centers on Germany, India, and South Africa for active ingredient synthesis and regional formulation. Raw material dependencies include copper sulfate feedstock, quaternary ammonium precursors, and peroxyacetic acid carriers. Supply chain risk manifests as single-source vulnerability for copper-based active ingredients amid mining output fluctuations. Distribution runs through sub-Saharan distributor networks where technical support requirements exceed direct sales infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in technical service unbundling, as municipal procurement shifts from chemical-only tenders toward integrated water quality management contracts create specialist niches.
For Market Incumbents: Entrench position through backward integration into concentrate blending operations in Egypt and South Africa to capture margin compression from import volume restrictions. Lock in multi-year technical service contracts with Gauteng and Western Cape municipalities before competitor replication. Copper price volatility and biological algaecide substitution threats demand defensive certification investment for non-metal discharge compliance. For New Entrants and Emerging Players: Sub-Saharan distributor partnerships in Kenya and Tanzania represent the most penetrable entry point where established players lack direct sales infrastructure. Nigerian warm-water aquaculture cooperatives seeking controlled-release granule formulations offer second white-space target with limited incumbent technical presence. Go-to-market angle should emphasize bundled reservoir monitoring and dosing calibration to mirror municipal procurement pattern shifts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical service providers bundling monitoring with chemical supply in South African municipal accounts. Long-term viability over a 5-10 year horizon favors acquisition targets with regional registration expertise for REACH-aligned Gulf Cooperation Council frameworks. Signal to watch is consolidation pressure through distributor acquisition in sub-Saharan markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Blending | Egyptian cooperatives bypass import volume restrictions through localized formulation capabilities. |
| Technical Service Contract Expansion | South African municipalities bundle reservoir monitoring with algaecide supply under National Water Act compliance. |
| Distributor Network Acquisition | Sub-Saharan markets with limited direct sales infrastructure enable first-mover positioning for technical support. |
| Controlled-Release Granule Development | Nigerian and Egyptian warm-water aquaculture presents untapped demand for sustained-release formulations. |
| Non-Metal Formulation Registration | Peroxyacetic acid migration into municipal protocols captures copper resistance scenarios in sensitive catchments. |
Research Methodology
Desk research of customs and trade databases, chemical registration filings, and municipal procurement records preceded structured interviews with water treatment utility procurement managers, agricultural cooperative supply officers, distributor network operators, and formulation R&D directors. Primary fieldwork across South Africa, Egypt, Nigeria, and UAE validated secondary indicators through plant-level capacity assessments and tender document analysis. Bottom-up volume triangulation against top-down value estimates anchored segmentation splits.
Assumption sets held regulatory enforcement intensity and copper price bands fixed while varying thermal stratification frequency and tourism cycle amplitude across the projection horizon. Segmentation dimensions modeled include product type, formulation concentration tier, application environment, and distribution channel structure. CAGRs derived from fitted growth curves applied to baseline procurement volumes adjusted for documented compliance mandate expansion. Industry-specific inputs incorporated microcystin threshold enforcement patterns and irrigation district maintenance protocols.
Practitioners should monitor Gulf Cooperation Council chemical harmonization timelines and copper commodity volatility bands for early signals of forecast deviation. Forecasts reflect assumptions documented across stakeholder interviews and secondary validation sources. Material shifts in REACH-aligned registration requirements or South African National Water Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Propiconazole Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
US Insecticide Market
Crop Protection
Europe Soil Treatment Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Europe Nematicide Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Azoxystrobin Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
South America Fungicide Market
Crop Protection
South America Nematicides Market
Crop Protection
Iprodione Market
Crop Protection
Grain Fumigants Market