
 South Korea Crop Protection Chemicals Market | 2026-2036
South Korea Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Crop Protection Chemicals Market Analytics
Biological fermentation-based active ingredient production is rewriting manufacturing economics for Korean formulators. Syngenta leverages its global trait-to-chemical pipeline to anchor premium herbicide positioning in the domestic market. Farm Hannong sustains deep R&D ties with domestic agricultural universities to differentiate its fungicide portfolio. Kyung Nong Corporation controls extensive distributor networks across the Honam and Yeongnam rice belts, occupying a critical logistics layer that multinational rivals struggle to replicate.
South Korea crop protection chemicals encompass synthetic and biological formulations designed to manage weeds, insects, and fungal pathogens in cultivated systems, typically manufactured through multi-step organic synthesis or microbial fermentation with purity thresholds dictated by MFDS registration requirements. Their primary commercial purpose centers on securing yield stability for high-value fruit, vegetable, and staple grain production under intensive cultivation regimes. Herbicides command the largest product type position, reflecting persistent labor shortages that make manual weeding uneconomical for rice and orchard operations. Biopesticides represent the fastest-expanding formulation category, as export-oriented growers in Gyeonggi and South Gyeongsang provinces face tightening maximum residue limits in target markets. Liquid formulations dominate application patterns, though wettable powders retain share in mechanized rice farming where tank-mix flexibility reduces per-hectare input costs.
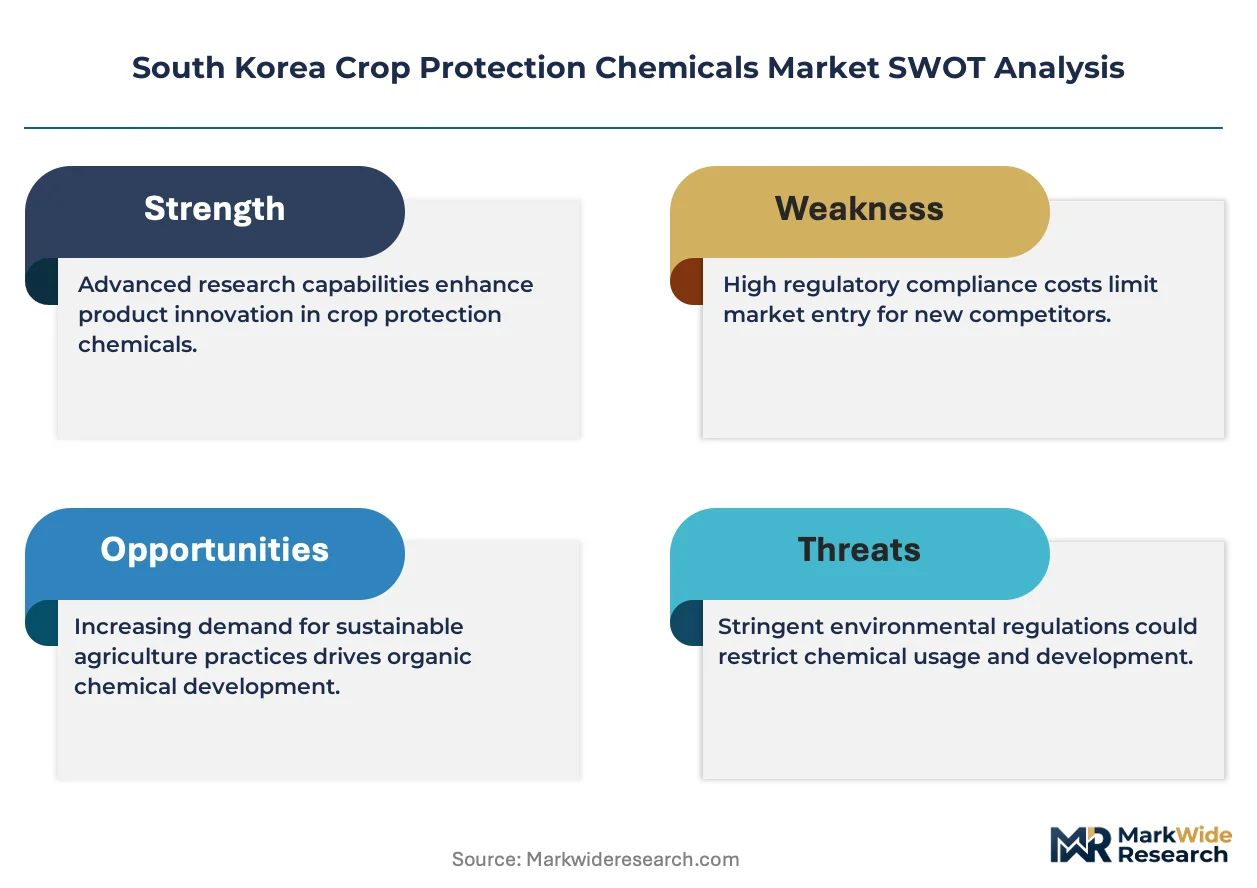
MFDS pesticide registration protocols and MAFRA's positive list system for agricultural chemical residues jointly determine which active ingredients gain market access, with residue testing protocols pushing formulators toward lower-toxicity chemistries. The Ministry of Environment's water source protection zones impose additional buffer restrictions on aerial and ground applications near major river systems. Stakeholders must weigh the capital requirements of biological manufacturing scale-up against the regulatory runway available before synthetic active ingredient re-evaluations potentially remove legacy products from the approved list.
Market Dynamics
MAFRA's positive list system for agricultural chemical residues is compressing the approved active ingredient universe, forcing formulators toward lower-toxicity chemistries and biological alternatives. This regulatory compression is virtualizing traditional synthetic herbicide portfolios while accelerating fermentation-based manufacturing investments across domestic production facilities.
Growth Catalysts
- Precision Application Technology:Drone-mounted spraying systems in Jeolla Province rice operations are reducing per-hectare chemical usage by enabling variable-rate distribution. This technology pull is creating demand for liquid formulations optimized for aerial application.
- Export Market Residue Standards:Tightening maximum residue limits in destination markets for Gyeonggi Province greenhouse produce is driving biopesticide adoption. Growers face commercial exclusion without compliant input portfolios.
- MFDS Registration Pathways:Streamlined evaluation procedures for microbial fermentation products are shortening time-to-market for domestic biological manufacturers. This policy framework is accelerating pipeline conversion from synthetic to biological active ingredients.
Market Restraints
- Active Ingredient Import Concentration:Over seventy percent of synthetic herbicide technicals originate from Chinese chemical manufacturers, exposing Korean formulators to supply disruption and currency fluctuation risks.
- Fermentation Scale-Up Capital Requirements:Biological manufacturing facilities demand three to five times the capital intensity of conventional synthesis plants, constraining mid-tier domestic players from capacity expansion.
- Water Source Protection Buffers:Ministry of Environment restrictions on aerial and ground applications near the Han, Nakdong, and Geum river systems are eliminating arable hectares from addressable market calculations.
Strategic Opportunities
- Smart Farm Integration:AI-driven pest detection systems in South Gyeongsang Province citrus orchards are creating bundled service opportunities combining monitoring hardware with precision chemical application.
- Biostimulant Adjacent Expansion:Fermentation expertise developed for biopesticide production is transferable to plant health biostimulants, opening greenhouse vegetable segments with premium pricing tolerance.
- MAFRA Green Bio Initiative:Subsidized demonstration programs for biological alternatives in rice farming are reducing farmer trial risk and accelerating adoption curve compression in the staple grain segment.
Industry Challenges
- Microbial Strain Development Talent Scarcity:Domestic universities produce insufficient fermentation specialists to staff expanding biological R&D programs, forcing compensation inflation and recruitment delays.
- Tank-Mix Compatibility Certification:Grower demand for application flexibility requires extensive compatibility testing across product combinations, extending registration timelines and elevating development costs.
- Legacy Distributor Capability Gaps:Established Honam and Yeongnam rice belt networks lack technical training to support precision application equipment and biological product handling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Crop Protection Chemicals Market |
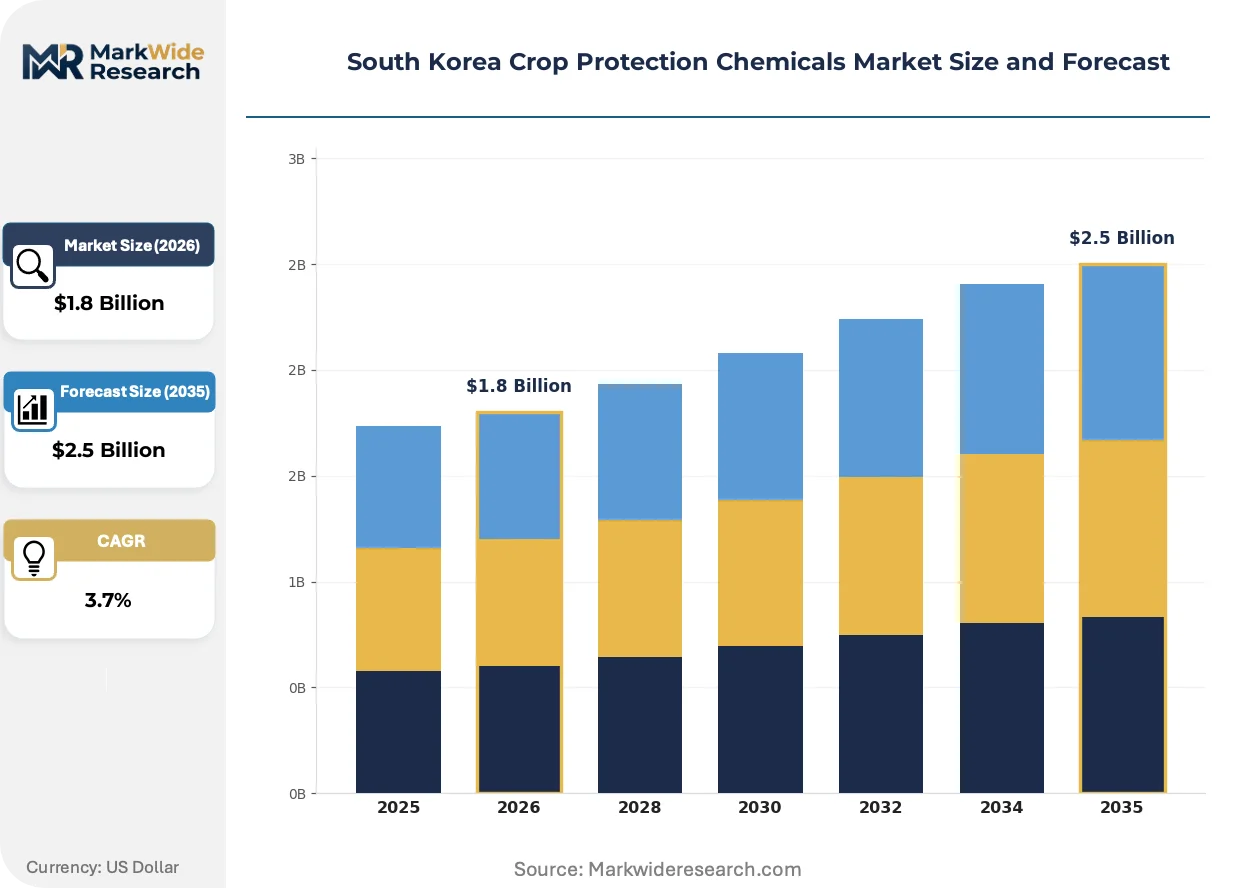
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Biopesticides Application: Agriculture, Horticulture, Turf Management, Forestry Formulation: Granules, Liquids, Emulsifiable Concentrates, Wettable Powders Distribution Channel: Retailers, Online Sales, Direct Sales, Distributors |
| Companies Covered | Syngenta, Bayer Korea Ltd., UPL, Adama Korea Co., Ltd., Farm Hannong, BASF SE, Kyung Nong Corporation, Nonghyup Chemical, KoreaBio Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Crop Protection Chemicals Market Evolving Landscape
Fermentation-based manufacturing and digital application systems are converging to restructure input economics across Korean agricultural value chains. Three distinct trajectories are compressing traditional competitive positions while opening white space for technology-anchored entrants.
RNA interference pesticides targeting specific lepidopteran pests are virtualizing broad-spectrum synthetic insecticide demand in vegetable greenhouse operations. Farm operators in Gyeonggi Province are piloting these precision biocontrol agents at commercial scale. The technology is virtualizing calendar-based spraying schedules into targeted intervention protocols triggered by pest pressure monitoring.
MFDS tightened residue surveillance protocols under MAFRA's positive list system are disqualifying legacy organophosphate chemistries from approved status. Formulators must reformulate portfolios around lower-toxicity alternatives or exit affected crop segments entirely. Rice farming cooperatives in Jeolla Province are responding by consolidating procurement around suppliers with verified residue-compliant product lines.
Direct-to-farm digital platforms are disintermediating traditional agricultural supply cooperatives for input purchasing decisions. Younger farm operators in South Gyeongnam fruit regions are sourcing chemicals through mobile applications offering transparent pricing and technical documentation. This channel compression is most visible in high-value horticulture segments where growers prioritize rapid access to specialty formulations over cooperative loyalty programs.
South Korea Crop Protection Chemicals Market Segmentation
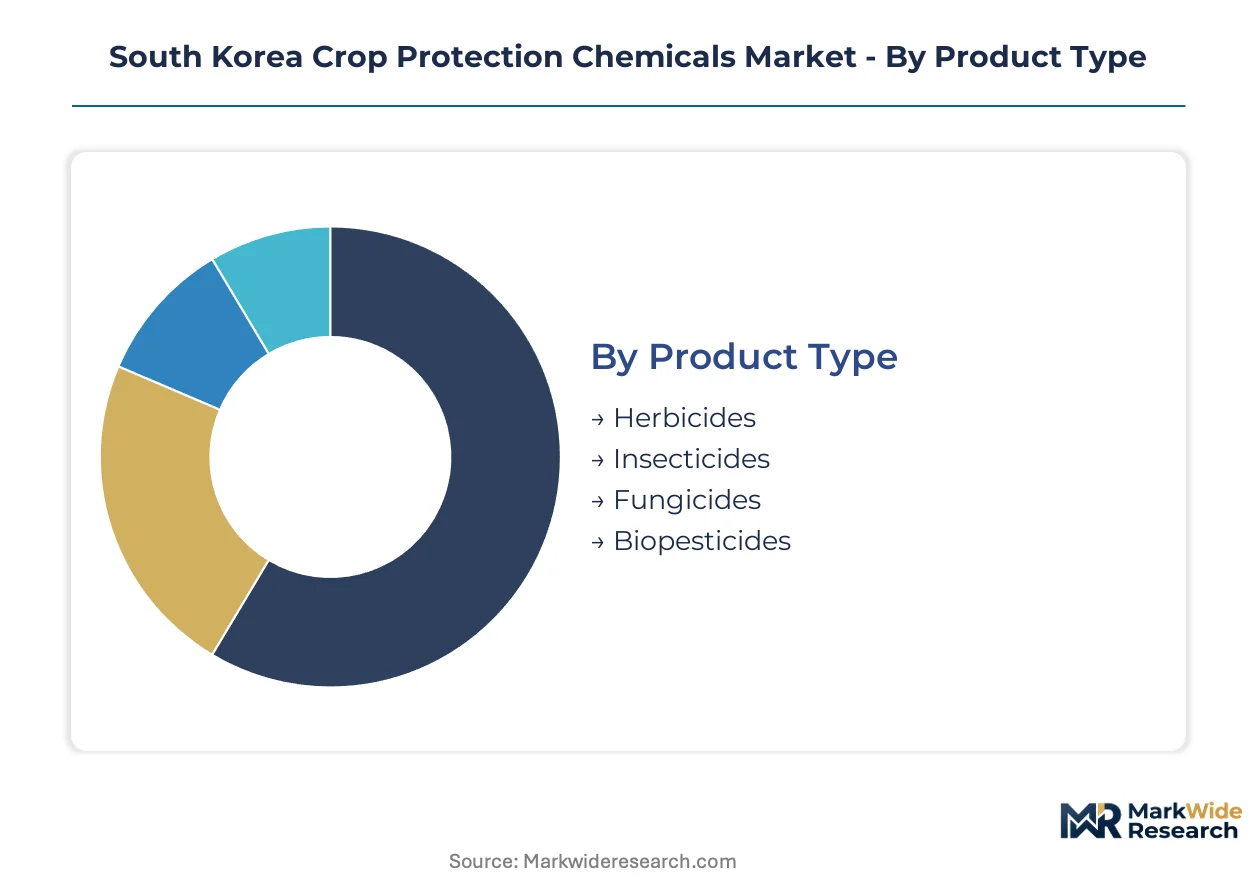
Segmentation reveals how regulatory pressure and farming technology are fragmenting demand across input categories. Each dimension captures distinct procurement behaviors between mechanized rice operations and precision greenhouse systems.
Product Type:
Mature synthetic chemistries dominate current volumes while biological alternatives accelerate from negligible bases.
- Herbicides:Synthetic auxin and ALS-inhibitor formulations control grassy weeds in rice paddies and orchard floors. Jeolla Province mechanized operations depend on pre-emergence and post-emergence protocols to offset labor scarcity.
- Insecticides:Pyrethroid and neonicotinoid chemistries target lepidopteran and sucking pest complexes in vegetable greenhouses. Gyeonggi Province export-oriented growers face residue compliance thresholds that favor rapid-degradation molecules.
- Fungicides:Triazole and strobilurin-based products manage blast and sheath blight in rice systems.
- Biopesticides:Bacillus thuringiensis and Beauveria bassiana fermentation products are climbing the fastest as MAFRA demonstration programs reduce farmer trial risk.
Herbicides retain volume leadership; biopesticides hold the steepest expansion curve.
Application:
Cost tier separation distinguishes capital-intensive protected cultivation from open-field staple grain production.
- Agriculture:Rice, barley, and soybean operations across Honam and Yeongnam belts consume bulk formulated products through cooperative procurement channels. Per-hectare input costs remain tightly constrained by price-sensitive grain economics.
- Horticulture:High-value strawberry, tomato, and pepper cultivation in Gyeonggi Province greenhouse clusters commands premium pricing tolerance for specialty formulations. Export market residue standards drive rapid product turnover in this segment.
- Turf Management:Golf course and sports field maintenance in metropolitan peripheries requires selective herbicide and fungicide applications.
- Forestry:Pine wilt disease control and reforestation support programs utilize limited-volume insecticide treatments.
Agriculture retains volume leadership; horticulture holds the steepest expansion curve.
Formulation:
Application equipment compatibility determines formulation selection across aerial, ground, and manual delivery systems.
- Liquids:Suspension concentrates and soluble liquids enable drone-mounted variable-rate distribution in Jeolla Province rice operations. Tank-mix flexibility supports combination spraying protocols that reduce per-hectare labor requirements.
- Wettable Powders:Dry flowable formulations retain cost advantage in mechanized rice farming where water access supports reconstitution at field edges. Honam belt cooperatives favor these products for bulk procurement efficiency.
- Granules:Controlled-release formulations target soil-dwelling pest complexes in orchard systems.
- Emulsifiable Concentrates:Oil-based carriers penetrate waxy cuticles in tree fruit applications.
Liquids retain volume leadership; granules hold the steepest expansion curve.
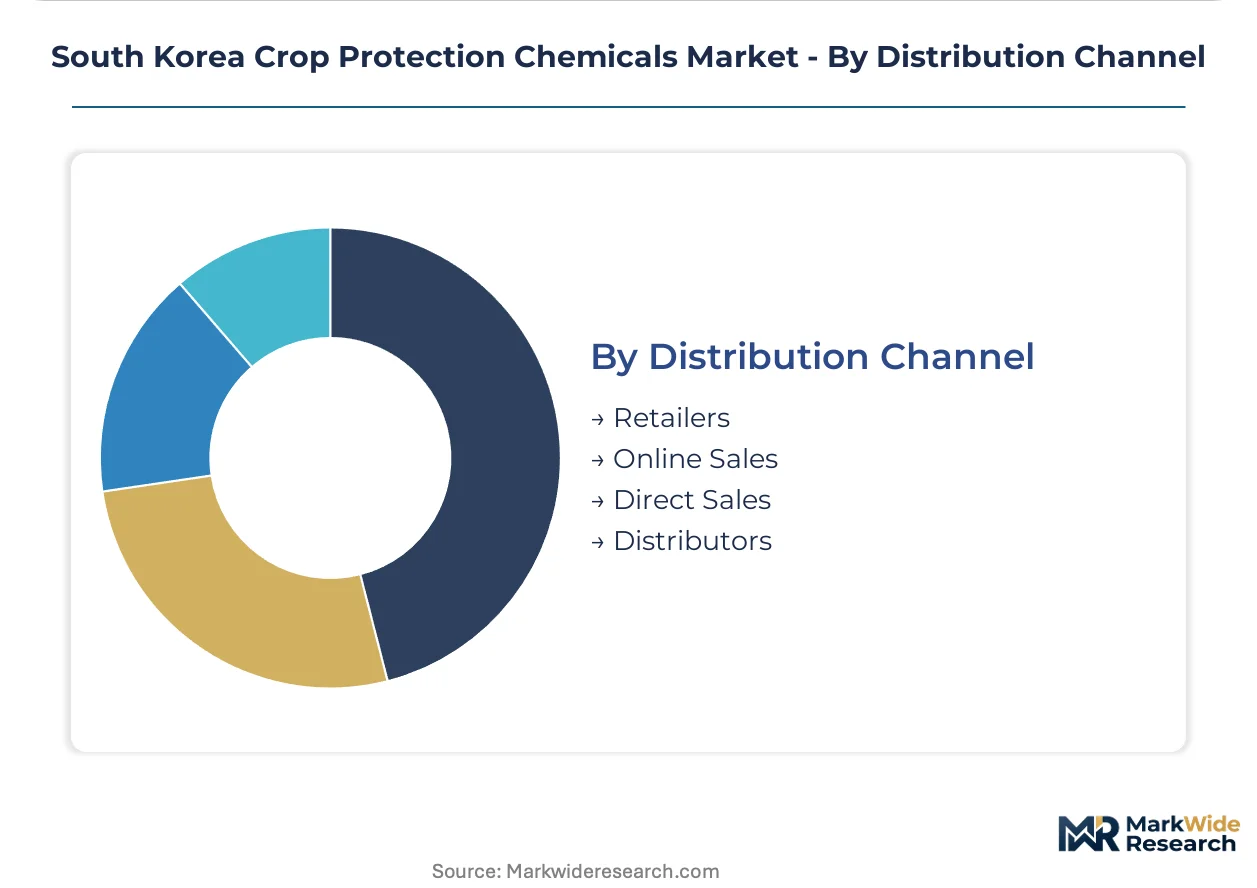
Distribution Channel:
Customer type fragmentation separates generational cohorts in purchasing behavior and technical support expectations.
- Distributors:Kyung Nong Corporation and regional agricultural cooperative networks control last-mile logistics across Honam and Yeongnam rice belts. Technical field staff provide application timing recommendations that anchor farmer loyalty.
- Direct Sales:Large-scale greenhouse operations in Gyeonggi Province negotiate volume contracts with formulators for residue-compliant specialty products. Direct relationships enable rapid regulatory response when MFDS adjusts approved lists.
- Retailers:Local agricultural supply stores serve smallholder operations with immediate availability and credit terms.
- Online Sales:Mobile platforms disintermediate traditional channels among younger farm operators in South Gyeongnam fruit regions seeking transparent pricing and rapid delivery.
Distributors retain volume leadership; online sales hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese technical-grade active ingredient exports supply Korean formulators through concentrated procurement corridors. Jeolla Province rice cooperatives and Gyeonggi greenhouse clusters anchor domestic demand distribution.
Seoul Capital Area
Gyeonggi Province greenhouse vegetable operations drive biopesticide procurement for export compliance. MFDS residue surveillance protocols disqualify legacy chemistries from approved lists. Suwon and Icheon clusters consolidate around residue-compliant specialty suppliers.
Busan-Ulsan
Southeastern port infrastructure handles bulk technical ingredient imports from Chinese manufacturers. Ministry of Environment water source buffers restrict aerial applications near Nakdong River tributaries. Ulsan industrial zones host fermentation-based manufacturing scale-up projects.
Daegu-Gyeongbuk
Apple and pear orchard operations in Gyeongsan and Yeongcheon command selective fungicide formulations. MAFRA demonstration programs subsidize biological alternative trials in tree fruit segments. Younger operators pilot drone-mounted spraying systems for hilly terrain coverage.
Daejeon-Sejong
Central government research complexes anchor public-private biological R&D partnerships. Rural Development Administration funding streams accelerate microbial strain development programs. Sejong administrative city proximity enables rapid regulatory consultation for registration pathways.
Gwangju-Honam
Jeolla Province rice belt consumption concentrates in mechanized pre-emergence and post-emergence herbicide protocols. Kyung Nong Corporation distributor networks control last-mile logistics across cooperative procurement channels. Iksan and Naju farming clusters face labor scarcity that eliminates manual weeding economics.
South Korea Crop Protection Chemicals Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational formulators with global trait pipelines and domestic players controlling distribution infrastructure. Synthetic technical-grade imports from Chinese manufacturers concentrate upstream supply risk. Three archetypes dominate: global integrated agrochemical conglomerates, domestic fermentation-based specialists, and regional distributor-logistics hybrids. Capacity expansion in biological manufacturing and strategic partnerships with agricultural universities constitute the primary competitive vectors.
Among multinational formulators, Syngenta and BASF SE occupy positions anchored by global R&D pipelines and premium herbicide positioning. Domestic players Farm Hannong and Kyung Nong Corporation exemplify contrasting archetypes—one representing university-tied biological R&D differentiation, the other embodying distributor-network control across rice belt logistics. Bayer Korea Ltd. and Adama Korea Co., Ltd. sit within the multinational subsidiary tier, leveraging parent-compound access for residue-compliant portfolio assembly.
| Leading Market Players |
|---|
| Syngenta |
| Bayer Korea Ltd. |
| UPL |
| Adama Korea Co., Ltd. |
| Farm Hannong |
| BASF SE |
| Kyung Nong Corporation |
| Nonghyup Chemical |
| KoreaBio Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Shandong Province chemical manufacturing clusters anchor synthetic technical-grade active ingredient supply for Korean formulators, with capacity utilization swings at Chinese producers translating directly into Korean procurement cost volatility. Downstream pricing power concentrates among distributors controlling cooperative procurement channels across Jeolla and Gyeongsang rice belts.
Pricing Analysis
Next-generation biological formulations command 40-60% premiums over synthetic herbicide equivalents, while legacy organophosphate chemistries face accelerated price erosion under MFDS residue disqualification. Three-tier pricing structure across premium biologicals, standard synthetics, and economy generics reflects certification-grade differentiation and volume-scale procurement power. Pricing pressure stems from Chinese technical import concentration and currency fluctuation exposure. Rice farming cooperatives exhibit highest price sensitivity due to grain margin constraints; Gyeonggi greenhouse exporters show lowest sensitivity given residue compliance premiums.
Supply Chain Analysis
Extended payment terms from Chinese technical suppliers have compressed Korean formulator working capital cycles, forcing supply-chain finance facility adoption. Raw material flows concentrate through Shandong, Jiangsu, and Zhejiang chemical manufacturing provinces. Key inputs include 2,4-D technical, glyphosate acid, and pyrethroid intermediates. Single-source vulnerability runs through the Yellow Sea shipping corridor. Distribution runs through Kyung Nong Corporation and agricultural cooperative networks across Honam and Yeongnam belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological substitution threatens synthetic incumbents as MAFRA demonstration programs accelerate farmer trial adoption and residue compliance requirements harden. Incumbents must navigate this transition while defending position against fermentation-based specialists.
For Market Incumbents: Insulate core herbicide revenues through backward integration into biological fermentation capacity and exclusive distributor channel lock-ups across rice belt cooperatives. Accelerate microbial strain development partnerships with domestic agricultural universities to offset talent scarcity. Prioritize residue-compliant portfolio certification ahead of MFDS re-evaluation cycles. For New Entrants and Emerging Players: Establish a beachhead in precision application service bundling for Jeolla Province drone-mounted spraying operations, where legacy distributors lack technical capability. Target Gyeonggi Province greenhouse segments with rapid-registration biological alternatives for export-compliant produce. Pursue direct-to-farm digital platform partnerships to bypass cooperative procurement chokepoints. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agrochemical parents seeking to divest non-core synthetic portfolios under regulatory pressure. Long-term viability hinges on biological manufacturing scale-up execution and MFDS registration pathway access. Watch MAFRA positive list expansion velocity as inflection signal for substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Domestic biological manufacturing scale-up reduces Chinese technical import dependency for Korean formulators. |
| Precision Application Partnership | Drone-mounted spraying bundling captures Jeolla Province rice cooperative demand from legacy distributors. |
| Residue-Compliant Portfolio Certification | MFDS registration pathway investment secures market access as positive list tightens. |
| University R&D Collaboration | Microbial strain development partnerships offset domestic fermentation specialist talent scarcity. |
| Direct-to-Farm Digital Platform | Mobile purchasing disintermediation targets younger South Gyeongnam fruit operator cohorts. |
Research Methodology
Cross-validation between regulatory filing analysis and distributor procurement data anchors the qualitative findings in this study. Primary interviews with crop protection formulator executives, agricultural cooperative procurement managers, precision application equipment operators, and MFDS regulatory affairs specialists combined with secondary validation from Korea Customs Service import records, MAFRA subsidy program disclosures, Rural Development Administration research publications, and MFDS pesticide registration databases. Bottom-up volume modeling and top-down value reconciliation triangulate market size estimates.
Calibration against historical registration volumes and cooperative procurement patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application sector, formulation technology, and distribution channel, with additional granularity on residue compliance tier. CAGRs derived from trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporate MFDS re-evaluation schedules and MAFRA demonstration program expansion trajectories.
Sensitivities concentrate around Chinese technical supply disruption, won-yuan exchange volatility, and MAFRA positive list expansion timing. Forecasts reflect documented assumptions on biological adoption curves and precision application penetration rates. Macroeconomic deviation, regulatory acceleration, or breakthrough RNAi pesticide commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Metamitron Herbicides Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
US Pest Control Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Azoxystrobin Market
Crop Protection
Tembotrione Market
Crop Protection
Tebuconazole Market
Crop Protection
Europe Fungicide Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
North America Molluscicides Market