
 Soybean Market | 2026-2036
Soybean Market Size, Share, and Industry Trends Forecast 2026-2036
Soybean Market Analysis
Brazil's expanding crush capacity in Mato Grosso is narrowing the exportable surplus window for rival origins. Cargill, Incorporated leverages its river logistics network to anchor origination flows from the interior to Atlantic ports. Bunge Limited competes through processing scale at Santos and Paranaguá. Louis Dreyfus Company sustains origination ties with Mato Grosso farm cooperatives through pre-financing programs.
Soybeans are leguminous oilseeds containing roughly 18-20% oil and 35-40% protein by weight, harvested primarily for mechanical crushing into meal and crude degummed oil. The crop serves as the dominant global protein feedstock for monogastric and ruminant livestock rations. Whole soybeans and soybean oil together command the largest value share, though soy milk and tofu within food and beverage applications are pulling higher unit margins in developed retail channels. Animal feed remains the volume anchor, while biofuels-linked oil offtake is expanding fastest under renewable fuel mandates.
The USDA and EPA regulate biofuel blending obligations and renewable identification numbers that directly shape domestic crush demand in the United States. Brazil's MAPA enforces sanitary protocols for export eligibility, while China's SAMR oversees GMO approval timelines that gate market access for North and South American shipments. Stakeholders must monitor how asynchronous biotech trait approvals between Beijing and Brasília reroute trade flows before planting commitments lock in.
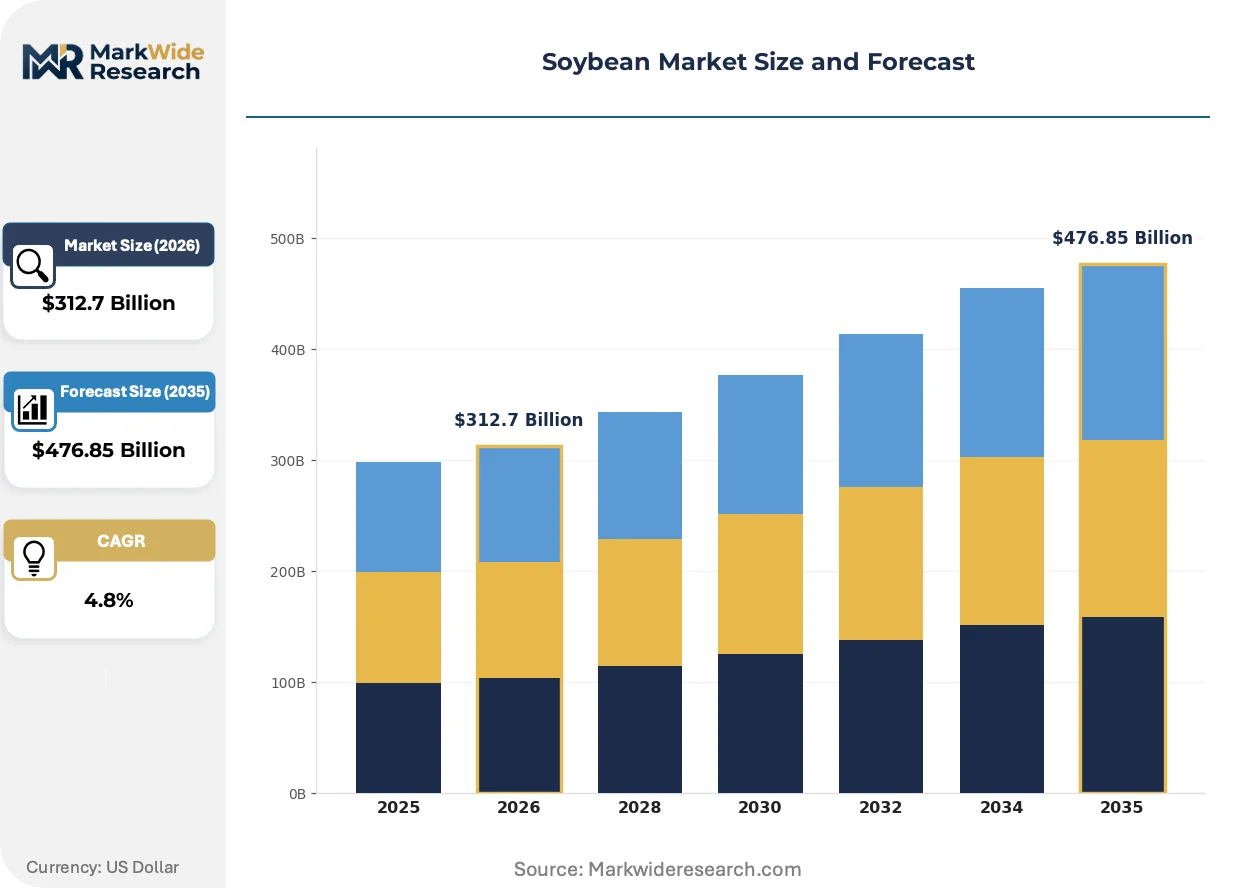
Market Dynamics
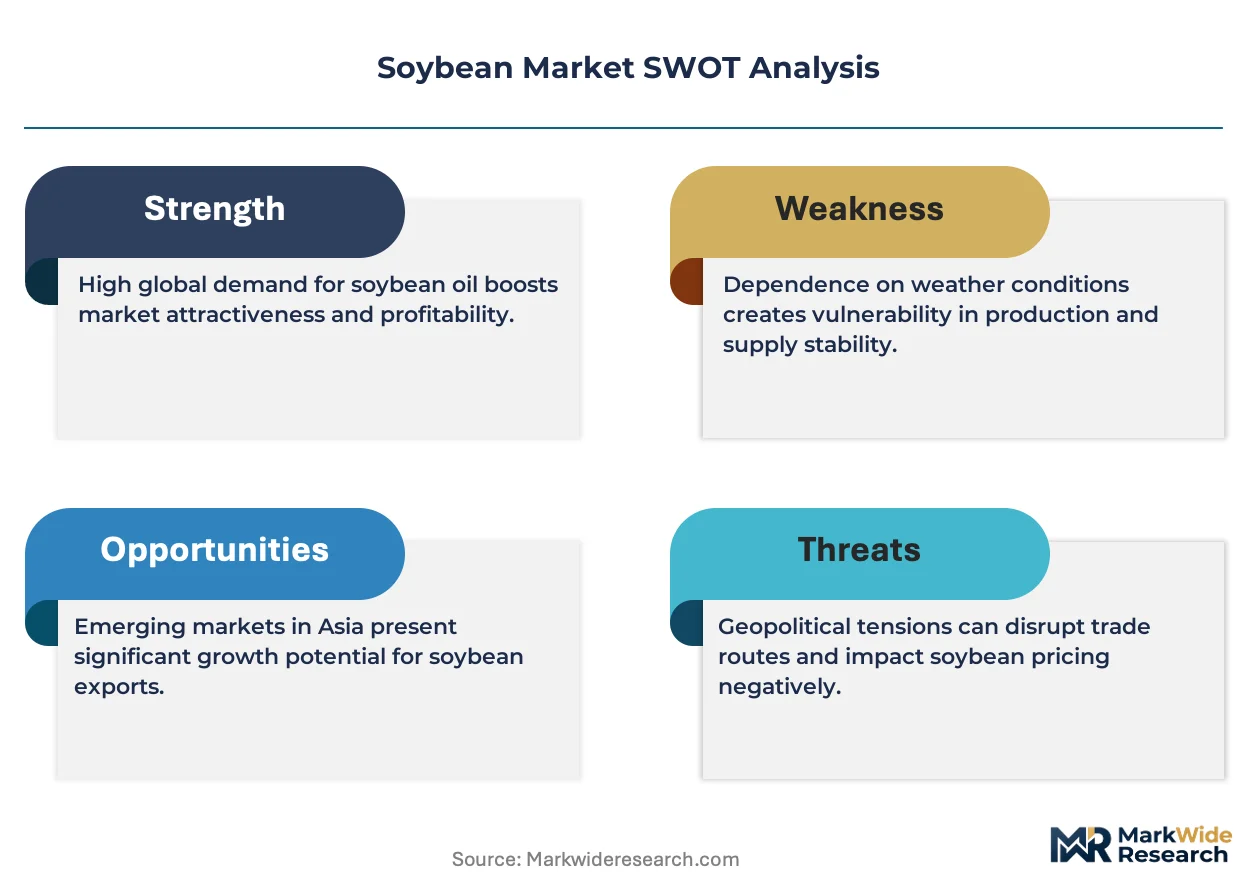
EU Green Deal deforestation regulations are forcing a wholesale reconfiguration of origination and crushing footprints across the soybean complex, with compliance timelines compressing investment cycles for port infrastructure and traceability systems.
Growth Catalysts
- Renewable Fuel Mandates:EPA biofuel blending obligations under the Renewable Fuel Standard are expanding crush demand for oil offtake in the United States, redirecting domestic bean flows away from export channels.
- China's Coastal Crushing Clusters:Demand concentration around Shanghai and Guangzhou is pulling investment into port-side processing capacity, shortening supply chains for imported South American originations.
- Brazil's MAPA Sanitary Protocols:Export eligibility frameworks are tightening quality benchmarks, accelerating consolidation among Mato Grosso farm cooperatives that can meet documentation requirements.
Market Restraints
- Input Cost Volatility:Natural gas and electricity price swings directly compress crush margins, particularly for processors dependent on spot power markets in the US Midwest.
- Supply Concentration Risk:Brazilian interior-to-port logistics corridors face chokepoint vulnerability during the peak harvest window, with barge and rail capacity constraints amplifying price dislocations.
- Asynchronous Biotech Approvals:SAMR GMO approval timelines in Beijing frequently lag Brasília trait clearances, forcing trade flow rerouting after planting commitments lock in.
Strategic Opportunities
- Underpenetrated Food Processing:Soy milk and tofu applications in developed retail channels are pulling higher unit margins than commodity meal, creating white space for branded ingredient suppliers.
- EU Green Deal Compliance Services:Traceability and certification platforms that verify deforestation-free supply chains represent a regulatory tailwind for technology providers serving export-oriented crushers.
- River Logistics Digitization:Integration of IoT sensors with barge fleet management is collapsing transit time variance for interior Brazilian originations, opening efficiency gains for integrated processors.
Industry Challenges
- Traceability System Integration:Retrofitting legacy elevator and crushing assets with satellite-linked farm-to-port monitoring requires substantial capex outlays with uncertain payback periods.
- Regulatory Compliance Talent:Shortages of professionals fluent in both EU Green Deal documentation requirements and Brazilian MAPA sanitary protocols are delaying certification timelines for mid-size exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soybean Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Soybeans, Soybean Oil, Soy Milk, Tofu End Use Industry: Food and Beverage, Animal Feed, Biofuels, Cosmetics Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale Packaging Type: Bags, Totes, Cans, Bulk Containers |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Bunge Limited, Louis Dreyfus Company, COFCO Corporation, Wilmar International Limited, Olam International, Golden Agri-Resources Ltd., CHS Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soybean Market Emerging Trajectories
Mechanical processing efficiency and regulatory compliance technology are converging to reshape competitive positioning across origination, crushing, and distribution layers of the soybean value chain.
High-shear extrusion preprocessing is collapsing energy requirements per ton of crushed beans while preserving protein quality in meal output. Large-scale processors in Iowa and Illinois are retrofitting existing solvent extraction lines with extrusion front-ends, cutting natural gas consumption by double-digit percentages. The technology is collapsing the operating cost gap between older inland facilities and newer coastal greenfield plants.
The EU Green Deal's deforestation regulation is mandating geolocation verification for all soybean shipments entering European ports, effective across the twenty-seven member states. This policy is forcing exporters to deploy satellite monitoring and blockchain documentation from farm gate to vessel hold. Brazilian cooperatives in Mato Grosso are responding by consolidating origination volumes through fewer, larger entities that can absorb compliance system investments.
Buyers in China's coastal crushing clusters are shortening procurement cycles from quarterly to monthly tenders, compressing price discovery windows and amplifying volatility transmission. This behavioral shift is displacing long-term offtake contracts that previously anchored Brazilian export planning. The pattern is most visible in Guangzhou, where processors are building smaller, more frequent inventories to manage SAMR approval uncertainty.
Soybean Market Segmentation
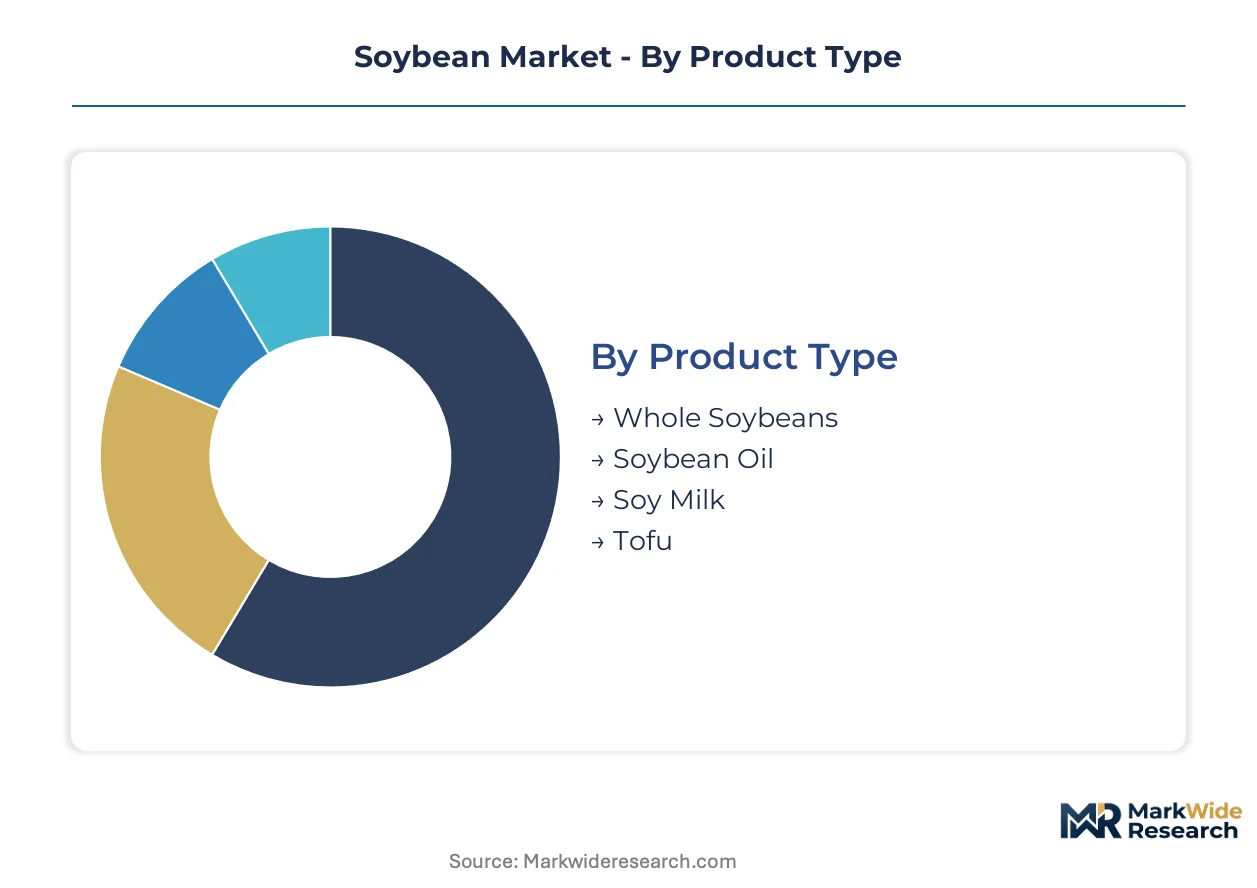
Soybean market segmentation reveals divergent margin profiles across the value chain, with commodity crushing operations competing on scale while food-grade derivatives command premium positioning. Understanding product type turnover and channel velocity separates volume-driven processors from specialty ingredient suppliers.
Product Type:
Cycle times vary dramatically across soybean derivatives, with unprocessed beans turning in weeks and fermented food products requiring months of maturation.
- Whole Soybeans:Unprocessed oilseeds containing 18-20% oil and 35-40% protein by weight serve as the raw input for mechanical crushing operations. Demand concentrates in Mato Grosso farm cooperatives supplying Atlantic export corridors, with EU Green Deal traceability requirements now gating market access.
- Soybean Oil:Crude degummed oil extracted through solvent processing flows primarily into renewable diesel hydroprocessing facilities under EPA blending mandates. Coastal US refineries are redirecting domestic crush capacity away from export channels to capture RIN value.
- Soy Milk:Aqueous emulsion of soy proteins and lipids positioned in developed retail channels commands unit margins substantially above commodity meal. Japanese and North American beverage processors lead formulation innovation.
- Tofu:Coagulated soy protein curd requiring controlled fermentation cycles serves East Asian foodservice and Western plant-based retail segments. Production batch timelines extend well beyond oilseed crush schedules.
Whole soybeans anchors the volume base while soy milk gains share at the steepest rate.
End Use Industry:
Cost tier differentiation separates commodity feed applications from certified food-grade and renewable fuel offtake.
- Food and Beverage:Tofu, soy milk, and protein isolate applications require identity-preserved supply chains with GMO segregation and allergen controls. Shanghai and Guangzhou crushing clusters are shortening procurement cycles to serve this quality-sensitive segment.
- Animal Feed:Soybean meal dominates monogastric and ruminant livestock rations globally, with Brazilian processors lifting crush volumes as EU deforestation rules tighten. MAPA sanitary protocols now filter export eligibility.
- Biofuels:Renewable diesel and sustainable aviation fuel offtake is expanding most quickly under US EPA and California LCFS frameworks. Oil yields per acre determine crush economics for this margin-sensitive segment.
- Cosmetics:Refined oil derivatives for emollient applications occupy a niche position with stringent purity specifications. South Korean and Japanese formulators drive specification standards.
Animal feed commands the revenue base while biofuels climbs the fastest on policy support.
Distribution Channel:
Customer type fragmentation splits between bulk industrial procurement and fragmented retail consumption.
- Direct Sales:Long-term offtake contracts between crushers and integrated livestock operators or refiners are compressing as Chinese buyers shift toward monthly tenders. Santos and Paranaguá port processors face recontracting pressure.
- Retail:Packaged soy milk and tofu in developed markets requires cold chain logistics and brand investment. Urban Chinese consumers are pulling premium positioning for organic-certified products.
- E-commerce:Direct-to-consumer platforms for specialty tofu and fermented soy foods are gaining traction in Japan and South Korea. Fulfillment complexity limits scale.
- Wholesale:Aggregated volume sales to foodservice distributors and regional feed blenders remain the default channel for commodity meal. Price transparency platforms are eroding traditional broker margins.
Direct sales retains the volume anchor while e-commerce expands most quickly in niche segments.
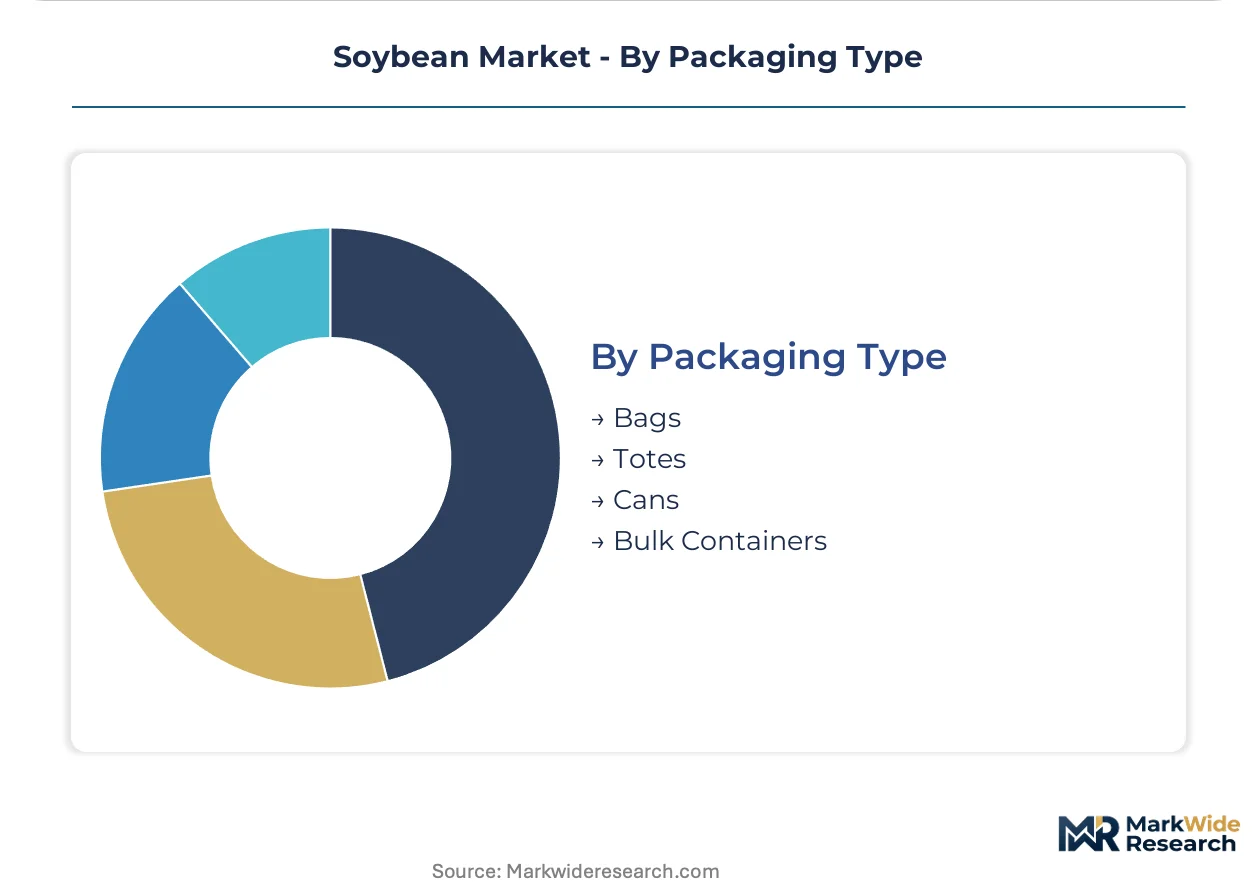
Packaging Type:
Supply concentration in bulk formats contrasts with dispersed specialty packaging for food-grade products.
- Bags:Multi-wall paper and woven polypropylene sacks serve foodservice tofu and retail soy flour segments. Chinese packaging converters dominate specification setting.
- Totes:Intermediate bulk containers for liquid soybean oil and protein concentrates bridge bulk and packaged formats. Midwest US processors favor this format for regional distribution.
- Cans:Aerosol and tinplate containers for culinary oils and spray applications carry premium positioning. Japanese retail channels maintain strict dimensional standards.
- Bulk Containers:Ocean freight vessels, rail hoppers, and river barges for whole soybeans and crude meal represent the dominant tonnage format. Brazilian interior-to-port logistics constraints favor this scale.
Bulk containers anchors the volume base while totes gains share at the steepest rate on flexibility demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA anchors regulatory frameworks across the dominant geography, with EPA biofuel mandates redirecting domestic crush flows and compressing exportable surpluses. Brazilian MAPA protocols and Chinese SAMR approval timelines create asynchronous friction points that reroute trade corridors.
United States
EPA Renewable Fuel Standard obligations and California LCFS credits are pulling soybean oil into renewable diesel hydroprocessing, redirecting Iowa and Illinois crush capacity away from export channels. The EPA regulates blending obligations that directly shape domestic demand concentration. Coastal US refineries in Texas and Louisiana are capturing RIN value premiums.
Brazil
MAPA sanitary protocols are tightening export eligibility benchmarks, accelerating consolidation among Mato Grosso farm cooperatives that can absorb documentation investments. The EU Green Deal deforestation regulation is forcing geolocation verification from farm gate to Atlantic ports. Santos and Paranaguá processors are retrofitting traceability systems to maintain European market access.
China
SAMR GMO approval timelines frequently lag Brasília trait clearances, forcing trade flow rerouting after planting commitments lock in. Shanghai and Guangzhou coastal crushing clusters are shortening procurement cycles from quarterly to monthly tenders. Guangdong province processors are building smaller, more frequent inventories to manage regulatory uncertainty.
Argentina
Export tax differentials between whole beans and processed derivatives are shaping crush investment decisions, with Rosario corridor processors expanding capacity to capture meal and oil value-add. The national agricultural regulator enforces quality benchmarks for export eligibility. Buenos Aires province crushing assets are repositioning to serve Brazilian deficit periods.
India
FSSAI food safety standards and DGFT import tariff structures are shaping domestic processing economics, with solvent extraction units in Madhya Pradesh and Maharashtra expanding to reduce import dependence. The central government's PLI scheme for edible oils is accelerating capacity additions. Gujarat port refineries are integrating with inland crushing clusters to shorten supply chains.
Soybean Market Vendor Landscape
Integrated trading houses and cooperative-backed processors split the market into distinct competitive spheres, with origination scale and logistics integration serving as primary differentiators. The structure concentrates around entities commanding river-to-port corridor control in Brazil and interior elevator networks in the US Midwest. Strategic archetypes include global merchandisers with balance-sheet capacity, regional crushers with origination ties, and cooperative aggregators with farmer financing relationships. Dominant competitive moves center on backward integration into farm-level traceability systems and strategic partnerships with renewable fuel refiners.
Among North American integrated processors, Archer Daniels Midland Company and Cargill, Incorporated occupy positions exemplifying scale-driven merchandising archetypes, with Cargill leveraging river logistics networks to anchor origination flows. Bunge Limited represents the coastal processing specialist model, competing through scale at Atlantic port facilities. These entities sit within a competitive matrix where origination financing relationships and compliance infrastructure investments determine access to premium market segments.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Bunge Limited |
| Louis Dreyfus Company |
| COFCO Corporation |
| Wilmar International Limited |
| Olam International |
| Golden Agri-Resources Ltd. |
| CHS Inc. |
| Others |
Supply Flow & Price Mechanics
Brazil's Paraná-Tieté waterway corridor cost dynamics compress exportable surplus windows for rival origins while amplifying price differentiation between EU Green Deal-compliant and conventional shipments. Supply concentration in Mato Grosso farm cooperatives concentrates origination power, translating into tiered pricing across traceability-verified and undocumented flows.
Pricing Analysis
Price spreads between Santos port export quotes and US Gulf delivered prices widen during peak Brazilian harvest compression, reflecting freight differentials and currency hedging costs. The market operates on a commodity spot-contract hybrid model, with quarterly offtake agreements giving way to monthly tenders as Chinese coastal crushers manage SAMR approval uncertainty. Price differentiation hinges on EU Green Deal geolocation certification and MAPA sanitary documentation completeness, with compliant shipments commanding substantial premia. Margins are tightening for inland US processors exposed to spot natural gas markets, while Brazilian port crushers capture RIN-linked value through renewable diesel offtake contracts. Livestock feed blenders exhibit highest price sensitivity, whereas food-grade soy milk processors absorb premia for identity-preserved supply chains.
Supply Chain Analysis
Extended payment terms from Mato Grosso farm cooperatives to Santos port processors, typically stretching ninety to one hundred twenty days, strain working capital and concentrate financing power among integrated trading houses. Supply concentrates in Brazil, the United States, and Argentina, with Brazilian interior-to-port logistics drawing from barge, rail, and truck modalities. Raw material flows hinge on glyphosate-tolerant seed traits, fertilizer nitrogen inputs, and diesel fuel for mechanical harvesting. Single-source vulnerability runs through the Paraná-Tieté-Paraguay waterway system, where drought-induced draft restrictions have historically stranded exportable surpluses. Distribution runs through long-term offtake contracts collapsing toward spot market procurement, with Chinese coastal crushers building smaller, more frequent inventories to manage regulatory uncertainty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traceability-as-a-service platforms represent the fastest-expanding recurring-revenue layer, outpacing commodity crush margins as EU Green Deal compliance mandates force farm-to-port monitoring investments across Brazilian origination networks.
For Market Incumbents: Insulate origination relationships by embedding pre-financing programs with Mato Grosso cooperatives, locking in volume commitments before planting windows close. Deepen backward integration into satellite-linked geolocation verification systems to capture EU Green Deal compliance premia. Defend against specialty food-grade entrants by accelerating high-shear extrusion retrofits that collapse energy costs per ton and preserve protein quality for branded ingredient positioning. For New Entrants and Emerging Players: India's solvent extraction capacity underpenetration in Madhya Pradesh and Maharashtra offers white-space entry, with FSSAI food safety standards creating certification barriers that favor capitalized newcomers over fragmented domestic processors. Target the soy milk and tofu segment in developed retail channels, where unit margins substantially exceed commodity meal and brand investment requirements filter competition. Pursue direct-to-ecommerce fulfillment partnerships with Japanese and South Korean platforms, bypassing established wholesale distribution chokepoints. For Investors and Strategic Acquirers: The EU Green Deal deforestation regulation reshapes the acquisition landscape by forcing geolocation verification infrastructure investments that favor balance-sheet-heavy integrated processors over cooperative-backed regional crushers. Long-term viability across the analysis window centers on entities commanding river-to-port corridor control with embedded traceability systems. Target acquisition archetypes include Mato Grosso cooperative aggregators with farmer financing relationships and compliance-ready documentation platforms. Watch for SAMR-MAPA biotech approval synchronization as the inflection signal that would reroute trade flows and reposition crush capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Traceability | EU Green Deal geolocation mandates force satellite-linked monitoring investments from Mato Grosso farm gates to Atlantic ports. |
| High-Shear Extrusion Retrofit Deployment | Iowa and Illinois processors cut natural gas consumption double-digits while preserving meal protein quality for renewable diesel offtake. |
| Renewable Diesel Refiner Partnership | Coastal US refineries in Texas and Louisiana capture RIN value premiums under EPA Renewable Fuel Standard obligations. |
| Monthly Tender Procurement Shift | Shanghai and Guangzhou crushers compress price discovery windows and amplify volatility transmission through shortened cycles. |
| Pre-Financing Program Expansion | Louis Dreyfus Company and integrated trading houses lock origination volumes with Mato Grosso cooperatives before planting commitments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with crushing operations managers, origination traders at Atlantic port facilities, renewable diesel refinery procurement leads, and MAPA compliance officers; alongside secondary validation through USDA crop progress reports, ANEC export vessel lineups, EPA RIN transaction disclosures, and Brazilian customs trade data. Bottom-up volume estimates from state-level crush capacity utilization triangulated against top-down demand projections from feed ration formulation models and biofuel blending obligation calculations.
Forecast inputs considered product type segmentation across whole soybeans, crude degummed oil, soy milk, and tofu derivatives; end-use industry splits between animal feed, biofuels, and food and beverage applications; and distribution channel dynamics spanning direct sales, wholesale, and emerging e-commerce platforms. CAGRs derived from historical volume trajectories adjusted for policy shock impacts, with renewable fuel mandate expansion rates and SAMR approval timeline volatility serving as key sensitivity drivers across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese coastal processors or coordinated farmer cooperative consolidation in Mato Grosso would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Oats Market
Grains
Rolled Oats Market
Grains
Triticale Market
Grains
North America Wheat Market
Grains
Brown Rice Market
Grains
Oat Flour Market
Grains
Africa Wheat Protein Market
Grains
Cornmeal Market
Grains
North America Wheat Protein Market
Grains
Millets Market
Grains
Organic Wheat Flour Market
Grains
Mexico Rice Market
Grains
Red Rice Market
Grains
Masa Corn Products Market
Grains
North America Oats Market
Grains
Asia-Pacific Guar Market