
 Southeast Asia Renewable Energy Market | 2026-2036
Southeast Asia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Renewable Energy Market Analytics
Project finance with long-term power purchase agreements is rewriting competitive access across Southeast Asia's renewable sector. Gulf Energy Development PCL leverages its balance sheet strength to dominate utility-scale solar in Thailand. ACEN Corp anchors its growth through geographic diversification across the Philippines, Vietnam, and Indonesia. Ørsted navigates offshore wind development with European technical standards adapted to tropical conditions.
Southeast Asia renewable energy encompasses electricity generation from solar photovoltaic, onshore and offshore wind, biomass combustion, and run-of-river hydro systems, typically feeding into national grids or islanded industrial microgrids at voltages from 22 kV to 500 kV. Solar photovoltaic dominates capacity additions due to module cost declines and high irradiance levels exceeding 1,500 kWh per square meter annually across equatorial zones. Wind installations concentrate in Vietnam's Ninh Thuan province and southern Thailand where monsoon patterns sustain capacity factors above 35 percent. Hybrid deployment models combining solar with battery storage are capturing margin pools as grid stability requirements tighten across archipelagic geographies.
Indonesia's Ministry of Energy and Mineral Resources sets renewable portfolio obligations for state utility PLN, while Vietnam's Power Development Plan 8 mandates private participation in transmission buildout. The Philippines Energy Regulatory Commission governs feed-in tariff eligibility and net metering standards for rooftop solar. Stakeholders must monitor regulatory clarity on cross-border power trading mechanisms between Laos, Thailand, and Singapore as regional grid integration advances.
Market Dynamics
Feed-in tariff revisions across Indonesia and the Philippines are redirecting capital flows toward hybrid solar-storage configurations, compressing development timelines and altering competitive positioning among independent power producers.
Growth Catalysts
- Power Development Plan 8:Vietnam's framework mandates private participation in transmission buildout, opening grid infrastructure to non-state capital.
- Industrial manufacturing clusters:Grid-scale solar procurement by electronics and textile producers in Vietnam and Thailand is accelerating offtake contracting.
- High irradiance zones:Equatorial solar resources exceeding 1,500 kWh per square meter annually are collapsing levelized cost thresholds for photovoltaic deployment.
Market Restraints
- Polysilicon supply concentration:Input cost volatility from Chinese ingot and wafer production creates margin pressure for Southeast Asian developers.
- Archipelagic grid fragmentation:Technical limitation in inter-island transmission constrains renewable absorption in Indonesia's eastern provinces.
- Cross-border trading ambiguity:Regulatory friction in Lao-Thai-Singapore power wheeling mechanisms delays regional market integration.
Strategic Opportunities
- Mindanao geothermal-solar zones:Underpenetrated geography in the Philippines southern island offers untapped hybrid resource pairing.
- Battery storage convergence:Technology convergence between lithium-ion systems and photovoltaic inverters enables islanded industrial microgrids.
- Net metering expansion:Regulatory tailwind from Philippines Energy Regulatory Commission standards unlocks commercial rooftop solar financing.
Industry Challenges
- Offshore wind installation expertise:Talent gap in jack-up vessel operations and subsea cable laying constrains Vietnam's Ninh Thuan pipeline.
- Geothermal exploration permits:Licensing complexity with Indonesia's Ministry of Energy and Mineral Resources extends pre-construction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Renewable Energy Market |
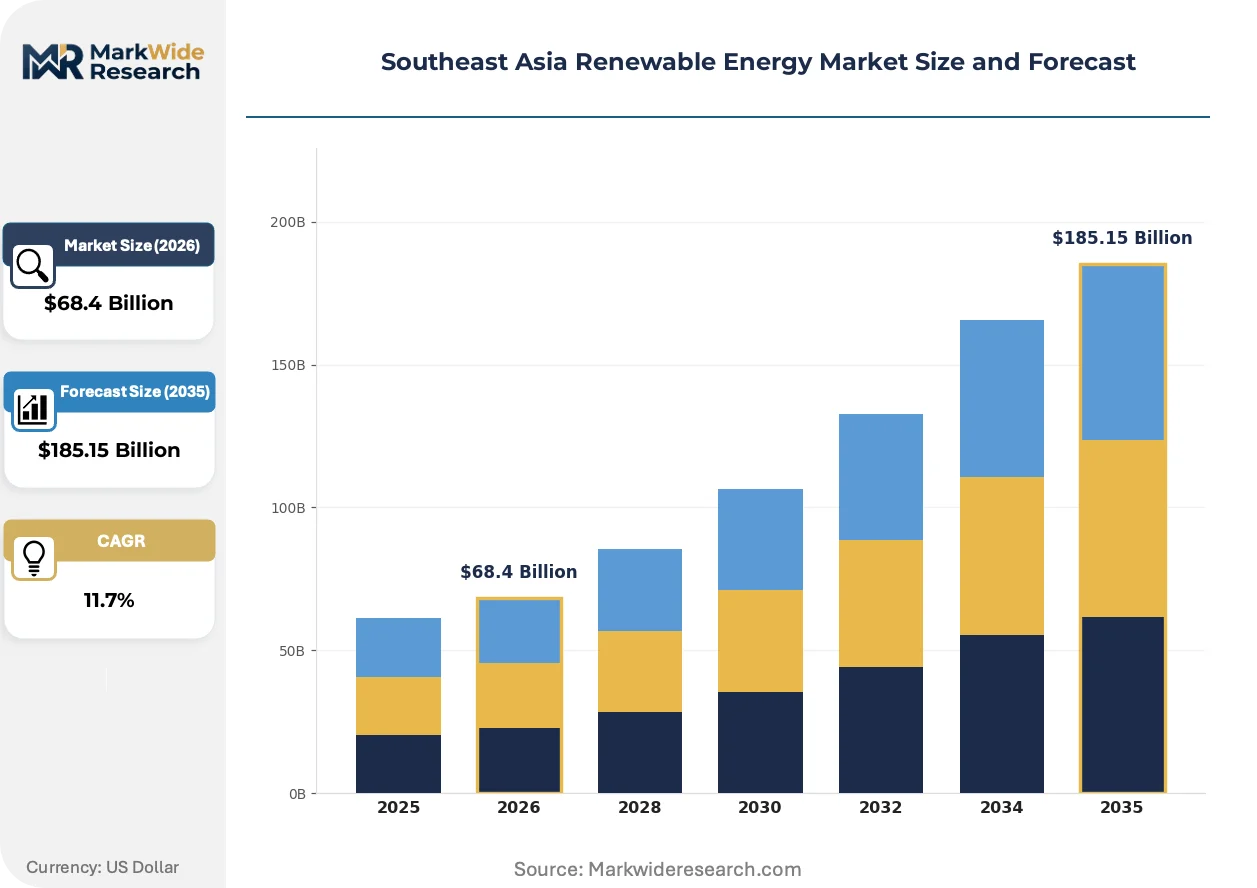
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro End User: Residential, Commercial, Industrial, Government Deployment: On-grid, Off-grid, Hybrid, Community Service Type: Consulting, Installation, Maintenance, Financing |
| Companies Covered | B.Grimm Power PCL, Gulf Energy Development PCL, ACEN Corp, Vena Energy, BCPG PCL, Power Construction Corporation of China, China Southern Power Grid Company, Keppel Corp, Ørsted, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Renewable Energy Market Evolving Landscape
Technology cost curves and regulatory redesign are compressing traditional development models across Southeast Asia's renewable sector. Three forces dominate the current transformation.
Bifacial photovoltaic modules with tracking systems are collapsing single-axis installation economics for utility-scale developers. Industrial offtakers in Vietnam's central coast provinces are adopting these configurations at pace, eliminating the premium that fixed-tilt systems once commanded in high-irradiance zones.
Indonesia's renewable portfolio obligations for state utility PLN are redirecting procurement toward hybrid dispatchable capacity. The mandate forces PLN to contract solar-plus-storage rather than pure photovoltaic, altering developer bid strategies and equipment sourcing patterns across the archipelago.
Corporate power purchase agreements are displacing traditional feed-in tariff dependence for Southeast Asian manufacturers. Electronics clusters in Thailand's Eastern Economic Corridor are negotiating direct renewable supply contracts, bypassing utility intermediaries and establishing price certainty independent of grid tariff fluctuations.
Southeast Asia Renewable Energy Market Segmentation
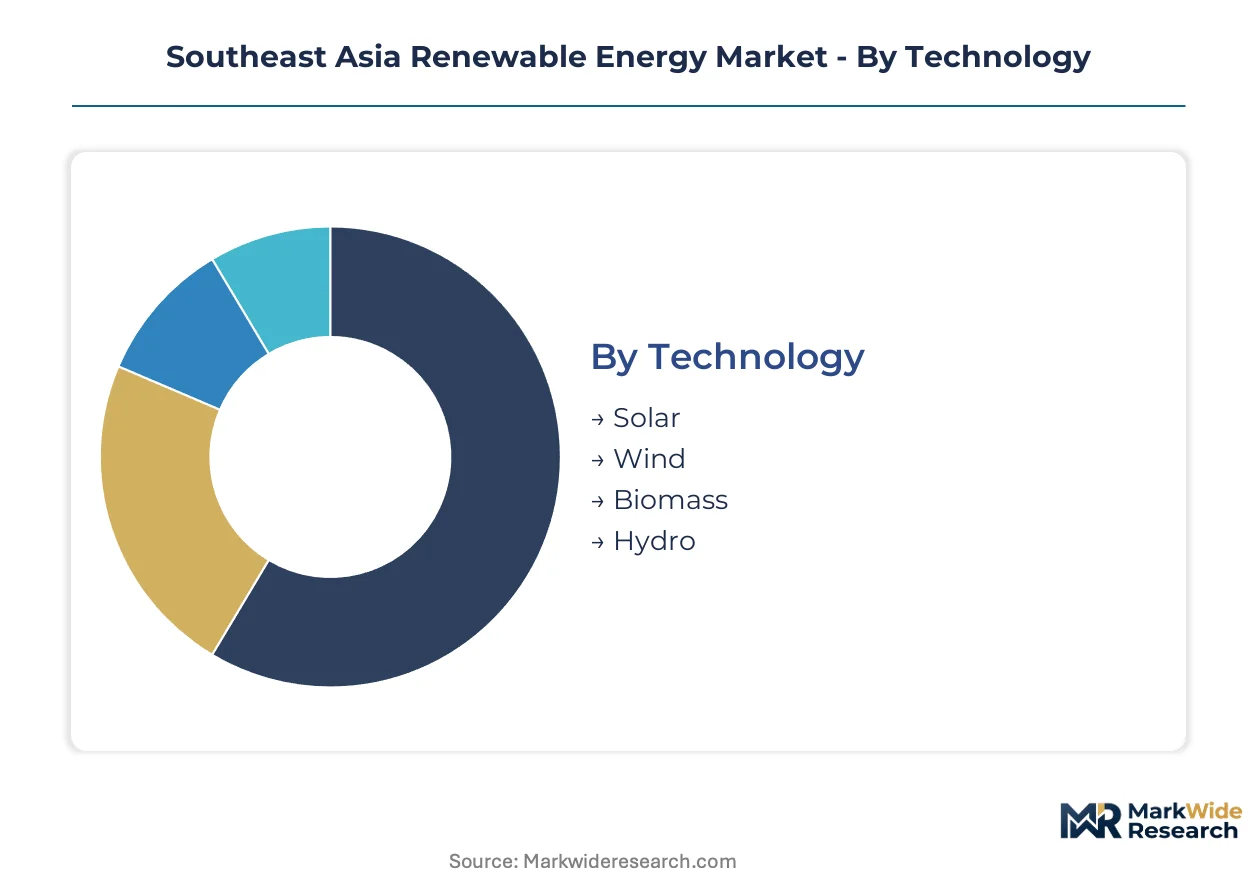
Segmentation reveals how capital allocation and development timelines diverge across Southeast Asia's renewable sector. Technology choices determine project payback periods, while deployment models dictate regulatory exposure and offtake risk.
Technology:
Photovoltaic modules turn over fastest as manufacturers release efficiency upgrades annually, while geothermal and large hydro assets operate across decades with minimal technology refresh cycles.
- Solar:Photovoltaic systems utilizing monocrystalline and bifacial modules dominate capacity additions across Vietnam's central coast and Thailand's Eastern Economic Corridor. Industrial manufacturing clusters in these geographies are procuring grid-scale installations directly, bypassing traditional utility intermediaries.
- Wind:Onshore turbines concentrate in Vietnam's Ninh Thuan province and southern Thailand where monsoon patterns sustain capacity factors above 35 percent. Offshore development faces constraints from limited jack-up vessel availability and subsea cable installation expertise.
- Biomass:Agricultural residue combustion systems serve rural industrial heat demand across Indonesia's palm oil processing belt.
- Hydro:Run-of-river installations feed islanded grids in the Philippines' Mindanao region and Laos' export-oriented generation base.
Solar dominates installed base. Wind is where expansion concentrates.
End User:
Cost tiers separate premium industrial offtakers seeking price certainty from residential segments dependent on net metering subsidies.
- Industrial:Electronics and textile manufacturers in Vietnam and Thailand negotiate corporate power purchase agreements directly with developers, establishing renewable supply contracts independent of grid tariff fluctuations.
- Commercial:Retail and logistics facilities across Metro Manila and Bangkok deploy rooftop photovoltaic under Philippines Energy Regulatory Commission net metering standards.
- Residential:Distributed solar installations remain concentrated in Thailand's urban periphery where financing mechanisms have matured.
- Government:State utility PLN in Indonesia contracts renewable capacity under renewable portfolio obligations mandating solar-plus-storage configurations.
Industrial offtakers command premium pricing for certainty. Commercial rooftops represent the steepest expansion trajectory.
Deployment:
Application logic separates grid-connected utility-scale projects from islanded configurations serving archipelagic geography.
- On-grid:Utility-scale solar and wind feed national transmission networks at 115 kV to 500 kV across Vietnam, Thailand, and the Philippines.
- Hybrid:Solar-plus-battery configurations are capturing margin pools as Indonesia's renewable portfolio obligations force dispatchable capacity procurement.
- Off-grid:Diesel displacement systems serve Indonesia's eastern provinces where inter-island transmission constraints prevent grid absorption.
- Community:Shared renewable models operate in the Philippines' missionary electrification zones.
On-grid deployments anchor current capacity. Hybrid systems are gaining share fastest.
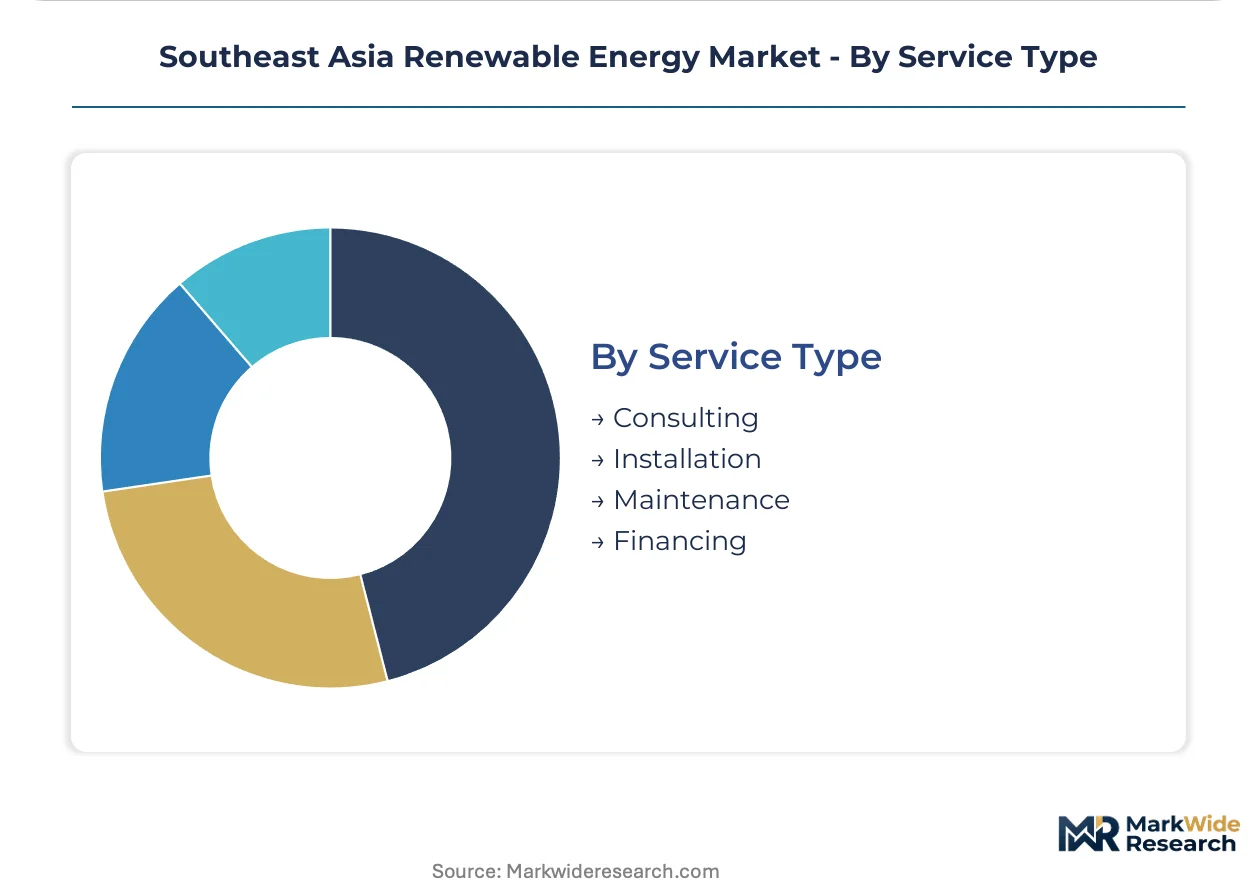
Service Type:
Customer type determines whether providers capture recurring revenue streams or one-time project margins.
- Installation:Engineering, procurement, and construction contracts for utility-scale solar dominate service revenue in Vietnam and Thailand.
- Financing:Project finance with long-term power purchase agreements is rewriting competitive access, with balance sheet strength determining developer market position.
- Maintenance:Operations and service contracts extend across 20-25 year asset lifespans for wind and geothermal installations.
- Consulting:Regulatory navigation services support foreign developers entering Indonesia's geothermal exploration permitting process.
Installation commands current revenue concentration. Financing is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam commands premium offtake pricing for central coast wind while Indonesia's eastern archipelago struggles with inter-island transmission constraints that suppress developer returns. This pricing-power asymmetry concentrates capital deployment in mainland Southeast Asia.
Vietnam
Electronics manufacturers in Bac Ninh and Thai Nguyen provinces are procuring grid-scale solar directly through corporate power purchase agreements. Vietnam's Power Development Plan 8 mandates private participation in transmission buildout, opening 500 kV infrastructure to non-state capital. The Ninh Thuan wind corridor anchors offshore development where monsoon patterns sustain capacity factors above 35 percent.
Thailand
Textile and automotive suppliers in the Eastern Economic Corridor are negotiating renewable supply contracts independent of utility intermediaries. The country's feed-in tariff revisions redirect procurement toward hybrid solar-storage configurations. Gulf Energy Development PCL leverages balance sheet strength to dominate utility-scale solar deployment across the corridor's industrial zones.
Indonesia
Palm oil processors in Sumatra and Kalimantan drive agricultural residue combustion demand for rural industrial heat. The Ministry of Energy and Mineral Resources sets renewable portfolio obligations for state utility PLN, forcing dispatchable capacity procurement. Eastern provinces from Papua to Nusa Tenggara face absorption constraints where inter-island transmission cannot accommodate renewable generation.
Philippines
Commercial retail and logistics facilities across Metro Manila deploy rooftop photovoltaic under Energy Regulatory Commission net metering standards. Feed-in tariff eligibility revisions redirect capital toward hybrid deployment models. Mindanao's geothermal-solar zones in the southern island remain underpenetrated, offering untapped resource pairing for developers.
Singapore
Data center operators and semiconductor fabs drive premium demand for renewable supply certainty. Regulatory frameworks governing cross-border power trading with Laos and Thailand remain unresolved, delaying regional market integration. The city-state's limited land area forces reliance on imported renewable generation through regional grid interconnection.
Southeast Asia Renewable Energy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The competitive structure concentrates around balance sheet strength and long-term power purchase agreement execution capability. Three archetypes dominate: Thai conglomerate-backed utilities with domestic transmission access, Philippine diversifiers with multi-country portfolios, and European offshore wind specialists adapting technical standards to tropical conditions. Dominant competitive moves include geographic diversification across regulatory jurisdictions and hybrid technology portfolio expansion.
Within the conglomerate-backed tier, Gulf Energy Development PCL and B.Grimm Power PCL represent the Thai utility archetype with established domestic market positions. ACEN Corp exemplifies the geographic diversification strategy across Philippines, Vietnam, and Indonesia markets. Ørsted occupies the European technical specialist position for offshore wind development.
| Leading Market Players |
|---|
| B.Grimm Power PCL |
| Gulf Energy Development PCL |
| ACEN Corp |
| Vena Energy |
| BCPG PCL |
| Power Construction Corporation of China |
| China Southern Power Grid Company |
| Keppel Corp |
| Ørsted |
| Others |
Value Network & Pricing Analysis
Polysilicon supply concentration in Chinese ingot and wafer production determines both three-tier pricing structure spreads across premium, standard, and economy module tiers and the geographic shape of Southeast Asian developer procurement networks. This single-source dependency feeds cost volatility directly into project finance structures, compressing margins for independent power producers while rewarding balance sheet-heavy conglomerates with captive sourcing arrangements.
Pricing Analysis
Industrial OEM buyers anchor long-term power purchase agreement pricing across Vietnam and Thailand. Three-tier pricing structure across premium, standard, and economy levels separates bifacial tracking configurations from fixed-tilt installations from off-grid diesel displacement systems. Cost compression in standard-tier utility-scale solar is intensifying because Chinese module oversupply floods procurement pipelines. Electronics manufacturers in Bac Ninh province demonstrate lowest price sensitivity, while rural Indonesian offtakers dependent on missionary electrification subsidies face acute margin pressure.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates supply chain risk calculations for Southeast Asian developers. Manufacturing concentrates in China, Vietnam, and Thailand for module assembly, inverter production, and balance-of-system components. Polysilicon ingots, lithium-ion cells, and high-voltage transformers feed from concentrated upstream sources. Single-source vulnerability in jack-up vessel availability constrains Vietnam's Ninh Thuan offshore pipeline. Distribution runs through EPC contractor networks with established relationships to state utility procurement officers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia's renewable sector tracks a cyclical recovery pattern tied to feed-in tariff revision cycles, with capital deployment accelerating as Indonesia and the Philippines clarify hybrid procurement mandates.
For Market Incumbents: Insulate project margin structures through backward integration into module assembly and inverter manufacturing. Gulf Energy Development PCL's balance sheet strength allows direct supplier negotiations that bypass volatile spot markets. Capacity addition in Vietnam's central coast wind corridor locks in monsoon resource access before offshore installation expertise scarcity worsens. Certification investment in PLN's renewable portfolio obligation compliance standards protects Indonesian market position against regulatory uncertainty.
For New Entrants and Emerging Players: Mindanao's geothermal-solar zones in the Philippines southern island represent the most penetrable entry point for hybrid resource pairing. Net metering expansion under Energy Regulatory Commission standards unlocks commercial rooftop solar financing across Metro Manila retail and logistics facilities. Direct corporate power purchase agreement origination with electronics manufacturers bypasses utility intermediary dependence and establishes price certainty independent of grid tariff fluctuations.
For Investors and Strategic Acquirers: Vietnam's Power Development Plan 8 implementation reshapes the acquisition landscape by mandating private transmission buildout participation. The five-to-ten year viability window favors developers with demonstrated power purchase agreement execution capability across multiple regulatory jurisdictions. Acquisition target archetype: Philippine diversifiers with multi-country portfolios spanning Indonesia geothermal exploration permits and Vietnamese solar deployment. Cross-border power trading mechanism clarity between Laos, Thailand, and Singapore serves as the critical inflection indicator for regional market integration plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Origination | Direct contracting with Bac Ninh electronics manufacturers secures offtake certainty independent of PLN tariff fluctuations. |
| Backward Integration into Module Assembly | Captive polysilicon sourcing insulates Thai developers from Chinese wafer price volatility and margin compression. |
| Hybrid Solar-Storage Deployment | Indonesia's renewable portfolio obligations force dispatchable capacity procurement, capturing premium margin pools. |
| Offshore Wind Installation Capability | Jack-up vessel access and subsea cable expertise unlock Vietnam's Ninh Thuan monsoon corridor capacity factors above 35 percent. |
| Net Metering Financing Structures | Philippines Energy Regulatory Commission standards enable commercial rooftop solar deployment across Metro Manila logistics facilities. |
Research Methodology
The analysis maps utility-scale solar, onshore wind, offshore wind, geothermal, and hybrid storage configurations, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary interviews with Thailand's Eastern Economic Corridor textile procurement leads and Vietnam's central coast electronics manufacturing clusters combined with secondary validation from IEA renewable deployment databases, FERC-style regulatory filings, and project finance transaction records. Bottom-up capacity addition tracking and top-down regulatory framework assessment enable triangulation across stakeholder perspectives.
Assumptions held fixed include current feed-in tariff structures and existing cross-border trading ambiguity, while technology cost curves and renewable portfolio obligation enforcement timelines varied across scenario modeling. Segmentation dimensions span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed base progression and annual capacity addition run-rates. Forecast inputs incorporate polysilicon price trajectory assumptions and jack-up vessel availability constraints for offshore development.
Practitioners should monitor feed-in tariff revision announcements and cross-border power trading mechanism developments for early signals of capital flow redirection. Forecasts reflect assumptions about regulatory enforcement consistency and technology cost curve trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Wave Energy Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Renewable Energy in South America Market