
 Biogas Upgrading Technology Market | 2026-2036
Biogas Upgrading Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Biogas Upgrading Technology Market Outlook
The energy company end-user segment is pivoting toward agricultural and landfill-sourced biomethane offtake agreements. Air Liquide leverages its industrial gas infrastructure to anchor large-scale membrane separation deployments across European biogas clusters. Greenlane Renewables specializes in water scrubbing systems for North American dairy and swine operations, while DMT Environmental Technology dominates chemical scrubbing installations for municipal wastewater treatment plants in the Netherlands and Belgium.
Biogas upgrading technology encompasses physical and chemical processes that remove carbon dioxide, hydrogen sulfide, moisture, and trace contaminants from raw biogas to produce pipeline-quality biomethane exceeding 96% methane content. Pressure swing adsorption systems using activated carbon or zeolite molecular sieves achieve methane recovery rates above 97% through cyclic pressure variations, serving grid injection specifications. Membrane separation is capturing the fastest growth trajectory as hollow-fiber polymer membranes reduce energy intensity versus amine scrubbing, while chemical scrubbing retains margin pools in high-sulfur feedstock applications where selective amines protect downstream catalysts.
The EU Green Deal and F-Gas Regulation are tightening methane leakage monitoring requirements for biomethane grid injection across Germany, France, and Denmark, forcing upgrading plant operators to install continuous emissions verification. Germany's Federal Network Agency and France's CRE are revising feed-in tariffs to favor biomethane with sub-1% methane slip, redirecting capital toward adsorption and cryogenic upgrading systems. Stakeholders must monitor how national renewable gas certificate schemes in Scandinavia and the Low Countries integrate with the EU hydrogen blending framework, as this will determine whether upgrading assets compete with or complement power-to-gas electrolyzers.
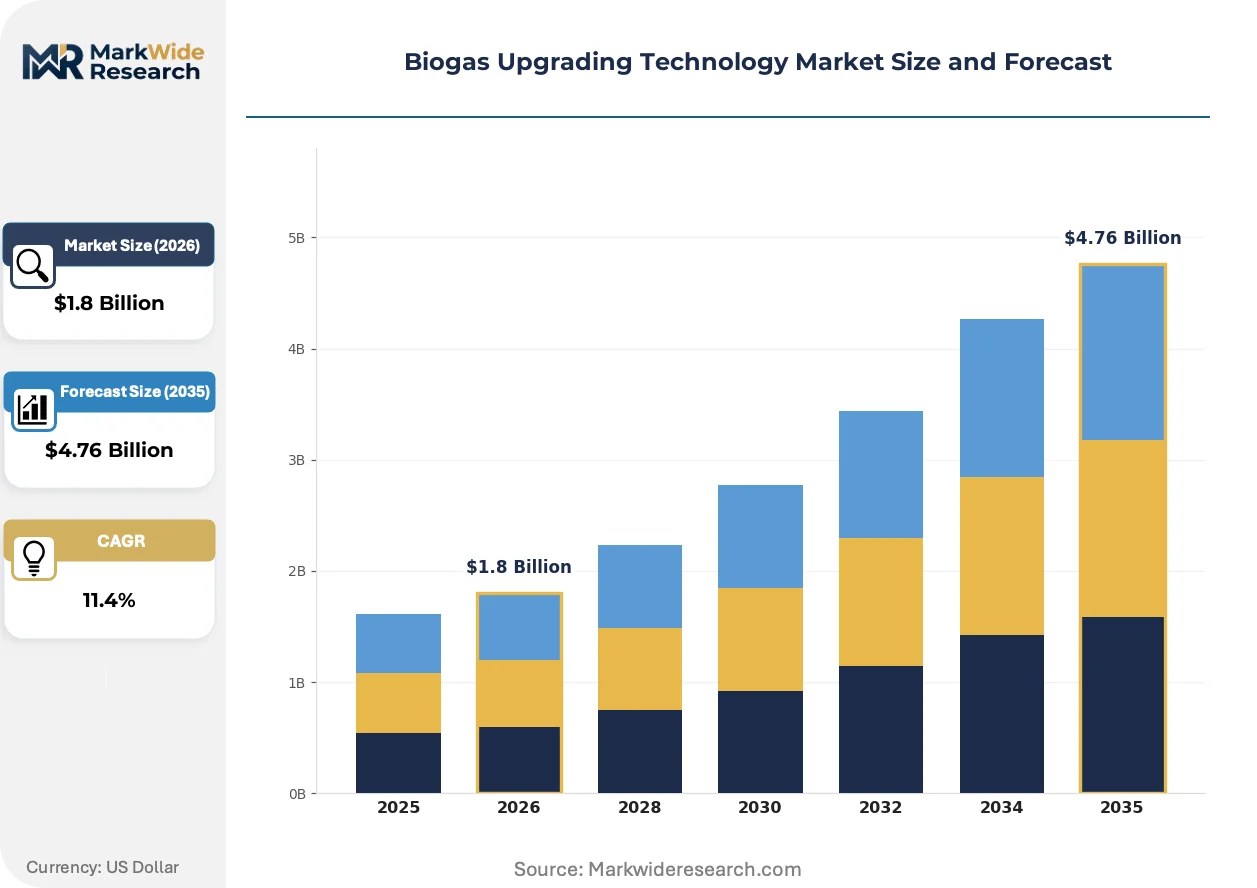
Market Dynamics
Membrane separation systems are compressing energy intensity benchmarks across European upgrading clusters while EU methane slip regulations force capital reallocation toward adsorption and cryogenic platforms.
Growth Catalysts
- EU F-Gas Regulation:Tightening methane leakage thresholds for grid injection are redirecting investment toward continuous emissions monitoring infrastructure in Germany and Denmark.
- Agricultural feedstock streams:Dairy and swine operations in North America are scaling anaerobic digestion capacity, creating dedicated demand for water scrubbing and membrane separation systems.
- Power-to-gas hub development:Chemical scrubbing installations are anchoring industrial biomethane offtake in Germany's Rhine-Ruhr corridor, linking upgrading assets to hydrogen blending pilot networks.
Market Restraints
- Amine cost volatility:Selective amine solvents for high-sulfur chemical scrubbing face feedstock price instability tied to petrochemical supply chains.
- Zeolite supply concentration:Molecular sieve manufacturing for pressure swing adsorption concentrates among limited specialty chemical producers in Germany and Japan.
- Cryogenic energy penalty:Ultra-low temperature upgrading systems face inherent thermodynamic efficiency limits that constrain deployment to premium grid injection specifications.
Strategic Opportunities
- Scandinavian certificate integration:National renewable gas guarantee schemes in Sweden and Norway are converging with EU hydrogen blending frameworks, creating hybrid asset valuation models.
- Landfill gas upgrading:Municipal waste recovery sites in France and Belgium represent underpenetrated feedstock streams for membrane separation retrofits.
- Membrane-cryogenic hybridization:Combining hollow-fiber polymer membranes with cryogenic polishing stages is opening sub-0.5% methane slip performance tiers for premium industrial offtake.
Industry Challenges
- Process control engineering scarcity:Operators struggle to recruit specialists capable of managing cyclic pressure variations in pressure swing adsorption systems at scale.
- Grid interconnection timelines:Biomethane injection certification from Germany's Federal Network Agency and France's CRE extends project commissioning windows by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biogas Upgrading Technology Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pressure Swing Adsorption, Membrane Separation, Water Scrubbing, Chemical Scrubbing Application: Power Generation, Biofuel Production, Natural Gas Injection, Vehicle Fuel End User: Agriculture, Wastewater Treatment Plants, Landfill Operators, Energy Companies Installation: On-site Systems, Centralized Facilities, Modular Units, Mobile Systems |
| Companies Covered | Air Liquide, EnviTec Biogas AG, Greenlane Renewables, Bright Renewables B.V., DMT Environmental Technology, Evonik Industries, Pentair, Xebec Adsorption, Atmos Power Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biogas Upgrading Technology Market Strategic Shifts
Technology convergence between upgrading platforms and hydrogen infrastructure is redefining asset valuation, while regulatory tightening on methane intensity forces equipment refresh cycles faster than historical replacement patterns.
Hollow-fiber polymer membranes are achieving selective CO2 permeation with 40% lower energy draw than conventional amine systems. Dairy and landfill operators in the Netherlands and Belgium are adopting these units for sub-megawatt scale installations. Membrane separation is integrating with power-to-gas electrolyzers, enabling shared compression and grid injection infrastructure that improves project economics.
The EU Green Deal's methane intensity thresholds are forcing continuous emissions verification systems at upgrading plants across Germany, France, and Denmark. France's CRE has revised feed-in tariffs to penalize methane slip above 1%, redirecting capital toward adsorption and cryogenic systems. Grid injection specifications in these markets now require sub-0.5% methane loss rates, compressing acceptable technology performance bands.
Long-term biomethane offtake agreements are displacing spot market transactions as the dominant procurement model. Energy companies in Germany's industrial corridor are signing 10-15 year supply contracts directly with agricultural digester operators. This contract structure is visible most acutely in the Rhine-Ruhr region, where chemical producers seek price certainty for renewable gas feedstock against volatile natural gas benchmarks.
Biogas Upgrading Technology Market Segmentation
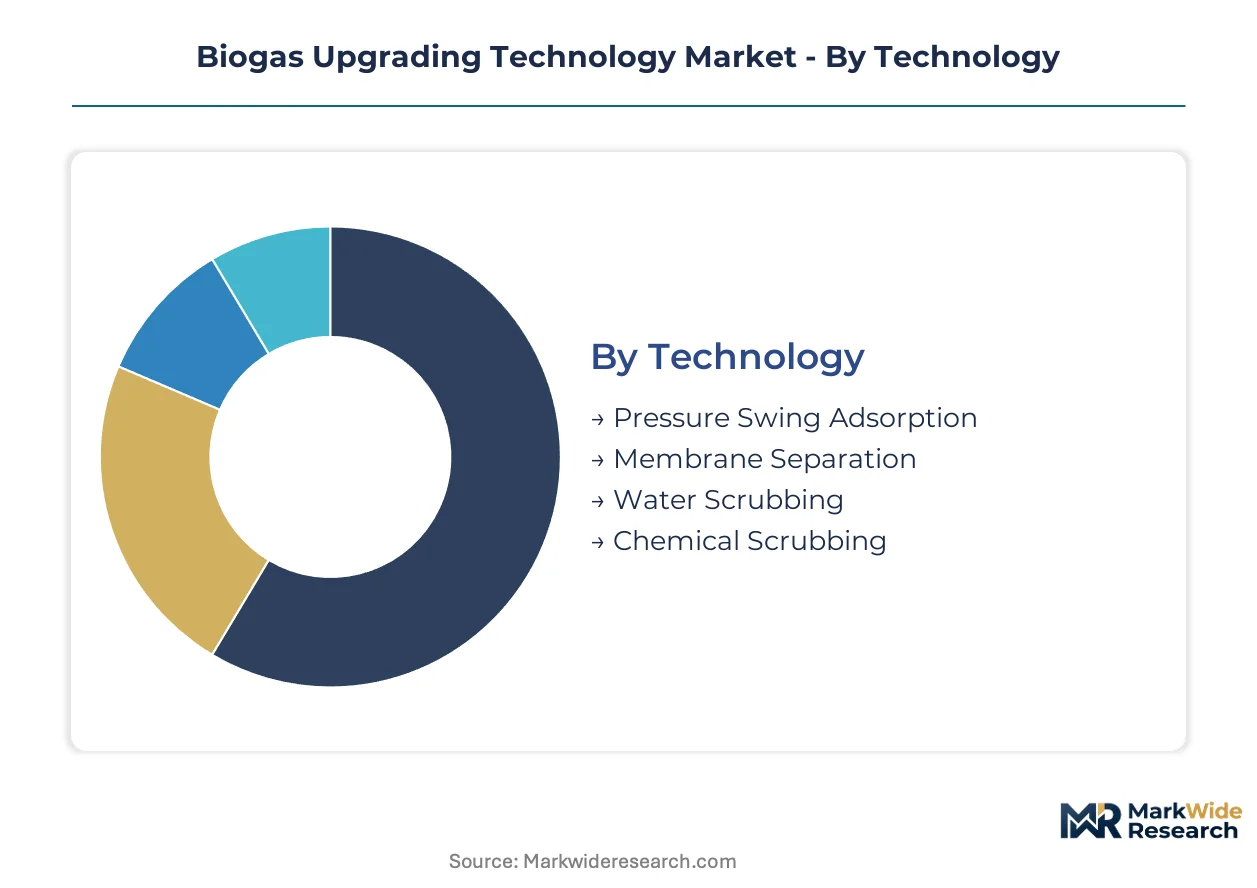
Biogas upgrading technology segments map directly to distinct certification burdens and capital intensity profiles. Technology choice determines methane recovery specifications, while application type dictates grid interconnection protocols and end-use certification pathways.
Technology:
Grid injection certification in Germany, France, and Denmark mandates specific methane purity thresholds that segment technologies by regulatory burden. France's CRE and Germany's Federal Network Agency enforce sub-1% methane slip standards that favor certain upgrading platforms.
- Pressure Swing Adsorption:Cyclic pressure variations through activated carbon or zeolite molecular sieves achieve methane recovery above 97%. Demand concentrates in Germany's Rhine-Ruhr industrial corridor where chemical producers require consistent pipeline-quality output for power-to-gas hub integration.
- Membrane Separation:Hollow-fiber polymer membranes reduce energy intensity by 40% versus amine systems while maintaining selective CO2 permeation. Dairy and swine operations in the Netherlands and Belgium deploy these for sub-megawatt installations where continuous emissions monitoring satisfies EU F-Gas Regulation requirements.
- Water Scrubbing:Physical absorption using water as solvent serves agricultural digesters with lower sulfur content.
- Chemical Scrubbing:Selective amine systems protect downstream catalysts in high-sulfur landfill and wastewater applications.
Leading the category by volume: Pressure Swing Adsorption. Expanding most quickly: Membrane Separation.
Application:
Application segments diverge by revenue model stability and offtake contract duration, with industrial procurement patterns favoring long-term supply agreements over spot market transactions.
- Natural Gas Injection:Pipeline-quality biomethane exceeding 96% methane content requires continuous emissions verification under EU Green Deal methane intensity thresholds. Germany's industrial corridor anchors demand as chemical producers sign 10-15 year offtake agreements with agricultural digester operators.
- Power Generation:Biomethane-fired combined heat and power plants serve district heating networks in Denmark and Sweden where renewable gas certificate schemes integrate with national energy transition frameworks.
- Biofuel Production:Liquefied biomethane for transport applications faces vehicle certification protocols.
- Vehicle Fuel:Compressed biomethane filling stations require fuel quality standards alignment with EU transport decarbonization mandates.
Highest contract duration stability: Natural Gas Injection. Steepest expansion trajectory: Biofuel Production.
End User:
End user segments reflect feedstock availability and digester scale economics, with agricultural streams offering volume growth and landfill sites presenting retrofit opportunities.
- Agriculture:Dairy and swine operations in North America scale anaerobic digestion capacity with dedicated water scrubbing and membrane separation demand. Farm-scale installations in the Netherlands cluster near existing natural gas distribution infrastructure.
- Landfill Operators:Municipal waste recovery sites in France and Belgium represent underpenetrated feedstock streams where membrane separation retrofits capture methane from decomposing organic waste.
- Wastewater Treatment Plants:Municipal facilities in the Netherlands and Belgium deploy chemical scrubbing for high-moisture biogas streams.
- Energy Companies:Industrial gas offtakers anchor large-scale upgrading investments through procurement agreements.
Deepest feedstock reserves: Agriculture. Fastest project commissioning: Landfill Operators.
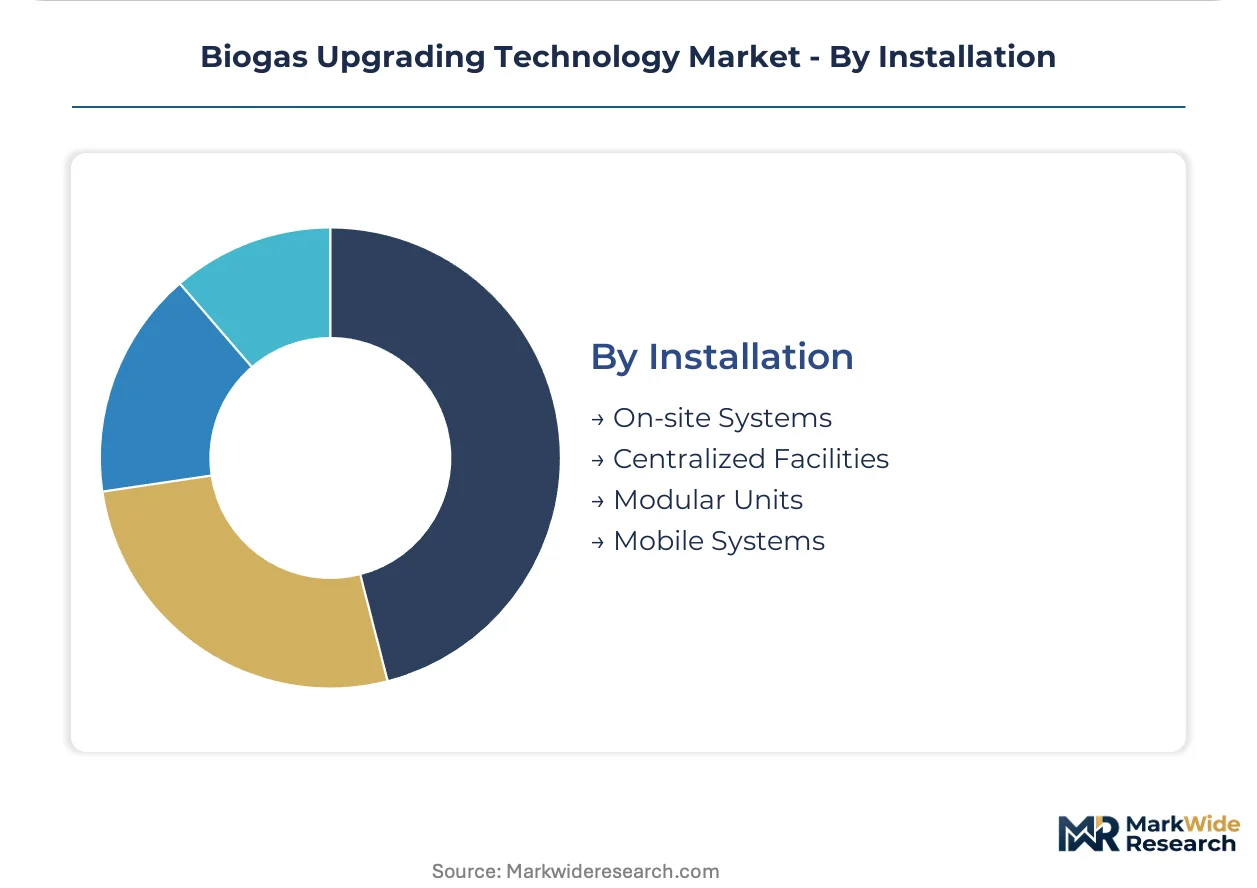
Installation:
Installation architecture determines capital deployment flexibility and geographic mobility, with modular formats gaining traction in distributed agricultural feedstock environments.
- Modular Units:Containerized upgrading systems enable rapid deployment across fragmented agricultural digester networks. Scandinavian operators favor these for seasonal biomass availability and remote grid interconnection challenges.
- Centralized Facilities:Large-scale installations serve multiple feedstock aggregators in Germany's industrial corridor where shared compression infrastructure improves project economics.
- On-site Systems:Dedicated upgrading at digester locations minimizes biogas transport losses.
- Mobile Systems:Temporary deployment formats serve pilot projects and emergency grid injection requirements.
Widest deployment flexibility: Modular Units. Highest throughput per installation: Centralized Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes more pipeline-quality biomethane than it produces domestically, drawing supply from Dutch and Danish upgrading clusters. France and the Netherlands export surplus capacity across border interconnectors, while Belgium and Denmark balance regional flows through certificate-trading mechanisms.
Germany
The Rhine-Ruhr industrial corridor anchors demand as BASF and Evonik sign long-term offtake agreements with agricultural digester operators. Germany's Federal Network Agency enforces sub-1% methane slip standards through revised feed-in tariffs. Chemical scrubbing installations concentrate in North Rhine-Westphalia, linking upgrading assets to hydrogen blending pilot networks at power-to-gas hubs.
France
Municipal landfill operators in Hauts-de-France are retrofitting membrane separation systems to capture methane from decomposing organic waste. France's CRE penalizes methane slip above 1% through tariff adjustments under EU Green Deal implementation. The Paris Basin hosts biomethane injection clusters serving compressed natural gas vehicle fleets and industrial heat users.
Netherlands
Dairy cooperatives in Gelderland and Overijssel deploy water scrubbing systems for sub-megawatt farm-scale installations. The Dutch national renewable gas certificate scheme integrates with EU hydrogen blending frameworks, creating hybrid asset valuation models. Rotterdam's port infrastructure enables liquefied biomethane export to maritime shipping clients.
Belgium
Wastewater treatment plants in Flanders deploy chemical scrubbing for high-moisture biogas streams from municipal digesters. Belgium's federal energy regulator aligns grid injection specifications with French and German methane intensity thresholds. The Port of Antwerp hosts upgrading facilities serving chemical producers seeking renewable feedstock alternatives.
Denmark
Agricultural digester networks in Jutland supply district heating plants through combined heat and power configurations. Danish energy policy mandates renewable gas certificate trading with Swedish and Norwegian schemes. Copenhagen's power-to-gas pilots test membrane-cryogenic hybrid systems for sub-0.5% methane slip performance.
Biogas Upgrading Technology Market Competitive Environment
Top-tier vendors anchor industrial gas infrastructure, while mid-tier specialists concentrate on regional feedstock applications. The vendor base organizes around three archetypes: diversified industrial gas conglomerates with membrane separation portfolios, dedicated biogas technology firms with water scrubbing specialization, and chemical process engineering houses with amine scrubbing expertise. Competitive moves center on strategic partnerships with agricultural cooperatives and technology licensing agreements for modular system deployment.
Within the industrial gas tier, Air Liquide and Evonik Industries occupy positions leveraging existing chemical plant infrastructure for large-scale upgrading integration. Greenlane Renewables exemplifies the dedicated biogas technology archetype, while DMT Environmental Technology represents regional engineering specialists. These three companies anchor distinct competitive vectors: industrial gas conglomerates compete on compression and grid injection integration, dedicated firms on agricultural feedstock relationships, and regional specialists on municipal wastewater and landfill gas applications.
| Leading Market Players |
|---|
| Air Liquide |
| EnviTec Biogas AG |
| Greenlane Renewables |
| Bright Renewables B.V. |
| DMT Environmental Technology |
| Evonik Industries |
| Pentair |
| Xebec Adsorption |
| Atmos Power Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive integration into hollow-fiber polymer membrane production anchors supply security for European upgrading vendors while compressing procurement costs against volatile zeolite import prices. This backward integration choice concentrates pricing power among Germany's industrial gas conglomerates that control both molecular sieve supply and compression infrastructure deployment.
Pricing Analysis
Short lead-time premiums of 15-25% apply to membrane separation systems needed for EU F-Gas Regulation compliance deadlines, while standard delivery windows attract volume discounts from agricultural cooperative buyers. Project-based pricing dominates, with chemical scrubbing installations commanding higher quotes for selective amine solvent bundles versus water scrubbing alternatives. Price differentiation centers on methane recovery certification tier and grid injection specification stringency, with sub-0.5% methane slip systems carrying substantial premiums. Cost compression in membrane modules is intensifying because hollow-fiber manufacturing scale-up in the Netherlands and Belgium feeds price competition. Municipal wastewater treatment plants exhibit highest price sensitivity due to constrained capital budgets, while Rhine-Ruhr chemical producers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Zeolite molecular sieve supply rests on specialty chemical producers concentrated in Germany and Japan, with activated carbon sourcing drawing from coconut shell processors in Southeast Asia and Eastern European coal derivative facilities. Hollow-fiber polymer membrane production feeds from petrochemical feedstocks with pricing tethered to ethylene oxide and polyimide precursor markets. Single-source vulnerability concentrates in high-purity zeolite manufacturing where two German suppliers dominate pressure swing adsorption system inputs. Distribution runs through industrial gas infrastructure partnerships that bundle compression, grid interconnection, and certificate trading services into turnkey procurement packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's methane intensity thresholds function as a cost-of-compliance moat, forcing equipment refresh cycles that favor incumbents with certified technology platforms and established emissions verification protocols.
For Market Incumbents: Hedge membrane separation margin erosion by deepening captive production of hollow-fiber polymers in the Netherlands and Belgium, while securing long-term zeolite supply agreements with German specialty chemical partners before feedstock volatility intensifies. Anchor defensive positioning through certification pre-approval with France's CRE and Germany's Federal Network Agency, creating switching costs for agricultural digester operators facing grid interconnection timelines. For New Entrants and Emerging Players: Enter via landfill gas upgrading retrofits in France's Hauts-de-France region and Belgium's Flanders corridor, where municipal waste recovery sites present underpenetrated feedstock streams with lower competitive density than agricultural markets. Target membrane-cryogenic hybrid system niches for premium industrial offtake in Denmark's power-to-gas pilot networks, leveraging modular deployment formats to compress project commissioning windows against centralized facility competition. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial gas conglomerates seeking regional technology platforms, with strategic value accruing to targets holding EU F-Gas Regulation certification and established agricultural cooperative relationships. Long-term viability hinges on technology portfolios spanning multiple upgrading chemistries rather than single-platform dependence. Watch EU hydrogen blending framework integration with national renewable gas certificate schemes as the inflection signal determining whether upgrading assets compete with or complement electrolyzer investments.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Manufacturing Scale-Up | Captive hollow-fiber production in the Netherlands reduces energy intensity benchmarks against amine system competition. |
| EU F-Gas Certification Pre-Approval | Early CRE and Federal Network Agency alignment compresses grid interconnection timelines for German and French deployments. |
| Long-Term Biomethane Offtake Agreements | 10-15 year supply contracts with Rhine-Ruhr chemical producers displace spot market volatility for revenue stability. |
| Membrane-Cryogenic Hybrid Development | Sub-0.5% methane slip performance tiers unlock premium industrial procurement in Denmark's power-to-gas hubs. |
| Agricultural Cooperative Partnerships | Direct relationships with Dutch dairy and Belgian swine operations secure dedicated feedstock streams for water scrubbing demand. |
Study Parameters
Trade association filings from the European Biogas Association, national renewable gas registry databases, and EU ETS emissions verification records formed the secondary backbone, cross-referenced against primary interviews with upgrading plant operators, EPC contractors, and agricultural digester developers. This study combined bottom-up project pipeline tracking with top-down regulatory impact modeling to triangulate technology deployment trajectories across the analysis window.
Historical trendline analysis of installed capacity and feedstock utilization rates informed the projection framework, with segmentation across technology type, application pathway, end-user category, and installation format. CAGRs derived from equipment shipment data and grid injection certification timelines, incorporating methane slip regulation stringency as a demand elasticity input alongside feedstock availability curves for agricultural and landfill streams.
Forecast precision tightens around the base case; tail outcomes carry wider variance under zeolite supply disruption scenarios or accelerated EU hydrogen blending mandates that could redirect capital toward electrolyzer competition. Forecasts reflect documented assumptions on regulatory implementation timelines and feedstock cost trajectories. A small set of named triggers—CRE tariff revision schedules, Federal Network Agency methane slip enforcement actions, and Scandinavian certificate integration protocols—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Farm Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Solar Cooker Market