
 Renewable Energy Monitoring and Control System Market | 2026-2036
Renewable Energy Monitoring and Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Monitoring and Control System Market Analytics
Chinese inverter and sensor manufacturers is broadening production capacity for grid-edge monitoring hardware. Siemens leverages deep automation expertise to anchor European utility contracts. Schneider Electric competes through integrated software-hardware platforms. GE Vernova sustains turbine-to-grid data pipelines across North American wind portfolios.
Renewable energy monitoring and control systems comprise sensor networks, communication gateways, and software platforms that collect real-time performance data from generation assets and execute automated dispatch commands with sub-second latency. These systems synchronize variable renewable output with grid frequency requirements, curtailment protocols, and predictive maintenance schedules. SCADA deployments dominate utility-scale installations where centralized visibility across dispersed solar and wind assets commands premium pricing. IoT sensor layers represent the fastest-expanding segment as distributed residential and commercial rooftop systems proliferate. Artificial Intelligence modules extract predictive failure signals from vibration, thermal, and electrical waveform data, concentrating margin pools in software analytics.
FERC Order 2222 in the United States, the EU Green Deal's digitalization mandates, and China's GB standards for grid-connected renewable equipment collectively reshape product certification requirements and market access conditions. Compliance with these frameworks determines eligibility for grid interconnection tariffs and capacity market participation. Stakeholders must track evolving cybersecurity standards for critical energy infrastructure as regulatory bodies harden data protection requirements for remote monitoring networks.
Market Dynamics
The convergence of variable renewable penetration with grid stability mandates is compressing dispatch latency requirements from minutes to sub-second intervals, forcing hardware-software co-design across SCADA and edge computing layers.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules unlock revenue streams for residential and commercial monitoring deployments across US wholesale markets.
- EU F-Gas Regulation:Tightened equipment standards accelerate sensor replacement cycles and drive demand for next-generation refrigerant monitoring in thermal management systems.
- Utility-scale solar expansion:Solar farm operators in China and the United States deploy centralized SCADA architectures to manage dispersed gigawatt-scale portfolios.
Market Restraints
- Semiconductor supply concentration:Analog-to-digital converter and power management IC sourcing bottlenecks from East Asian foundries delay sensor gateway production.
- Cybersecurity compliance costs:Critical infrastructure protection standards impose certification burdens that inflate product development timelines by 12-18 months.
- Legacy protocol fragmentation:Proprietary Modbus and DNP3 implementations complicate interoperability between equipment generations from different OEMs.
Strategic Opportunities
- India's renewable tender pipeline:Central and state-level solar-wind hybrid auctions create demand for integrated monitoring platforms across 500+ MW installations.
- Edge-AI convergence:On-device inference chips combined with vibration analytics enable predictive maintenance without cloud dependency for offshore wind assets.
- Performance-based O&M contracts:Asset owners in Germany now compensate service providers against availability guarantees, requiring granular production telemetry.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time operating systems faces talent shortages as automotive and aerospace sectors compete for the same skill pool.
- Multi-vendor integration complexity:Wind turbine SCADA retrofits must reconcile 15-20 year old control architectures with modern IoT middleware without production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Monitoring and Control System Market |
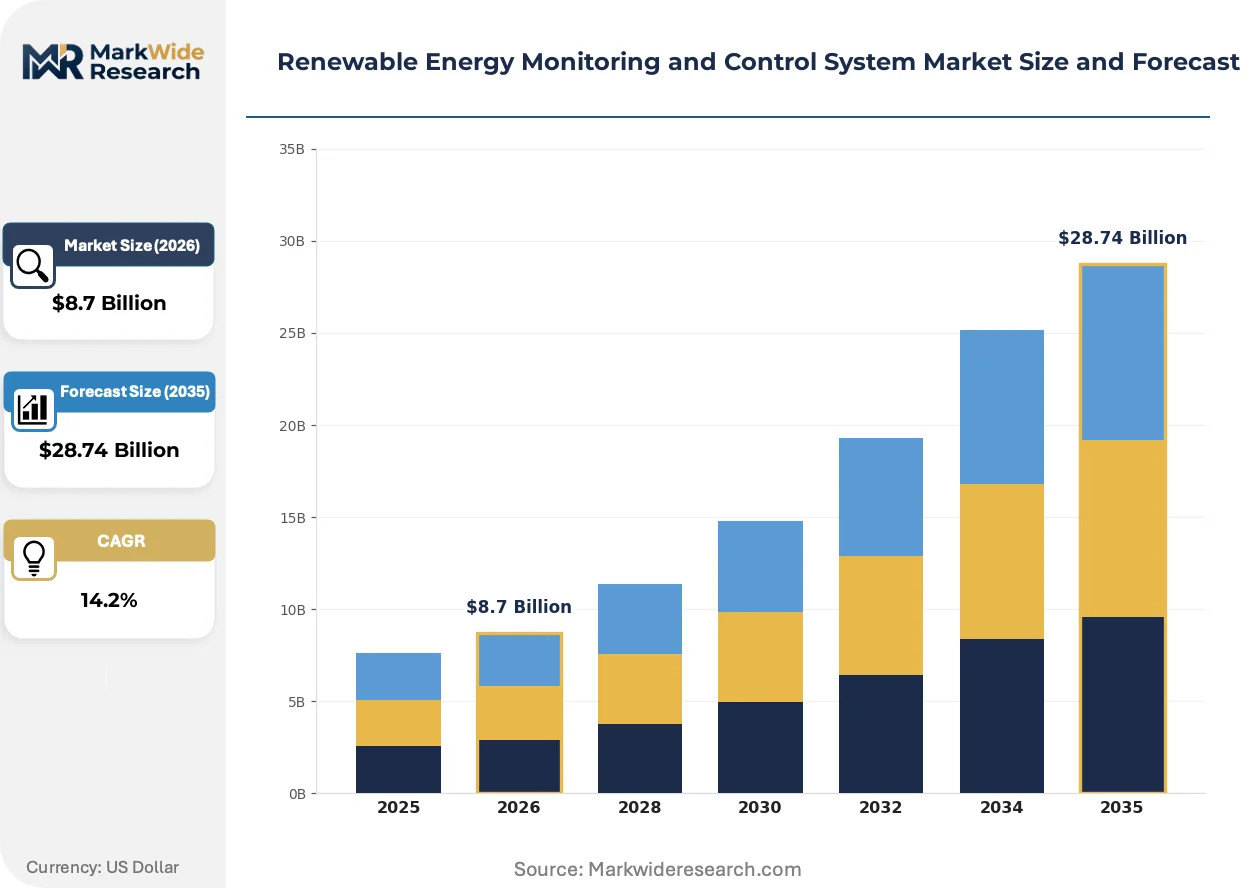
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SCADA, IoT, Artificial Intelligence, Blockchain Application: Solar Power, Wind Energy, Hydropower, Biomass End User: Utilities, Industrial, Commercial, Residential Solution: Hardware, Software, Services, Analytics |
| Companies Covered | Toshiba, Uplight, Siemens, Gantner Instruments, EnergyCAP, Schneider Electric, InfluxData, LineVision, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Monitoring and Control System Market Evolving Landscape
Digital twin architectures and synthetic data generation are compressing commissioning timelines while hardening control algorithms against edge-case grid events. These capabilities reshape competitive differentiation around software analytics rather than hardware reliability alone.
Digital twin platforms replicate physical renewable assets in virtual environments for control-loop testing before field deployment. Offshore wind developers in the North Sea adopt these tools to simulate wake effects and nacelle orientation strategies. This technology is integrating with SCADA historians to enable closed-loop optimization without risking actual generation assets.
The EU Green Deal's digitalization mandates require granular carbon accounting linked to production telemetry for capacity market eligibility. Equipment suppliers must embed emissions tracking into firmware by default. German and Spanish grid operators now reject interconnection applications lacking certified data provenance chains.
Asset owners increasingly unbundle hardware procurement from software subscriptions, treating monitoring platforms as operational expenses rather than capital projects. Danish and US independent power producers lead this shift, negotiating multi-year analytics licenses separate from sensor hardware. This purchasing pattern pressures incumbent vendors to restructure pricing and support models.
Renewable Energy Monitoring and Control System Market Segmentation
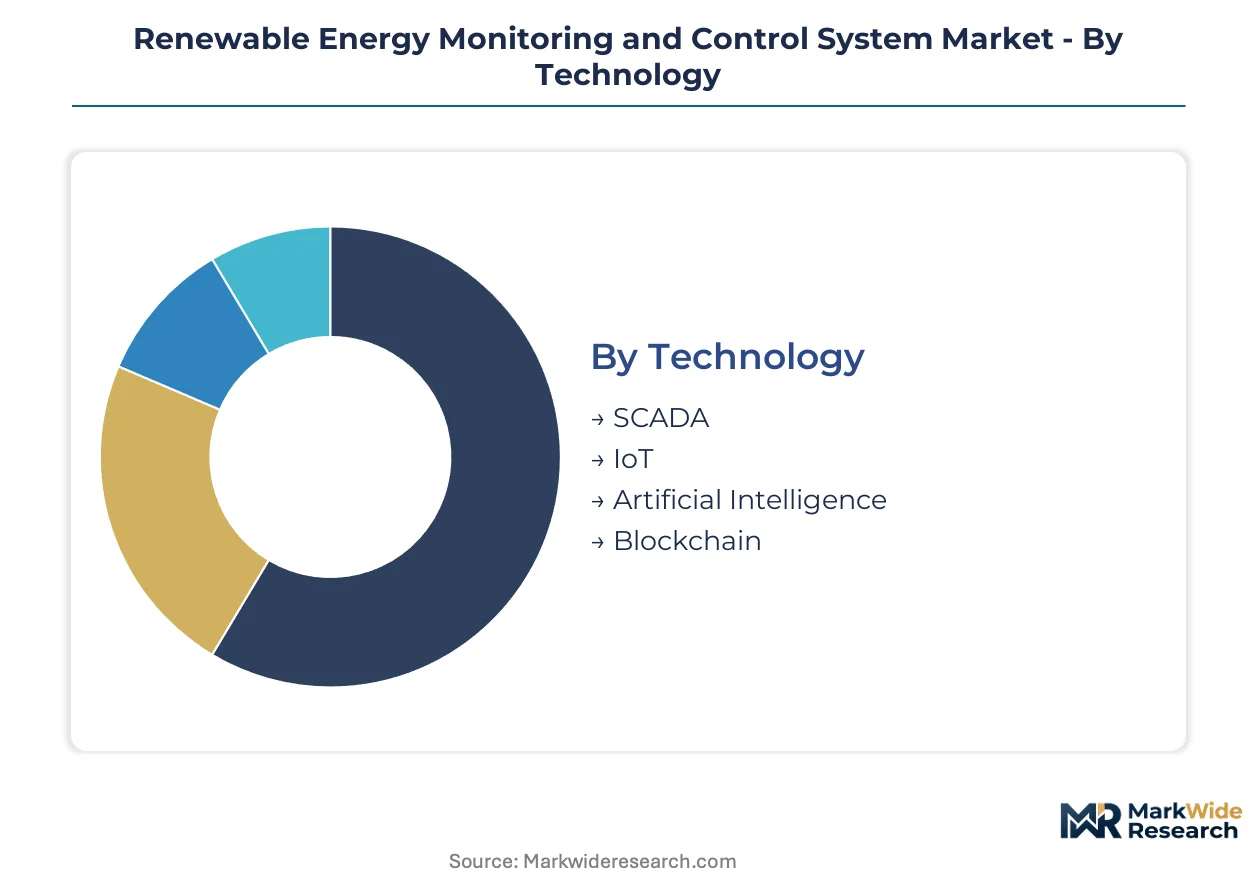
Technology heterogeneity across renewable assets demands precise segmentation matching control system capabilities to generation source requirements. Procurement patterns diverge sharply between centralized utility architectures and distributed residential deployments.
Technology:
Customization intensity varies from configurable SCADA platforms to standardized AI inference modules, with integration complexity driving vendor selection criteria.
- SCADA:Centralized supervisory systems aggregate telemetry from dispersed generation assets through hardened communication protocols. Utility-scale solar farms in the United States and China deploy these architectures to manage gigawatt-scale portfolios with sub-second dispatch latency.
- IoT:Distributed sensor networks embed at grid edge for residential and commercial rooftop monitoring. German utilities leverage these layers to aggregate behind-the-meter resources under FERC Order 2222-style frameworks.
- Artificial Intelligence:Predictive analytics modules extract failure signatures from vibration and thermal data.
- Blockchain:Immutable data provenance chains certify carbon accounting for EU Green Deal compliance.
Most installed capacity flows through SCADA deployments. Expansion is steepest in IoT sensor layers.
Application:
Cost tier differentiation separates premium offshore wind monitoring from standardized residential solar inverters, with project scale determining feature depth.
- Solar Power:Photovoltaic monitoring spans string-level power electronics to plant-wide performance ratio tracking. Chinese manufacturers dominate hardware supply while European developers prioritize predictive cleaning algorithms for desert installations.
- Wind Energy:Turbine control systems integrate nacelle orientation, blade pitch, and grid synchronization. Offshore developments in the North Sea drive demand for corrosion-resistant edge computing with satellite backhaul.
- Hydropower:Run-of-river and pumped storage facilities require flow forecasting integration.
- Biomass:Combustion optimization and emissions monitoring systems track feedstock variability.
Wind Energy commands the highest per-megawatt monitoring spend. Solar Power delivers volume scale across distributed and utility segments.
End User:
Customer type determines procurement authority, with utilities centralizing specifications and residential buyers deferring to installer recommendations.
- Utilities:Transmission and distribution operators mandate interoperability certification and cybersecurity hardening. German TSOs reject interconnection proposals lacking certified data provenance chains under EU digitalization mandates.
- Industrial:C&I offtakers integrate renewable monitoring with facility energy management systems. US data center operators in Virginia and Texas specify sub-second frequency response capabilities.
- Commercial:Retail and office building owners prioritize dashboard visibility and ESG reporting integration.
- Residential:Homeowners rely on installer-provisioned monitoring with mobile application interfaces.
Utilities concentrate procurement volume through framework agreements. Commercial segment expansion accelerates with corporate PPA growth.
Solution:
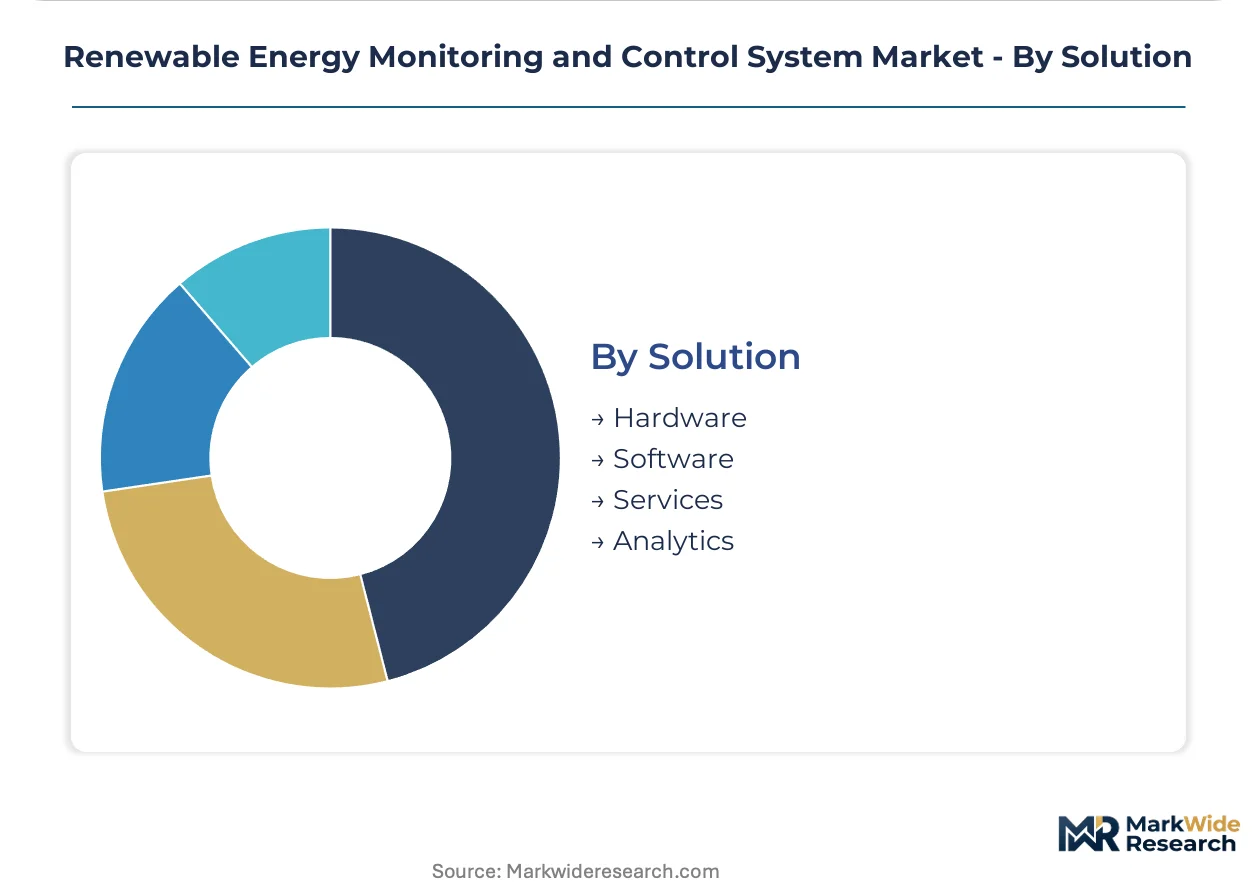
Margin pools concentrate in software and analytics as hardware commoditizes, with services revenue stabilizing through long-term O&M contracts.
- Hardware:Sensor assemblies, communication gateways, and edge computing devices form the physical layer. Chinese inverter manufacturers are broadening production capacity for grid-edge monitoring components.
- Software:SCADA platforms, digital twin environments, and fleet management applications command recurring license fees. Danish independent power producers negotiate multi-year analytics subscriptions separate from sensor procurement.
- Services:Installation, commissioning, and technical support packages accompany hardware deployment.
- Analytics:Predictive maintenance algorithms and performance optimization engines extract value from raw telemetry.
Hardware captures initial project expenditure. Analytics delivers the steepest margin expansion trajectory as asset owners unbundle software from equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's F-Gas Regulation enforcement tightens equipment replacement cycles faster than China's GB standards revision timeline, creating divergent compliance windows for sensor manufacturers.
United States
FERC Order 2222 aggregation rules unlock wholesale market participation for distributed solar and storage assets. Virginia and Texas data center operators specify sub-second frequency response capabilities in procurement contracts. The Southwest solar belt drives concentrated SCADA deployments across gigawatt-scale photovoltaic installations.
Germany
Transmission system operators reject interconnection proposals lacking certified data provenance chains under EU Green Deal digitalization mandates. Performance-based O&M contracts now tie service provider compensation to availability guarantees. The North Sea offshore wind corridor demands corrosion-resistant edge computing with satellite backhaul connectivity.
China
GB standards for grid-connected renewable equipment reshape product certification requirements for domestic and export markets. Inverter manufacturers broaden production capacity for grid-edge monitoring hardware. The Yangtze River Delta solar manufacturing cluster integrates sensor assembly with module production lines.
India
Central and state-level solar-wind hybrid auctions create demand for integrated monitoring platforms across 500+ MW installations. The country's national renewable energy regulator mandates telemetry standards for capacity market participation. Gujarat and Rajasthan host concentrated utility-scale solar deployments requiring centralized fleet management.
United Kingdom
Offshore wind developers in the North Sea adopt digital twin architectures for wake effect simulation and nacelle orientation testing. Grid operators enforce cybersecurity hardening standards for critical energy infrastructure. Scottish onshore wind portfolios drive predictive maintenance algorithm adoption across aging turbine fleets.
Renewable Energy Monitoring and Control System Market Competitive Landscape
European producers anchor one tier through deep automation expertise and utility framework agreements; Chinese specialists hold volume scale through integrated inverter-sensor manufacturing. The vendor structure stratifies across three archetypes: diversified industrial conglomerates with energy divisions, pure-play monitoring technology developers, and hardware-originated platform builders. Consolidation pressure concentrates among mid-scale firmware developers facing semiconductor sourcing bottlenecks. Geographic expansion and strategic partnerships represent the dominant competitive moves as vendors seek to unbundle software subscriptions from hardware procurement.
Among diversified industrial groups, Siemens, Schneider Electric, and GE Vernova exemplify distinct strategic positioning. Siemens leverages automation heritage to anchor European utility contracts through framework agreements. Schneider Electric competes through integrated software-hardware platforms spanning multiple generation technologies. GE Vernova sustains turbine-to-grid data pipeline relationships across North American wind portfolios. These three occupy positions that reflect varying degrees of vertical integration into sensor manufacturing versus software analytics specialization.
| Leading Market Players |
|---|
| Toshiba |
| Uplight |
| Siemens |
| Gantner Instruments |
| EnergyCAP |
| Schneider Electric |
| InfluxData |
| LineVision |
| GE Vernova |
| Others |
Value Network & Pricing Analysis
Edge-AI chip integration into sensor gateways is compressing hardware margins while concentrating procurement leverage among semiconductor foundries with advanced node capacity. This dual compression forces tier-one vendors to unbundle software subscriptions from equipment sales, recasting monitoring platforms as recurring revenue streams rather than capital expenditure items.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for grid-edge monitoring hardware. Three-tier pricing structure across premium, standard, and economy levels separates cybersecurity-hardened utility-grade systems from commercial rooftop packages and residential inverter-embedded sensors. Price differentiation hinges on IEC 62443 certification tier and after-sales telemetry support. Cost compression in the standard tier is intensifying because Chinese manufacturers are vertically integrating sensor assembly with module production lines. Residential buyers exhibit highest price sensitivity, while German transmission system operators prioritize certification compliance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Chinese solar manufacturers and North American independent power producers. Analog-to-digital converter and power management IC sourcing draws from Taiwan, South Korea, and Japan. Raw material dependencies span silicon wafers, rare-earth magnets for turbine sensors, and lithium compounds for edge device batteries. Single-source vulnerability concentrates in 28nm and below semiconductor fabrication. Distribution runs through systems integrators for utility-scale deployments and inverter OEMs for distributed residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal digitalization mandates and FERC Order 2222 aggregation rules continuously expand addressable demand through compliance-driven replacement cycles.
For Market Incumbents: To counter firmware talent poaching from automotive and aerospace sectors, anchor European utility relationships through multi-year framework agreements with embedded cybersecurity certification. Deepen in-house production of edge-AI inference chips to reduce foundry dependency and defend margin position against Chinese inverter manufacturers expanding into monitoring hardware. For New Entrants and Emerging Players: Systems integrators serving India's 500+ MW solar-wind hybrid auctions represent the most penetrable channel for unproven vendors. White-space concentrates in performance-based O&M contract analytics where Danish and US independent power producers now unbundle software procurement from hardware. Target corrosion-resistant edge computing for North Sea offshore wind as the entry wedge, leveraging satellite backhaul partnerships to bypass terrestrial infrastructure gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale firmware developers facing semiconductor sourcing bottlenecks and 12-18 month certification delays. Long-term viability centers on software analytics specialization rather than hardware commoditization over the next decade. Watch for FERC Order 2222 implementation velocity across US regional transmission organizations as the inflection signal for distributed resource aggregation platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Hardware Unbundling | Danish IPPs now negotiate multi-year analytics licenses separate from sensor procurement. |
| Cybersecurity Certification Investment | IEC 62443 compliance determines grid interconnection eligibility under EU Green Deal mandates. |
| Edge-AI Chip Integration | On-device inference enables predictive maintenance without cloud dependency for offshore wind. |
| Digital Twin Platform Deployment | North Sea developers simulate wake effects and nacelle orientation before field commissioning. |
| Performance-Based O&M Contracts | German asset owners compensate service providers against availability guarantees requiring granular telemetry. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned utility planning officers, IPP project developers, EPC contractors, and grid operators across Germany, China, and the United States. Secondary validation drew from FERC filings, EIA data, IEA reports, and project development databases. Bottom-up capacity installation tracking and top-down regulatory framework analysis were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to pre-pandemic baseline growth trajectories and post-2022 supply normalization trends. The analytical framework modeled segmentation across generation technology, project scale tier, deployment architecture, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and average revenue per unit trajectories. Forecast inputs incorporated semiconductor lead time normalization and EU F-Gas Regulation compliance deadline effects.
Revisions become necessary when semiconductor sourcing constraints extend beyond current foundry capacity expansion timelines or when cybersecurity standards harden data protection requirements for remote monitoring networks. Forecasts reflect assumptions regarding grid interconnection tariff stability and distributed resource aggregation rule implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Solar Oven Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Marine Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
South Africa Rooftop Solar Market