
 South Africa Solar Photovoltaic (PV) Market | 2026-2036
South Africa Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Solar Photovoltaic (PV) Market Analytics
Aftermarket service revenue is tilting toward operations and maintenance contracts as project pipelines mature. Scatec anchors its position through utility-scale development expertise across Southern Africa. Canadian Solar leverages integrated module manufacturing to control cost structures in procurement cycles. SOLA specializes in commercial and industrial rooftop installations, occupying a niche between residential installers and utility developers.
South Africa Solar Photovoltaic (PV) systems convert sunlight into direct current electricity through semiconductor junctions, with monocrystalline silicon modules achieving conversion efficiencies above 21% under standard test conditions. These installations serve primarily to displace coal-fired grid electricity and provide energy security for power-intensive operations. Bifacial modules are gaining traction in utility-scale deployments where albedo reflection boosts yield, while off-grid technology segments address rural electrification gaps beyond Eskom's distribution network. The utility-scale application category commands the largest capital allocation, though commercial-industrial rooftop systems deliver faster payback periods through behind-the-meter savings.
South Africa's National Energy Regulator (NERSA) governs licensing thresholds for embedded generation, while the Department of Mineral Resources and Energy administers the Integrated Resource Plan that mandates renewable capacity procurement. The country's grid code compliance requirements shape inverter specifications and system design standards for all grid-tied installations. Stakeholders must monitor regulatory adjustments to licensing exemptions and wheeling frameworks that determine how distributed generators monetize surplus output across municipal boundaries.
Market Dynamics
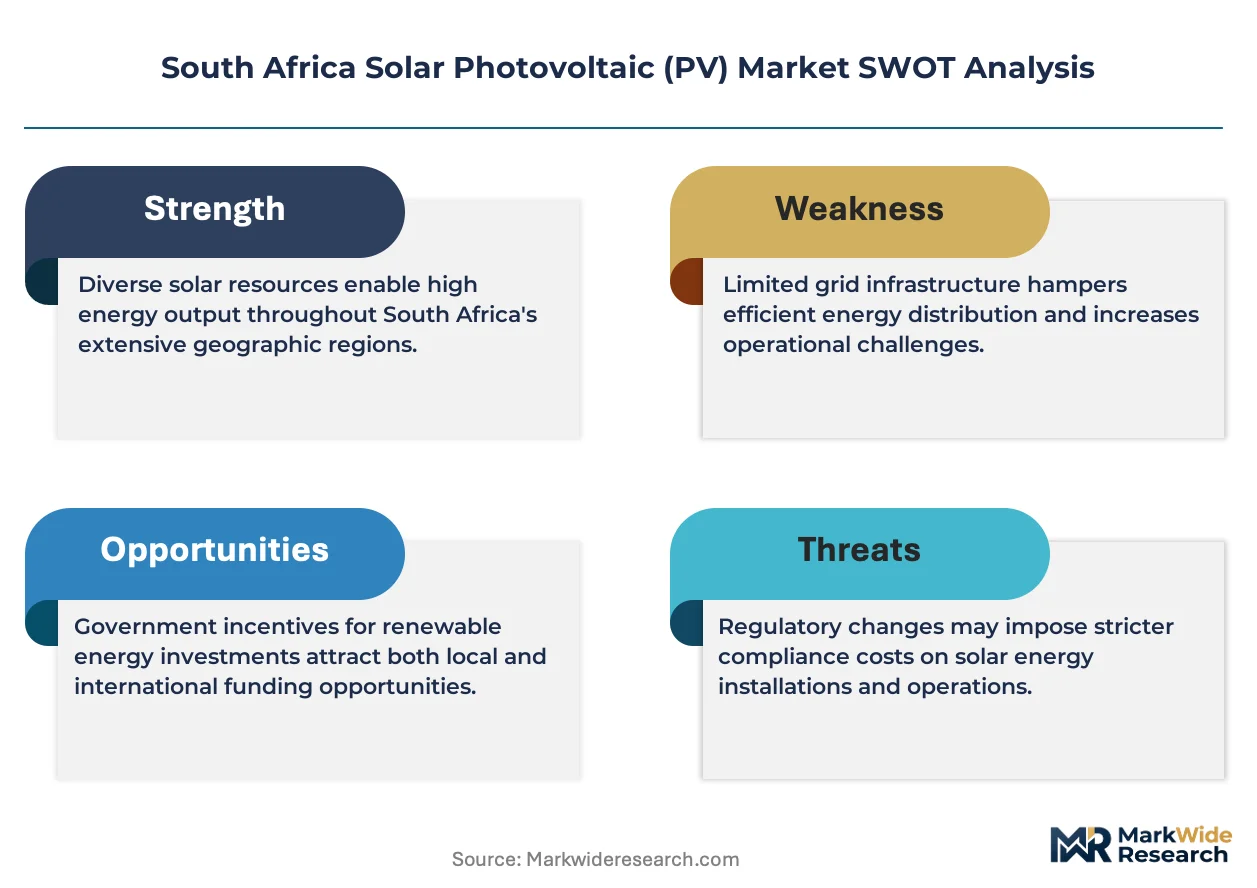
Eskom's chronic generation shortfall and load-shedding schedules are forcing commercial and industrial consumers toward behind-the-meter solar installations, restructuring electricity procurement from centralized utility dependence to distributed self-generation.
Growth Catalysts
- Integrated Resource Plan mandates:The Department of Mineral Resources and Energy's procurement targets compel renewable capacity additions, creating guaranteed offtake mechanisms for independent power producers.
- Commercial and industrial rooftop demand:Mining operations and manufacturing facilities in Gauteng province are deploying captive solar to secure power supply continuity amid grid instability.
- Bifacial module technology:Albedo-enhanced yield performance is expanding viable project economics across South Africa's high-irradiance regions, particularly in Northern Cape utility-scale developments.
Market Restraints
- Polysilicon input cost volatility:Raw material price swings compress developer margins and delay financial close on merchant solar projects.
- Grid code compliance burden:NERSA's technical standards for inverter synchronization and fault ride-through capability add engineering complexity and certification timelines.
- Lithium-ion storage substitution pressure:Battery energy storage systems compete for capital allocation in hybrid project configurations, diverting investment from pure-play PV expansions.
Strategic Opportunities
- Wheeling framework expansion:Evolving municipal regulations enabling surplus electricity monetization across distribution boundaries unlock new revenue streams for distributed generators.
- Agricultural irrigation pumping:Off-grid solar pumping systems address electrification gaps beyond Eskom's rural network, serving Western Cape and Limpopo farming cooperatives.
- Green hydrogen convergence:Electrolyzer-integrated solar installations create demand for dedicated renewable power offtake in Northern Cape industrial zones.
Industry Challenges
- Grid integration engineering capacity:Scarce power systems engineers familiar with South African grid code requirements bottleneck project execution timelines.
- Municipal licensing fragmentation:Inconsistent embedded generation approval processes across metropolitan municipalities delay commercial rooftop commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Solar Photovoltaic (PV) Market |
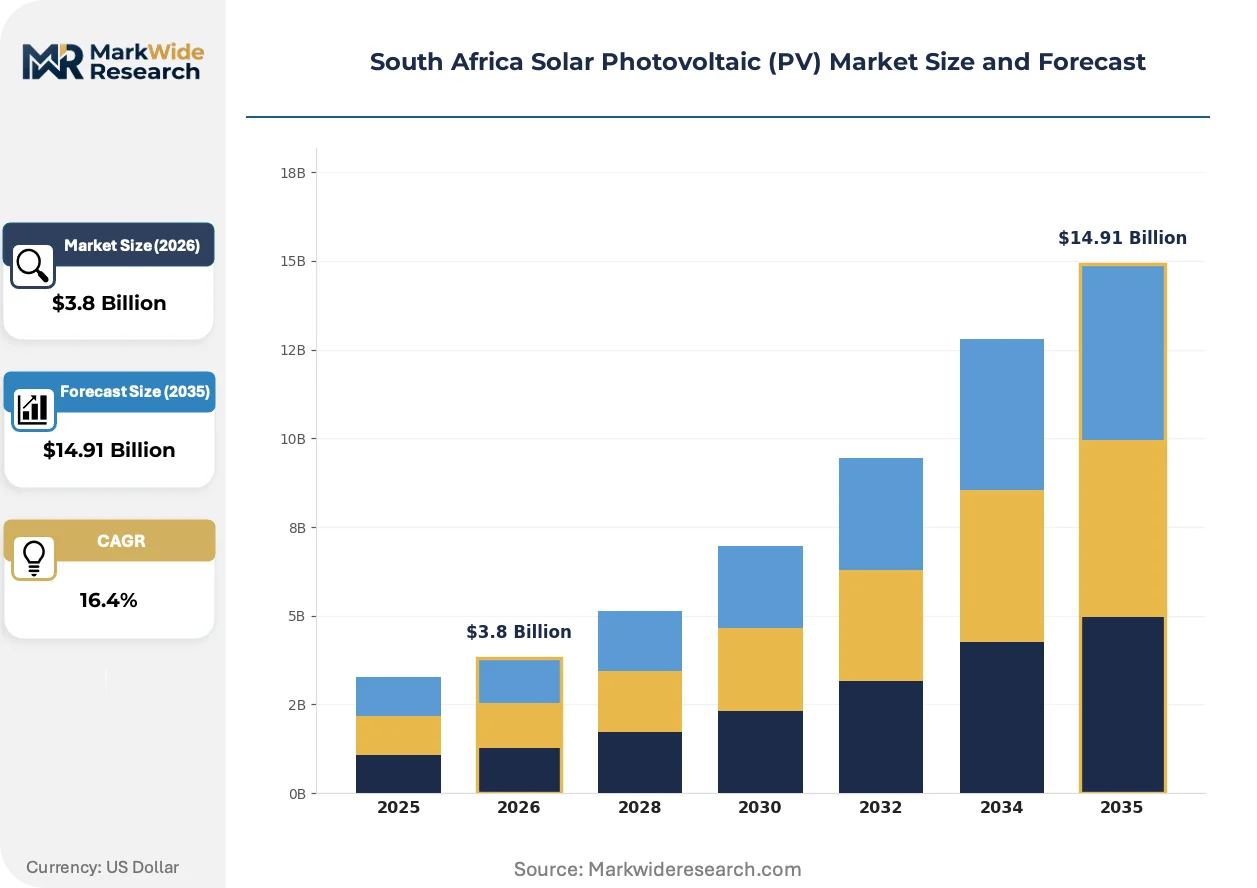
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin Film, Bifacial Technology: Grid-Tied, Off-Grid, Hybrid, Concentrated Photovoltaics Application: Residential, Commercial, Industrial, Utility-Scale End User: Homeowners, Businesses, Government, Utilities |
| Companies Covered | NOA Group, ARTsolar, Scatec, Seraphim Solar, Canadian Solar, Hive Energy, Akuo Energy, AMEA Power, SOLA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Solar Photovoltaic (PV) Market Evolving Landscape
Technology cost compression and regulatory adaptation are converging to restructure how solar capacity is financed, constructed, and monetized across South African electricity markets.
Monocrystalline PERC cell architectures are collapsing the cost differential between premium and standard module tiers. Mining houses and industrial offtakers in the Rustenburg platinum belt are specifying these modules for 200MW-plus captive installations. The technology is collapsing developer procurement strategies from price-per-watt bidding toward levelized cost of energy optimization.
NERSA's licensing exemption threshold revisions are reshaping distributed generation entry barriers. The regulator's upward adjustment of capacity caps exempts more commercial installations from full licensing procedures. Commercial and industrial rooftop developers in Johannesburg and Pretoria metropolitan areas are accelerating project pipelines in response to streamlined permitting.
Power purchase agreement tenor compression is altering developer risk allocation and equity return requirements. Industrial offtakers are negotiating shorter contract durations with merchant price exposure rather than 20-year utility-linked escalators. This shift is most pronounced in Gauteng manufacturing corridors where corporate treasuries prioritize balance sheet flexibility over long-term price certainty.
South Africa Solar Photovoltaic (PV) Market Segmentation
South Africa's solar PV market fragments across technology maturity curves and customer risk appetites. Each segmentation dimension reveals distinct procurement patterns shaped by grid reliability pressures and regulatory licensing thresholds.
Product Type:
Module selection spans efficiency premiums to cost-optimized deployments across Gauteng industrial rooftops and Northern Cape utility fields.
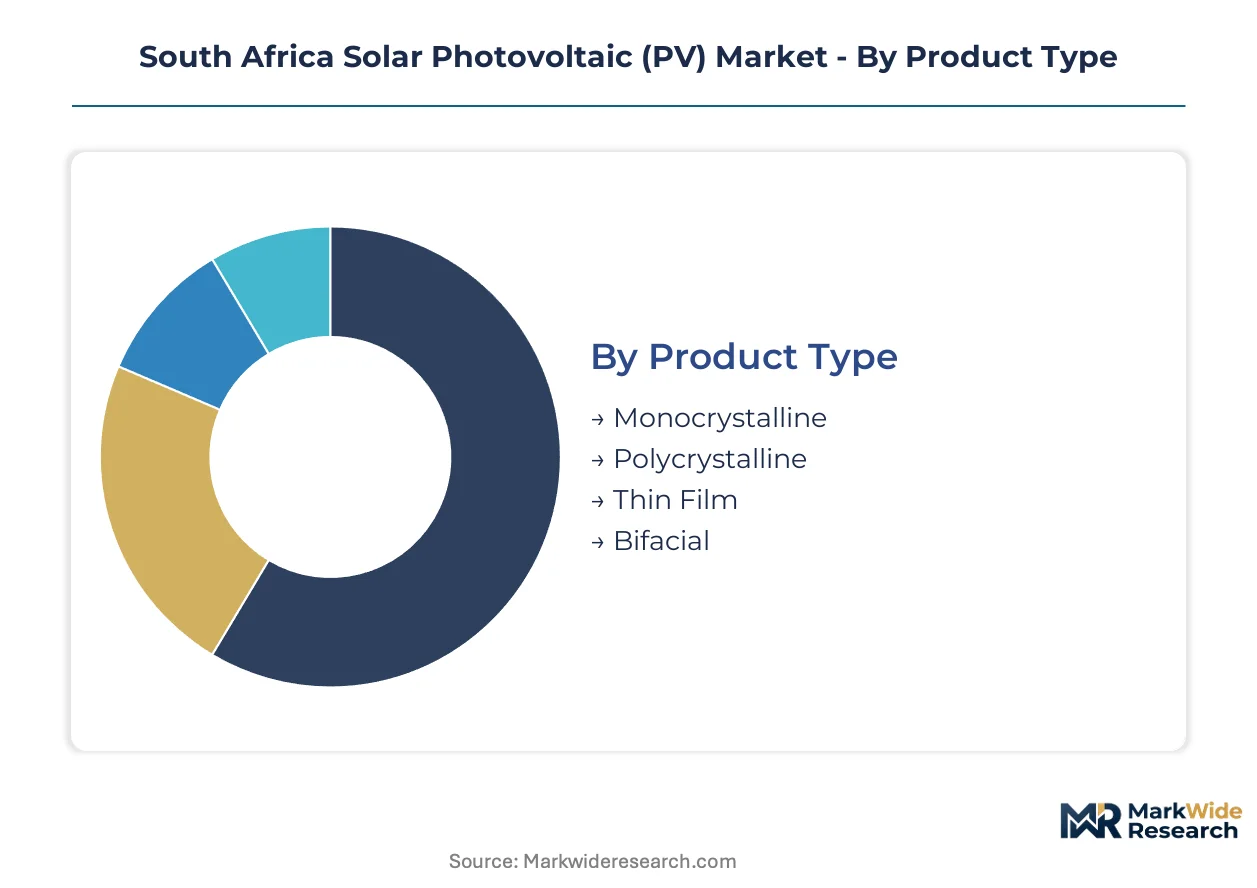
- Monocrystalline:PERC cell architectures deliver conversion efficiencies above 21% under standard test conditions. Mining houses in the Rustenburg platinum belt specify these modules for 200MW-plus captive installations where space constraints demand maximum output density.
- Bifacial:Albedo-enhanced yield performance expands viable project economics across high-irradiance regions, particularly in Northern Cape utility-scale developments where ground reflection boosts annual energy harvest significantly.
- Polycrystalline:Cost-sensitive commercial installers in Pretoria metropolitan areas favor these modules for sub-1MW rooftop systems where capital efficiency outweighs premium efficiency metrics.
- Thin Film:Cadmium telluride and CIGS technologies occupy niche applications in building-integrated PV projects across Cape Town commercial developments where aesthetic integration drives specification.
The dominant share belongs to Monocrystalline, while Bifacial is closing the gap fastest.
Technology:
System architecture choices reflect grid access quality and backup power requirements across municipal boundaries.
- Grid-Tied:Inverter-synchronized installations dominate Johannesburg and Pretoria metropolitan corridors where NERSA licensing exemptions streamline permitting for sub-1MW commercial systems behind the meter.
- Hybrid:Battery-integrated configurations are expanding most quickly in Gauteng manufacturing facilities where load-shedding schedules mandate four-to-eight hour autonomy periods for critical production lines.
- Off-Grid:Standalone systems serve Western Cape and Limpopo farming cooperatives beyond Eskom's rural distribution network, powering irrigation pumping and cold storage operations.
- Concentrated Photovoltaics:Dual-axis tracking concentrator systems remain experimental in Northern Cape testbeds where direct normal irradiance exceeds 2,800 kWh/m² annually.
Grid-Tied commands installed capacity leadership, though Hybrid configurations are gaining share fastest as battery costs compress.
Application:
Scale tiers align with financing sophistication and offtaker credit quality across South Africa's electricity procurement landscape.
- Utility-Scale:Independent power producer developments in Northern Cape and Free State provinces leverage Renewable Energy Independent Power Producer Procurement Programme auction mechanisms for 100MW-plus installations.
- Industrial:Behind-the-meter rooftop and ground-mount systems deliver fastest payback periods for manufacturing facilities in Gauteng province where displaced municipal tariff savings justify capital deployment.
- Commercial:Office parks and retail centers in Durban and Cape Town metropolitan areas deploy sub-5MW systems under power purchase agreements with tenors compressing toward 10-year terms.
- Residential:Homeowner installations concentrate in suburban Johannesburg and Cape Town neighborhoods where sectional title regulations and inverter sizing constraints limit average system scale.
Utility-Scale retains capital allocation dominance, while Industrial applications are climbing the fastest amid load-shedding pressures.
End User:
Customer segments diverge sharply on procurement risk tolerance and contract structure preferences.
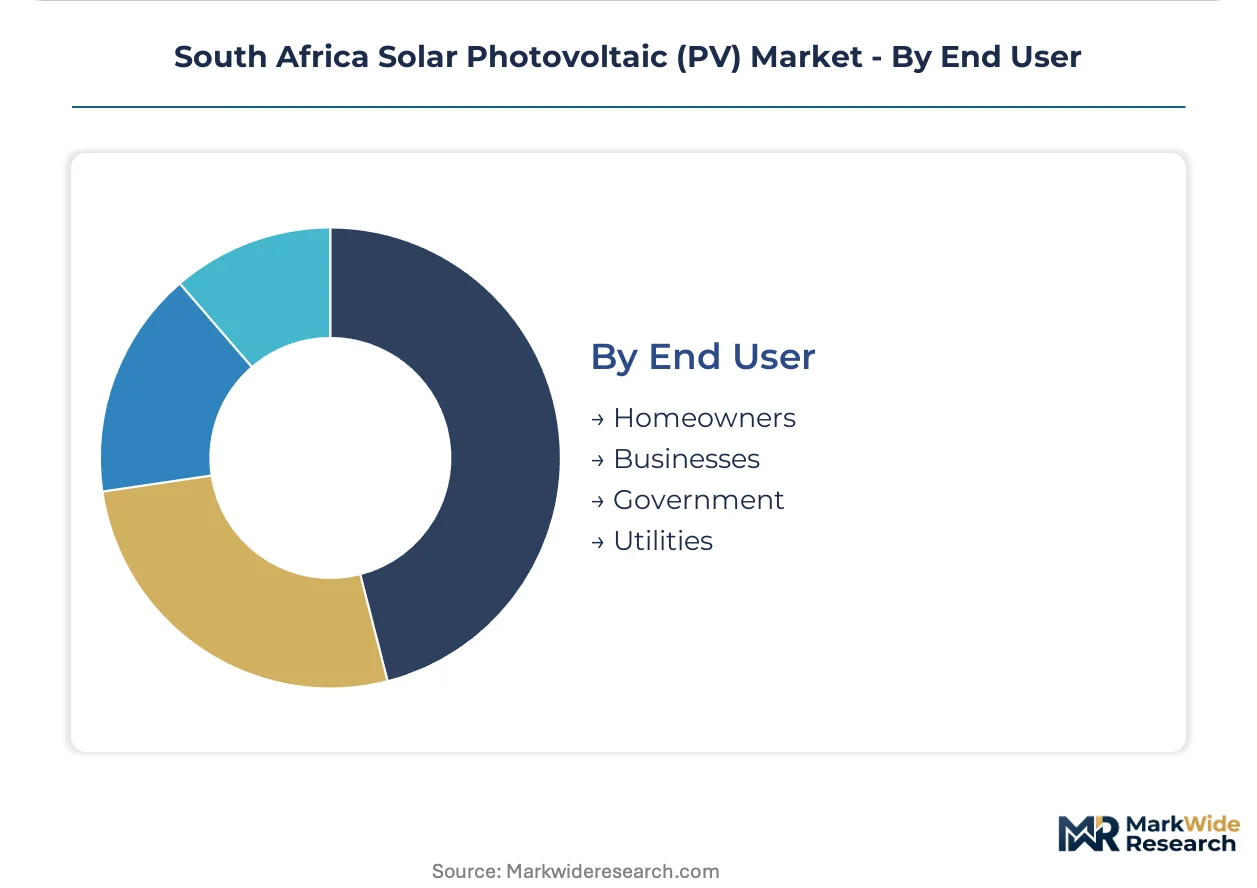
- Businesses:Mining operations and manufacturing facilities prioritize energy security through captive generation, negotiating direct engineering-procurement-construction contracts with developers rather than leasing structures.
- Utilities:Eskom and municipal distributors procure renewable capacity through competitive auctions, though grid connection queues and transmission availability constraints delay project energization timelines.
- Government:Department of Public Works facilities and provincial hospitals deploy solar through public-private partnership frameworks with availability-based payment mechanisms.
- Homeowners:Individual residential buyers rely on installer financing and green loan products from South African banking institutions, with system sizes typically capped at 10kW by single-phase connection limits.
Businesses drive volume concentration, while Government procurement is expanding most quickly under accelerated infrastructure deployment mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across South Africa's provinces, with industrial buyers in Gauteng accepting premium tariffs for supply security while agricultural users in Limpopo prioritize capital efficiency over performance metrics.
Gauteng
Mining houses and manufacturing facilities in Johannesburg and Pretoria metropolitan corridors deploy captive solar to circumvent Eskom load-shedding schedules. NERSA's licensing exemption threshold revisions streamline permitting for sub-1MW commercial installations behind the meter. The Rustenburg platinum belt hosts 200MW-plus monocrystalline PERC deployments where space constraints demand maximum output density per hectare.
Northern Cape
Utility-scale independent power producers leverage albedo-enhanced bifacial modules across high-irradiance desert regions where ground reflection boosts annual energy harvest. The Department of Mineral Resources and Energy's Renewable Energy Independent Power Producer Procurement Programme auction mechanisms guarantee offtake for 100MW-plus developments. Green hydrogen industrial zones near Upington create dedicated renewable power demand for electrolyzer-integrated solar installations.
Western Cape
Building-integrated thin film technologies address aesthetic specifications in Cape Town commercial developments while off-grid pumping systems serve agricultural irrigation beyond Eskom's rural distribution network. The provincial government accelerates public-private partnership frameworks for Department of Public Works facilities with availability-based payment mechanisms. Stellenbosch and Paarl farming cooperatives deploy standalone systems for cold storage operations.
KwaZulu-Natal
Durban metropolitan office parks and retail centers negotiate compressed power purchase agreement tenors toward 10-year terms rather than traditional 20-year utility-linked escalators. Municipal wheeling framework evolution enables surplus electricity monetization across distribution boundaries for distributed generators. Richards Bay industrial corridors attract hybrid battery-integrated configurations where load-shedding mandates four-to-eight hour autonomy periods.
South Africa Solar Photovoltaic (PV) Market Competitive Landscape
Capability concentration sits with utility-scale developers possessing integrated resource plan auction expertise; scale advantage sits with module manufacturers controlling upstream polysilicon cost structures. The vendor base organizes across three tiers: international developers with Southern African regional portfolios, domestic commercial-industrial specialists, and integrated module suppliers. Strategic moves center on wheeling framework pre-positioning and hybrid storage bundling to capture load-shedding premium demand.
Among international developers with regional footprints, Scatec anchors utility-scale development expertise across Southern Africa, Canadian Solar exemplifies integrated module manufacturing control over procurement cost structures, and SOLA occupies the commercial-industrial rooftop niche between residential installers and utility developers. These three represent distinct competitive archetypes: the regional platform builder, the verticalized manufacturer, and the segment-focused specialist.
| Leading Market Players |
|---|
| NOA Group |
| ARTsolar |
| Scatec |
| Seraphim Solar |
| Canadian Solar |
| Hive Energy |
| Akuo Energy |
| AMEA Power |
| SOLA |
| Others |
Value Network & Pricing Analysis
Chinese polysilicon ingot capacity concentration anchors module cost structures across South African procurement cycles, with margin pools shifting downstream toward developers controlling grid connection queues and NERSA licensing pathways. Module price volatility transmits directly to project finance terms, compressing developer equity returns when polysilicon spot markets spike.
Pricing Analysis
Operations and maintenance contract revenue drives lifetime value for installed capacity owners, with ten-year service agreements now standard in utility-scale offtake negotiations. Three-tier pricing structure across premium monocrystalline PERC, standard polycrystalline, and economy thin-film tiers reflects conversion efficiency differentials and brand certification levels. Pricing pressure stems from lithium-ion battery cost compression diverting capital allocation in hybrid configurations. Mining houses in the Rustenburg belt exhibit lowest price sensitivity, prioritizing supply security over per-watt savings, while agricultural cooperatives in Limpopo demand capital-optimized polycrystalline deployments.
Supply Chain Analysis
Export control regimes on semiconductor manufacturing equipment constrain South African inverter suppliers' access to advanced IGBT and SiC component tiers, forcing reliance on legacy silicon architectures. Module supply concentrates in China, Vietnam, and Malaysia, with polysilicon feedstock drawing from Xinjiang and Inner Mongolia smelters. Raw material dependencies span high-purity silicon metal, silver paste for cell metallization, and aluminum framing extrusions. Single-source vulnerability sits with Chinese inverter OEMs commanding over seventy percent of distributed generation shipments. Distribution runs through Johannesburg-based EPC contractors and Pretoria engineering-procurement firms serving Gauteng industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's solar PV market sits in early-cycle expansion, with load-shedding frequency accelerating behind-the-meter adoption faster than Integrated Resource Plan procurement timelines anticipated. Mining sector energy security mandates create guaranteed demand floors independent of auction mechanism success.
For Market Incumbents: Insulate project pipelines against polysilicon cost volatility through backward integration into module assembly or long-term polysilicon offtake agreements with Chinese suppliers. Lock in grid connection capacity reservations at Northern Cape substations before transmission availability constraints harden. Battery energy storage substitution pressure threatens pure-play PV margins; hybrid bundling capabilities separate survivors from stranded developers. For New Entrants and Emerging Players: Build out agricultural irrigation pumping expertise in Western Cape and Limpopo farming cooperatives, where electrification gaps beyond Eskom's rural network create uncontested white space. Municipal wheeling framework evolution unlocks surplus monetization for distributed generators willing to navigate fragmented licensing processes across metropolitan boundaries. Direct sales to farming cooperatives bypass competitive auction exposure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commercial-industrial rooftop developers holding Johannesburg and Pretoria metropolitan project pipelines. Five-to-ten year viability hinges on NERSA licensing exemption threshold stability and municipal wheeling framework maturation. Acquisition targets should demonstrate grid code compliance engineering capacity and existing relationships with platinum belt mining houses. The signal to watch is Eskom generation availability improvement; sustained grid stability would compress behind-the-meter premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Storage Bundling | Captures load-shedding premium demand from Gauteng manufacturing facilities requiring four-to-eight hour autonomy. |
| Wheeling Framework Pre-Positioning | Enables surplus electricity monetization across municipal boundaries as KwaZulu-Natal regulations evolve. |
| Monocrystalline PERC Scale-Up | Collapses cost differential toward premium tier dominance in Rustenburg platinum belt captive installations. |
| Green Hydrogen Integration | Creates dedicated renewable power offtake in Northern Cape electrolyzer-integrated solar zones near Upington. |
| NERSA Licensing Streamlining | Accelerates commercial rooftop pipelines in Johannesburg metropolitan areas through exemption threshold optimization. |
Research Methodology
The analysis maps utility-scale IPP developments, commercial-industrial rooftop installations, and off-grid agricultural systems, each validated through project developers, EPC contractors, and mining house energy procurement officers. Primary interviews with NERSA licensing specialists and municipal electricity distributors combined with secondary validation from Department of Mineral Resources and Energy procurement databases, Eskom transmission connection queue records, and Renewable Energy Independent Power Producer Procurement Programme auction results. Bottom-up project pipeline aggregation triangulates against top-down capacity installation tracking.
Assumption sets held NERSA regulatory thresholds and Eskom generation shortfall severity within observed ranges while varying polysilicon input cost trajectories and battery energy storage substitution rates across the projection horizon. Segmentation dimensions modeled include module technology tier, system architecture type, application scale category, and provincial grid reliability profile. CAGRs derive from installed capacity build rates correlated with licensing approval velocity and mining sector capital expenditure cycles. Forecast inputs incorporate bifacial module yield enhancement assumptions and wheeling framework adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese inverter OEMs or polysilicon suppliers would shift outcomes. Material shifts in NERSA licensing exemption thresholds, Eskom generation availability, or municipal wheeling framework adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Green Energy Lighting Market