
 South Africa Rooftop Solar Market | 2026-2036
South Africa Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Rooftop Solar Market Outlook
Commercial property portfolios and industrial estates are bifurcating from the traditional residential-led demand pattern that defined earlier market phases. Sola Group leverages its vertically integrated engineering capability to capture large-scale commercial contracts across Johannesburg and Cape Town. Sunworx Solar anchors its position through specialized residential financing products that reduce upfront capital barriers for middle-income households. Tasol Solar differentiates via aggressive geographic expansion into secondary cities and peri-urban municipalities.
Rooftop solar refers to photovoltaic systems mounted on building structures, typically comprising monocrystalline or polycrystalline silicon modules with DC-to-AC inverters and balance-of-system components, designed to generate electricity at the point of consumption rather than through centralized transmission. These installations serve commercial, industrial, and residential consumers seeking to offset grid dependency and manage volatile tariff structures from Eskom. Grid-tied configurations dominate current deployment volumes, though hybrid systems incorporating battery backup represent the fastest-expanding segment as load-shedding persistence drives storage co-investment. Agricultural applications remain underpenetrated relative to commercial and industrial uptake, creating a latent margin pool for specialized installers.
South Africa's National Energy Regulator and the Department of Mineral Resources and Energy enforce licensing thresholds and grid-connection standards that determine project economics and market access for distributed generators. Municipal-level bylaws across Johannesburg, Cape Town, and eThekwini create fragmented permitting environments that delay commissioning timelines and elevate soft costs for developers. Stakeholders must monitor evolving wheeling frameworks and embedded generation tariff reforms that could either unlock cross-border commercial demand or compress project returns through revised grid-use charges.
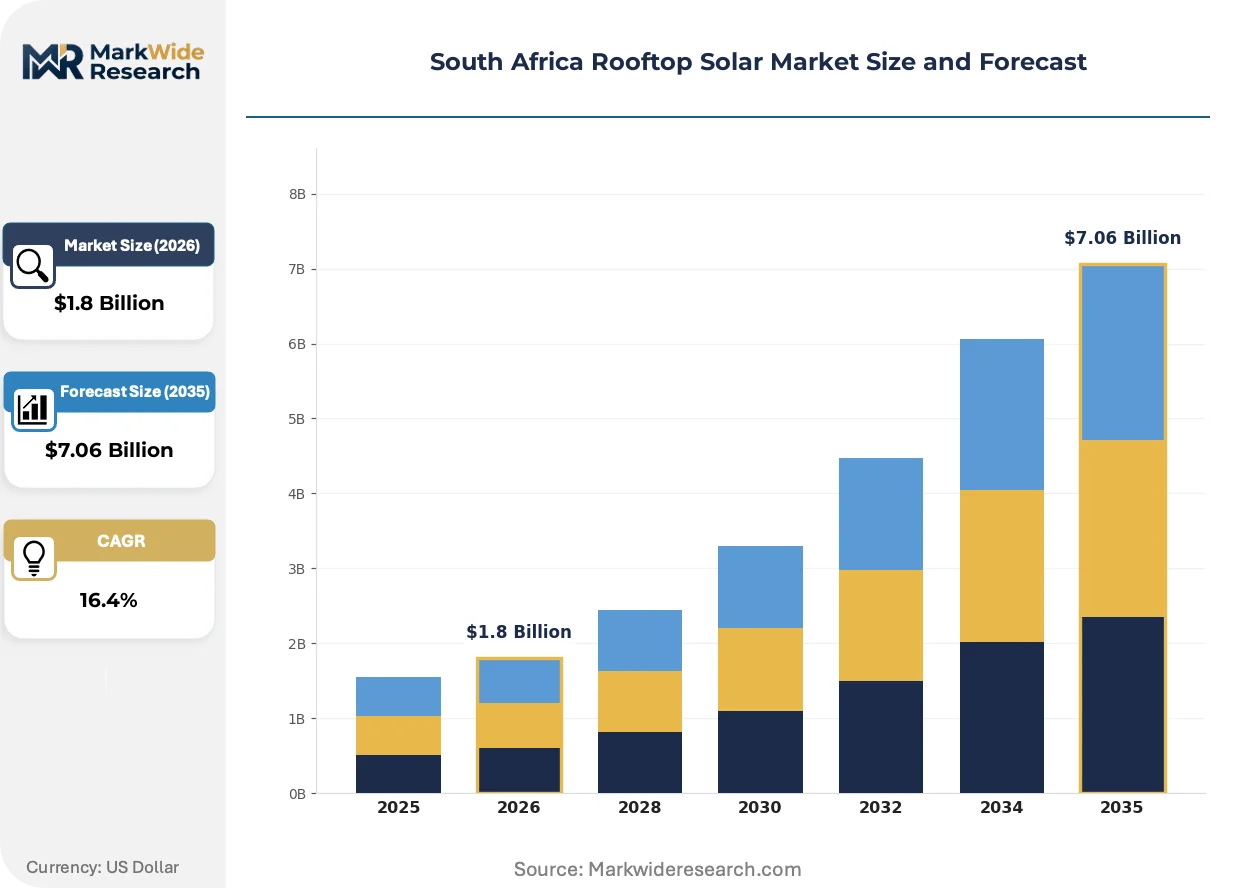
Market Dynamics
Eskom's tariff restructuring and persistent load-shedding schedules are forcing commercial property owners to treat distributed generation as core infrastructure rather than supplementary supply. This structural pressure is compressing payback period calculations and accelerating capital reallocation from traditional grid dependency to on-site photovoltaic systems with integrated storage.
Growth Catalysts
- Embedded Generation Licensing Threshold:The Department of Mineral Resources and Energy's streamlined licensing for sub-100MW projects eliminates bureaucratic friction for industrial estates seeking self-sufficiency. Commercial developers in Gauteng exploit this to bypass municipal procurement delays.
- Monocrystalline PERC Efficiency Gains:Module manufacturers have pushed conversion rates past 21%, shrinking rooftop footprint requirements for equivalent output. Warehouse operators in the Western Cape corridor prioritize these panels to maximize generation per square meter of available surface.
- Agricultural Irrigation Load Profiles:Pumping operations in Limpopo and Mpumalanga present predictable daytime demand curves that align perfectly with solar generation peaks. Agribusinesses are retrofitting diesel-dependent irrigation systems with grid-tied arrays to hedge against fuel price volatility.
Market Restraints
- Lithium-Ion Battery Cost Concentration:Cell supply chains remain dominated by East Asian manufacturers, exposing South African project developers to currency fluctuation risk and extended lead times for hybrid system components.
- Municipal Bylaw Fragmentation:Johannesburg, Cape Town, and eThekwini each enforce distinct grid-connection standards and inspection protocols. This regulatory patchwork elevates soft costs and extends commissioning timelines for national installer networks.
- Diesel Generator Substitution:Backup power alternatives maintain installed base advantages in price-sensitive segments. Lower-income households and small commercial tenants often defer solar capital expenditure in favor of proven generator sets with minimal upfront outlay.
Strategic Opportunities
- Peri-Urban Municipalities:Secondary cities in the Eastern Cape and Free State present underpenetrated demand pools where land availability supports larger ground-mounted distributed systems serving multiple commercial off-takers.
- Wheeling Framework Liberalization:Pending reforms to cross-border electricity trading rules could enable commercial property owners in Gauteng to monetize excess generation through direct supply agreements with industrial consumers across municipal boundaries.
- Agrivoltaics Integration:Dual-use installations combining photovoltaic canopy structures with protected crop cultivation address land scarcity constraints. Wine estates in the Western Cape are piloting these configurations to diversify revenue streams.
Industry Challenges
- Certified Installer Pipeline:The South African Photovoltaic Industry Association reports insufficient accredited technicians to match installation demand growth. Training program expansion lags market expansion by approximately eighteen months.
- Grid Synchronization Standards:NERSA's evolving technical requirements for inverter compliance force repeated equipment specification changes. Project developers face stranded inventory risk when procurement cycles misalign with standard updates.
- Financing Documentation Burden:Residential solar loans require extensive property title verification and municipal rate clearance certificates. Middle-income households abandon applications due to administrative complexity despite available credit products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Rooftop Solar Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Grid-Tied, Off-Grid, Hybrid, Battery Backup Application: Residential, Commercial, Industrial, Agricultural Technology: Monocrystalline, Polycrystalline, Thin Film, Bifacial End User: Homeowners, Businesses, Farms, Institutions |
| Companies Covered | BrightBlack Energy, Sola Group, GENERGY, Sunworx Solar, Tasol Solar, Valsa Trading, PiA Solar SA, GoSolr, Solareff, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Rooftop Solar Market Strategic Shifts
Technology convergence between photovoltaic generation and battery storage is collapsing the traditional separation between energy production and consumption management. This integration is redefining system architecture, procurement evaluation criteria, and the competitive capabilities required of installation providers.
String inverter architectures with module-level power electronics are fragmenting the historical dominance of central inverter configurations in commercial deployments. Large-format rooftop projects in Johannesburg's industrial corridors are adopting these distributed electronics to mitigate shading losses and enable granular performance monitoring. The shift is compressing margins for traditional central inverter suppliers while elevating the technical sophistication required of system integrators.
South Africa's National Energy Regulator has proposed revisions to embedded generation tariff structures that would introduce time-of-use grid-use charges for exported electricity. Industrial off-takers with predictable consumption profiles are restructuring power purchase agreements to minimize exposure to peak-period grid charges. Mining operations in the Northern Cape are front-loading battery capacity in response to anticipated tariff rebalancing.
Direct equipment procurement by large commercial energy users is displacing traditional engineering-procurement-construction contracting models. Property portfolio managers with internal technical capabilities are sourcing modules and inverters separately, engaging installers for labor-only scopes. This unbundling is most visible in Cape Town's commercial real estate sector, where listed property trusts have established dedicated energy procurement functions.
South Africa Rooftop Solar Market Segmentation
Rooftop solar procurement patterns diverge sharply across system configurations and user profiles. Eskom's tariff restructuring and load-shedding persistence create asymmetric substitution pressures that reshape segment prioritization for installers and financiers.
System Type:
Hybrid configurations face the strongest diesel generator substitution threat in price-sensitive segments, while grid-tied systems confront municipal connection standard fragmentation.
- Grid-Tied:Direct grid-synchronous installations without storage dominate warehouse rooftops in Johannesburg's industrial corridors. Cape Town commercial property trusts favor these for maximum generation density per square meter where grid stability permits.
- Off-Grid:Fully autonomous systems with oversized battery banks serve remote agricultural operations in Limpopo and Mpumalanga where grid extension costs prove prohibitive. Diesel price volatility accelerates payback calculations for irrigation pumping loads.
- Hybrid:Grid-connected systems with integrated battery backup represent the steepest expansion curve as load-shedding schedules force storage co-investment. Mining operations in the Northern Cape front-load capacity to hedge against NERSA's proposed time-of-use grid charges.
- Battery Backup:Standalone storage retrofits for existing solar arrays concentrate in Gauteng commercial estates seeking peak-shaving capabilities. Lithium-ion supply chain concentration in East Asia exposes developers to currency fluctuation risk.
Grid-Tied retains volume leadership; Hybrid holds the steepest expansion curve.
Application:
Cost tier stratification separates premium commercial installations from constrained residential uptake, with industrial estates commanding the largest average system sizes.
- Residential:Single-family and multi-unit dwelling installations concentrate in middle-income Gauteng suburbs and Western Cape coastal municipalities. Financing documentation burdens including property title verification and municipal rate clearance certificates stall application completion despite available credit products.
- Commercial:Office buildings, retail centers, and hospitality properties in Cape Town's listed property trusts drive procurement unbundling toward direct equipment sourcing. Internal technical capabilities displace traditional engineering-procurement-construction contracting models.
- Industrial:Manufacturing facilities and logistics warehouses exploit the sub-100MW embedded generation licensing threshold to bypass municipal procurement delays. Warehouse operators prioritize monocrystalline PERC panels to maximize generation per available surface.
- Agricultural:Underpenetrated relative to commercial and industrial uptake, with wine estates in the Western Cape piloting agrivoltaic configurations combining photovoltaic canopy structures with protected crop cultivation.
Commercial applications command the highest revenue concentration; Agricultural represents the most underdeveloped margin pool.
Technology:
Module efficiency gains are concentrating procurement toward premium cell architectures, compressing polycrystalline market share.
- Monocrystalline:Single-crystal silicon cells with PERC architecture push conversion rates past 21%, shrinking rooftop footprint requirements. Johannesburg industrial developers specify these for space-constrained installations.
- Polycrystalline:Multi-crystal silicon modules retain cost advantages in price-sensitive peri-urban deployments. Secondary cities in the Eastern Cape and Free State show residual demand for these lower-specification panels.
- Thin Film:Cadmium-telluride and amorphous silicon configurations suit building-integrated applications where weight and flexibility outweigh efficiency metrics. Limited deployment in South Africa's efficiency-focused market.
- Bifacial:Dual-sided generation modules capture reflected irradiance from roof surfaces and ground mounting. Ground-mounted distributed systems in peri-urban municipalities exploit this technology for multi-off-taker arrays.
Monocrystalline dominates current procurement volumes; Bifacial is climbing the fastest as ground-mounted applications expand.
End User:
Customer sophistication tiers separate institutional buyers with dedicated energy procurement functions from households facing administrative complexity barriers.
- Homeowners:Individual residential adopters in Gauteng and Western Cape corridors encounter upfront capital barriers despite specialized financing products. Middle-income households abandon loan applications due to documentation burdens.
- Businesses:Corporate and SME energy users treat distributed generation as core infrastructure rather than supplementary supply. Commercial property owners accelerate capital reallocation from grid dependency to on-site systems.
- Farms:Agribusinesses in Limpopo and Mpumalanga retrofit diesel-dependent irrigation with grid-tied arrays. Predictable daytime pumping demand curves align with solar generation peaks.
- Institutions:Schools, hospitals, and government facilities with predictable consumption profiles restructure power purchase agreements to minimize exposure to peak-period grid charges.
Businesses drive the largest aggregate capacity additions; Farms show the fastest uptake acceleration among underpenetrated categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa exports rooftop solar engineering expertise and financing models into neighboring Southern African Development Community markets, while module supply chains flow inward from East Asian manufacturers through Durban and Cape Town ports.
Gauteng Province
Johannesburg's commercial property trusts drive aggregate capacity installations across warehouse and logistics corridors. The Department of Mineral Resources and Energy's sub-100MW embedded generation licensing threshold accelerates industrial estate self-sufficiency applications. Pretoria's peri-urban municipalities attract ground-mounted distributed systems serving multiple off-takers.
Western Cape Corridor
Cape Town's listed property trusts pioneer direct equipment procurement unbundling, displacing traditional engineering-procurement-construction contracts. The city's municipal grid-connection standards create distinct inspection protocols separate from Johannesburg and eThekwini. Wine estates in Stellenbosch and Paarl pilot agrivoltaic canopy structures combining photovoltaic generation with protected crop cultivation.
KwaZulu-Natal
eThekwini's port infrastructure positions Durban as the primary entry point for imported modules and battery components. The municipality's unique grid-connection bylaws fragment permitting timelines relative to Gauteng and Western Cape standards. Industrial zones in Pinetown and New Germany concentrate logistics-driven rooftop installations.
Eastern Cape
Secondary cities including Gqeberha and East London present underpenetrated demand pools with land availability for larger ground-mounted systems. The province's agricultural irrigation load profiles align with predictable daytime solar generation curves. Port Elizabeth's manufacturing base shows residual demand for cost-optimized polycrystalline configurations.
Limpopo and Mpumalanga
Agribusinesses retrofit diesel-dependent irrigation pumping systems with grid-tied arrays to hedge against fuel price volatility. Mining operations in the Northern Cape front-load battery capacity anticipating NERSA's proposed time-of-use grid charges. Remote agricultural operations deploy fully autonomous off-grid systems where grid extension costs prove prohibitive.
South Africa Rooftop Solar Market Competitive Environment
Player mix skews toward vertically integrated engineering specialists and residential financing platforms rather than pure equipment distributors. Market structure concentrates around Johannesburg and Cape Town operational footprints, with secondary city expansion emerging as the primary vector for growth capture. Three archetypes dominate: engineering-led commercial installers, residential finance-integrated providers, and geographic expansion specialists targeting peri-urban municipalities. Competitive dynamics center on procurement unbundling capabilities and installer certification pipeline development.
Among engineering-integrated specialists, Sola Group anchors the commercial contract segment through vertically controlled project delivery. Sunworx Solar occupies the residential finance tier with specialized capital products reducing upfront barriers. Tasol Solar exemplifies the geographic expansion archetype, pushing installation capacity into secondary cities and peri-urban municipalities beyond core metro concentrations.
| Leading Market Players |
|---|
| BrightBlack Energy |
| Sola Group |
| GENERGY |
| Sunworx Solar |
| Tasol Solar |
| Valsa Trading |
| PiA Solar SA |
| GoSolr |
| Solareff |
| Others |
Value Chain & Pricing Dynamics
NERSA's evolving grid synchronization standards gate both equipment qualification and installer certification tiers, simultaneously filtering supply-side participants and segmenting pricing power across certified versus uncertified project channels. This regulatory scaffolding compresses margins for non-compliant inventory while elevating premium capture for firms with forward-certified component pipelines.
Pricing Analysis
Monocrystalline PERC modules command a generation premium over polycrystalline alternatives, while next-generation bifacial configurations extract further uplift for ground-mounted applications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with price erosion running through polycrystalline tiers as efficiency gaps widen. Industrial estate buyers in Gauteng show lowest price sensitivity due to diesel substitution economics, while peri-urban residential segments in Eastern Cape municipalities exhibit acute cost consciousness.
Supply Chain Analysis
Extended lithium-ion battery lead times from East Asian cell manufacturers have forced South African developers to front-load procurement cycles and carry elevated working capital buffers. Module supply concentrates in China, South Korea, and Vietnam, with inverter electronics drawing from German and Chinese component ecosystems. Single-source vulnerability in battery cell supply exposes projects to currency fluctuation risk, while distribution runs through Durban and Cape Town port infrastructure with downstream fragmentation across Johannesburg, Cape Town, and eThekwini installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across municipal regulatory boundaries creates niche capture opportunities for specialized players with localized permitting expertise and relationships with provincial energy regulators.
For Market Incumbents: Fortify certification pipelines through South African Photovoltaic Industry Association accreditation programs to offset technician scarcity threats. Deepen backward integration into engineering-procurement-construction capabilities to defend against procurement unbundling by Cape Town property trusts with internal technical teams. Prioritize captive supply relationships with East Asian battery manufacturers to mitigate currency exposure on hybrid system components. For New Entrants and Emerging Players: Differentiate on agrivoltaic integration capabilities targeting Western Cape wine estates with dual-use canopy structures. Agricultural irrigation retrofit opportunities in Limpopo and Mpumalanga present the most penetrable segment given diesel price volatility and predictable daytime load profiles. Pursue municipal relationship-led go-to-market models in Eastern Cape secondary cities where land availability supports multi-off-taker ground-mounted arrays. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across residential financing platforms as standardized credit products reduce customer acquisition costs. Long-term viability favors vertically integrated engineering specialists with captive installation capacity rather than pure equipment distributors. Monitor NERSA embedded generation tariff reform announcements as the critical inflection signal for industrial battery front-loading demand.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Certification Program Expansion | South African Photovoltaic Industry Association accreditation addresses technician pipeline gaps constraining market growth. |
| Battery Supply Agreement Structuring | East Asian manufacturer contracts with currency hedging provisions mitigate hybrid system cost volatility. |
| Agrivoltaic Pilot Development | Western Cape wine estate canopy installations unlock dual-revenue streams from generation and crop protection. |
| Peri-Urban Municipal Expansion | Eastern Cape and Free State secondary cities offer underpenetrated demand pools with favorable land availability. |
| Direct Equipment Procurement Capability | Cape Town commercial property trust unbundling trends favor labor-only installation providers with technical sophistication. |
Study Parameters
Initial hypotheses were tested against primary input from IPP project developers, EPC contractors, municipal planning officers, and grid operators and refined through secondary validation across EIA data, IEA renewable energy reports, NERSA regulatory filings, and project development databases. Bottom-up installation volume estimates triangulated against top-down addressable rooftop surface calculations derived from commercial building stock assessments.
Variance decomposition across system configuration, application type, technology tier, and end-user sophistication dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth trajectory modeling incorporating Eskom tariff restructuring schedules, load-shedding persistence assumptions, and embedded generation licensing threshold evolution. Key inputs included monocrystalline PERC efficiency gain curves and lithium-ion battery cost decline trajectories.
Material uncertainties — municipal bylaw harmonization failures, NERSA tariff reform timing, and East Asian supply chain disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory continuity and technology cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Highway Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Solar Bicycle Shed Market