
 Renewable Energy in South America Market | 2026-2036
Renewable Energy in South America Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy in South America Market Insights
Utility-scale project certification is bifurcating the competitive landscape between developers capable of securing long-term power purchase agreements and smaller entrants locked out of grid access. Enel Green Power S.p.A. leverages its integrated development-engineering-procurement model across Chile and Peru. Iberdrola S.A. anchors its South American presence through Neoenergia S.A., controlling transmission access in Brazil's wind-rich Northeast. Statkraft competes on hydropower optimization expertise in Colombia and Peru.
Renewable energy in South America encompasses electricity generation systems harnessing solar irradiance, wind currents, river flows, and organic feedstocks through photovoltaic panels, horizontal-axis turbines, reservoir-fed turbines, and combustion or anaerobic digestion units. Hydropower occupies the largest installed base but faces reservoir volatility and social licensing constraints that constrain margin expansion. Solar photovoltaic leads capacity additions across Chile's Atacama and Brazil's semi-arid zones, where irradiance exceeds peak grid demand periods. Offshore wind remains nascent though southern Brazil's coastline attracts early-stage site assessments. Utilities dominate procurement volumes, while industrial off-takers in mining and green hydrogen pre-development increasingly bypass traditional distribution channels through corporate renewable power purchase agreements.
Brazil's ANEEL regulates grid connection queues and distributed generation net metering, directly shaping project economics for residential and commercial segments. Chile's Ministry of Energy and SEC enforce grid code compliance and environmental impact standards that filter developer capability. Argentina's national energy secretariat administers auction rounds under RenovAr and subsequent programs, determining market access through currency convertibility guarantees and local content requirements. Stakeholders must monitor whether transmission expansion keeps pace with generation queue depth, as interconnection bottlenecks increasingly determine which projects achieve commercial operation and which stall in permitting limbo.
Market Dynamics
Utility-scale solar and wind procurement queues in Brazil and Chile are creating a structural bottleneck where transmission access determines which developers achieve commercial operation and which projects stall in permitting limbo.
Growth Catalysts
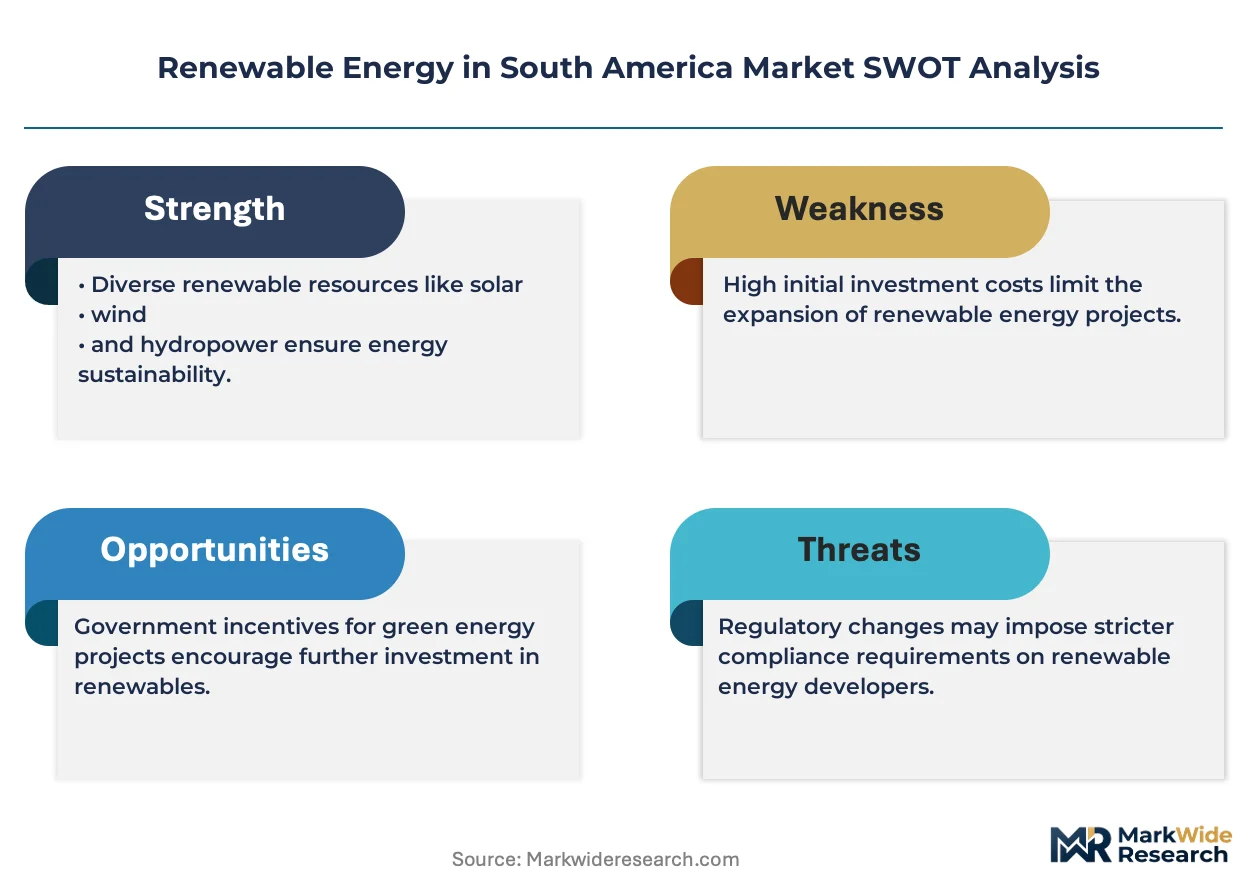
- Brazil's PROINFA framework:The national renewable energy incentive program mandates distributor procurement quotas that guarantee offtake for qualifying biomass, wind, and small hydro projects across the Northeast and semi-arid regions.
- Green hydrogen pre-development:Mining conglomerates in Chile's Atacama and industrial zones in southern Brazil are signing direct corporate renewable power purchase agreements that bypass traditional utility intermediaries.
- Argentina's RenovAr auction rounds:The national energy secretariat's competitive bidding mechanism provides currency convertibility guarantees that de-risk project finance for international capital providers.
Market Restraints
- Transmission interconnection queues:Brazil's ANEEL grid connection backlog exceeds 200 gigawatts of solar and wind capacity waiting for substation upgrades and line extensions.
- Local content requirements:Argentina's domestic manufacturing mandates for turbine towers and module assembly raise delivered equipment costs by constraining supplier choice to regional producers.
- Reservoir hydrology volatility:Colombia's reliance on runoff-dependent generation exposes power purchase agreement pricing to El Niño-driven drought cycles that compress thermal dispatch margins.
Strategic Opportunities
- Offshore wind site assessment:Southern Brazil's coastline from Rio Grande do Sul to Santa Catarina offers sustained wind resources that remain untapped by commercial-scale floating or fixed-bottom installations.
- Distributed generation net metering:Brazil's ANEEL regulatory framework for residential and commercial rooftop solar creates a fragmented installer market with consolidation potential in the Southeast metropolitan corridors.
- Hybrid solar-plus-storage configurations:Chile's Atacama Desert developers are pairing photovoltaic arrays with lithium-ion battery systems to capture evening peak pricing and satisfy mining offtaker reliability requirements.
Industry Challenges
- Grid code compliance engineering:Chile's SEC and Brazil's ONS enforce frequency response and reactive power standards that require specialized inverter programming and late-stage design revisions.
- Social licensing timelines:Indigenous consultation and land-use negotiations in Peru's Amazon basin and Colombia's Andean corridors extend environmental permitting by 18-36 months beyond technical construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy in South America Market |
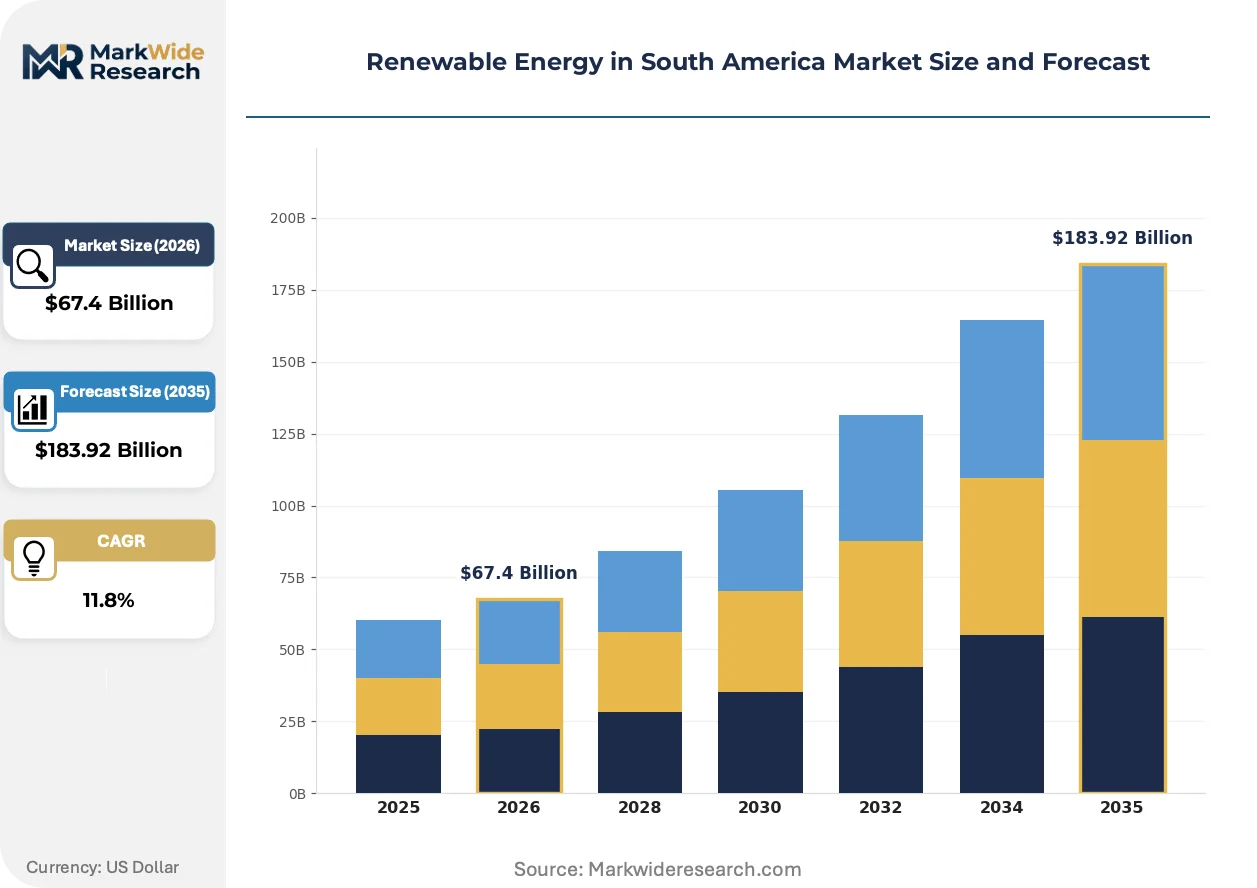
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $183.92 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Hydropower, Biomass Technology Type: Photovoltaic, Concentrated Solar Power, Offshore Wind, Onshore Wind End User: Utilities, Industrial Sector, Residential Customers, Commercial Establishments Application: Electricity Generation, Heating, Transportation, Off-Grid Solutions |
| Companies Covered | Enel Green Power S.p.A., Iberdrola S.A., ENGIE Brasil Energia S.A., Neoenergia S.A., AES Andes S.A., Statkraft, Alupar Investimento SA, Enel Americas SA, Mainstream Renewable Power, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy in South America Market Trends and Innovations
Bifacial photovoltaic modules and agrivoltaic land-use models are reshaping project economics across South America's high-irradiance zones, while digital twin platforms compress commissioning timelines for complex hybrid installations.
Bifacial solar panel technology captures reflected irradiance from ground surfaces and albedo-enhancing substrates, boosting energy yield by 8-15% in Chile's Atacama salt flat environments and Brazil's semi-arid caatinga biome. Mining operators in Peru and Chile are specifying bifacial configurations for direct-wire corporate supply contracts that displace diesel generation at remote extraction sites. This performance premium is fragmenting the module supplier landscape between premium bifacial producers and legacy monofacial manufacturers locked into utility-scale tenders with strict capex floors.
Chile's Ministry of Energy has enacted a carbon neutrality mandate for the national electricity system by 2050, backed by accelerated environmental permitting for renewable projects and carbon border adjustment exposure for energy-intensive exports. The regulation forces mining smelters and desalination plants to source verified renewable supply or face competitiveness penalties in European markets. Developers are responding by securing early-mover grid connection rights in the Atacama and Antofagasta regions ahead of transmission expansion timelines.
Industrial offtakers in Brazil's Minas Gerais iron ore belt and Chile's copper cathode sector are unbundling energy procurement from bundled utility tariffs, establishing dedicated renewable supply subsidiaries that negotiate directly with project sponsors. This disintermediation collapses the traditional distributor margin stack and transfers volume risk to corporate balance sheets. The practice is most advanced among multinational mining houses with sustainability-linked debt covenants requiring Scope 2 emissions reductions by 2030.
Renewable Energy in South America Market Segmentation
Margin concentration across South American renewable energy markets varies sharply by segment, with transmission-linked utility-scale projects commanding premium returns while distributed generation competes on installation velocity. Understanding where value pools settle within each segmentation dimension determines developer capital allocation and equipment supplier positioning strategies.
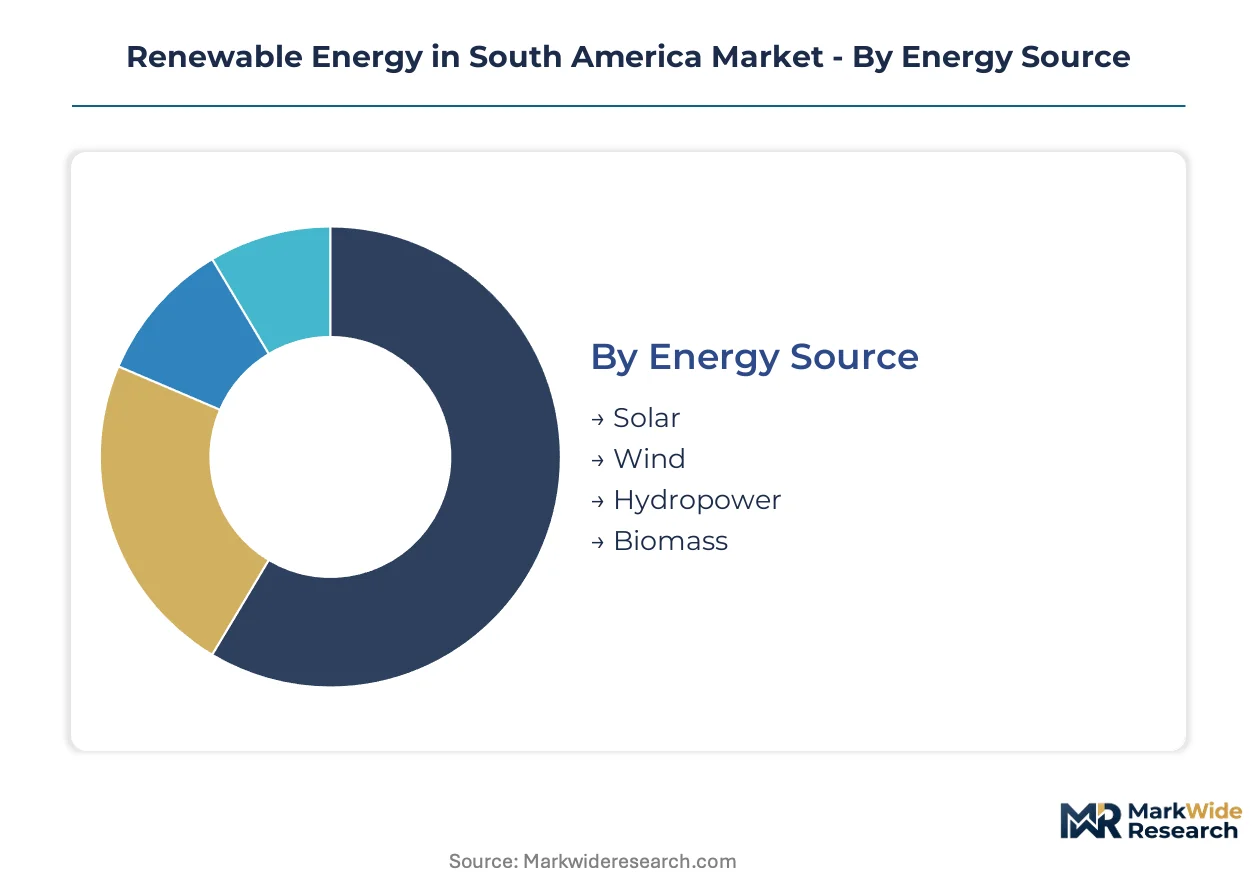
Energy Source:
Hydropower retains the deepest margin pools due to established reservoir infrastructure and long-term contracted offtake, though solar and wind are capturing incremental investment flows.
- Solar:Photovoltaic arrays dominate capacity additions across Chile's Atacama Desert and Brazil's Northeast semi-arid zones, where irradiance exceeds 2,400 kWh/m² annually. Mining operators in Antofagasta and copper smelters in Minas Gerais are signing direct corporate power purchase agreements that displace diesel generation and bypass utility intermediaries entirely.
- Wind:Onshore turbines anchor Brazil's generation mix, with the Rio Grande do Norte and Ceará corridors hosting the continent's densest project clusters. Grid connection queues at ANEEL now exceed 80 gigawatts of wind capacity awaiting substation upgrades, creating a structural bottleneck that filters developer viability.
- Hydropower:Reservoir-fed turbines supply baseline generation across Colombia, Peru, and southern Brazil, though El Niño-driven hydrology volatility compresses dispatch margins during drought cycles.
- Biomass:Bagasse combustion and agricultural residue digestion units serve captive industrial demand in São Paulo state's sugarcane belt and Argentina's Pampas grain corridor.
The dominant share belongs to hydropower, while solar is closing the gap fastest.
Technology Type:
Technology selection maps directly to geography, with photovoltaic and onshore wind commanding deployment volumes while concentrated solar and offshore wind remain pre-commercial.
- Photovoltaic:Silicon-based panel installations scale rapidly across high-irradiance zones, with bifacial module configurations capturing 8-15% yield premiums in Chile's salt flat environments through albedo-enhanced rear-side generation.
- Onshore Wind:Horizontal-axis turbines with 3-4 MW unit ratings dominate Brazil's procurement auctions, where PROINFA framework quotas guarantee offtake for qualifying projects in wind-rich Northeast states.
- Concentrated Solar Power:Parabolic trough and tower configurations with molten salt thermal storage occupy niche deployment in Chile's Atacama, limited by higher capex requirements against photovoltaic competition.
- Offshore Wind:Floating and fixed-bottom site assessments are advancing across southern Brazil's coastline from Rio Grande do Sul to Santa Catarina, though no commercial-scale projects have reached financial close.
Photovoltaic holds the installed base lead, though onshore wind is expanding most quickly in annual capacity additions.
End User:
Customer type determines contract structure, with utilities securing long-term auction-backed power purchase agreements while industrial offtakers pursue direct bilateral arrangements.
- Utilities:State-controlled distributors and generation companies in Brazil, Chile, and Colombia dominate procurement through regulated auction mechanisms and renewable portfolio obligations that guarantee offtake volumes.
- Industrial Sector:Mining conglomerates in Chile's copper cathode sector and iron ore operators in Brazil's Minas Gerais belt are unbundling energy procurement from bundled tariffs, establishing captive renewable supply subsidiaries with sustainability-linked debt covenants requiring Scope 2 emissions reductions.
- Residential Customers:Rooftop solar installations accelerate under Brazil's ANEEL net metering framework, with fragmented installer markets consolidating across São Paulo and Rio de Janeiro metropolitan corridors.
- Commercial Establishments:Shopping centers, data centers, and manufacturing facilities in Santiago and Buenos Aires deploy mid-scale distributed generation to hedge against regulated tariff volatility.
Utilities control the largest contract volumes, while industrial sector direct procurement is gaining share fastest.
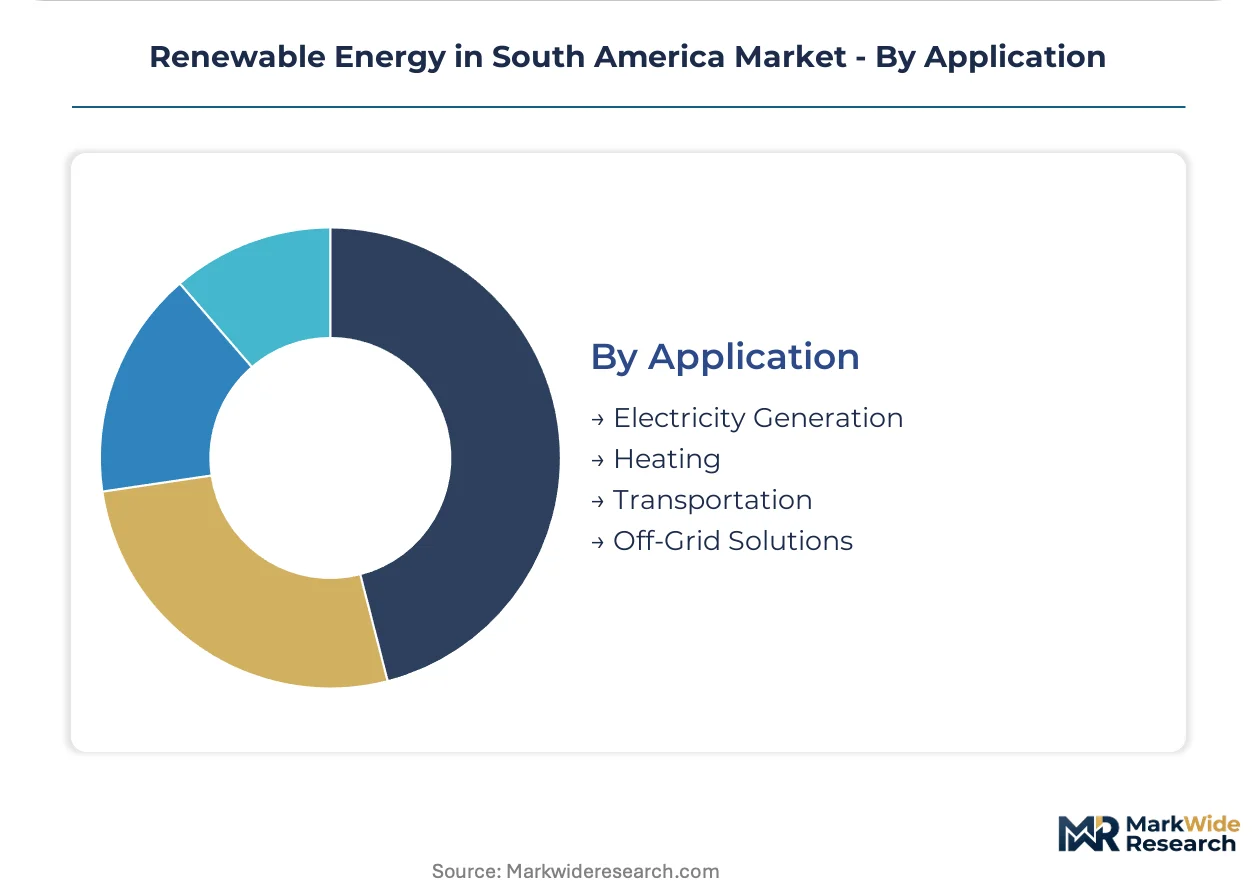
Application:
Application scope tracks electrification depth, with grid-connected generation commanding capital deployment while heating and transportation remain peripheral.
- Electricity Generation:Grid-connected renewable plants supply national transmission systems and isolated regional grids, with Chile's SING and SIC systems and Brazil's National Interconnected System absorbing the majority of new capacity.
- Off-Grid Solutions:Remote mining camps in Peru's Amazon basin and agricultural operations in Argentina's Patagonia deploy hybrid solar-diesel microgrids where transmission extension is economically unviable.
- Heating:Solar thermal collectors serve industrial process heat in Chile's mining sector and residential water heating in Brazil's Southeast, though penetration remains limited against natural gas competition.
- Transportation:Biofuel blending mandates in Brazil and Argentina support ethanol and biodiesel consumption, while electric vehicle charging infrastructure creates incremental renewable electricity demand in urban corridors.
Electricity generation captures the dominant application share, while off-grid solutions are climbing the fastest as remote industrial load growth outpaces transmission expansion timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South America's renewable energy trade flows reflect a net exporter position in hydroelectricity from Colombia and Paraguay, balanced by equipment import dependence for solar modules and wind turbines from Asia. Currency volatility across Argentina and Brazil shapes project finance structures, while transmission infrastructure gaps create intra-regional arbitrage opportunities.
Brazil
Utility-scale wind and solar procurement accelerates through ANEEL-regulated auctions, with over 80 gigawatts of capacity queuing for grid connection in the Northeast corridor. The PROINFA framework mandates distributor quotas that guarantee offtake for qualifying biomass, wind, and small hydro projects. Developers concentrate activity in Rio Grande do Norte and Ceará, where sustained trade winds and expanding transmission backbone attract international capital.
Chile
Mining sector electrification drives corporate renewable power purchase agreements in the Atacama Desert, where irradiance exceeds 2,400 kWh/m² annually. The Ministry of Energy and SEC enforce grid code compliance and carbon neutrality mandates for the 2050 electricity system target. Project sponsors secure early-mover connection rights in Antofagasta and Tarapacá ahead of transmission expansion timelines.
Argentina
RenovAr auction rounds provide currency convertibility guarantees that de-risk project finance for international investors in wind and solar developments. The national energy secretariat administers local content requirements for turbine towers and module assembly that raise delivered equipment costs. Developers target the Patagonia wind corridor and Cuyo solar zone, where resource quality offsets construction financing premiums.
Colombia
Runoff-dependent hydropower dominates generation mix, exposing power purchase agreement pricing to El Niño-driven drought cycles that compress thermal dispatch margins. The Mining and Energy Planning Unit (UPME) regulates grid expansion planning and renewable energy integration standards. Developers pursue diversification into solar and wind in the Guajira Peninsula, where indigenous consultation requirements extend permitting timelines.
Peru
Remote mining camps in the Amazon basin deploy hybrid solar-diesel microgrids where transmission extension remains economically unviable. The Ministry of Energy and Mines oversees concession auctions and environmental certification for renewable projects. Developers navigate social licensing negotiations in Andean corridors and jungle regions, where land-use agreements extend construction schedules by 18-36 months.
Renewable Energy in South America Market Competitive Landscape
Listed utilities compete with private developers across transmission access and long-term contract origination. Market structure concentrates around integrated generation-transmission groups capable of securing grid connection rights ahead of queue depth. Three archetypes dominate: European-headquartered multinationals with integrated development models, Latin American utilities with regional transmission control, and specialized renewable developers focused on corporate offtaker relationships. Competitive dynamics center on early-stage site acquisition and strategic partnerships with mining and industrial load centers.
Within the multinational tier, Enel Green Power S.p.A. and Iberdrola S.A. exemplify integrated development-engineering-procurement capabilities across Chile and Brazil. Statkraft occupies a position anchored on hydropower optimization expertise in Colombia and Peru. These entities represent the scale-driven segment where transmission-linked project pipelines determine competitive positioning.
| Leading Market Players |
|---|
| Enel Green Power S.p.A. |
| Iberdrola S.A. |
| ENGIE Brasil Energia S.A. |
| Neoenergia S.A. |
| AES Andes S.A. |
| Statkraft |
| Alupar Investimento SA |
| Enel Americas SA |
| Mainstream Renewable Power |
| Others |
Pricing and Supply Chain Analysis
Ninety-day module inventory buffers at Brazilian port terminals concentrate pricing power with integrated developers holding warehouse capacity, while spot buyers absorb volatility from Asia-Pacific shipping schedules. Contract structures bifurcate between long-term offtake agreements indexed to ANEEL auction floors and corporate PPAs negotiated directly with mining houses in Chile's Atacama.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across South American renewable markets. Price differentiation separates grid-connected utility-scale projects with secured transmission access from distributed generation competing on installation velocity and net metering arbitrage. Cost compression in module procurement is intensifying because Chinese manufacturers are diverting oversupply into Latin American spot markets. Mining conglomerates in Chile's copper belt exhibit lowest price sensitivity due to carbon border adjustment exposure, while residential rooftop installers in Brazil's Southeast face margin erosion from fragmented competition.
Supply Chain Analysis
China, Vietnam, and Malaysia anchor photovoltaic module assembly and wind turbine component fabrication feeding South American project pipelines. Equipment procurement draws from polysilicon wafers, rare-earth magnets for turbine drivetrains, and lithium-ion cells for hybrid storage configurations. Single-source vulnerability concentrates in high-voltage inverter supply where European and Chinese manufacturers dominate certified product lists. Distribution runs through EPC contractors with established logistics networks into Brazil's Northeast wind corridor and Chile's Atacama solar zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green hydrogen pre-development across South America represents a high-growth disruption, accelerated by Chile's carbon neutrality mandate forcing mining sector electrification and Brazil's offshore wind site assessments attracting early-stage capital deployment.
For Market Incumbents: Shield transmission-linked project pipelines by securing substation upgrade schedules ahead of ANEEL queue depth, and deepen backward integration into energy storage system assembly to capture hybrid configuration premiums as mining offtakers demand evening peak reliability. For New Entrants and Emerging Players: Anchor in Argentina's RenovAr auction rounds where currency convertibility guarantees de-risk project finance for international capital providers, and target distributed generation net metering in Brazil's Southeast metropolitan corridors where installer consolidation creates acquisition opportunities for scaled platforms. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-transition play because transmission expansion timelines determine which generation assets achieve commercial operation versus permitting limbo. Acquisition targets should emphasize developers with secured grid connection rights in Chile's Antofagasta region or Brazil's Rio Grande do Norte corridor. The signal to watch is interconnection queue clearance rates relative to generation capacity additions.| Strategic Initiative | Industry Significance |
|---|---|
| Transmission-Linked Capacity Buildout | Secures commercial operation dates ahead of ANEEL queue bottlenecks in Brazil's Northeast corridor. |
| Corporate Power Purchase Agreement | Bypasses utility intermediaries for mining sector offtakers facing Scope 2 emissions reduction covenants. |
| Hybrid Solar-Plus-Storage Configuration | Captures evening peak pricing for Chilean mining operators requiring dispatchable renewable supply. |
| Backward Integration into Inverter Assembly | Reduces grid code compliance engineering costs for SEC and ONS reactive power standards. |
| Offshore Wind Site Assessment | Positions early-mover advantage across southern Brazil's untapped Rio Grande do Sul coastline. |
Research Methodology
Desk research of EIA generation statistics, IEA renewable investment flows, ANEEL regulatory filings, and project development databases preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork captured transmission queue dynamics, corporate PPA negotiation structures, and social licensing timeline variability. Secondary validation drew from customs records tracking module import volumes and equipment supplier shipment disclosures. Bottom-up project pipelines were triangulated against top-down regulatory capacity targets.
Variance decomposition across the projection horizon isolates capacity addition drivers by energy source, generation scale tier, regulatory framework, and regional grid type. CAGRs were derived from segmented growth trajectory modeling incorporating auction schedule visibility, transmission expansion commitments, and offtaker demand elasticity. Forecast inputs include El Niño hydrology cycles affecting Colombian dispatch margins and currency volatility indices shaping Argentine project finance structures.
Material uncertainties — drought-driven thermal dispatch spikes, auction round cancellations, and transmission construction delays — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory continuity for PROINFA and RenovAr frameworks, social licensing timeline normalization, and grid code compliance standardization. Recalibration cycles align with material shifts in interconnection queue clearance rates, green hydrogen offtake commitments, and carbon border adjustment implementation in European export markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
China Wind Energy Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Green Renewable Energy Market