
 West Europe Renewable Energy Market | 2026-2036
West Europe Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
West Europe Renewable Energy Market Insights
The EU Green Deal is consolidating the cost-of-entry calculus for new renewable developers across West Europe. Vestas Wind Systems A/S leverages its turbine manufacturing scale to dominate Northern European offshore installations. Siemens Gamesa Renewable Energy SA anchors its position through specialized blade engineering and service density across Iberian wind corridors. Ørsted sustains technology leadership in floating offshore platforms while navigating tighter EU supply-chain audit requirements.
West Europe renewable energy encompasses electricity generation from solar photovoltaic arrays, onshore and offshore wind turbines, biomass combustion systems, and run-of-river hydropower facilities, typically operating at grid-scale voltages of 110 kV to 400 kV for transmission integration. Wind turbine technology leads installed capacity across the region, with offshore segments commanding premium margins due to foundation complexity and cable installation depth. Photovoltaic deployment accelerates fastest among residential end users, driven by streamlined permitting in France and Italy. Utility-scale biomass retains structural importance in Germany and Austria where district heating networks create baseload demand.
EMA carbon neutrality guidelines, EU Green Deal investment screening, and national renewable auction designs in Germany, France, and Spain collectively determine project bankability and technology selection. REACH compliance for turbine blade materials and F-Gas Regulation phase-downs for heat pump refrigerants add compliance layers that favor established suppliers with in-house certification teams. Stakeholders must monitor auction price floors and grid connection queue reforms as these mechanisms will determine which technology portfolios secure capacity awards.
Market Dynamics
Carbon border adjustments under the EU Green Deal are restructuring project finance requirements across West Europe, forcing developers to front-load compliance costs and reconfigure supply chain documentation before construction begins.
Growth Catalysts
- Corporate PPA Expansion:Industrial power buyers in Germany and France are scaling contracted renewable offtake, creating bankable revenue streams for utility-scale developers without relying solely on merchant price exposure.
- Streamlined Permitting:France and Italy have reduced authorization timelines for residential photovoltaic installations, accelerating deployment velocity among distributed energy prosumers.
- EU Green Deal Investment Screening:The framework channels institutional capital toward certified low-carbon projects, elevating project bankability scores for compliant developers in auction rounds.
Market Restraints
- Foundation Cost Escalation:Offshore wind installation requires specialized vessel fleets and subsea cable laying capacity, concentrating execution risk among North Sea port infrastructure operators.
- Blade Material Compliance:REACH regulations governing epoxy resins and carbon fiber composites in turbine manufacturing add certification layers that extend procurement cycles for blade suppliers.
- Grid Connection Queues:Transmission system operators in Spain and Portugal face backlogged interconnection requests, delaying commercial operation dates for completed solar and wind assets.
Strategic Opportunities
- Floating Offshore Platforms:Deep-water wind sites off the Iberian coast and in the Bay of Biscay remain underpenetrated, offering first-mover advantages for foundation technology specialists.
- District Heating Integration:Biomass and geothermal assets in Germany and Austria can anchor municipal heating network decarbonization, securing long-term baseload offtake contracts.
- F-Gas Phase-Down Arbitrage:Heat pump manufacturers capturing refrigerant transition timelines under the EU F-Gas Regulation can secure premium positioning in residential and commercial building retrofits.
Industry Challenges
- Specialized Technician Scarcity:Offshore turbine maintenance and high-voltage cable installation require certified crews that training programs in France and Germany have not yet scaled to match deployment targets.
- Supply Chain Audit Complexity:EU Green Deal due diligence rules mandate documented carbon intensity across component tiers, forcing developers to requalify suppliers and extend procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Europe Renewable Energy Market |
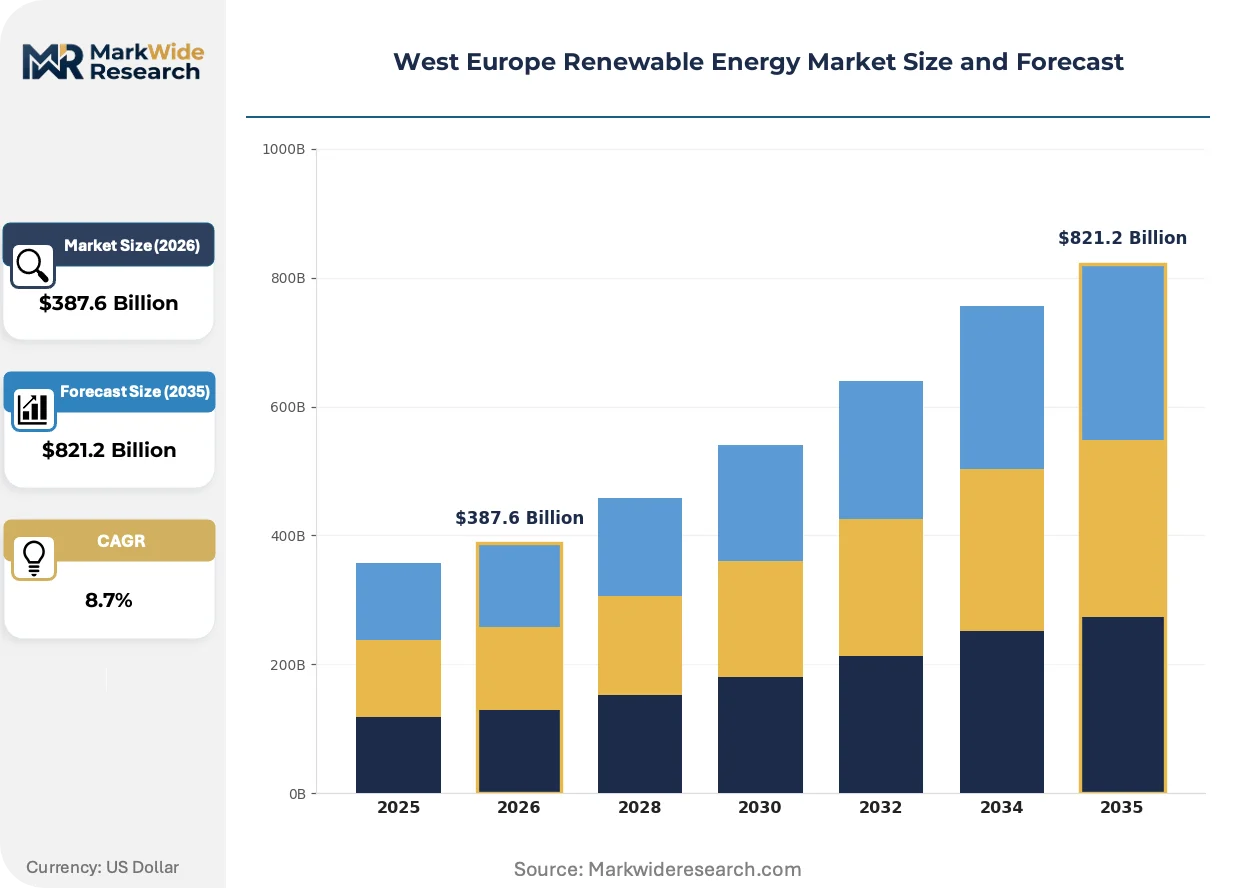
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Hydropower Technology: Photovoltaic, Wind Turbine, Geothermal, Tidal End User: Residential, Commercial, Industrial, Utilities Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | Renewable Energy Systems Ltd, Vestas Wind Systems A/S, Electricite de France SA, Siemens Gamesa Renewable Energy SA, Engie SA, TotalEnergies, Iberdrola, Ørsted, RWE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Europe Renewable Energy Market Trends and Innovations
Technology convergence and regulatory tightening are compressing development cycles while elevating performance thresholds for grid-connected assets across West Europe.
Agrivoltaic array deployment is electrifying rural land use economics by enabling simultaneous agricultural production and solar generation on the same plots. French and Italian farming cooperatives are piloting these dual-use installations to diversify revenue streams. The configuration is compressing land acquisition conflicts that previously stalled utility-scale solar expansion in agricultural zones.
EU Green Deal carbon border adjustment mechanisms are imposing emissions documentation requirements on imported steel, cement, and polysilicon used in turbine and panel manufacturing. Developers must now secure supply chain attestations before financial close. German and Spanish project sponsors are responding by regionalizing component sourcing to reduce compliance friction.
Industrial offtakers are consolidating procurement through long-term power purchase agreements that bypass traditional utility intermediaries. Data center operators in the Netherlands and automotive manufacturers in Germany are negotiating directly with renewable developers for dedicated capacity. This disintermediation is most visible in the Netherlands, where grid constraints have made physical delivery contracts preferable to virtual PPAs.
West Europe Renewable Energy Market Segmentation
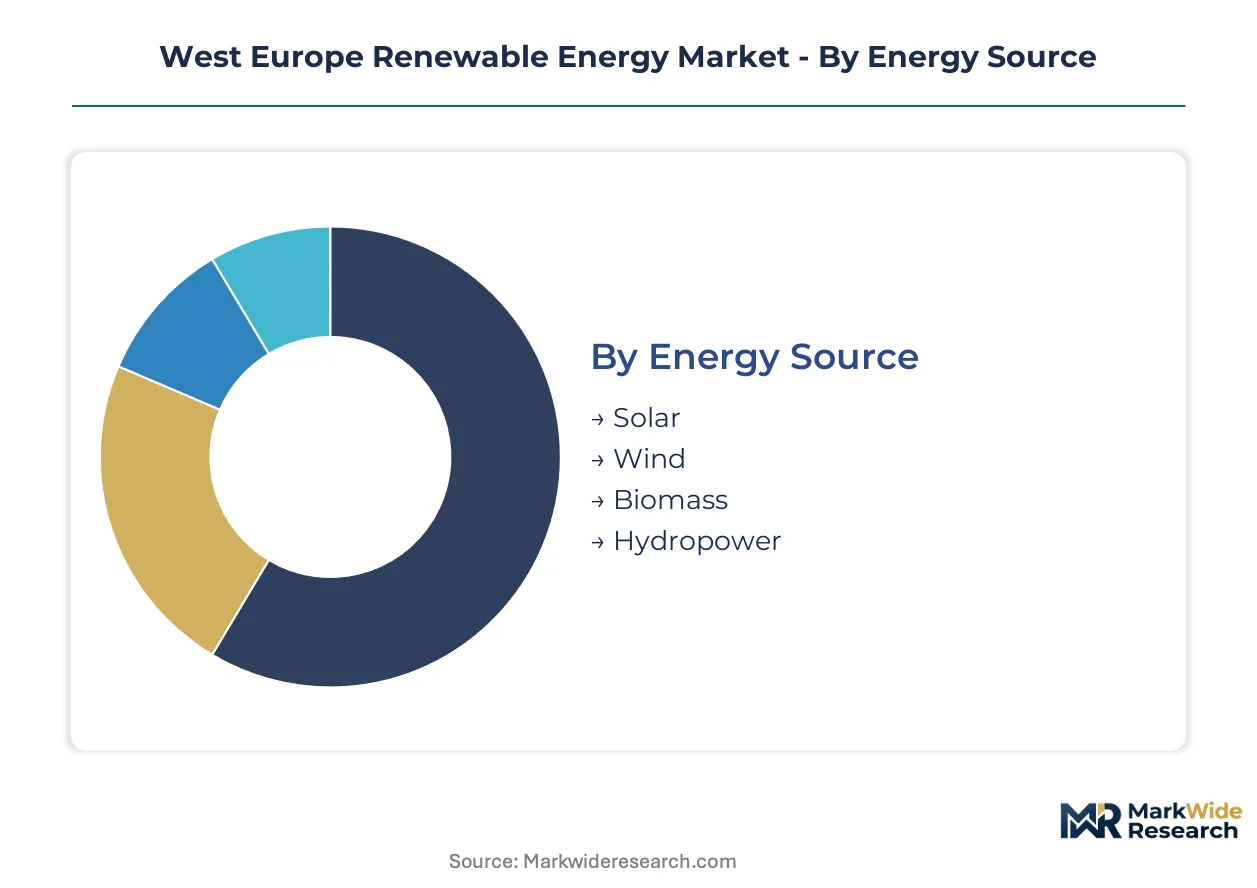
Segmentation in West Europe renewable energy reveals how technology maturity, customer risk profiles, and service bundling determine project economics. Developers select segment combinations based on auction design, grid access timelines, and offtake creditworthiness rather than technology preference alone.
Energy Source:
Developers differentiate by resource availability, land use constraints, and capacity factor predictability when selecting energy sources for West European deployment.
- Solar:Photovoltaic arrays dominate residential deployment in France and Italy where streamlined rooftop permitting accelerates prosumer adoption. Utility-scale projects in Spain and Portugal face land acquisition competition from agricultural interests, compressing development timelines for ground-mounted installations.
- Wind:Offshore turbines command foundation complexity premiums in the North Sea and Bay of Biscay, while onshore corridors in Northern Germany and Iberia face community acceptance thresholds that shape site selection. Grid connection queues for completed wind assets in Spain and Portugal currently delay commercial operation dates.
- Biomass:Combustion systems retain structural importance in Germany and Austria where district heating networks create baseload demand that stabilizes revenue streams.
- Hydropower:Run-of-river facilities operate at grid-scale voltages across Alpine geographies, constrained by environmental flow requirements and seasonal precipitation variability.
Volume sits with Wind; growth tilts toward Solar.
Technology:
Technology selection tracks capital intensity, component supply chain localization, and EU Green Deal compliance documentation requirements.
- Photovoltaic:Module efficiency gains and polysilicon sourcing transparency dominate procurement decisions. German and Spanish project sponsors regionalize component sourcing to satisfy carbon border adjustment attestations.
- Wind Turbine:Foundation engineering and blade material REACH compliance extend procurement cycles. Specialized vessel fleets for offshore installation concentrate execution risk among North Sea port operators.
- Geothermal:Deep drilling expertise and subsurface exploration risk limit deployment to Rhine Graben and Upper Rhine Valley geological formations.
- Tidal:Prototype testing in Brittany and Scottish waters encounters marine consenting complexity that stretches development horizons beyond conventional renewable timelines.
Installed base concentrates in Wind Turbine; capacity additions favor Photovoltaic.
End User:
Customer segmentation reflects offtake contract duration, credit rating, and physical delivery requirements versus virtual PPA structures.
- Residential:Prosumers in France and Italy deploy rooftop systems under streamlined permitting regimes, with financing bundled through green mortgage products and energy cooperative structures.
- Commercial:Mid-size enterprises in the Netherlands and Germany negotiate directly with developers for dedicated capacity, bypassing utility intermediaries where grid constraints make physical delivery preferable to synthetic hedges.
- Industrial:Automotive manufacturers in Germany and data center operators in the Netherlands scale contracted renewable offtake through long-term power purchase agreements that create bankable revenue streams.
- Utilities:Incumbent generators participate in national renewable auctions in Germany, France, and Spain, with auction price floors and grid connection queue reforms determining technology portfolio awards.
Contracted volume clusters with Utilities; margin expansion tracks Industrial.
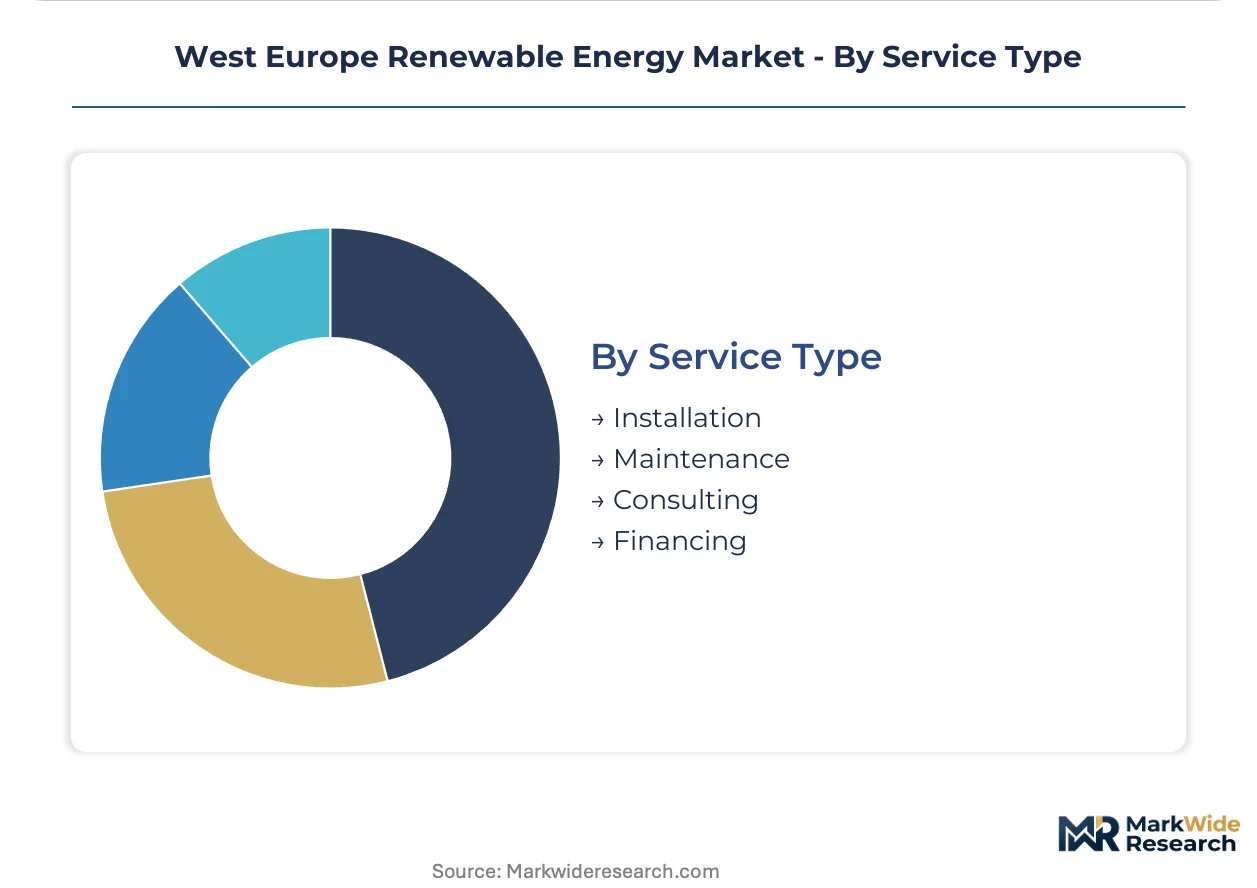
Service Type:
Service bundling separates full-stack developers from specialized component suppliers based on project phase and risk retention preferences.
- Installation:Execution risk concentrates in offshore foundation specialists and high-voltage cable laying contractors where certified crew scarcity in France and Germany has not scaled to match deployment targets.
- Maintenance:Service density agreements across Iberian wind corridors anchor recurring revenue for turbine OEMs with regional technician networks.
- Consulting:Permitting navigation and EU Green Deal investment screening compliance command premium fees as regulatory layers multiply.
- Financing:Project bankability scoring under EMA carbon neutrality guidelines channels institutional capital toward certified low-carbon developments.
Revenue scale favors Installation; recurring value accumulates in Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial power buyers in Germany and France are concentrating contracted renewable offtake, while Spain and Portugal emerge as utility-scale solar and wind demand centers. The EU Green Deal's carbon border adjustments are restructuring project finance requirements across all West European markets.
Germany
Automotive manufacturers and data center operators are scaling corporate PPAs to secure dedicated renewable capacity. The national renewable auction design under the EEG framework determines technology portfolio awards through price floors and grid connection reforms. The North Sea ports of Bremerhaven and Cuxhaven host specialized vessel fleets for offshore wind foundation installation.
France
Streamlined rooftop permitting accelerates residential photovoltaic deployment among prosumer households. EMA carbon neutrality guidelines channel institutional capital toward certified low-carbon developments in national auction rounds. The Île-de-France region concentrates data center operators negotiating direct physical delivery contracts with developers.
Spain
Utility-scale solar and wind developers face land acquisition competition from agricultural interests in ground-mounted project zones. Grid connection queue backlogs at transmission system operators delay commercial operation dates for completed assets. The Castilla-La Mancha and Extremadura regions host concentrated agrivoltaic pilot installations enabling dual-use land economics.
Netherlands
Grid constraints make physical delivery power purchase agreements preferable to virtual hedges for industrial offtakers. The F-Gas Regulation phase-down creates premium positioning opportunities for heat pump manufacturers capturing refrigerant transition timelines. The Rotterdam port cluster anchors North Sea offshore wind cable installation and foundation component logistics.
Portugal
Deep-water wind sites off the Atlantic coast remain underpenetrated, offering first-mover advantages for floating offshore platform specialists. EU Green Deal supply chain audit requirements mandate documented carbon intensity across imported steel and cement for turbine manufacturing. The Porto and Lisbon metropolitan areas concentrate permitting navigation consultants serving international project sponsors.
West Europe Renewable Energy Market Competitive Landscape
Danish and German producers anchor the offshore wind turbine tier; Spanish and French utility specialists hold integrated generation portfolios. The market structure concentrates around three strategic archetypes: turbine original equipment manufacturers with service density networks, vertically integrated utility-scale developers with auction execution capabilities, and specialized foundation engineering firms with subsea installation expertise. Competitive positioning hardens through regionalized component sourcing to satisfy carbon border adjustment attestations, and through long-term maintenance agreements locking in recurring revenue across Iberian wind corridors.
Among Danish turbine specialists, Vestas Wind Systems A/S and Ørsted occupy positions exemplifying manufacturing scale and floating platform technology leadership respectively. Siemens Gamesa Renewable Energy SA represents the Spanish-German engineering archetype with specialized blade capabilities. These three entities anchor the competitive landscape by demonstrating how EU REACH compliance for epoxy resins and carbon fiber composites, combined with regional technician network density, separates bankable project sponsors from development-stage competitors.
| Leading Market Players |
|---|
| Renewable Energy Systems Ltd |
| Vestas Wind Systems A/S |
| Electricite de France SA |
| Siemens Gamesa Renewable Energy SA |
| Engie SA |
| TotalEnergies |
| Iberdrola |
| Ørsted |
| RWE |
| Others |
Pricing and Supply Chain Analysis
Polysilicon and epoxy resin costs cascade through turbine blade and photovoltaic module manufacturing into three-tier pricing structures across premium certified, standard utility-grade, and economy residential tiers in West Europe. Carbon border adjustment documentation requirements under EU Green Deal rules amplify procurement friction for imported inputs, compressing margins for developers unable to regionalize component sourcing.
Pricing Analysis
Premium pricing for expedited turbine blade delivery compresses procurement cycles for offshore wind developers facing vessel charter windows in North Sea ports. Contract-based long-term offtake agreements dominate utility-scale transactions, with price differentiation tracking certification tier under EMA carbon neutrality guidelines and volume scale in national auction rounds. Cost compression in residential photovoltaic systems intensifies as streamlined permitting in France and Italy accelerates installer competition. Industrial offtakers in Germany exhibit lowest price sensitivity due to carbon border exposure, while residential prosumers in Italy demonstrate highest sensitivity to upfront capital requirements.
Supply Chain Analysis
Regional distribution centers at Bremerhaven, Rotterdam, and Bilbao anchor hub-and-spoke logistics patterns for offshore wind foundation components across North Sea and Bay of Biscay development zones. Manufacturing concentrates in Denmark for turbine nacelles, Spain for blade engineering, and Germany for grid-scale inverter systems. Raw material flows draw from Chinese polysilicon, German steel, and Portuguese cement for floating platform gravity bases. Single-source vulnerability in specialized installation vessel fleets concentrates execution risk among North Sea port operators. Distribution runs through EPC contractor networks with direct-to-project-site delivery for utility-scale assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
West Europe renewable energy is consolidating around developers with integrated supply chain documentation capabilities, as EU Green Deal audit requirements force acquisition-dependent competitors into distressed exits.
For Market Incumbents: Cement technology leadership by capturing floating offshore platform installation slots at Iberian deep-water sites before specialized vessel capacity saturates. Deepen backward integration into blade material certification under REACH regulations to lock out competitors dependent on third-party epoxy resin suppliers. Acquire regional technician training programs in France and Germany to preempt crew scarcity bottlenecks threatening maintenance revenue streams.
For New Entrants and Emerging Players: The mid-market price-point gap between premium certified developments and economy residential installations offers white-space entry for agrivoltaic specialists serving French and Italian farming cooperatives. Target district heating integration contracts in German and Austrian municipal networks where baseload offtake stabilizes revenue. Deploy permitting navigation services as lead offering to international sponsors unfamiliar with EU Green Deal investment screening protocols.
For Investors and Strategic Acquirers: Grid connection queue clearance at Spanish and Portuguese transmission system operators is the leading indicator that project development backlogs will convert to operational cash flows. Long-term viability across the analysis window favors vertically integrated developers with captive maintenance networks over pure-play installation contractors. Monitor auction price floor adjustments in German EEG rounds as signal for margin compression timing in utility-scale segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Component Sourcing | Reduces EU Green Deal carbon border attestation friction for German and Spanish project sponsors. |
| Floating Platform Technology Licensing | Unlocks deep-water sites off Portugal and Bay of Biscay for first-mover Iberian developers. |
| Agrivoltaic Pilot Expansion | Resolves land acquisition conflicts in Castilla-La Mancha agricultural zones for Spanish solar developers. |
| Corporate PPA Direct Negotiation | Bypasses utility intermediaries for Netherlands data center operators facing physical delivery constraints. |
| Technician Training Program Acquisition | Secures certified crew pipelines for offshore maintenance contracts across French and German North Sea assets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with WindEurope statistics, IEA renewable deployment databases, and national auction results from Bundesnetzagentur, CRE, and REE enabled bottom-up and top-down triangulation across technology segments.
Data-stream reconciliation across project development pipelines, installed capacity registries, and corporate offtake announcements shaped the analytical framework. Segmentation dimensions modeled include energy source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from capacity addition trajectories and revenue-per-megawatt assumptions across the projection horizon, incorporating auction price evolution and supply chain cost indices.
Inputs from transmission system operators and permitting authorities were available through the study window; gaps in floating offshore platform cost benchmarks introduce uncertainty bands around deep-water deployment forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Philippines Renewable Energy Market