
 Azerbaijan Renewable Energy Market | 2026-2036
Azerbaijan Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Azerbaijan Renewable Energy Market Outlook
Modular solar-plus-storage configurations are broadening buyer choice across Azerbaijan's renewable procurement landscape. ACWA Power International leverages its integrated development model to anchor large-scale independent power projects in priority zones. Abu Dhabi Future Energy Company PJSC (Masdar) sustains technology leadership through concentrated solar thermal and photovoltaic hybrid designs. Azerenerji JSC dominates legacy grid infrastructure and navigates the transition from thermal baseload to variable renewable integration.
Azerbaijan renewable energy encompasses solar photovoltaic, onshore wind, small-to-large hydropower, and biomass conversion systems operating within a continental climate zone with 2,200-2,800 annual sunshine hours and Caspian Sea wind corridors exceeding seven meters per second at 50-meter hub heights; these resources feed national grid expansion, industrial decarbonization, and rural electrification objectives. Solar Power leads installed capacity growth due to falling module costs and short construction cycles, while Wind Turbines occupy higher-margin positions in coastal and mountainous terrain where capacity factors justify extended development timelines. Hydropower retains structural importance as a dispatchable balancing resource amid rising variable generation penetration.
Azerbaijan's Ministry of Energy implements renewable auction mechanisms aligned with presidential decrees on clean energy targets, while the State Agency on Alternative and Renewable Energy Sources enforces technical standards for grid interconnection and equipment certification. The country's national regulator for electricity sets transmission tariff structures that influence renewable project economics and merchant revenue exposure. Stakeholders must monitor auction design evolution and domestic content requirements that could reshape supplier selection and capital deployment timelines.
Market Dynamics
Feed-in tariff revisions and grid connection priority rules are accelerating project timelines for solar and wind developers serving industrial offtakers in aluminum smelting and petrochemicals. The Ministry of Energy's auction mechanisms are compressing approval cycles while concentrating deployment in high-irradiance zones.
Growth Catalysts
- Presidential Decree Framework:Clean energy targets established under presidential decrees mandate renewable capacity additions that lock in long-term demand visibility for developers.
- Aluminum Smelting Load:Energy-intensive smelters in the Absheron Peninsula are executing power purchase agreements that anchor utility-scale project finance.
- Caspian Wind Corridors:Seven-meter-per-second wind speeds at 50-meter hub heights in coastal zones justify extended development timelines for higher-margin turbine installations.
Market Restraints
- Grid Integration Costs:Legacy thermal baseload infrastructure operated by Azerenerji JSC requires substantial balancing investment to accommodate variable renewable penetration.
- Domestic Content Requirements:Evolving local equipment sourcing rules under the State Agency on Alternative and Renewable Energy Sources extend supplier qualification timelines.
- Module Price Volatility:Solar photovoltaic component cost fluctuations compress developer margins on fixed-tariff projects.
Strategic Opportunities
- Nakhchivan Autonomous Republic:Isolated grid conditions and superior irradiance levels create favorable economics for modular solar-plus-storage configurations.
- Hybrid Technology Convergence:Concentrated solar thermal and photovoltaic hybrid designs are opening dispatchable renewable positions previously reserved for conventional thermal.
- Rural Electrification Channels:Distributed generation partnerships with agricultural cooperatives are bypassing centralized procurement bottlenecks.
Industry Challenges
- Variable Generation Forecasting:Grid operators lack real-time meteorological data integration to manage ramp events from utility-scale solar and wind assets.
- Interconnection Queue Management:Technical standards enforcement by the State Agency on Alternative and Renewable Energy Sources creates certification backlogs for equipment imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azerbaijan Renewable Energy Market |
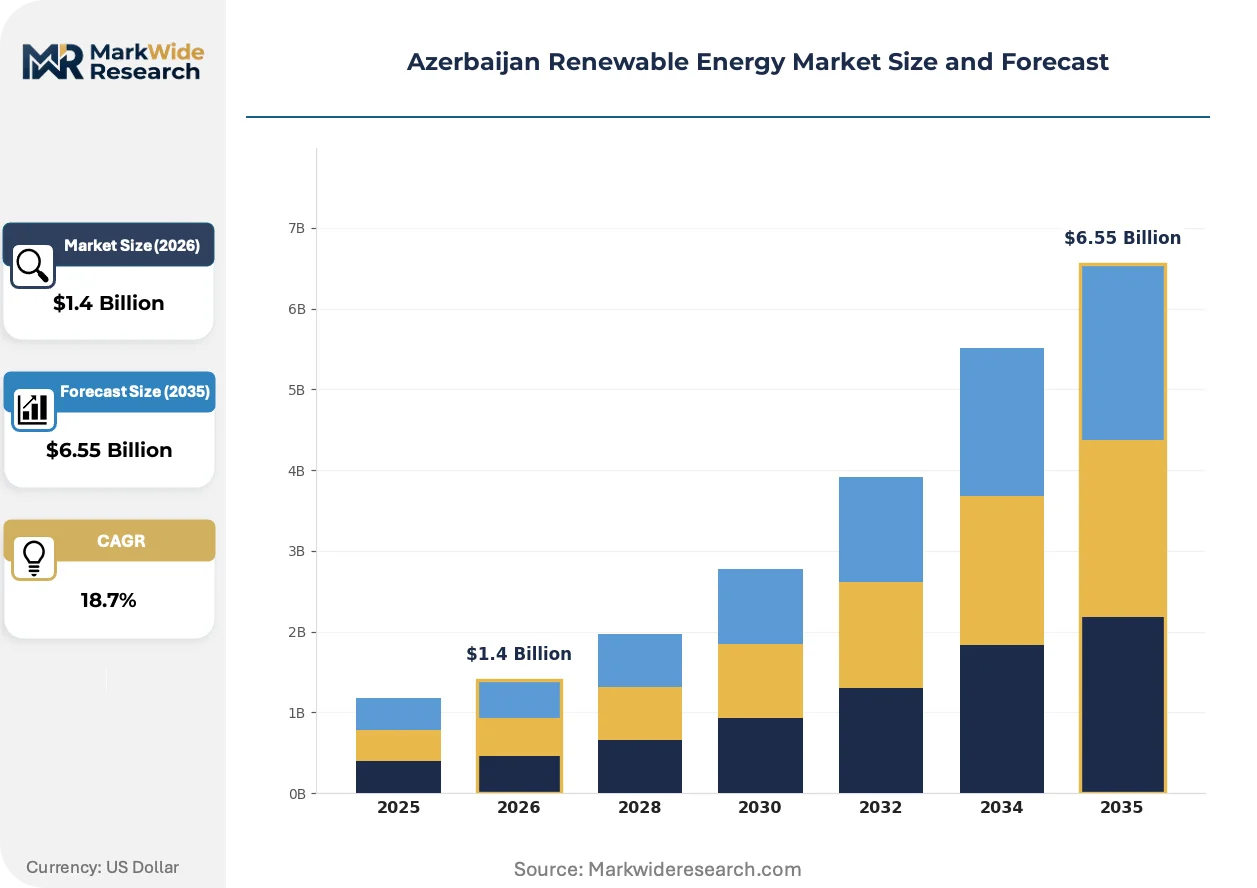
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Power, Wind Turbines, Hydropower, Biomass Application: Electricity Generation, Heating Systems, Off-Grid Solutions, Hybrid Systems End User: Residential, Commercial, Industrial, Government Installation Type: Ground-Mounted, Rooftop, Floating, Integrated |
| Companies Covered | Azerenerji JSC, ACWA Power International, Abu Dhabi Future Energy Company PJSC (Masdar), SOCAR Green, Azalternativenerji, Tamiz Shahar JSC, OCA Global Investments SL, BP Azerbaijan, Helind LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azerbaijan Renewable Energy Market Strategic Shifts
Technology convergence and procurement model evolution are compressing development cycles while expanding buyer choice across Azerbaijan's renewable landscape. Regulatory refinements are reshaping competitive positioning for integrated developers.
Bifacial solar modules with tracking systems are expanding into utility-scale deployments across the Absheron Peninsula and Nakhchivan Autonomous Republic. Aluminum smelters and petrochemical operators are adopting these configurations under 15-20 year power purchase agreements. The technology is expanding into merchant revenue positions previously uneconomical for fixed-tilt installations.
The Ministry of Energy's auction mechanism revisions are tightening domestic content thresholds and grid code compliance timelines. Developers must now pre-qualify equipment through State Agency on Alternative and Renewable Energy Sources certification protocols before bid submission. Large-scale independent power projects face compressed execution schedules that favor integrated developers with in-house engineering capabilities.
Industrial offtakers are consolidating procurement through direct bilateral negotiations rather than centralized tender participation. Aluminum smelters in priority zones are bypassing traditional utility intermediaries to secure dedicated renewable supply. This pattern concentrates in the Absheron Peninsula where load density justifies transmission infrastructure co-investment.
Azerbaijan Renewable Energy Market Segmentation
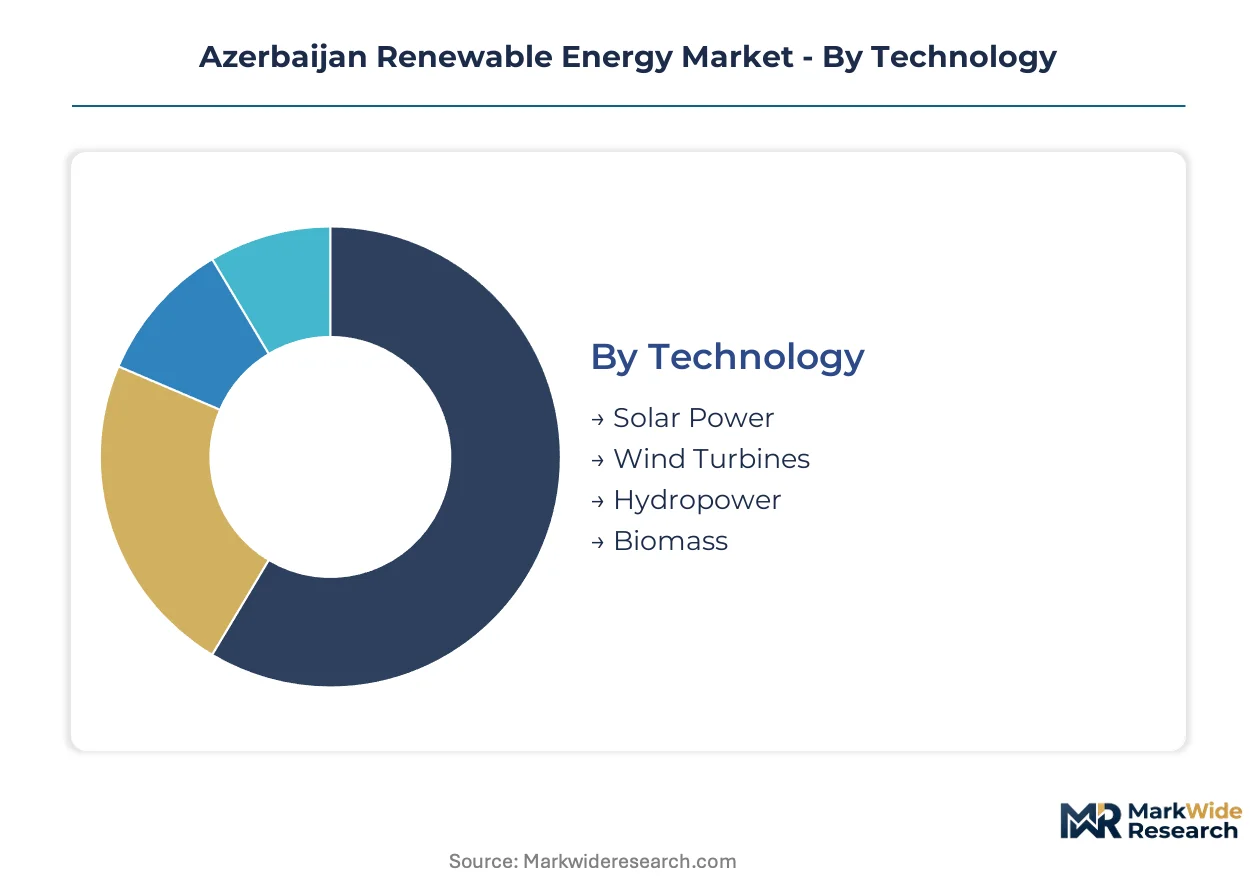
Segmentation reveals how Azerbaijan's renewable deployment stratifies across technology maturity, offtaker risk profiles, and infrastructure requirements. Each dimension shapes capital allocation, regulatory exposure, and project finance structures differently across the Absheron Peninsula and Nakhchivan Autonomous Republic.
Technology:
Standalone generation assets dominate utility-scale procurement, while embedded hybrid configurations are penetrating industrial microgrids and rural electrification channels.
- Solar Power:Photovoltaic modules with bifacial tracking systems capture 2,200-2,800 annual sunshine hours across Azerbaijan's continental climate zones. Demand concentrates in the Absheron Peninsula where aluminum smelters execute 15-20 year power purchase agreements anchoring project finance.
- Wind Turbines:Onshore turbines exploit Caspian Sea corridors exceeding seven meters per second at 50-meter hub heights. Coastal and mountainous terrain in priority zones justifies extended development timelines for higher-margin installations serving petrochemical offtakers.
- Hydropower:Small-to-large dispatchable assets retain structural importance as balancing resources amid rising variable generation penetration from solar and wind.
- Biomass:Agricultural residue conversion systems operate in distributed rural electrification partnerships bypassing centralized procurement bottlenecks.
Volume placements concentrate in Solar Power; the faster expansion belongs to Wind Turbines.
Application:
Grid-connected baseload supply commands the majority of capital deployment, though islanded and flexible configurations are capturing incremental share in isolated zones.
- Electricity Generation:Utility-scale solar and wind farms feed national grid expansion under Ministry of Energy auction mechanisms. The Absheron Peninsula's load density justifies transmission infrastructure co-investment with aluminum smelting and petrochemical operators.
- Hybrid Systems:Concentrated solar thermal and photovoltaic hybrid designs open dispatchable renewable positions previously reserved for conventional thermal generation. Nakhchivan Autonomous Republic's isolated grid conditions create favorable economics for these configurations.
- Heating Systems:Solar thermal collectors and biomass boilers serve residential and commercial thermal loads in rural districts with limited gas distribution.
- Off-Grid Solutions:Modular solar-plus-storage configurations address electrification gaps in agricultural cooperatives outside centralized utility coverage.
Capital deployment clusters in Electricity Generation; Hybrid Systems are climbing the fastest as balancing premiums escalate.
End User:
Energy-intensive industrial offtakers anchor utility-scale procurement, while fragmented residential and commercial demand drives distributed generation growth.
- Industrial:Aluminum smelters and petrochemical operators in the Absheron Peninsula consolidate procurement through direct bilateral negotiations bypassing traditional utility intermediaries. These offtakers execute power purchase agreements that de-risk project finance for large-scale independent power projects.
- Government:Ministry of Energy auction mechanisms and presidential decree frameworks mandate renewable capacity additions that lock in long-term demand visibility for developers serving public infrastructure.
- Commercial:Retail and logistics operators adopt rooftop solar under feed-in tariff frameworks with grid connection priority rules.
- Residential:Distributed solar penetration remains limited by financing access and interconnection queue management constraints enforced by the State Agency on Alternative and Renewable Energy Sources.
Contract volume concentrates in Industrial offtakers; Government procurement is gaining share fastest through auction mechanism expansion.
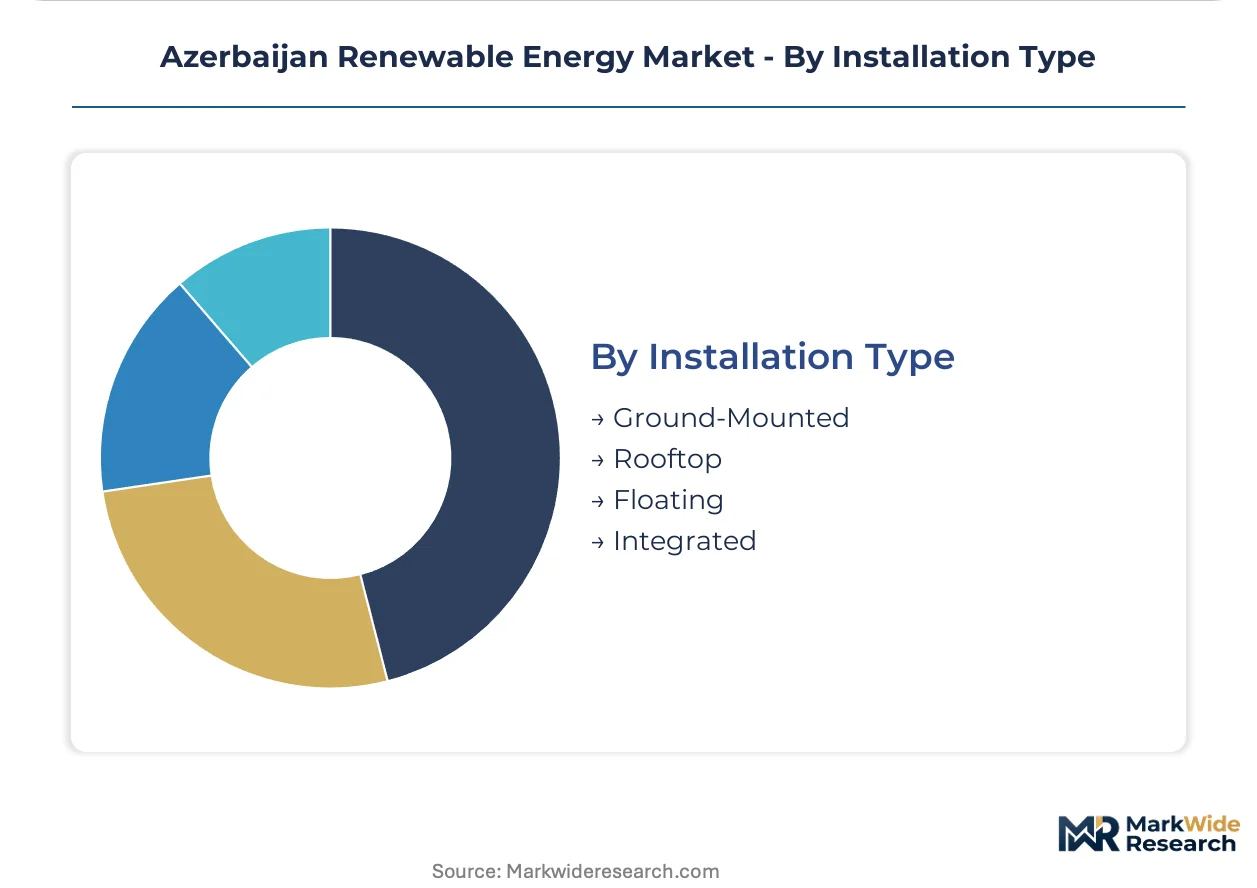
Installation Type:
Ground-mounted utility-scale arrays absorb the majority of module supply, though rooftop and integrated configurations are penetrating constrained sites and urban load centers.
- Ground-Mounted:Utility-scale solar and wind arrays occupy high-irradiance zones across the Absheron Peninsula and Nakhchivan Autonomous Republic. These installations connect to legacy grid infrastructure operated by Azerenerji JSC requiring substantial balancing investment.
- Rooftop:Commercial and industrial building-integrated systems bypass land acquisition constraints in dense urban corridors. Feed-in tariff revisions accelerate approval timelines for these distributed assets.
- Floating:Photovoltaic arrays on water bodies exploit evaporative cooling effects and reduced land-use conflicts in priority zones with suitable hydrographic conditions.
- Integrated:Building-integrated photovoltaics and agrivoltaic configurations merge generation with structural or agricultural functions in land-constrained deployments.
Project pipelines concentrate in Ground-Mounted installations; Rooftop deployment shows the steepest expansion trajectory as urban land constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Azerbaijan's renewable generation capacity concentrates in zones where industrial load density meets superior resource quality. The Absheron Peninsula consumes the majority of clean electricity output while Nakhchivan operates as an isolated laboratory for storage-integrated systems.
Absheron Peninsula
Aluminum smelters and petrochemical complexes anchor demand for utility-scale solar and wind installations across this coastal corridor. The Ministry of Energy's auction mechanisms prioritize grid connection for projects serving these energy-intensive offtakers. Baku's industrial suburbs host bifacial tracking arrays under 15-20 year power purchase agreements that de-risk project finance for independent power producers.
Nakhchivan Autonomous Republic
Isolated grid conditions and 2,800 annual sunshine hours create favorable economics for modular solar-plus-storage configurations. The State Agency on Alternative and Renewable Energy Sources enforces streamlined certification protocols for equipment destined to this exclave. Sharur and Babak districts host concentrated solar thermal and photovoltaic hybrid designs that supply dispatchable renewable power without mainland grid dependency.
Shirvan Plain
Caspian Sea wind corridors exceeding seven meters per second at 50-meter hub heights justify extended development timelines for coastal turbine installations. Feed-in tariff revisions accelerate approval cycles for projects feeding the national transmission backbone. Ali Bayramli and Salyan municipalities cluster higher-margin wind assets serving petrochemical operators with 24-hour baseload requirements.
Ganja-Qazakh Economic Region
Agricultural residue availability supports distributed biomass conversion systems bypassing centralized procurement bottlenecks. Rural electrification partnerships with farming cooperatives deploy small-scale photovoltaic arrays under simplified interconnection rules. Ganja city anchors commercial rooftop solar adoption among logistics operators seeking feed-in tariff revenue streams.
Small-to-large hydropower assets retain structural importance as balancing resources amid rising variable generation penetration from solar and wind installations.
Sheki-Zagatala
Mountainous terrain channels seasonal runoff through existing hydropower infrastructure operated by Azerenerji JSC. Grid operators here manage ramp events from upstream variable generation using real-time meteorological data integration pilots. Zagatala's transmission substations coordinate balancing investment across legacy thermal and emerging renewable assets.
Azerbaijan Renewable Energy Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists for utility-scale procurement contracts across Azerbaijan's priority zones. The market structure concentrates around integrated developers with in-house engineering capabilities and state-affiliated incumbents controlling legacy infrastructure. Three archetypes dominate: Gulf-based independent power producers with capital deployment scale, domestic grid operators navigating thermal-to-renewable transition, and specialized renewable developers targeting industrial offtakers. Competitive intensity centers on auction pre-qualification speed and bilateral negotiation leverage with aluminum smelting and petrochemical buyers.
Among Gulf-based developers, ACWA Power International and Abu Dhabi Future Energy Company PJSC (Masdar) represent the integrated development model that anchors large-scale independent power projects. Azerenerji JSC exemplifies the incumbent grid operator archetype, dominating legacy infrastructure while managing variable renewable integration. These three companies occupy positions that reflect the market's bifurcation between greenfield development specialists and state-affiliated transmission asset holders.
| Leading Market Players |
|---|
| Azerenerji JSC |
| ACWA Power International |
| Abu Dhabi Future Energy Company PJSC (Masdar) |
| SOCAR Green |
| Azalternativenerji |
| Tamiz Shahar JSC |
| OCA Global Investments SL |
| BP Azerbaijan |
| Helind LLC |
| Others |
Value Chain & Pricing Dynamics
Industrial offtakers in aluminum smelting and petrochemicals concentrate procurement leverage, anchoring long-term power purchase agreements that compress developer margins through fixed-tariff structures. This buyer concentration feeds into supply chain decisions favoring integrated developers with captive engineering capabilities over fragmented equipment vendors.
Pricing Analysis
Margin tightening in utility-scale solar reflects module price volatility and compressed construction timelines under Ministry of Energy auction schedules. Three-tier pricing structure across premium bifacial tracking, standard fixed-tilt, and economy rooftop configurations differentiates projects by irradiance zone and offtaker credit quality. Cost-down pressure on fixed-tariff portfolios accelerates as aluminum smelters demand 15-20 year contract tenors. Government auction participants show lowest price sensitivity; merchant revenue developers face highest.
Supply Chain Analysis
Photovoltaic module supply rests on Chinese crystalline silicon producers, South Korean inverter manufacturers, and European tracking system specialists. Polysilicon, glass, and rare earth magnet dependencies create exposure to commodity price swings and logistics chokepoints at Caspian Sea ports. Single-source vulnerability concentrates in high-efficiency cell imports. Distribution runs through EPC contractors with pre-qualified State Agency on Alternative and Renewable Energy Sources certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
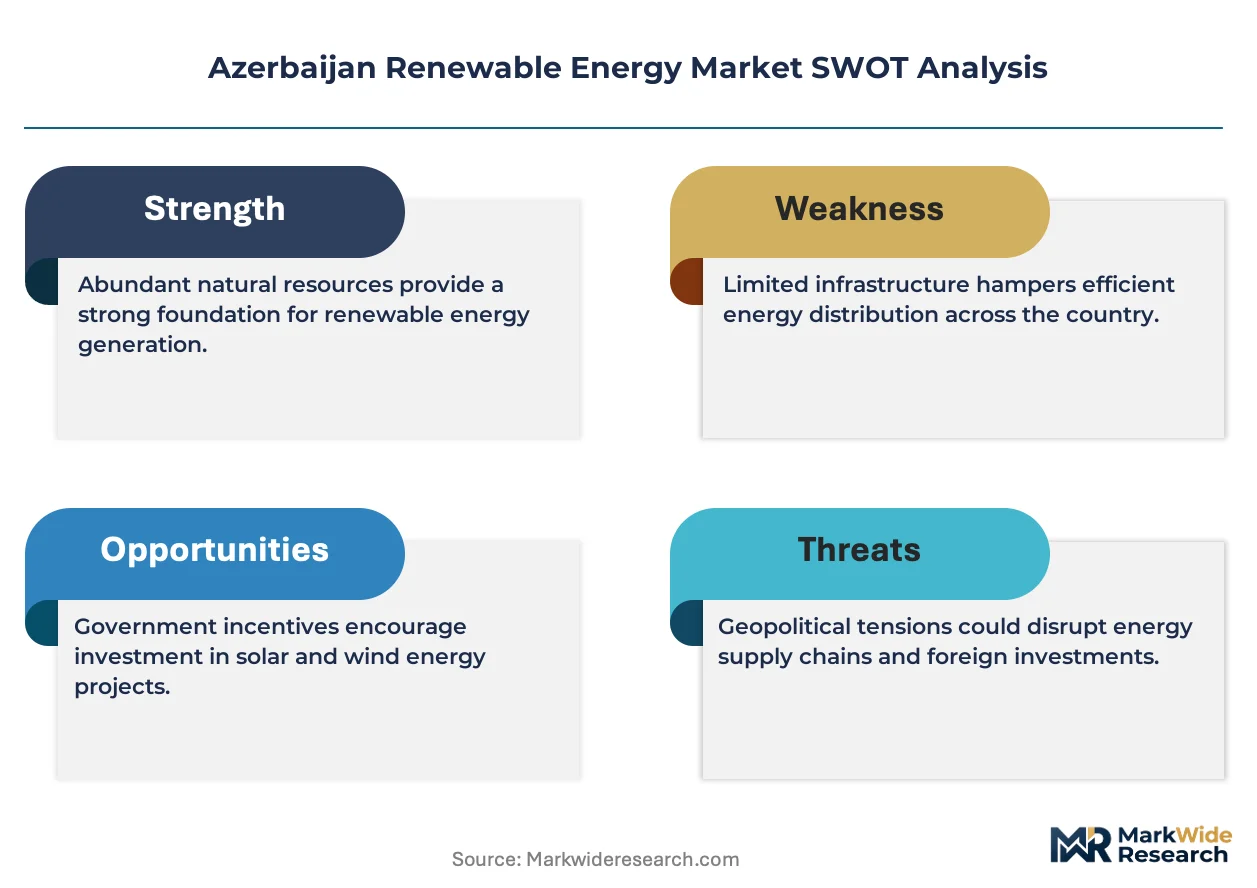
Azerbaijan's renewable market operates as a cost-of-compliance story where State Agency on Alternative and Renewable Energy Sources equipment certification creates barrier-to-entry moats favoring pre-qualified developers with established import protocols.
For Market Incumbents: To counter emerging Gulf-based independent power producers with integrated development models, Azerenerji JSC should accelerate backward integration into grid-scale battery storage manufacturing partnerships and secure exclusive interconnection rights in high-irradiance zones through co-investment with industrial offtakers.
For New Entrants and Emerging Players: Begin with modular solar-plus-storage configurations targeting Nakhchivan Autonomous Republic agricultural cooperatives outside centralized utility coverage, leveraging streamlined certification protocols and simplified interconnection rules as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors integrated developers with in-house EPC capabilities and pre-qualified equipment portfolios. Long-term viability hinges on auction mechanism execution speed. Watch Ministry of Energy domestic content threshold revisions as the critical inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Consolidation | Aluminum smelters in Absheron Peninsula anchor project finance through 15-20 year offtake commitments. |
| Backward Integration into Storage | Grid operators secure balancing capabilities amid rising solar and wind penetration from variable generation assets. |
| Technology Licensing Partnership | Concentrated solar thermal hybrid designs open dispatchable renewable positions in Nakhchivan's isolated grid. |
| Green Certification Program | State Agency on Alternative and Renewable Energy Sources protocols create compliant supplier moats in equipment procurement. |
| Capacity Buildout in Priority Zones | High-irradiance Absheron and Nakhchivan regions concentrate deployment under presidential decree clean energy mandates. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving utility planning officers, independent power project developers, EPC contractors, and grid operators. Ministry of Energy auction documentation, State Agency on Alternative and Renewable Energy Sources certification protocols, and Azerenerji JSC transmission tariff structures supplied bottom-up validation, while IEA regional energy outlooks and EIA country analyses provided top-down triangulation.
Segment-level modeling addressed technology, application, end user, and installation type dimensions across the projection horizon, with technology splits further disaggregated by bifacial versus monofacial module configurations and tracking versus fixed-tilt mounting systems. CAGRs derived from installed capacity buildout trajectories, auction award timelines, and industrial offtaker contract execution patterns. Forecast inputs incorporated presidential decree target compliance schedules and feed-in tariff revision calendars.
Underlying measurement precision varies by segment; utility-scale solar and wind carry tighter precision than distributed biomass and rural electrification channels. Forecasts reflect assumptions on auction mechanism stability, grid integration investment pacing, and module supply chain normalization. Regulatory decree amendments, interconnection queue bottlenecks, and domestic content rule evolution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
North America Solar Tracker Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Solar Tree Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Tidal Energy Generation Systems Market