
 France Renewable Energy Market | 2026-2036
France Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
France Renewable Energy Market Analysis
France's utility-scale solar pipeline is expanding across the country's southern corridor. Neoen leverages its early-mover position in large-scale photovoltaic parks to sustain project development momentum. Boralex anchors its competitive stance through specialized onshore wind expertise in Brittany and Normandy. TotalEnergies extends its integrated energy model to control downstream offtake channels for renewable power.
France renewable energy encompasses electricity and heat derived from solar irradiance, wind kinetic energy, hydrological flow, and organic biomass conversion, primarily through photovoltaic cells with silicon-based semiconductor junctions rated between 400–700 W per module, turbine rotor diameters spanning 90–160 meters for onshore installations, and anaerobic digestion systems processing agricultural residues at 35–55°C. Solar photovoltaic deployment leads installed capacity additions due to declining module costs and streamlined administrative authorization procedures under France's simplified environmental assessment framework. Offshore wind represents the fastest-growing technology segment as floating foundation pilots advance in the Mediterranean and Atlantic lease zones. Industrial end users constitute the most concentrated margin pool, with energy-intensive manufacturers securing long-term power purchase agreements to hedge against volatile wholesale electricity prices.
France's renewable energy sector operates under the EU Green Deal emission reduction targets, the French Energy Regulatory Commission's (CRE) tariff and auction mechanisms, and the Multi-Annual Energy Programming (PPE) law mandating specific capacity trajectories for each technology. CRE's biennial tariff reviews shape investor returns by adjusting feed-in premiums for solar and wind based on technology cost curves and grid integration constraints. Stakeholders must monitor forthcoming offshore wind tender rounds and evolving grid connection queue priorities as France accelerates toward its electrification and hydrogen production objectives.
Market Dynamics
France's renewable energy market is restructuring around grid interconnection bottlenecks and the CRE's evolving auction mechanisms, which are compressing developer margins while accelerating project consolidation among capital-heavy utilities.
Growth Catalysts
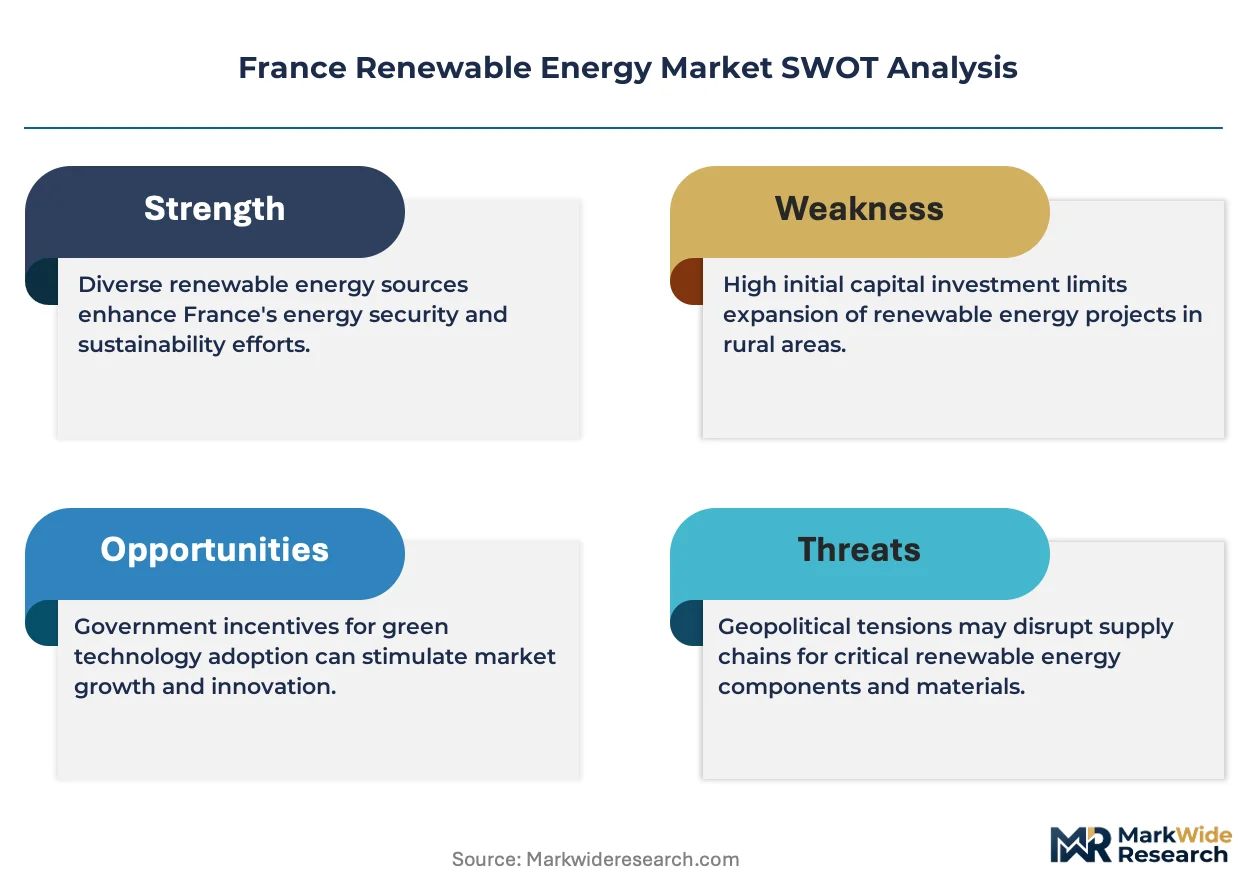
- EU Green Deal emission mandates:Binding carbon reduction targets force industrial energy consumers toward renewable power purchase agreements, creating guaranteed offtake demand for new solar and wind capacity.
- Occitanie solar irradiance concentration:Southern France's superior photovoltaic yield attracts utility-scale developers seeking optimal capacity factors for merchant and contracted projects alike.
- French hydrogen strategy capital flows:National funding mechanisms for electrolyzer deployment stimulate co-located renewable generation to supply carbon-free hydrogen production facilities.
Market Restraints
- Grid connection queue congestion:RTE's interconnection backlog extends project commissioning timelines, trapping capital in development-phase assets and inflating weighted average cost of capital for independent power producers.
- Offshore wind foundation cost volatility:Steel and specialized marine engineering inputs face supply constraints from North Sea and Baltic fabrication yards, pressuring project economics in Atlantic and Mediterranean lease zones.
- Administrative authorization delays:Prefectural permitting procedures under France's environmental code create procedural friction, particularly for onshore wind in protected rural and coastal zones.
Strategic Opportunities
- Hauts-de-France wind corridor underpenetration:Northern France's onshore wind resource remains below installed capacity potential relative to Brittany and Normandy, offering first-mover positioning for turbine supply chain localization.
- Floating offshore foundation pilots:Mediterranean deep-water lease zones enable technology convergence between semi-submersible platforms and high-capacity factor turbines inaccessible to fixed-bottom designs.
- Industrial self-consumption regulatory tailwind:Simplified authorization thresholds for behind-the-meter solar installations allow energy-intensive manufacturers to bypass wholesale market exposure through captive generation.
Industry Challenges
- Electrical grid engineering talent scarcity:Specialized power systems integration expertise for inverter-based renewable resources lags behind deployment velocity, delaying commissioning and increasing EPC contractor pricing power.
- Hybrid storage system certification complexity:Co-located battery and renewable assets face evolving fire safety and grid code compliance timelines from ANSM and CRE, extending project development cycles.
- Legacy nuclear baseload displacement coordination:EDF's reactor fleet scheduling and grid stability requirements create operational friction for variable renewable integration, demanding enhanced forecasting and demand response capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Renewable Energy Market |
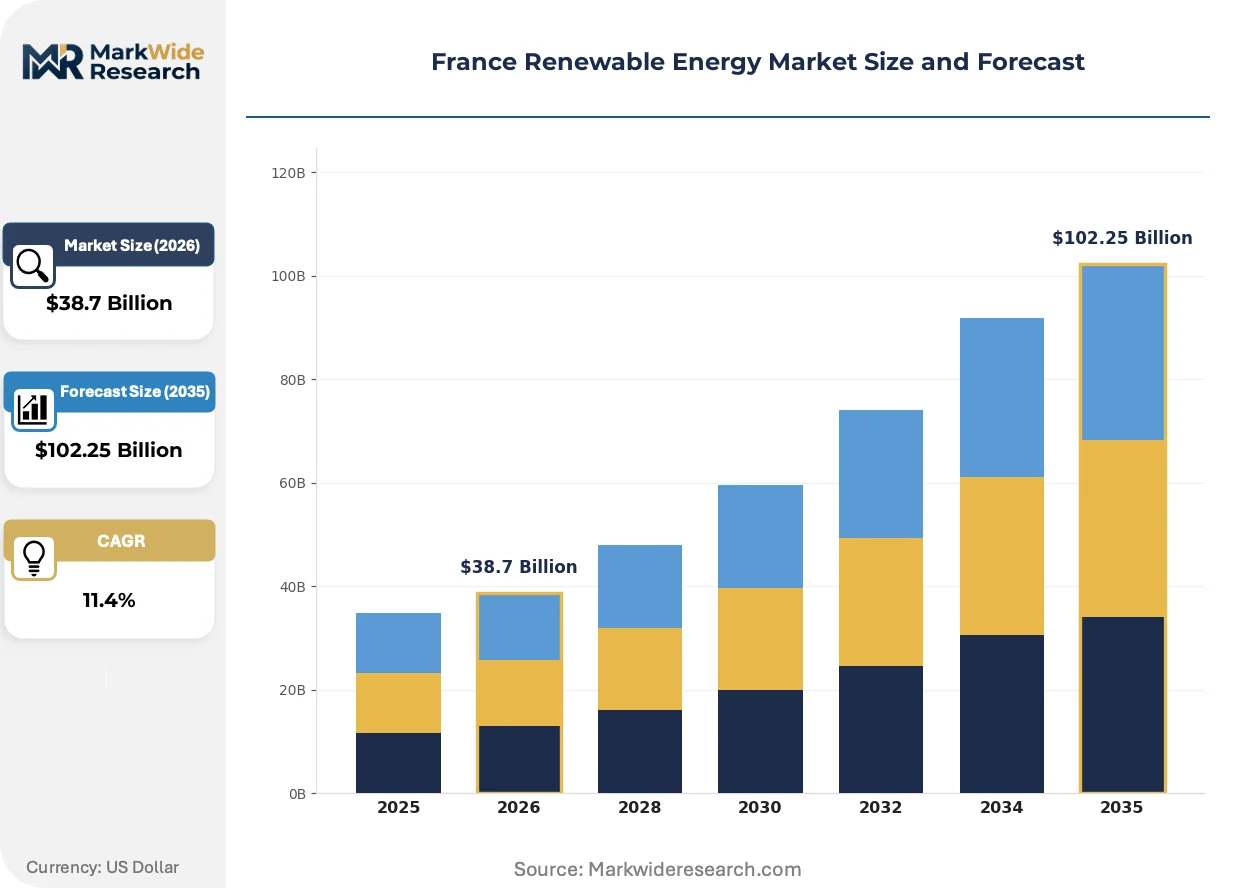
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Hydro, Biomass Technology: Photovoltaic, Offshore Wind, Geothermal, Fuel Cells Application: Power Generation, Heating, Transportation, Industrial End User: Residential, Commercial, Industries, Utilities |
| Companies Covered | Neoen, Boralex, TotalEnergies, SOLVEO Energies, Groupe VALOREM, EDF Renewables, Voltalia, Charwood Energy Group, Engie Green, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Renewable Energy Market Emerging Trajectories
Technology trajectories in French renewables are converging on higher-capacity-factor assets and digitalized grid integration, with policy mechanisms and industrial procurement patterns accelerating capital reallocation toward these configurations.
High-efficiency bifacial photovoltaic modules with tracking systems are absorbing premium project development attention in France's southern corridor. Utility-scale developers in Occitanie and Provence-Alpes-Côte d'Azur are deploying these configurations to maximize yield per hectare under land-use constraints. The technology is absorbing interconnection capacity allocation priority as CRE's auction scoring favors higher capacity factor submissions.
France's implementation of the EU Green Deal through revised Multi-Annual Energy Programming mandates is tightening technology-specific capacity installation timelines. The regulatory consequence compresses development-phase risk windows and elevates penalties for non-delivery in offshore wind tender rounds. Floating foundation projects in Mediterranean lease zones face the most acute compliance pressure, with developers accelerating engineering validation to meet commissioning deadlines.
Energy-intensive manufacturers are consolidating procurement through direct bilateral power purchase agreements rather than regulated tariff mechanisms. This buyer behavior shift displaces traditional utility intermediation for aluminum, chemical, and data center loads in northern and eastern industrial zones. The pattern is most visible in Dunkirk and Fos-sur-Mer, where hydrogen production and metallurgy facilities anchor long-term renewable offtake commitments.
France Renewable Energy Market Segmentation
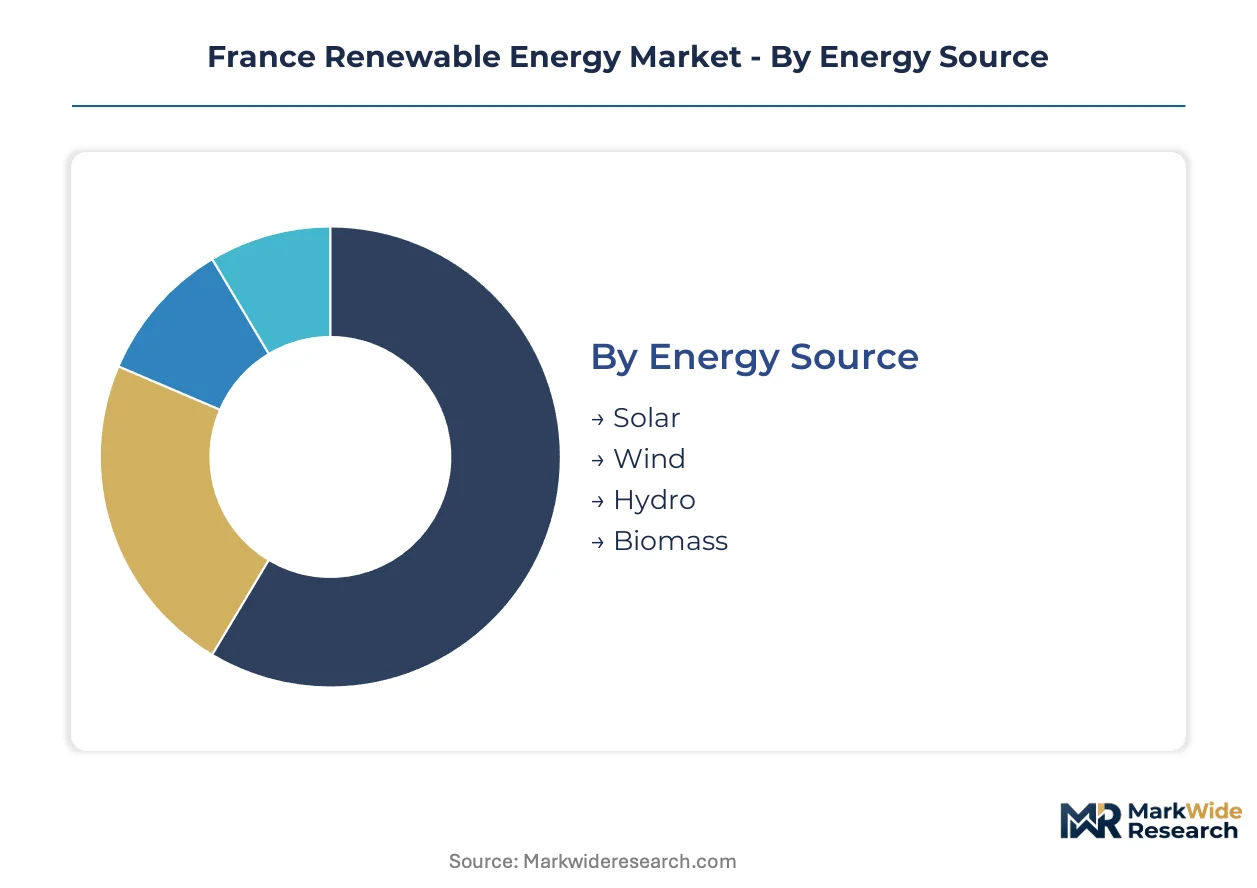
Segmentation in France's renewable energy market reveals how regulatory frameworks and grid integration requirements shape capital allocation across technology classes. Each dimension carries distinct permitting burdens and revenue structures that determine developer positioning.
Energy Source:
Solar and wind installations require CRE tariff authorization or competitive auction qualification, while hydro and biomass face additional environmental impact assessments under France's environmental code.
- Solar:Photovoltaic systems utilizing silicon-based modules rated 400–700 W capture premium development attention in Occitanie's high-irradiance zones. Utility-scale parks in southern France concentrate procurement volume as simplified administrative procedures compress development timelines.
- Wind:Onshore turbines with 90–160 meter rotor diameters dominate Brittany and Normandy installations, while floating offshore pilots advance in Mediterranean lease zones. Foundation engineering constraints and marine coordination requirements inflate capital intensity relative to terrestrial alternatives.
- Hydro:Run-of-river and small-scale installations leverage existing waterway infrastructure. Regulatory approval from regional environmental authorities creates procedural friction distinct from CRE-managed solar and wind pathways.
- Biomass:Anaerobic digestion systems processing agricultural residues at 35–55°C supply decentralized heat and power. Feedstock supply contracts and agricultural waste sourcing agreements determine project bankability.
Leading the category by volume: Solar. Growing fastest: Offshore wind.
Technology:
Cost tier differentiation separates mature commercial technologies from pilot-phase systems requiring demonstration-scale validation.
- Photovoltaic:Bifacial modules with tracking systems maximize yield per hectare under southern France's land-use constraints. CRE auction scoring favors higher capacity factor submissions, directing interconnection priority toward these configurations.
- Offshore Wind:Fixed-bottom foundations dominate Atlantic lease zones while floating semi-submersible platforms enable Mediterranean deep-water deployment. Steel supply constraints from North Sea fabrication yards pressure project economics.
- Geothermal:Deep drilling operations target heat reservoirs for district heating networks. Exploration risk and subsurface uncertainty limit deployment relative to solar and wind alternatives.
- Fuel Cells:Hydrogen conversion systems co-locate with electrolyzer facilities under France's national hydrogen strategy. Electrolyzer offtake agreements and carbon-free production mandates anchor demand.
Highest capital deployment: Photovoltaic. Steepest expansion trajectory: Offshore wind.
Application:
Application segmentation tracks how end-use requirements dictate technology selection and grid connection specifications.
- Power Generation:Grid-scale solar and wind farms supply wholesale electricity markets and bilateral corporate power purchase agreements. RTE interconnection queue priority determines project sequencing.
- Heating:Biomass boilers and geothermal networks serve district heating infrastructure in dense urban zones. Seasonal demand patterns and thermal storage requirements shape system design.
- Transportation:Electrolyzer-produced hydrogen targets heavy-duty and maritime fuel substitution. France's hydrogen strategy funding mechanisms stimulate co-located renewable generation.
- Industrial:Energy-intensive manufacturers deploy behind-the-meter solar and secure long-term renewable offtake to hedge wholesale price volatility. Dunkirk and Fos-sur-Mer metallurgy facilities anchor procurement concentration.
Dominant revenue pool: Power generation. Gaining share fastest: Industrial self-consumption.
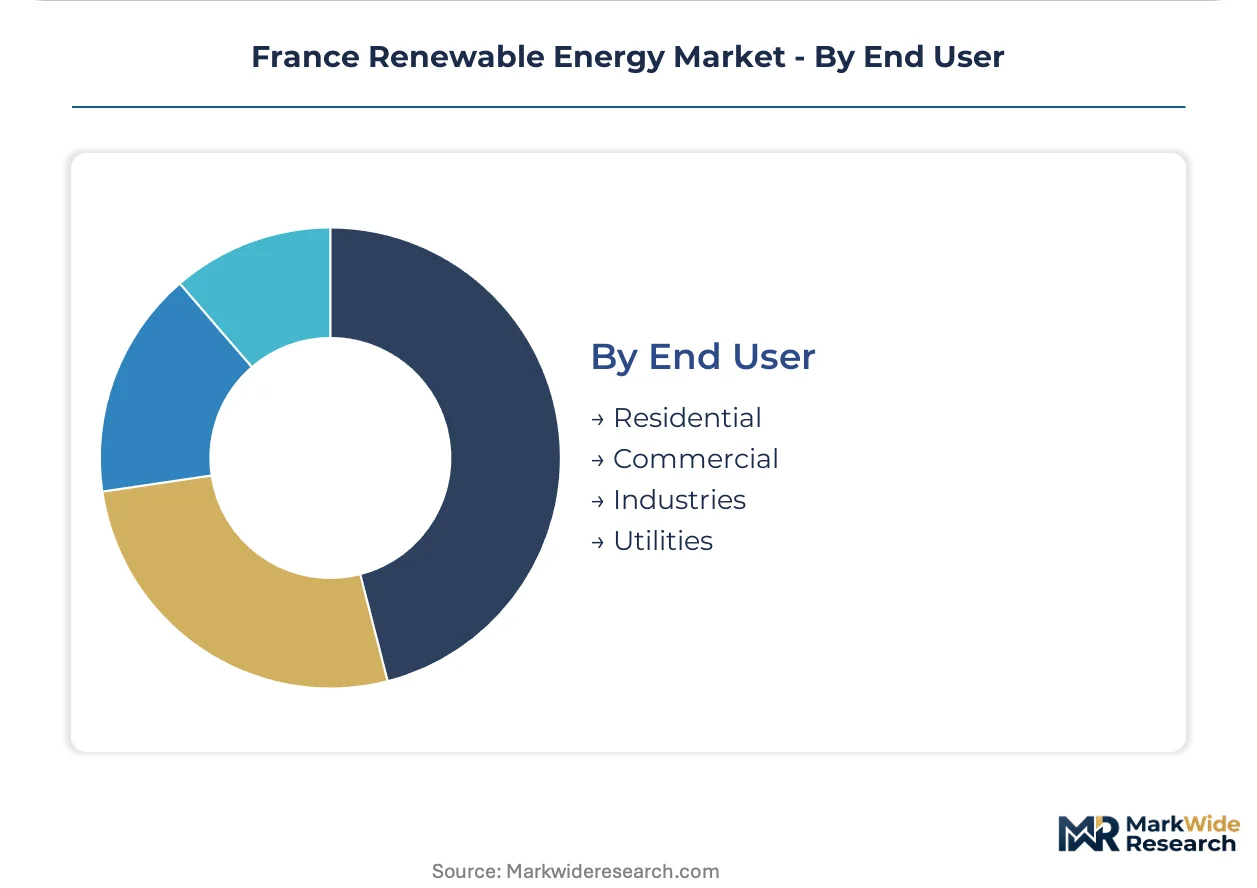
End User:
Customer type determines procurement channel access, with utilities holding grid-scale auction eligibility while residential and commercial segments navigate regulated tariff mechanisms.
- Residential:Rooftop photovoltaic systems benefit from simplified authorization thresholds for installations below capacity thresholds. Self-consumption with surplus injection dominates deployment economics.
- Commercial:Mid-scale solar installations serve retail, logistics, and office loads. Behind-the-meter configurations bypass wholesale market exposure through captive generation.
- Industries:Aluminum, chemical, and data center operators consolidate procurement through direct bilateral power purchase agreements. Long-term price hedging motivates renewable sourcing over regulated tariffs.
- Utilities:EDF and independent power producers compete in CRE auction rounds for grid-scale solar and wind capacity. Grid connection queue management and development-phase capital deployment determine competitive positioning.
Largest capacity absorption: Utilities. Expanding most quickly: Industrial direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern France's solar irradiance concentration anchors renewable development geography. The country's administrative regions distribute capacity across distinct resource profiles and industrial demand centers.
Occitanie
Occitanie's photovoltaic yield attracts utility-scale developers seeking optimal capacity factors. The CRE's simplified environmental assessment framework compresses development timelines for projects in this zone. Montpellier and Toulouse anchor solar park clusters where bifacial tracking systems maximize land-use efficiency.
Hauts-de-France
Onshore wind resource in northern France remains underpenetrated relative to western coastal regions. The French Energy Regulatory Commission's tariff mechanisms incentivize turbine deployment across the wind corridor. Dunkirk metallurgy facilities anchor industrial offtake demand for renewable power purchase agreements.
Brittany
Maritime wind exposure sustains established onshore turbine installations across coastal zones. Prefectural permitting under France's environmental code creates procedural friction for expansion in protected rural areas. Rennes and Brest harbor specialized engineering expertise for foundation and grid integration services.
Provence-Alpes-Côte d'Azur
Mediterranean deep-water lease zones enable floating offshore foundation pilots inaccessible to fixed-bottom designs. The EU Green Deal implementation tightens technology-specific capacity installation timelines for these demonstration projects. Marseille anchors marine coordination infrastructure for Atlantic and Mediterranean lease zone development.
Normandy
Established onshore wind expertise concentrates in western agricultural zones with favorable turbine siting conditions. Grid connection queue congestion from RTE's interconnection backlog extends project commissioning timelines across the region. Caen and Le Havre support component logistics for rotor assembly and marine transport operations.
France Renewable Energy Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized technology niches and regional permitting expertise. The market structures around capital-heavy utilities with grid-scale auction eligibility and mid-cap developers with localized land-access relationships. Strategic archetypes include integrated energy conglomerates controlling downstream offtake, independent power producers with pure-play renewable portfolios, and industrial self-consumption specialists. Dominant competitive moves encompass project portfolio consolidation through acquisition and co-development partnerships for grid interconnection queue positioning.
Within the integrated energy tier, TotalEnergies exemplifies downstream channel control through bilateral corporate power purchase agreements. Neoen and Boralex occupy positions as pure-play developers with differentiated geographic specializations—Neoen leveraging utility-scale photovoltaic expertise across southern France, Boralex anchoring onshore wind development in Brittany and Normandy. These three entities represent distinct capital deployment archetypes competing for CRE auction qualification and interconnection priority.
| Leading Market Players |
|---|
| Neoen |
| Boralex |
| TotalEnergies |
| SOLVEO Energies |
| Groupe VALOREM |
| EDF Renewables |
| Voltalia |
| Charwood Energy Group |
| Engie Green |
| Others |
Supply Flow & Price Mechanics
Backward integration into turbine component manufacturing anchors supply position and pricing power for French renewable developers competing in CRE auction rounds. EDF Renewables and TotalEnergies leverage captive production of nacelles and blade assemblies to compress EPC contractor margins while insulating project economics from steel price volatility.
Pricing Analysis
Warranty and O&M service bundling separates premium-tier EPC offerings from unbundled economy alternatives in French utility-scale solar and wind procurement. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in equipment certification grade and after-sales coverage duration. Cost compression in economy-tier photovoltaic modules is intensifying because Chinese manufacturers are flooding European spot markets with excess inventory. Industrial offtakers securing bilateral power purchase agreements exhibit lowest price sensitivity, while residential rooftop installers face acute margin pressure from regulated tariff compression.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polysilicon and wafer suppliers dominating photovoltaic module feedstock. The French renewable supply chain draws from China for solar cells, Vietnam for module assembly, and Germany for specialized inverter electronics. Steel and rare earth magnet dependencies for turbine generators create tariff exposure from EU carbon border adjustment mechanisms. Distribution runs through EPC contractors with established RTE grid connection queue relationships, concentrating downstream channel control among capital-heavy integrated utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's renewable energy market reads as a cost-of-compliance story where EU Green Deal emission mandates and CRE auction qualification requirements erect barrier-to-entry moats for players with established regulatory navigation capabilities.
For Market Incumbents: Extend grid interconnection queue positioning through co-development partnerships with mid-cap land-access specialists in Hauts-de-France and Occitanie. Threat from floating offshore foundation engineering specialists demands captive investment in marine coordination capabilities. Vertical integration into electrolyzer offtake channels anchors hydrogen strategy alignment. For New Entrants and Emerging Players: The premium-economy price-point gap in behind-the-meter industrial solar creates white-space opportunity for standardized self-consumption system packages. Hauts-de-France wind corridor underpenetration offers most penetrable geography relative to saturated Brittany and Normandy markets. Direct sales to energy-intensive manufacturers bypass utility intermediary capture. For Investors and Strategic Acquirers: Exit pathways concentrate in utility-scale portfolio acquisition by integrated energy conglomerates seeking CRE auction eligibility. Long-term viability frames around electrolyzer co-location and green hydrogen offtake contract duration. Signal to watch is floating offshore foundation commissioning timeline compression in Mediterranean lease zones.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Utility-scale solar parks in Occitanie maximize land-use efficiency under CRE simplified authorization. |
| Power Purchase Agreement | Industrial offtakers in Dunkirk and Fos-sur-Mer anchor long-term renewable procurement commitments. |
| Technology Licensing | Floating foundation pilots in Mediterranean deep-water zones enable technology transfer partnerships. |
| Vertical Integration into Storage | Co-located battery assets address ANSM fire safety compliance and CRE grid code requirements. |
| Green Certification Program | EU Green Deal alignment secures preferential auction scoring and tariff premium eligibility. |
Methodological Framework
Multi-period observation of CRE auction outcomes, RTE interconnection queue progression, and electrolyzer project announcements anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA data, IEA renewable energy reports, FERC filings, and project development databases. Bottom-up capacity addition modeling and top-down policy trajectory analysis enabled triangulation across data sources.
Input-output matrix framing structured the analytical framework across the projection horizon, modeling segmentation by fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from technology cost curve trajectories and deployment velocity benchmarks. Forecast inputs incorporated silicon module price indices and steel cost volatility assumptions.
Inputs from CRE auction databases and RTE grid connection registries were available through the study window; gaps in floating offshore foundation pilot performance data introduce uncertainty bands around Mediterranean deployment timelines. Forecasts reflect assumptions about administrative authorization procedure streamlining and EU carbon border adjustment implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Heating Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Solar Thermal Water Heater Market