
 Russian Federation Renewable Energy Market | 2026-2036
Russian Federation Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Russian Federation Renewable Energy Market Analytics
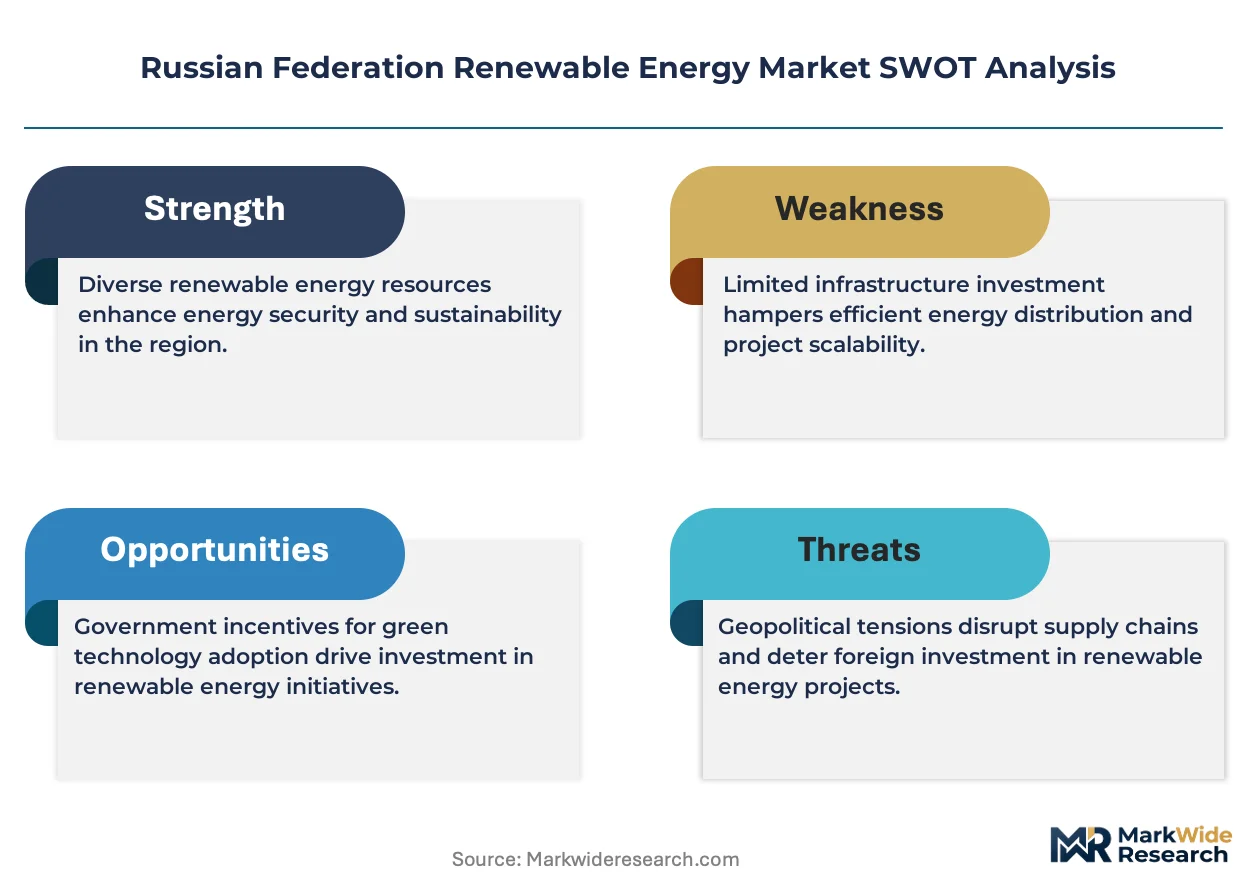
Project finance structures with long-term power purchase agreements is reconfiguring competitive entry barriers for independent producers without legacy generation assets. RusHydro leverages its existing hydroelectric infrastructure to anchor grid balancing services for variable renewable output. Hevel LLC specializes in domestic heterojunction solar module manufacturing, sustaining cost advantages against imported panel suppliers. Fortum Oyj operates selective wind development clusters, positioning its portfolio to capture priority grid connection rights in high-resource zones.
The Russian Federation Renewable Energy sector encompasses power generation systems that convert solar irradiance, wind kinetic energy, biomass combustion, or water flow into grid-deliverable electricity, with utility-scale photovoltaic installations typically exceeding 25 MWac and onshore wind turbines rated between 2.5 MW and 4.5 MW. Solar technology leads capacity additions among new-build renewables, though hydro retains structural dominance in total installed base and annual generation volume. Industrial end users represent the fastest-growing demand segment as energy-intensive manufacturers pursue long-term price hedging through corporate renewable procurement. Utility-scale installation types concentrate capital deployment and margin pools, while distributed systems face interconnection queue constraints that limit near-term scaling.
Russia's Ministry of Energy administers capacity-based competitive selection mechanisms that determine subsidized tariff eligibility, while the Federal Antimonopoly Service oversees grid access pricing and non-discriminatory connection protocols. Technical standards from Rosstandart govern equipment certification requirements that filter market participation. Stakeholders must monitor regulatory adjustments to local content rules and grid code compliance deadlines that will determine project economics and supplier qualification status.
Market Dynamics
The Ministry of Energy's capacity auction mechanism is compressing development timelines as industrial grid operators accelerate procurement of non-thermal baseload alternatives. This regulatory architecture is redistributing capital flows toward utility-scale photovoltaic and onshore wind clusters.
Growth Catalysts
- Industrial Load Defection:Energy-intensive manufacturers in the metallurgical and chemical sectors are executing corporate power purchase agreements to hedge against volatile natural gas tariffs.
- Southern Solar Irradiation Concentration:Astrakhan, Volgograd, and Rostov regions exhibit annual solar insolation exceeding 1,400 kWh/m², enabling capacity factors above 18% for utility-scale photovoltaic installations.
- Local Content Requirements:The Ministry of Industry and Trade mandates minimum domestic value thresholds for module assembly and inverter manufacturing, protecting domestic heterojunction production lines from import competition.
Market Restraints
- Grid Interconnection Queues:Federal Grid Company transmission capacity allocation protocols impose 18-24 month connection delays for distributed systems below 25 MWac.
- Silicon Feedstock Import Dependence:Polysilicon refining capacity concentrates in China and Germany, exposing domestic module assemblers to freight cost volatility and currency fluctuation.
- Natural Gas Price Suppression:Gazprom's regulated domestic tariff structure maintains thermal generation cost advantages below renewable levelized costs in Northwest and Central Federal Districts.
Strategic Opportunities
- Far East Off-Grid Mining:Gold and copper extraction operations in Magadan and Sakha Republic seek diesel displacement through hybrid solar-diesel microgrids.
- Green Hydrogen Pilots:The Ministry of Energy's hydrogen economy roadmap prioritizes electrolyzer deployment at RusHydro's existing hydroelectric sites for ammonia export markets.
- Agrivoltaic Integration:Southern agricultural regions are testing elevated photovoltaic arrays that sustain crop cultivation beneath generation infrastructure.
Industry Challenges
- Grid Balancing Skill Scarcity:System operators lack training in frequency regulation protocols for inverter-based generation, complicating variable renewable integration.
- Rosstandart Certification Backlogs:Equipment type-approval timelines for imported wind turbine components extend 8-12 months, delaying project commissioning.
- Legacy Thermal Asset Stranding:Regional distribution utilities face balance-sheet impairment as coal and gas plants lose dispatch priority to auction-selected renewable capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian Federation Renewable Energy Market |
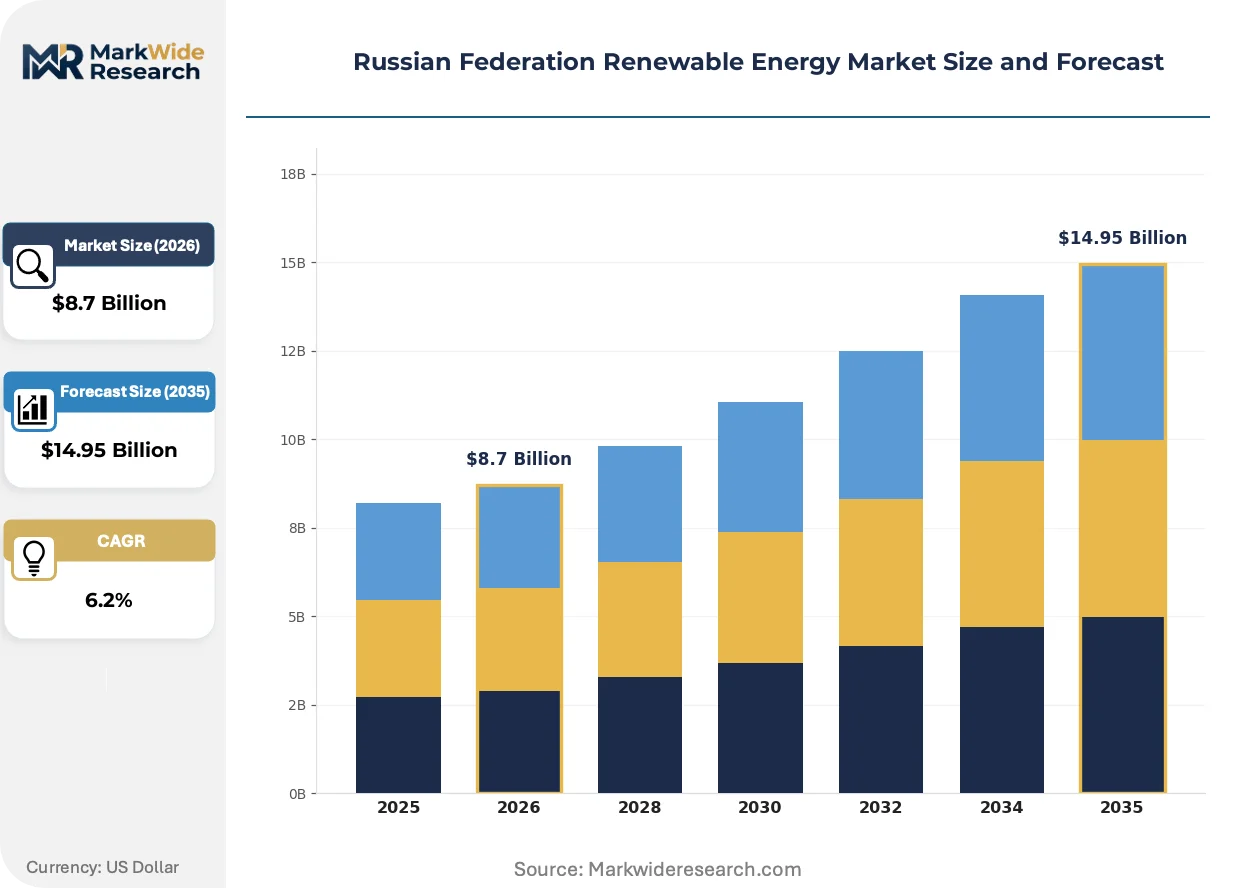
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro Application: Power Generation, Heating, Transportation, Off-Grid End User: Residential, Commercial, Industrial, Public Sector Installation Type: Utility-Scale, Distributed, Hybrid, Remote |
| Companies Covered | RusHydro, Hevel LLC, Fortum Oyj, Rosseti PJSC, Enel SpA, General Electric Co, Unigreen Energy, INTER RAO UES, EuroSibEnergo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian Federation Renewable Energy Market Evolving Landscape
Heterojunction cell architecture and bifacial module designs are compressing levelized cost trajectories for utility-scale developers. These technological advances intersect with regulatory tightening on local content and grid code compliance.
Silicon heterojunction technology is hybridizing photovoltaic module efficiency with temperature coefficient advantages. Industrial offtakers in the aluminum smelting sector are specifying these modules for captive generation facilities. The technology is hybridizing project finance structures by reducing DC/AC ratio requirements and land use intensity.
Rosstandart's updated grid code for distributed generation mandates ride-through capabilities and reactive power provision from inverters above 1 MW. This regulatory revision forces retrofit investments at existing photovoltaic installations commissioned under earlier technical standards. Utility-scale projects in the Southern Federal District face accelerated compliance deadlines relative to other regions.
Corporate renewable procurement is consolidating buyer power among energy-intensive manufacturers. Long-term power purchase agreements are displacing merchant exposure for independent producers. This contractual shift concentrates in the Volga and Ural Federal Districts where industrial load centers cluster near transmission infrastructure.
Russian Federation Renewable Energy Market Segmentation
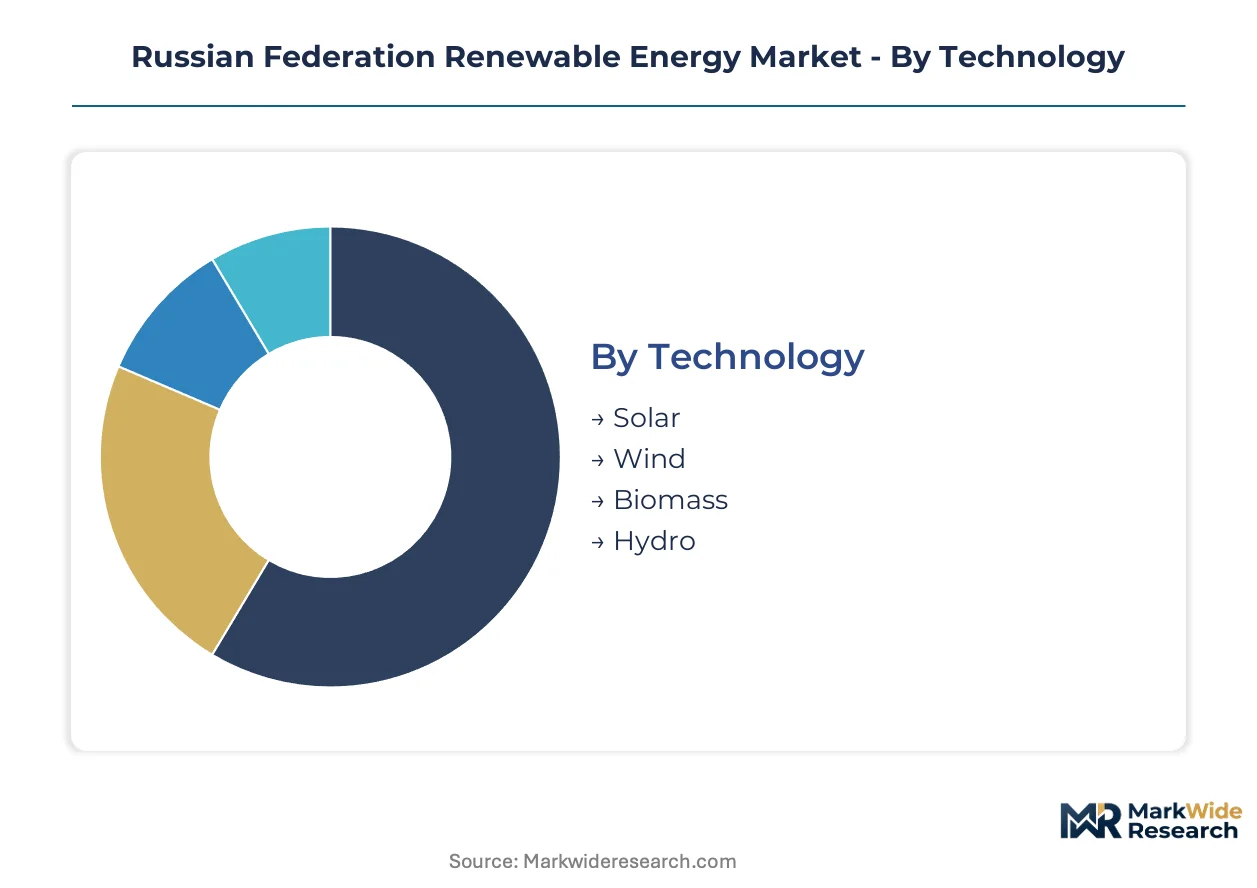
Technology choices in the Russian Federation Renewable Energy Market concentrate capital deployment and determine regulatory compliance pathways. Application diversity shapes tariff structures and interconnection protocols. End user segmentation dictates procurement scale and contract duration preferences.
Technology:
Technology selection governs capacity factor performance and local content qualification thresholds under Ministry of Energy auction rules.
- Solar:Photovoltaic installations leverage heterojunction cell architecture with bifacial module designs capturing rear-side albedo gain. Demand clusters in Astrakhan, Volgograd, and Rostov regions where annual insolation exceeds 1,400 kWh/m², though silicon feedstock import dependence exposes project economics to freight cost volatility.
- Wind:Onshore turbines rated between 2.5 MW and 4.5 MW exploit high-resource zones in coastal and steppe regions. Developers prioritize priority grid connection rights in these clusters, facing Rosstandart certification backlogs of 8-12 months for imported nacelle components.
- Biomass:Combustion systems utilizing agricultural residue and forestry waste supply district heating networks. Facilities concentrate in Central and Northwestern Federal Districts with established feedstock logistics.
- Hydro:Run-of-river and pumped storage infrastructure anchors grid balancing services for variable renewable output. RusHydro's existing asset base dominates installed capacity and annual generation volume.
Hydro holds installed capacity. Solar is rotating up the share rankings.
Application:
Application type determines power delivery infrastructure requirements and offtaker contract structures.
- Power Generation:Grid-deliverable electricity from utility-scale installations feeds wholesale market mechanisms and corporate power purchase agreements. Industrial offtakers in metallurgical and chemical sectors execute these contracts to hedge against volatile natural gas tariffs.
- Heating:Biomass-fueled district heating and solar thermal collectors serve municipal and industrial thermal loads. Systems concentrate in regions with legacy centralized heating infrastructure.
- Transportation:Electrolyzer deployment at RusHydro hydroelectric sites produces hydrogen for ammonia export markets under the Ministry of Energy hydrogen economy roadmap.
- Off-Grid:Hybrid solar-diesel microgrids displace diesel generation at gold and copper extraction operations in Magadan and Sakha Republic.
Power Generation commands revenue concentration. Off-Grid is gaining share fastest.
End User:
End user category shapes project scale, financing structure, and regulatory incentive eligibility.
- Industrial:Energy-intensive manufacturers in aluminum smelting and chemical processing pursue captive generation facilities and long-term price hedging. Procurement concentrates in Volga and Ural Federal Districts near transmission infrastructure.
- Commercial:Retail and office facilities deploy rooftop photovoltaic systems under net metering arrangements. Interconnection queue constraints limit scaling below 25 MWac.
- Residential:Single-family and multi-unit buildings install distributed solar with battery storage. Federal Grid Company protocols impose 18-24 month connection delays.
- Public Sector:Municipal buildings and government facilities procure renewable capacity through centralized tender mechanisms. Local content requirements filter supplier qualification.
Industrial anchors contract volume. Commercial is climbing the fastest.
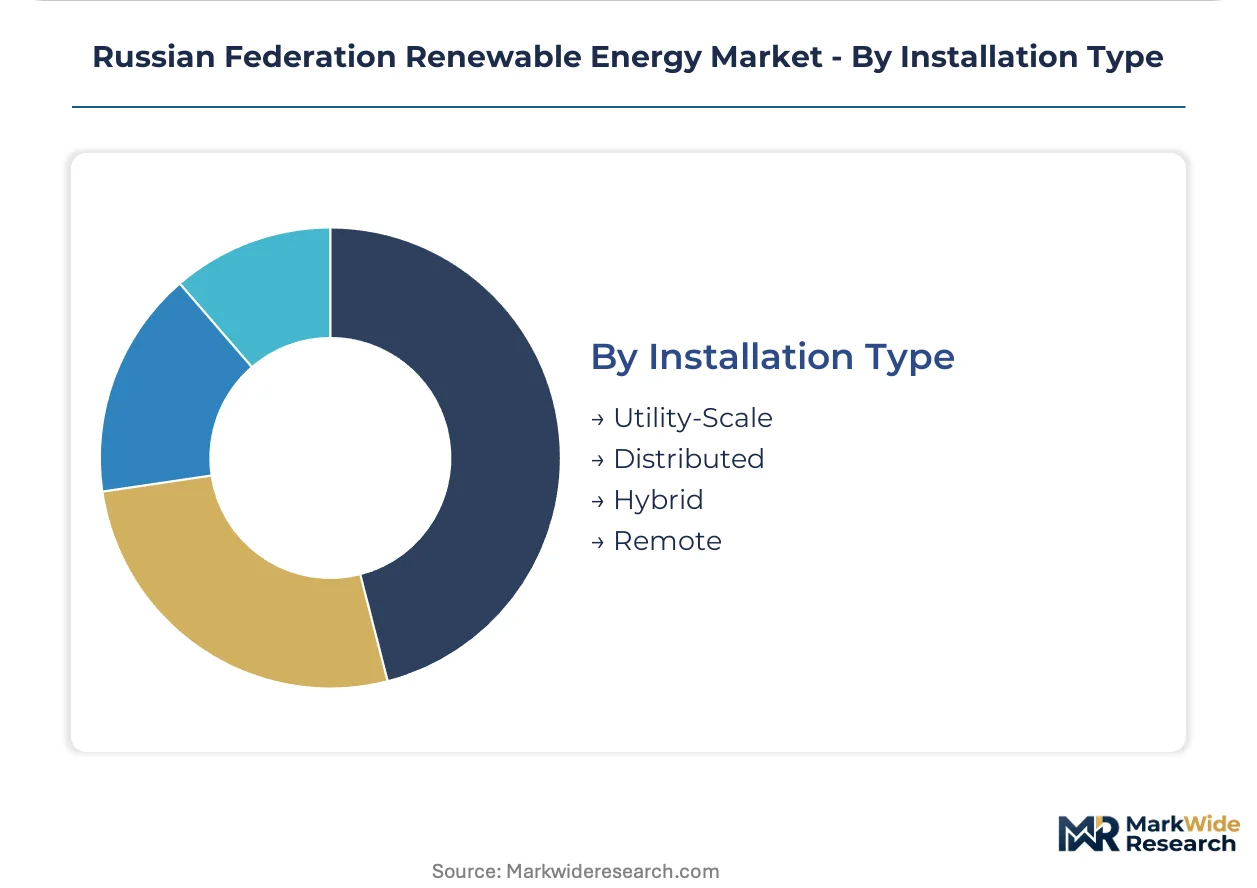
Installation Type:
Installation scale determines capital intensity, regulatory jurisdiction, and grid access protocols.
- Utility-Scale:Installations exceeding 25 MWac concentrate capital deployment and margin pools. Projects compete in Ministry of Energy capacity auctions for subsidized tariff eligibility.
- Distributed:Systems below 25 MWac face interconnection queue constraints and fragmented offtaker aggregation. Federal Antimonopoly Service oversees grid access pricing for these installations.
- Hybrid:Co-located solar-wind or solar-storage configurations optimize capacity factor and grid stability. Developers target high-resource zones with complementary generation profiles.
- Remote:Standalone microgrids serve mining and settlement loads beyond centralized grid reach. Diesel displacement economics drive deployment in Far East regions.
Utility-Scale dominates capital flows. Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's renewable energy export potential remains constrained by domestic absorption priorities, with cross-border electricity flows limited to neighboring Commonwealth of Independent States markets. Southern Federal District installations supply surplus generation to North Caucasus industrial zones. Ministry of Energy auction allocations concentrate capacity additions within domestic load centers rather than border-adjacent transmission corridors.
Southern Federal District
Astrakhan and Volgograd oblasts host utility-scale photovoltaic clusters exploiting 1,400 kWh/m² annual insolation. The Ministry of Energy's capacity auction mechanism prioritizes these zones for subsidized tariff eligibility. Rostov-on-Don anchors module assembly logistics, with heterojunction production lines serving regional developers.
Volga Federal District
Samara and Ulyanovsk regions concentrate wind development corridors with priority grid connection rights. Federal Antimonopoly Service protocols govern transmission access pricing for auction-selected projects. Tolyatti chemical manufacturers execute corporate power purchase agreements to hedge volatile natural gas exposure.
Far Eastern Federal District
Magadan and Sakha Republic mining operations deploy hybrid solar-diesel microgrids for diesel displacement at gold extraction sites. Ministry of Energy hydrogen economy roadmaps prioritize electrolyzer pilots at RusHydro hydroelectric installations. Yakutsk anchors remote power system engineering expertise.
Northwestern Federal District
Leningrad Oblast and Karelia retain hydroelectric dominance through RusHydro's existing pumped storage infrastructure. Rosstandart grid code compliance deadlines accelerate retrofit investments at legacy installations. Saint Petersburg transmission utilities balance variable renewable output from southern Federal District imports.
Siberian Federal District
Krasnoyarsk Krai biomass facilities utilize forestry waste for district heating networks. Federal Grid Company interconnection queues impose 18-24 month delays for distributed systems below 25 MWac. Novosibirsk industrial load centers pursue captive generation through centralized tender mechanisms.
Russian Federation Renewable Energy Market Competitive Landscape
On the supply side, the industry is consolidating around state-affiliated generation holdings and selective foreign operators with auction-winning track records. RusHydro anchors grid balancing services through hydroelectric infrastructure. Strategic archetypes divide between legacy hydro operators diversifying into variable renewable integration, domestic module manufacturers protected by local content rules, and European utilities capturing priority connection rights. Competitive moves center on securing auction tariff eligibility and achieving Rosstandart certification compliance for imported components.
Within the state-affiliated tier, RusHydro exemplifies hydro-anchored diversification into grid stability services. Hevel LLC occupies a position within domestic manufacturing archetypes, representing heterojunction production lines shielded by Ministry of Industry and Trade local content mandates. Fortum Oyj sits among European utility entrants, exemplifying selective wind development strategies targeting high-resource zone priority access.
| Leading Market Players |
|---|
| RusHydro |
| Hevel LLC |
| Fortum Oyj |
| Rosseti PJSC |
| Enel SpA |
| General Electric Co |
| Unigreen Energy |
| INTER RAO UES |
| EuroSibEnergo |
| Others |
Value Network & Pricing Analysis
Trans-Siberian Railway freight corridors from China to Novosibirsk shape module landed costs, concentrating pricing power among domestic heterojunction assemblers while forcing import-dependent developers into premium tier positioning against locally certified competitors.
Pricing Analysis
Industrial OEM buyers anchor project-based long-term offtake structures with 15-20 year power purchase agreements. Price differentiation rests on local content certification tier and grid connection priority rights. Cost compression in standard-tier modules intensifies because silicon feedstock freight volatility erodes importer margins. Metallurgical offtakers exhibit lowest price sensitivity due to natural gas hedge premiums, while commercial rooftop aggregators face acute margin pressure from interconnection queue delays.
Supply Chain Analysis
Tariff exposure between China and the Russian Federation dominates polysilicon sourcing risk, with alternative refining capacity concentrated in Germany and Malaysia. Raw material dependencies center on metallurgical-grade silicon, silver paste for cell metallization, and aluminum frames. Single-source vulnerability concentrates in heterojunction production equipment from Japanese and German suppliers. Distribution runs through Rostov-on-Don assembly hubs to Southern Federal District project sites, with Federal Grid Company managing transmission handoff logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against Gazprom's suppressed domestic gas tariffs, which threaten renewable project economics in Northwest and Central Federal Districts where thermal generation retains cost advantages.
For Market Incumbents: Build regulatory moats through accelerated Rosstandart certification pipelines for imported nacelle components. Secure priority grid connection rights in high-resource zones before auction saturation compresses tariff eligibility windows. Counter natural gas price suppression by deepening corporate PPA origination with aluminum smelters seeking price hedges.
For New Entrants and Emerging Players: Establish a beachhead in Far East off-grid mining microgrids where diesel displacement economics bypass grid interconnection constraints. Target Sakha Republic gold extraction operations with hybrid solar-diesel configurations. Penetrate through engineering partnerships with Yakutsk-based remote power system specialists.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated generation holdings divesting non-core renewable development subsidiaries. Long-term viability hinges on auction-winning track records and local content compliance infrastructure. Watch Ministry of Energy capacity allocation announcements as inflection indicators for tariff-eligible project pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Utility-scale solar clusters in Astrakhan exploit 1,400 kWh/m² insolation for auction eligibility. |
| Power Purchase Agreement | Corporate offtake contracts with Tolyatti chemical manufacturers displace merchant price exposure. |
| Technology Licensing | Heterojunction cell architecture transfers from Hevel LLC anchor production lines to regional assemblers. |
| Vertical Integration into Storage | RusHydro's pumped storage assets capture grid balancing premiums from variable renewable output. |
| Green Certification Program | Rosstandart grid code compliance investments unlock priority connection rights for certified developers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the Russian Federation renewable energy value chain. Primary interviews engaged Ministry of Energy auction administrators, Federal Grid Company interconnection planners, IPP project developers, EPC contractors, and metallurgical sector energy procurement officers. Secondary validation drew from EIA international energy statistics, IEA renewable market reports, FERC-equivalent Russian regulatory filings, and project development tracking databases. Bottom-up capacity addition tallies were triangulated against top-down investment flow estimates.
Calibration against historical auction outcomes and commissioning timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, installation scale tier, end-user category, and regional grid infrastructure type. CAGRs were derived from capacity auction pipeline analysis and corporate PPA origination velocity. Forecast inputs incorporated Ministry of Energy local content rule adjustments and Federal Antimonopoly Service transmission pricing protocols.
Sensitivities concentrate around silicon feedstock import cost volatility, natural gas tariff regulatory resets, and Rosstandart certification timeline extensions. Forecasts reflect documented assumptions regarding auction allocation volumes and interconnection queue clearance rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Ocean Power Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Rectenna Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
China Wind Energy Market