
 East Africa Natural Oil and Gas Midstream Market | 2026-2036
East Africa Natural Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Natural Oil and Gas Midstream Market Insights
Maintenance contracts tied to pipeline integrity management is shifting from reactive repair schedules toward predictive, condition-based service models. TotalEnergies leverages its integrated LNG development portfolio to anchor downstream offtake commitments across Mozambique and Tanzania. China National Petroleum Corporation sustains construction momentum on cross-border pipeline links between South Sudan and Kenyan port facilities. Kenya Pipeline Company Ltd dominates inland petroleum product distribution through its Mombasa-Nairobi-Eldoret pipeline network.
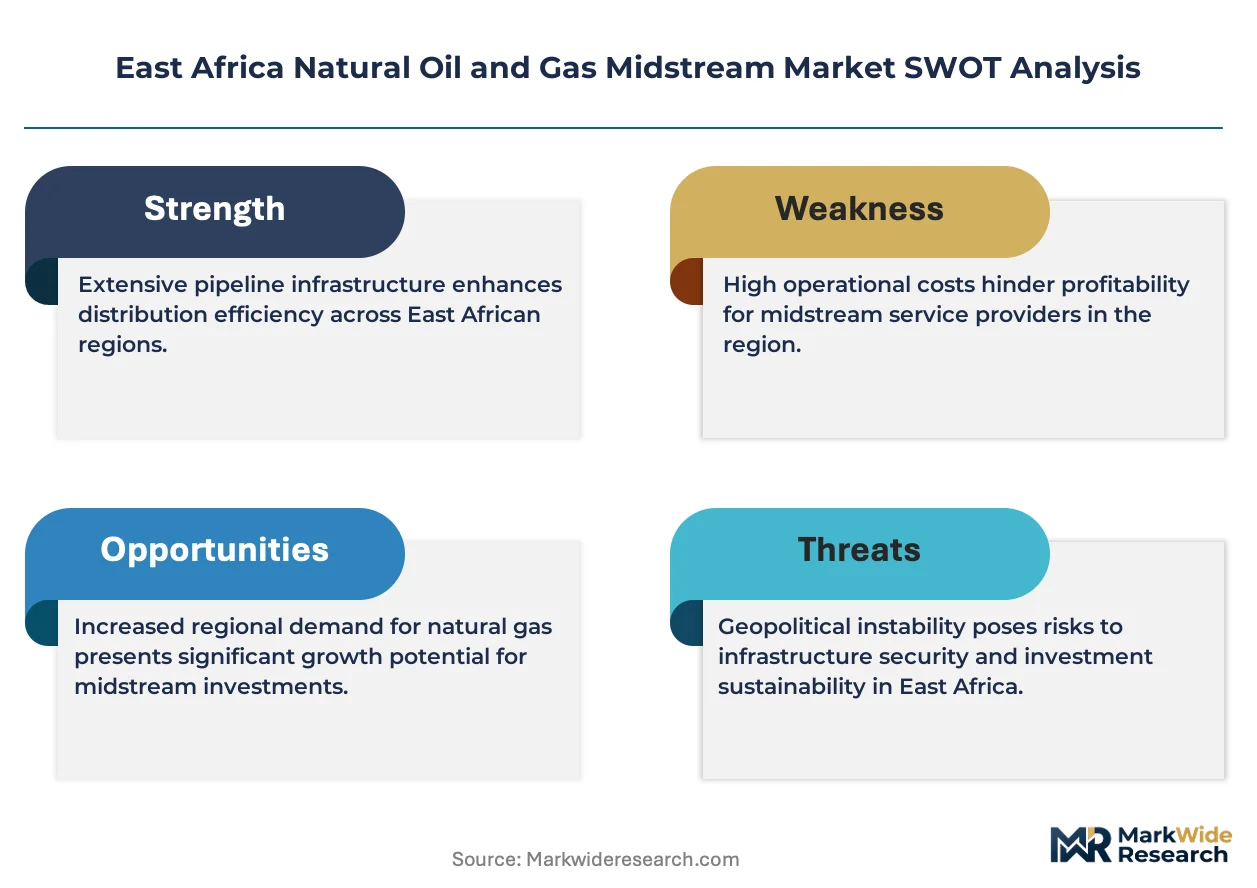
The East Africa Natural Oil and Gas Midstream sector encompasses the transportation, storage, and processing infrastructure bridging upstream extraction with downstream distribution, operating at pressures typically ranging from 50 to 150 bar for natural gas transmission and incorporating cathodic protection systems to prevent corrosion in coastal and high-humidity environments. Pipeline service type leads capital deployment due to the region's need to connect landlocked discoveries with coastal export terminals, while storage facilities command premium margins where strategic petroleum reserves and LNG regasification capacity face supply constraints. Automation technology within the monitoring systems category is expanding fastest as operators deploy SCADA networks across remote pipeline segments to reduce leak detection response times.
Kenya's Petroleum Act and Tanzania's Petroleum Development Corporation licensing framework shape market access by mandating local content thresholds and environmental impact assessments for midstream investments. The Extractive Industries Transparency Initiative standards enforce revenue disclosure protocols that influence how international operators structure joint ventures with national oil companies. Stakeholders must weigh the trade-offs between greenfield pipeline construction and incremental storage capacity additions as regional production profiles shift from oil toward gas-weighted reserve bases.
Market Dynamics
The shift from reactive pipeline maintenance to predictive, condition-based integrity management is compressing operational expenditure timelines across East African midstream infrastructure. Operators now deploy fiber-optic sensing and SCADA networks to detect corrosion anomalies before rupture, fundamentally altering capital allocation between construction and monitoring systems.
Growth Catalysts
- Rovuma Basin corridor development:Natural gas discoveries in northern Mozambique require dedicated pipeline networks linking onshore processing to coastal LNG export terminals, pulling investment toward compression stations and subsea tie-ins.
- Kenya's Petroleum Act local content mandates:Domestic labor and supplier thresholds for midstream licensing are building indigenous technical capacity around pipeline construction and terminal operations.
- SCADA automation deployment:Leak detection response times are shrinking as fiber-optic monitoring replaces manual pipeline patrols across Tanzania's Songo Songo gas transmission routes.
Market Restraints
- Steel alloy input volatility:High-grade pipeline steel prices fluctuate with global metallurgical coal markets, squeezing project margins for cross-border trunk line construction between South Sudan and Kenyan port facilities.
- Landlocked reserve geography:Ugandan crude discoveries lack direct coastal access, forcing expensive heated pipeline designs or rail transloading to Mombasa terminals.
- Extractive Industries Transparency Initiative disclosure protocols:Revenue reporting requirements add compliance layers to joint venture structuring with national oil companies, extending negotiation timelines.
Strategic Opportunities
- Tanzania's LNG regasification gap:Dar es Salaam industrial zones lack sufficient import terminal capacity, creating white space for floating storage and regasification unit deployment.
- Ethiopia's underpenetrated downstream:Addis Ababa's manufacturing corridors remain disconnected from regional gas networks, offering first-mover advantage for distribution pipeline concessions.
- Renewable-natural gas blending mandates:Kenya's power sector regulators are evaluating biogas injection standards that would retrofit existing transmission infrastructure for dual-fuel compatibility.
Industry Challenges
- Corrosion engineering skill scarcity:Cathodic protection system design and impressed current maintenance require specialized electrochemistry expertise rarely available in East African technical institutes.
- Legacy manual monitoring integration:SCADA networks must overlay existing pipeline segments originally built for patrol-based leak detection, creating data interoperability friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Natural Oil and Gas Midstream Market |
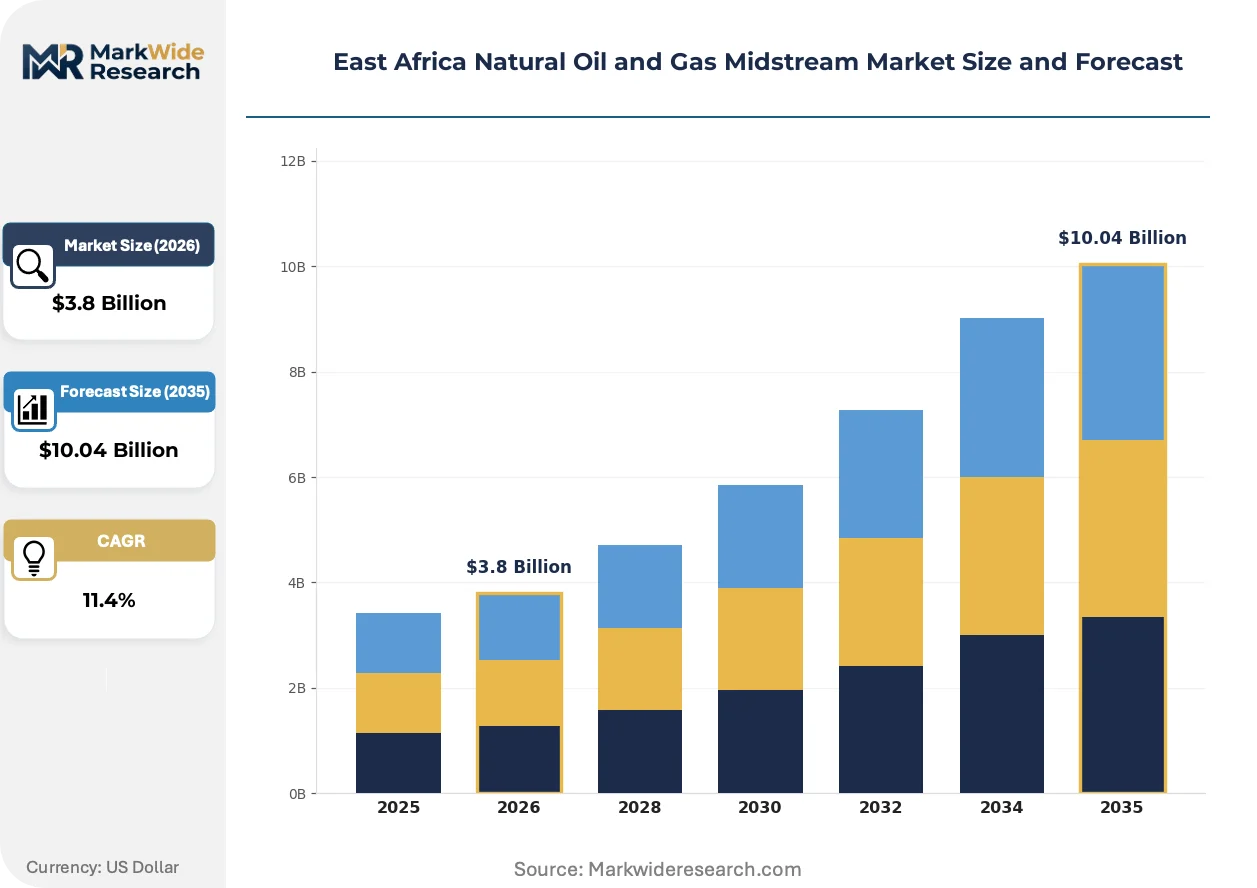
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pipelines, Storage Facilities, Transportation, Offloading Stations End User: Utilities, Manufacturers, Distributors, Exporters Technology: Automation, Monitoring Systems, Pressure Control, Valve Technology Application: Natural Gas Processing, Oil Refining, Transport & Logistics, Waste Management |
| Companies Covered | TotalEnergies, China National Petroleum Corporation, Petróleos de Moçambique SA, Kenya Pipeline Company Ltd, Eni S.p.A., Tullow Oil, Oil and Natural Gas Corporation, Equinor ASA, Shell PLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Natural Oil and Gas Midstream Market Trends and Innovations
Digitalization of pipeline integrity systems is converging with regional gas-to-power demand growth, creating pressure for real-time monitoring infrastructure that spans national borders. East African operators are prioritizing technologies that reduce physical inspection dependency across remote terrain.
Fiber-optic distributed acoustic sensing is electrifying pipeline monitoring capabilities by converting existing fiber cables into continuous vibration detectors. Kenya Pipeline Company Ltd deploys this technology across the Mombasa-Nairobi-Eldoret corridor to identify third-party interference and leaks within seconds. The technology is compressing insurance premiums and emergency response budgets while enabling extended intervals between physical surveys.
Tanzania's Petroleum Development Corporation licensing framework now mandates environmental impact assessments with climate risk scenarios for all new midstream investments. This requirement is extending project development timelines by 12-18 months but is redirecting capital toward elevated pipeline routing and flood-resistant terminal designs. Coastal segments linking Songo Songo to Dar es Salaam are most affected, with developers incorporating sea-level rise projections into cathodic protection specifications.
Power generation utilities in Nairobi and Dar es Salaam are consolidating procurement through long-term offtake agreements rather than spot market purchases. This concentration is displacing merchant gas traders and forcing pipeline operators to offer take-or-pay structures with guaranteed volume commitments. Tanzania Electric Supply Company Limited's consolidated purchasing function exemplifies this shift, which is most visible in Rufiji Basin power project negotiations.
East Africa Natural Oil and Gas Midstream Market Segmentation
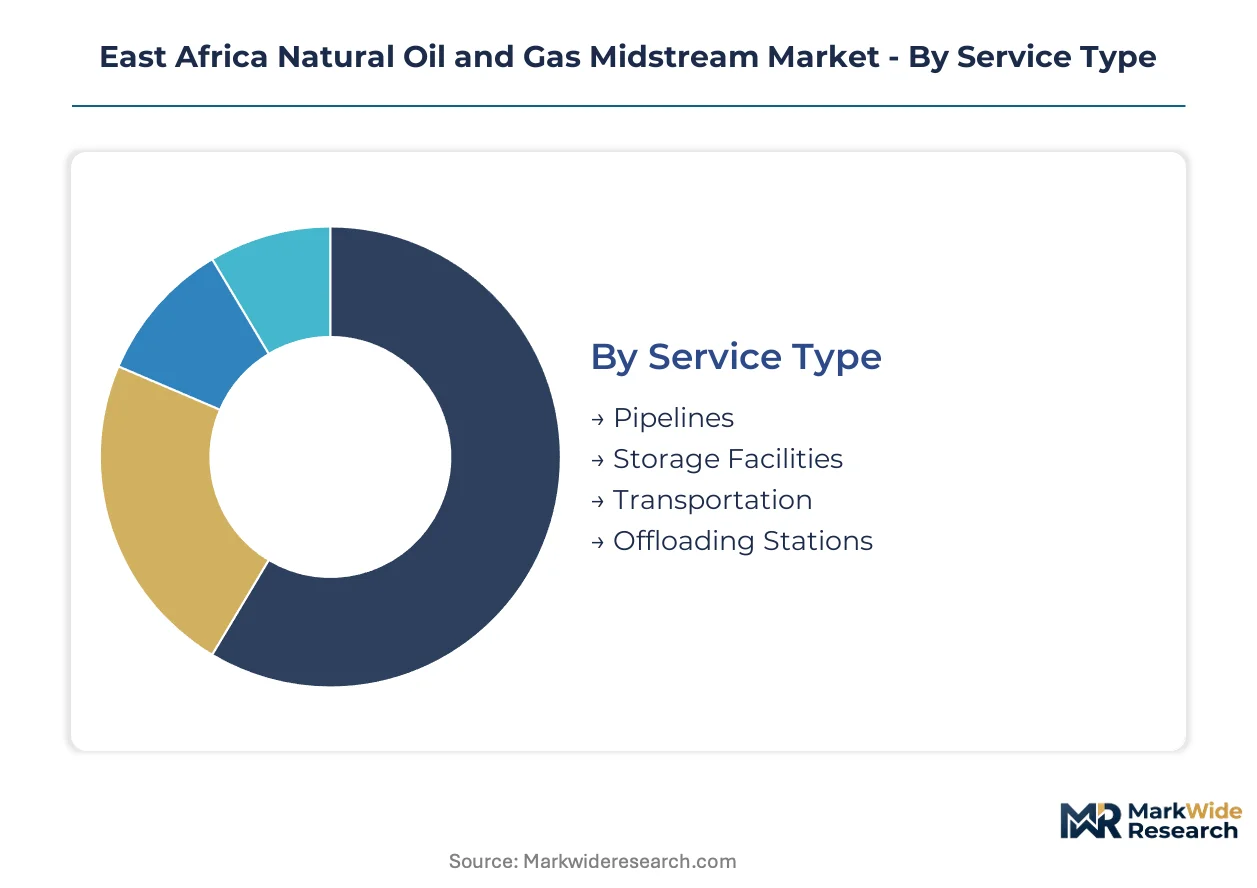
East Africa's midstream infrastructure spans four distinct segmentation dimensions that determine capital allocation priorities. Service type configurations dictate whether investment flows toward trunk pipelines or coastal storage terminals. Technology choices separate operators deploying predictive maintenance from those relying on manual inspection regimes.
Service Type:
Pipeline corridors concentrate supply capacity along the Rovuma Basin-to-coast axis, while storage investments cluster where LNG export terminals face berth constraints.
- Pipelines:High-pressure steel transmission lines operating at 50-150 bar connect landlocked upstream fields to coastal export infrastructure. Demand concentrates in northern Mozambique corridor developments where TotalEnergies anchors compression station investments for LNG feedstock delivery.
- Storage Facilities:Above-ground tank farms and underground caverns buffer supply volatility across Mombasa and Dar es Salaam port zones. Strategic petroleum reserve mandates in Kenya are pulling capital toward crude stockpiling capacity at Kipevu Oil Terminal.
- Transportation:Rail transloading and marine vessel chartering bridge pipeline gaps across Lake Victoria basin corridors.
- Offloading Stations:Single-point mooring systems and jetty infrastructure handle VLCC crude arrivals at Kenyan port facilities.
Today's leader: Pipelines. Tomorrow's challenger: Storage Facilities.
End User:
Procurement concentration among Nairobi and Dar es Salaam power utilities is displacing merchant gas traders from long-term offtake negotiations.
- Utilities:Kenya Power and Tanzania Electric Supply Company Limited consolidate procurement through take-or-pay structures for gas-fired generation capacity. Rufiji Basin power project negotiations exemplify this buyer concentration trend.
- Manufacturers:Cement and fertilizer producers in Addis Ababa industrial zones seek pipeline connectivity for process heat applications.
- Distributors:Product marketing companies lease terminal capacity for inland petroleum product movements across Kenya Pipeline Company networks.
- Exporters:LNG trading desks contract regasification slots at coastal terminals for re-export to Asian buyers.
Utilities command volume today. Manufacturers represent the steepest expansion trajectory as industrial gasification spreads.
Technology:
Automation deployment separates capital-efficient operators from those carrying higher inspection labor burdens across remote terrain.
- Automation:SCADA networks and fiber-optic distributed acoustic sensing compress leak detection response times from hours to seconds. Kenya Pipeline Company Ltd deploys this technology across the Mombasa-Nairobi-Eldoret corridor.
- Monitoring Systems:Cathodic protection and impressed current systems prevent corrosion in coastal humidity zones where maintenance skill scarcity elevates operational risk.
- Pressure Control:Compression station automation maintains throughput across elevation changes in Rift Valley pipeline routing.
- Valve Technology:Emergency shutdown systems and block valve automation isolate rupture segments within mandated isolation times.
Automation dominates current deployment. Monitoring Systems are gaining share fastest as regulatory environmental assessments mandate real-time integrity verification.
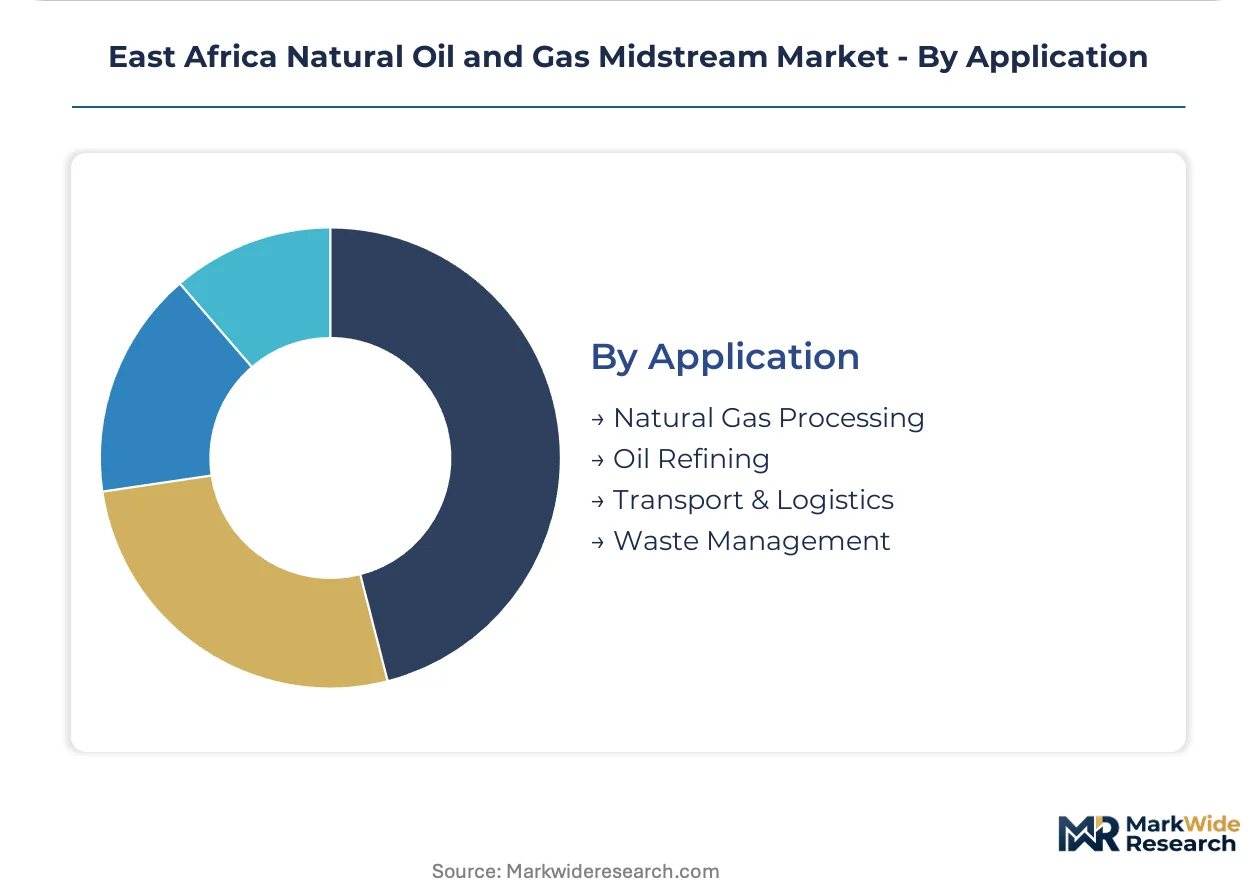
Application:
Natural gas processing investments are climbing the fastest as regional reserve profiles shift from oil-weighted toward gas-dominant production bases.
- Natural Gas Processing:Onshore treatment facilities remove CO2 and H2S from Rovuma Basin feedstocks prior to LNG liquefaction. Mozambique's Coral South development anchors regional processing capacity expansion.
- Oil Refining:Crude distillation and conversion capacity at Mombasa refinery handles Ugandan and South Sudanese crude arrivals.
- Transport & Logistics:Intermodal coordination between pipeline, rail, and marine modes manages landlocked reserve access constraints.
- Waste Management:Produced water handling and flare gas recovery systems address environmental compliance in extraction zones.
Natural Gas Processing leads capital deployment today. Transport & Logistics faces margin pressure from infrastructure gap bridging requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya commands the largest share of inland petroleum product distribution infrastructure while Mozambique anchors natural gas export capacity through its northern Rovuma Basin developments.
Kenya
Kenya Power and industrial manufacturers in Nairobi drive gas transmission demand through take-or-pay procurement structures. The Petroleum Act mandates local content thresholds for pipeline licensing, reshaping contractor selection criteria. The Mombasa-Nairobi-Eldoret corridor concentrates storage and distribution assets where Kenya Pipeline Company Ltd operates the dominant network.
Mozambique
TotalEnergies and Eni S.p.A. anchor LNG feedstock demand from offshore Coral South and onshore Rovuma Basin processing facilities. The national petroleum regulator enforces environmental impact assessments with climate risk scenarios for coastal terminal designs. Northern Cabo Delgado province hosts compression stations and subsea tie-ins linking gas fields to export infrastructure.
Tanzania
Tanzania Electric Supply Company Limited consolidates procurement for Rufiji Basin power projects and Dar es Salaam industrial zones. The Petroleum Development Corporation licensing framework extends project timelines through mandatory climate risk assessments. The Songo Songo-to-Dar es Salaam coastal corridor faces elevated cathodic protection specifications due to sea-level rise projections.
Uganda
Landlocked crude discoveries in the Albertine Graben force heated pipeline designs or rail transloading to Mombasa terminals. The national petroleum authority oversees environmental compliance for cross-border export infrastructure. Hoima district anchors upstream production while Kampala coordinates midstream access negotiations with Kenyan port authorities.
Ethiopia
Addis Ababa manufacturing corridors remain disconnected from regional gas networks, creating first-mover opportunities for distribution pipeline concessions. The Ministry of Mines and Petroleum regulates midstream licensing for cross-border energy trade. The Dire Dawa industrial zone represents the most concentrated demand center for future gasification projects.
East Africa Natural Oil and Gas Midstream Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy majors dominating LNG export infrastructure while national oil companies control inland distribution networks. The market structure concentrates around three archetypes: European majors with integrated LNG portfolios, Asian state-owned enterprises financing cross-border pipelines, and African national carriers operating legacy distribution assets. Competitive moves center on securing long-term offtake commitments through integrated development structures and deploying automation technology to compress operational expenditure timelines.
Among European integrated majors, TotalEnergies and Eni S.p.A. exemplify the LNG-anchored archetype through their Rovuma Basin development positions. Equinor ASA and Shell PLC occupy positions within the same tier, representing North European capital deployment into East African gas export infrastructure. China National Petroleum Corporation anchors the Asian state-backed financing archetype, while Kenya Pipeline Company Ltd exemplifies the national carrier model controlling critical inland distribution corridors.
| Leading Market Players |
|---|
| TotalEnergies |
| China National Petroleum Corporation |
| Petróleos de Moçambique SA |
| Kenya Pipeline Company Ltd |
| Eni S.p.A. |
| Tullow Oil |
| Oil and Natural Gas Corporation |
| Equinor ASA |
| Shell PLC |
| Others |
Pricing and Supply Chain Analysis
Backward integration into pipeline steel sourcing anchors pricing power for East African operators constructing cross-border trunk lines. Captive supply of high-grade metallurgical inputs insulates project margins from global alloy volatility while securing volume commitments from utilities in Nairobi and Dar es Salaam.
Pricing Analysis
Capacity additions in northern Mozambique are reshaping price floors for LNG feedstock delivery contracts. Long-term offtake structures with take-or-pay clauses dominate, separating integrated majors with guaranteed volume from merchant traders exposed to spot softness. Price differentiation rests on compression station redundancy and cathodic protection specifications. Industrial offtakers in cement and fertilizer sectors exhibit highest price sensitivity, while power utilities absorbing pass-through fuel costs show lowest elasticity.
Supply Chain Analysis
Regional distribution centers for pipeline components cluster in Mombasa, Dar es Salaam, and Maputo port zones. Manufacturing draws from Chinese steel mills, German valve specialists, and Italian compression equipment providers. Single-source vulnerability concentrates in subsea tie-in technology where European engineering houses control proprietary designs. Distribution runs through Kenya Pipeline Company networks for inland petroleum products and marine vessel chartering for cross-border crude movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's natural oil and gas midstream sector compounds steadily as Rovuma Basin gas discoveries anchor decades of infrastructure deployment. Regional reserve maturation from oil toward gas-weighted profiles sustains capital deployment across pipeline and processing corridors.
For Market Incumbents: Hedge against merchant trader displacement by locking take-or-pay structures with Tanzania Electric Supply Company Limited and Kenya Power before procurement consolidation completes. Prioritize fiber-optic sensing deployment across legacy pipeline segments to compress insurance premiums and extend survey intervals. Defensive consolidation around cathodic protection maintenance capabilities addresses skill scarcity in coastal humidity zones. For New Entrants and Emerging Players: The mid-tier pricing gap between TotalEnergies-anchored LNG infrastructure and state-owned distribution networks creates entry space for specialized automation providers. Target Ethiopia's Addis Ababa manufacturing corridors where gasification remains underpenetrated and first-mover concessions await. Pursue SCADA integration contracts for existing pipeline segments originally built for manual patrol regimes. For Investors and Strategic Acquirers: Roll-up economics work for regional monitoring technology specialists because fragmentation across Kenya, Tanzania, and Mozambique prevents scale efficiencies in predictive maintenance deployment. Five-to-ten year viability hinges on securing positions before utility procurement consolidation matures. Watch for Tanzania Petroleum Development Corporation licensing timeline extensions as inflection signals for capital deployment windows.| Strategic Initiative | Industry Significance |
|---|---|
| SCADA Network Deployment | Kenya Pipeline Company leverages fiber-optic sensing to reduce leak detection response times across the Mombasa-Nairobi-Eldoret corridor. |
| Local Content Compliance Investment | Contractors meeting Kenya Petroleum Act labor thresholds secure preferential licensing for cross-border trunk line construction. |
| Floating Storage and Regasification Unit Deployment | Dar es Salaam industrial zones lack sufficient import terminal capacity, creating white space for FSRU operators. |
| Cathodic Protection System Expansion | Coastal pipeline segments require elevated specifications due to sea-level rise projections in Tanzania's climate risk assessments. |
| Biogas Injection Infrastructure Retrofit | Kenya's power sector regulators are evaluating dual-fuel compatibility standards for existing transmission networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with utility planning officers, EPC contractors, pipeline integrity engineers, and national petroleum regulators informed demand projections and infrastructure timelines. Secondary validation drew from Petroleum Act filings, Extractive Industries Transparency Initiative disclosure reports, Tanzania Petroleum Development Corporation licensing records, and regional customs data. Bottom-up project pipeline assessments triangulated against top-down macroeconomic indicators.
Segment-weighting approaches distributed value across service type, technology deployment, and end-user procurement concentration. The analytical framework modeled pipeline corridor development, storage facility margins, and automation adoption curves across the projection horizon. CAGRs derived from capacity buildout schedules, offtake agreement tenors, and regulatory milestone timelines. Forecast inputs incorporated steel alloy price trajectories and climate risk assessment compliance costs.
Caveats apply where metallurgical coal market volatility, licensing timeline extensions, or regional security conditions could materially shift the outlook. Forecasts reflect documented assumptions regarding reserve development schedules and utility demand consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market